
 Solar EVA Market | 2026-2036
Solar EVA Market Size, Share, and Industry Trends Forecast 2026-2036
Solar EVA Market Analytics
China is rewriting supply dynamics for solar encapsulant materials. Hangzhou First PV Material Co., Ltd. dominates domestic film production with integrated extrusion and lamination capabilities. Jiangsu Akcome Solar Science & Technology Co., Ltd. leverages captive EVA demand from its downstream module assembly lines. Coveme S.p.A competes through European-sourced specialty films for premium bifacial applications.
Solar EVA denotes ethylene-vinyl acetate copolymer formulated as encapsulant film, typically containing 28-33% vinyl acetate content and crosslinked via peroxide curing to achieve >90% optical transmittance and moisture barrier performance below 2 g/m²-day. This material bonds photovoltaic cells to glass and backsheet substrates while protecting against environmental degradation over 25-year service life. Transparent EVA retains volume leadership across crystalline silicon installations, yet white EVA gains structural importance in bifacial module architectures where rear-side reflectivity boosts power output. Film-form supply dominates manufacturing workflows, though roll formats streamline automated layup for high-throughput panel assembly lines.
China's SAMR enforces GB/T 29848 standards for photovoltaic encapsulant optical and mechanical durability, while India's BIS mandates IS 16221 certification for imported solar materials used in government-backed projects. REACH compliance in Europe restricts certain peroxide crosslinker chemistries, compelling reformulation investments from Asian exporters. Stakeholders must track evolving certification requirements across destination markets while securing long-term ethylene supply commitments amid petrochemical capacity realignments.
Market Dynamics
China's dual carbon goals and updated GB standards for solar module encapsulants are tightening material specifications across the entire supply chain, forcing reformulation investments from film manufacturers and reshaping competitive positioning among integrated producers.
Growth Catalysts
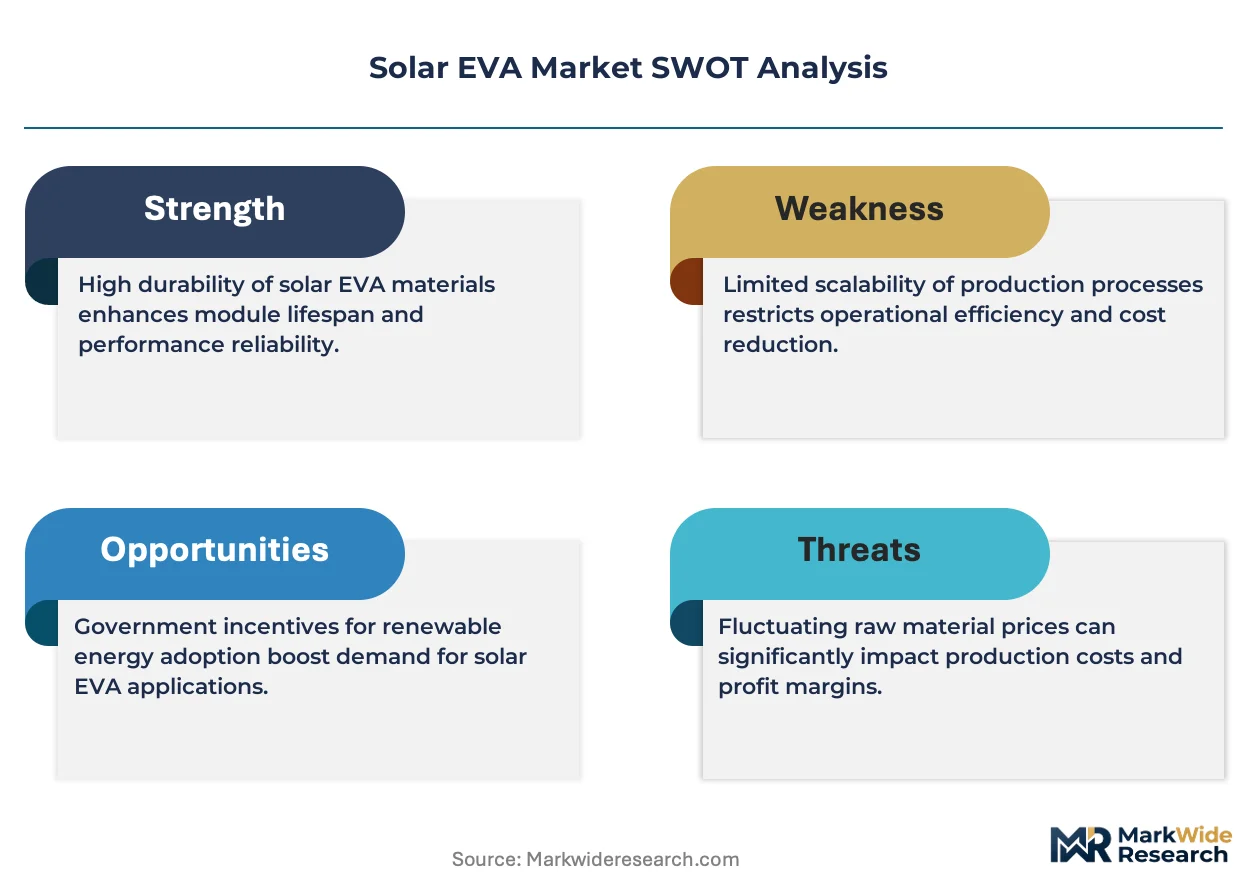
- Utility-scale photovoltaic installations:India's government-backed solar parks under CEA guidelines are driving bulk procurement of certified encapsulant films for multi-gigawatt projects.
- Bifacial module architectures:White EVA formulations with enhanced rear-side reflectivity are capturing demand from power-optimized panel designs seeking maximum energy yield per square meter.
- MIIT industrial clustering policies:China's manufacturing consolidation in Jiangsu province creates captive demand pools that absorb regional EVA film capacity.
Market Restraints
- Ethylene feedstock volatility:Petrochemical capacity realignments in Asia are creating input cost instability for vinyl acetate copolymer production.
- Supply concentration risk:Domestic Chinese producers control the majority of extrusion and lamination capacity, limiting sourcing alternatives for international module assemblers.
- REACH compliance friction:ECHA restrictions on certain peroxide crosslinker chemistries are compelling Asian exporters to maintain dual formulation inventories.
Strategic Opportunities
- European specialty film demand:Premium bifacial applications requiring optical-grade encapsulants present white-space for producers with REACH-certified chemistries.
- Automated layup integration:Roll-format EVA films compatible with high-throughput panel assembly lines enable downstream efficiency gains for tier-one module manufacturers.
- IS 16221 certification pathways:India's BIS mandates for imported solar materials create structured entry points for compliant foreign suppliers in government-backed tenders.
Industry Challenges
- Peroxide curing expertise shortage:Crosslinking process optimization for >90% optical transmittance requires specialized polymer chemists in short supply across Asian manufacturing hubs.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of GB/T 29848, IS 16221, and REACH compliance extends product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar EVA Market |
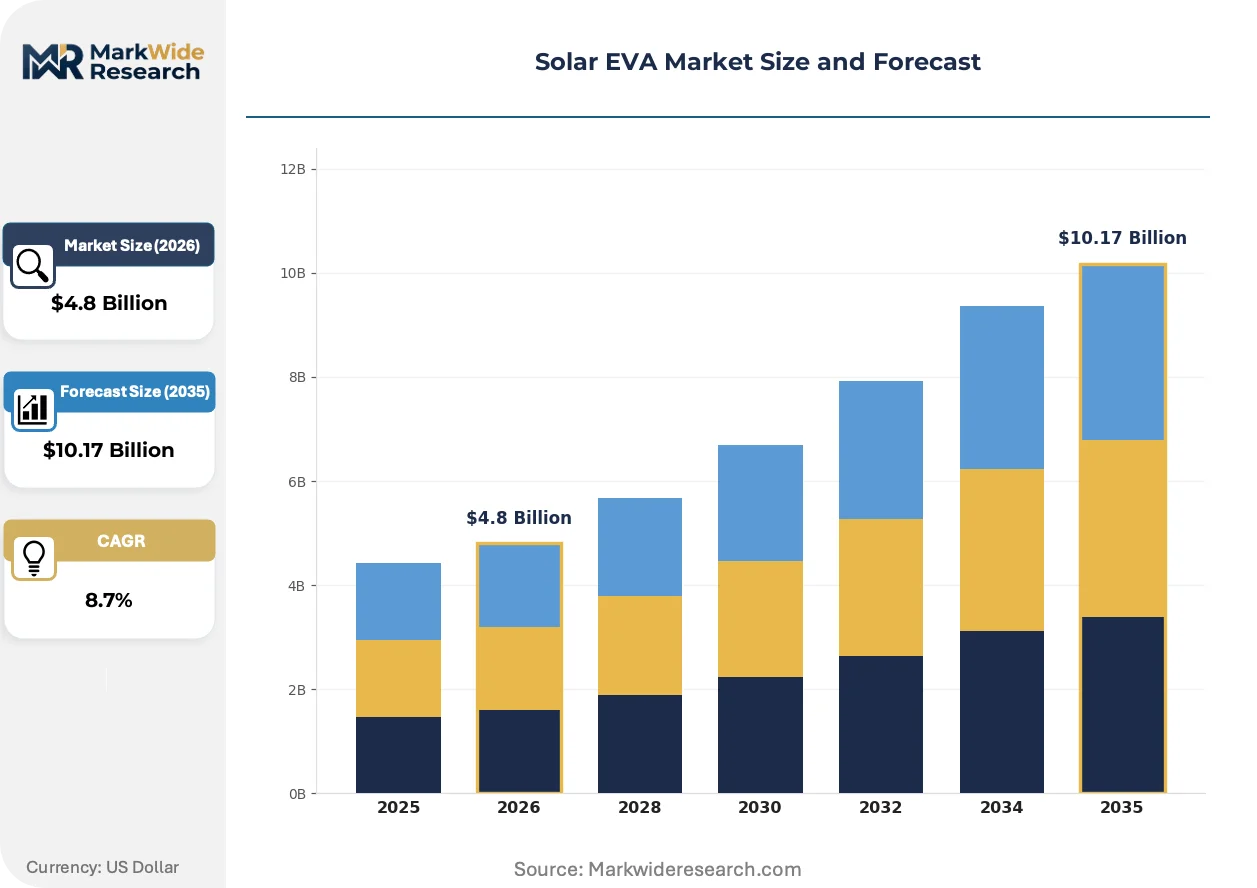
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent EVA, White EVA, Colored EVA, Others Form: Sheet, Film, Roll, Others End User: Solar Panel Manufacturers, OEMs, Distributors, Installers Technology: Crystalline Silicon, Thin Film, Bifacial, Others |
| Companies Covered | DuPont-Mitsui Polychemicals Co., Ltd., Wenzhou Ruiyang Photovoltaic Material, Hangzhou First PV Material Co., Ltd., Coveme S.p.A, Zhejiang Feiyu Photoelectricity S&T Co., Ltd., Bridgestone Corporation, Shenzhen Sveck Technology Co., Ltd., Specialized Technology Resources, Inc., Jiangsu Akcome Solar Science & Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar EVA Market Evolving Landscape
Digital process control systems are penetrating film manufacturing workflows, enabling real-time thickness and optical uniformity monitoring that reduces material waste while tightening specification bands for next-generation cell technologies.
POE-based co-extruded encapsulants are digitizing quality assurance protocols through inline spectroscopic inspection systems. Tier-one module producers in China are adopting these films for TOPCon cell architectures requiring enhanced moisture barrier performance below 2 g/m²-day. The technology is digitizing supplier qualification processes, compressing vendor approval timelines from months to weeks.
REACH Annex XVII restrictions on specific crosslinker additives are forcing reformulation of standard EVA chemistries for European-bound shipments. ECHA regulatory updates are triggering dual-track R&D investments among Asian exporters. Specialty film producers with pre-certified European formulations are capturing premium positioning in bifacial module supply chains serving EU renewable energy auctions.
Direct mill relationships are displacing distributor intermediaries in bulk encapsulant procurement. Large-scale Indian project developers under CEA tender structures are negotiating frame contracts with Jiangsu-based film extruders. This channel consolidation is most visible in utility-scale installations where volume certainty justifies dedicated production line allocations and technical service embedding.
Solar EVA Market Segmentation
Segmentation in solar EVA encapsulants reveals how formulation chemistry, physical format, and downstream integration requirements create distinct service and procurement patterns across the photovoltaic supply chain. Understanding these divisions helps suppliers align technical capabilities with specific customer workflows.
Product Type:
After-sales service intensity varies sharply across EVA formulations, with premium optical grades requiring technical field support during lamination process optimization while commodity transparent films operate on volume logistics.
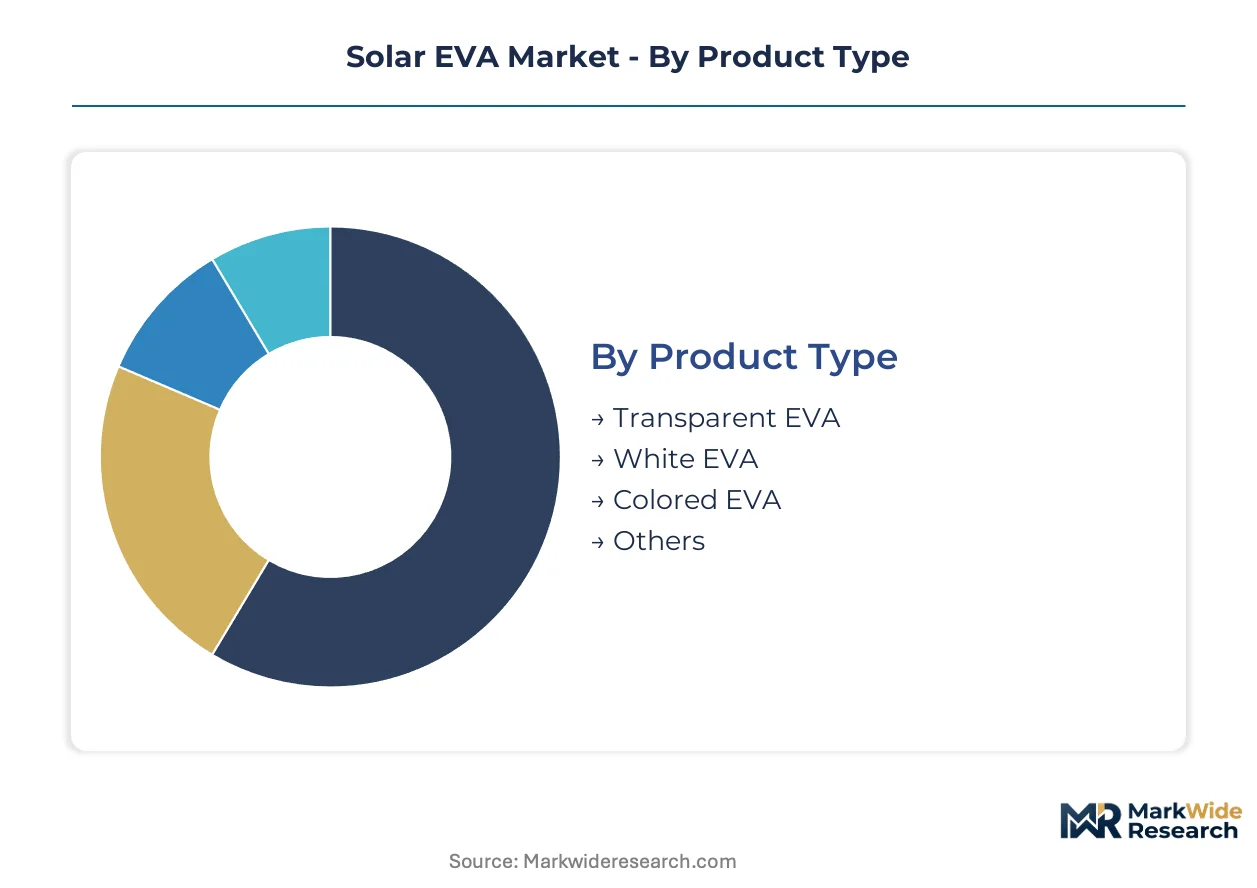
- Transparent EVA:Standard copolymer with 28-33% vinyl acetate content delivering >90% optical transmittance for conventional crystalline silicon modules. Demand concentrates in Jiangsu province integrated manufacturing clusters where captive consumption absorbs regional extrusion capacity under MIIT industrial consolidation policies.
- White EVA:Titanium dioxide-loaded formulation engineered for rear-side reflectivity in bifacial architectures, boosting power output through scattered light capture. Indian utility-scale developers under CEA tender structures are specifying white EVA for power-optimized panel designs seeking maximum energy yield per square meter.
- Colored EVA:Pigmented variants for building-integrated photovoltaics requiring aesthetic customization.
- Others:Specialty formulations including UV-cut and high-temperature resistant grades for niche applications.
By volume, Transparent EVA leads. By growth pace, White EVA is ahead.
Form:
Physical format selection directly determines automation compatibility and inventory carrying costs for module assembly operations.
- Film:Dominant supply format enabling precise thickness control and optical uniformity through extrusion calendering. China's SAMR-enforced GB/T 29848 standards for optical and mechanical durability are tightening specification bands for film-grade products.
- Roll:Continuous wound format compatible with high-throughput automated layup systems. Tier-one Chinese module producers are adopting roll-format EVA to compress panel assembly cycle times and reduce material waste.
- Sheet:Pre-cut dimensions for manual handling in smaller-scale or prototype production.
- Others:Custom die-cut configurations for specialized module geometries.
Film commands current procurement volumes. Roll formats are expanding most quickly as automation penetrates tier-one assembly lines.
End User:
Customer type shapes technical service embedding, certification documentation requirements, and contract structure complexity.
- Solar Panel Manufacturers:Integrated module producers with captive lamination lines and direct extruder relationships. These buyers negotiate frame contracts with Jiangsu-based film suppliers under CEA-aligned procurement structures for Indian government-backed projects.
- OEMs:Contract manufacturers assembling modules for third-party brands, requiring flexible supply agreements and rapid formulation switches.
- Distributors:Inventory intermediaries serving fragmented installer bases with standard transparent grades.
- Installers:Small-scale procurement of sheet-format EVA for repair and replacement applications.
Panel manufacturers absorb the majority of tonnage. OEMs represent the steepest expansion trajectory as brand owners outsource assembly capacity.
Technology:
Cell architecture selection dictates encapsulant optical, thermal, and moisture barrier performance requirements.
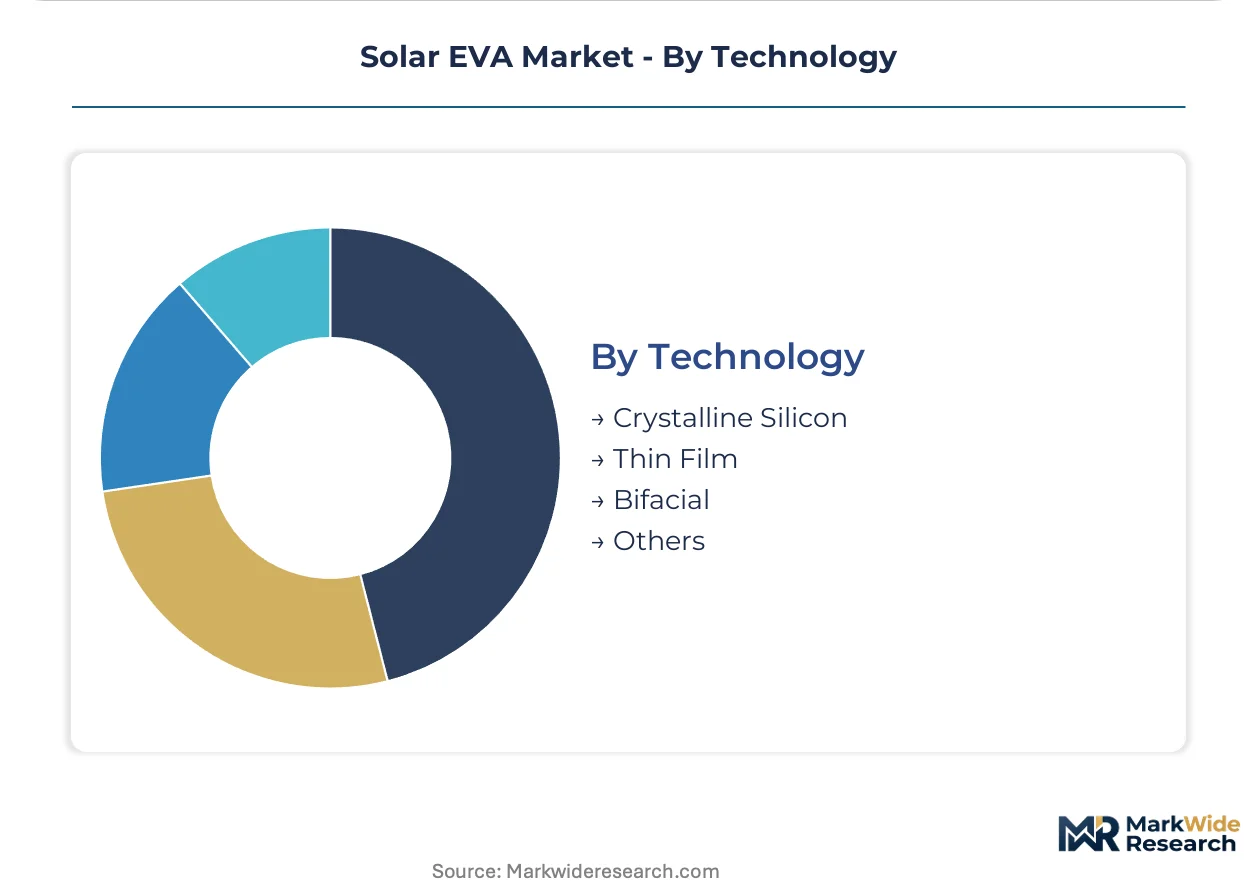
- Crystalline Silicon:Dominant cell technology requiring standard EVA formulations with peroxide crosslinking for 25-year service life. India's BIS mandates IS 16221 certification for imported encapsulants used in government-backed crystalline silicon installations.
- Bifacial:Dual-sided light capture architectures demanding white EVA rear encapsulation with enhanced reflectivity and modified crosslinking profiles to prevent rear-side degradation.
- Thin Film:Cadmium telluride and CIGS technologies requiring specialized barrier properties and thermal expansion matching.
- Others:Emerging perovskite tandem and heterojunction configurations with unstandardized encapsulant specifications.
Crystalline Silicon maintains volume leadership. Bifacial is gaining share fastest as power-optimized designs capture utility-scale procurement preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion and lamination capacity clusters in eastern China, with Jiangsu province absorbing the majority of domestic film supply through integrated manufacturing hubs under MIIT industrial consolidation policies.
China
Hangzhou First PV Material and Jiangsu Akcome Solar anchor domestic supply through integrated extrusion capabilities serving captive module assembly lines. SAMR-enforced GB/T 29848 standards tighten optical and mechanical durability specifications for photovoltaic encapsulants. Jiangsu province concentrates the bulk of film manufacturing, where MIIT clustering policies create dedicated demand pools that absorb regional EVA capacity.
India
Utility-scale solar parks under CEA guidelines drive bulk procurement of certified encapsulant films for multi-gigawatt crystalline silicon installations. BIS mandates IS 16221 certification for imported solar materials used in government-backed projects. Project developers negotiate direct frame contracts with Jiangsu-based extruders, bypassing distributor intermediaries for volume certainty.
United States
Domestic module assembly operations source specialty films for bifacial and premium applications requiring enhanced moisture barrier performance. IRA production incentives stimulate localized encapsulant demand from tier-one panel manufacturers. Southeast manufacturing corridors attract film suppliers seeking proximity to automated assembly lines serving utility-scale procurement.
Germany
European renewable energy auctions create demand for REACH-compliant encapsulant formulations with pre-certified chemistries. ECHA restrictions on specific peroxide crosslinker additives compel Asian exporters to maintain dual formulation inventories for EU-bound shipments. Industrial clusters in Bavaria and North Rhine-Westphalia host module producers specifying optical-grade films for premium bifacial architectures.
Japan
High-efficiency cell architectures drive specification for advanced encapsulant materials with enhanced thermal stability and optical uniformity. METI industrial policies support domestic module producers requiring specialized barrier properties for extended service life requirements. Kanto and Kansai manufacturing belts concentrate demand from tier-one assemblers serving residential and commercial rooftop segments.
Solar EVA Market Competitive Landscape
Integrated extrusion specialists and regional film fabricators split the market between captive supply chains and merchant sales channels. The vendor base concentrates around three strategic archetypes: domestic Chinese producers with backward integration into vinyl acetate supply, European specialty formulators with REACH-certified chemistries, and Japanese conglomerates with diversified polymer portfolios. Dominant competitive moves include capacity expansion in Jiangsu province manufacturing corridors and strategic partnerships between extruders and tier-one module producers for dedicated production line allocations.
Within the integrated domestic tier, Hangzhou First PV Material Co., Ltd. and Jiangsu Akcome Solar Science & Technology Co., Ltd. exemplify Chinese producers leveraging captive demand from downstream module assembly operations. Coveme S.p.A occupies a position among European specialty formulators supplying optical-grade films for premium bifacial applications requiring REACH-compliant crosslinker chemistries. These three anchors represent distinct geographic and strategic positioning vectors across the encapsulant supply chain.
| Leading Market Players |
|---|
| DuPont-Mitsui Polychemicals Co., Ltd. |
| Wenzhou Ruiyang Photovoltaic Material |
| Hangzhou First PV Material Co., Ltd. |
| Coveme S.p.A |
| Zhejiang Feiyu Photoelectricity S&T Co., Ltd. |
| Bridgestone Corporation |
| Shenzhen Sveck Technology Co., Ltd. |
| Specialized Technology Resources, Inc. |
| Jiangsu Akcome Solar Science & Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Ningbo container corridor shapes cost dynamics across solar EVA procurement, with freight rate volatility amplifying price spreads between Jiangsu-based integrated producers and import-dependent Indian module assemblers. This logistics tension concentrates pricing power among domestic Chinese extruders while forcing downstream buyers into long-term offtake negotiations to hedge input cost instability.
Pricing Analysis
GB/T 29848 dictates the pricing tier structure across solar encapsulant procurement, separating optical-grade premium formulations from standard transparent grades used in commodity crystalline silicon modules. Three-tier pricing stratifies across REACH-certified specialty films, BIS-compliant imports for Indian government tenders, and domestic Chinese standard grades. Cost compression in standard transparent EVA is intensifying because of ethylene feedstock volatility and petrochemical capacity realignments across Asia. Price-sensitive Indian project developers under CEA tender structures drive the steepest procurement negotiations, while European bifacial module producers exhibit lowest sensitivity due to performance premiums for optical-grade encapsulants.
Supply Chain Analysis
Hangzhou First PV Material and Jiangsu Akcome Solar anchor contract-manufacturing concentration through integrated extrusion and captive lamination capacity serving downstream module assembly lines. Geographic supply concentrates in China, South Korea, and Japan, with Jiangsu province absorbing the majority of global film-grade EVA output under MIIT industrial clustering policies. Raw material dependencies rest on ethylene monomer from regional petrochemical complexes, vinyl acetate supply from acetic acid derivatives, and peroxide crosslinker chemistries subject to ECHA REACH restrictions. Single-source vulnerability runs through concentrated Chinese extrusion capacity controlling global film supply. Distribution runs through direct mill relationships displacing distributor intermediaries in bulk procurement for utility-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar EVA sits in early-cycle expansion as bifacial module architectures penetrate utility-scale procurement preference, with white EVA formulations capturing structural demand from power-optimized panel designs seeking maximum energy yield per square meter.
For Market Incumbents: Insulate formulation expertise through captive peroxide curing R&D investments as POE-based co-extruded encapsulants threaten standard EVA share in TOPCon cell architectures. Secure backward integration into vinyl acetate supply to defend margin position against ethylene feedstock volatility. Prioritize dual-certification pathways for GB/T 29848 and REACH compliance to capture premium positioning in European renewable energy auctions. For New Entrants and Emerging Players: European specialty film demand represents underpenetrated white-space where REACH-certified chemistries command pricing premiums unavailable to standard Asian exporters. Target automated layup integration partnerships with tier-one module producers seeking roll-format EVA compatible with high-throughput panel assembly lines. Pursue IS 16221 certification early to structure entry into Indian government-backed tenders under CEA procurement frameworks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant polymer film assets and existing ethylene infrastructure. Long-term viability hinges on consolidation plays across encapsulant formulation expertise and module assembly integration over the next decade. Watch for inflection signals in peroxide crosslinker chemistry substitution rates as ECHA regulatory updates force reformulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate | Secures input cost stability for Jiangsu-based extruders amid petrochemical realignments. |
| REACH Certification Investment | Unlocks European bifacial module supply chains subject to ECHA crosslinker restrictions. |
| Roll-Format Automation Partnership | Aligns with tier-one Chinese module producers compressing panel assembly cycle times. |
| IS 16221 Compliance Pathway | Structures entry into Indian CEA tender procurement for government-backed solar parks. |
| POE Co-Extrusion Capability Buildout | Captures TOPCon cell architecture demand requiring enhanced moisture barrier performance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, MIIT industrial policy filings, and BIS certification registries. Primary interviews engaged polymer chemists at film extrusion facilities, procurement leads at tier-one module manufacturers, and regulatory affairs specialists navigating REACH and GB standard compliance. Secondary validation drew from SAMR enforcement bulletins, CEA tender documentation, and ECHA Annex XVII restriction updates. Bottom-up volume estimates from extrusion capacity utilization triangulated against top-down demand projections from module installation forecasts.
Forecast inputs include ethylene feedstock pricing trajectories, bifacial module penetration rates across utility-scale procurement, and regulatory compliance timeline assumptions. Segmentation dimensions span product type, physical format, end-user integration level, and cell technology architecture. CAGRs derive from installed capacity buildout curves and encapsulant intensity per watt across crystalline silicon and bifacial configurations. The analytical framework incorporates MIIT clustering policy impacts on regional supply concentration and CEA tender structures shaping Indian procurement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by POE-based encapsulant specialists or accelerated ECHA regulatory timelines would shift outcomes. Forecasts assume continued ethylene supply availability from regional petrochemical complexes and stable crosslinker chemistry regulatory frameworks. Quarterly review of BIS certification issuance rates, Jiangsu province extrusion capacity utilization, and ECHA Annex XVII update schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Global Photovoltaic Glass Market