
 Global Micro Solar Inverter Market | 2026-2036
Global Micro Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro Solar Inverter Market Outlook
The capital-intensity divergence between vertically integrated and fabless players is redrawing competitive boundaries in micro solar inverter manufacturing. Enphase Energy leverages captive semiconductor sourcing to sustain margin stability across volatile raw material cycles. APsystems anchors its position through dedicated R&D facilities in Taiwan, while Hoymiles competes via aggressive cost engineering for emerging market price points.
A micro solar inverter converts direct current from individual photovoltaic modules into alternating current at the panel level, typically operating at 95-97% peak efficiency with maximum power point tracking performed per module rather than per string. Its primary purpose eliminates partial-shading losses and enables granular system monitoring in distributed solar architectures. Residential end users dominate volume demand as module-level electronics become standard in rooftop retrofits, while power optimizers capture growing share in commercial installations where string inverter retrofit economics remain favorable. On-grid installations lead technology deployment, though hybrid configurations integrating battery-based storage are gaining structural importance as net metering policies evolve.
The EU Green Deal and CE marking requirements under the F-Gas Regulation shape product efficiency benchmarks and material compliance obligations for equipment sold across member states. The US Federal Energy Regulatory Commission and state-level public utility commissions influence interconnection standards that determine micro inverter compatibility with grid infrastructure. China's Ministry of Industry and Information Technology administers GB standards affecting export manufacturing protocols for electronics producers. Stakeholders must monitor evolving distributed energy resource interconnection rules as utilities reconsider compensation structures for behind-the-meter generation.
Market Dynamics
Module-level power electronics are displacing centralized string architectures as residential installers prioritize shade resilience and granular performance visibility in rooftop solar deployments across high-insolation markets.
Growth Catalysts
- EU Green Deal mandates:Binding renewable energy targets under the EU Green Deal are accelerating distributed generation equipment upgrades across member states, with efficiency benchmarks tightening procurement specifications for behind-the-meter installations.
- Net metering policy evolution:State-level public utility commissions in California and Texas are revising compensation structures that favor module-level monitoring and battery-ready inverters for residential retrofits.
- Grid parity achievement:Levelized cost improvements in photovoltaic module manufacturing are expanding addressable markets for premium power electronics in Germany, Australia, and the southwestern United States.
Market Restraints
- Semiconductor input volatility:Silicon carbide and gallium nitride wafer supply concentration in East Asian foundries exposes margin stability to raw material cycle fluctuations.
- String inverter retrofit economics:Existing commercial installations with functional central inverters face replacement cost barriers that slow module-level electronics penetration in the C&I segment.
- F-Gas Regulation compliance:CE marking requirements under the EU F-Gas Regulation impose material compliance obligations and certification timelines that extend product launch cycles for European market entry.
Strategic Opportunities
- Battery-storage convergence:Hybrid inverter architectures integrating DC-coupled battery management systems are capturing structural importance as time-of-use rate structures spread across deregulated US electricity markets.
- Emerging market price points:Aggressive cost engineering for Southeast Asian and Latin American residential segments is opening volume channels where string inverter legacy dominance remains entrenched.
- Utility-scale distributed pilots:Agricultural and commercial ground-mount installations in India and Brazil are testing module-level electronics for operational resilience in high-soiling environments.
Industry Challenges
- Power electronics talent scarcity:Specialized firmware engineering for maximum power point tracking algorithms and grid-forming inverters commands premium compensation that strains R&D budgets at mid-scale manufacturers.
- Multi-jurisdiction certification timelines:Parallel UL 1741-SA, IEC 62109, and country-specific grid code approvals extend product development cycles and fragment engineering resource allocation.
- Legacy monitoring platform integration:Proprietary communication protocols from incumbent inverter manufacturers create switching friction for installers managing heterogeneous fleet visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro Solar Inverter Market |
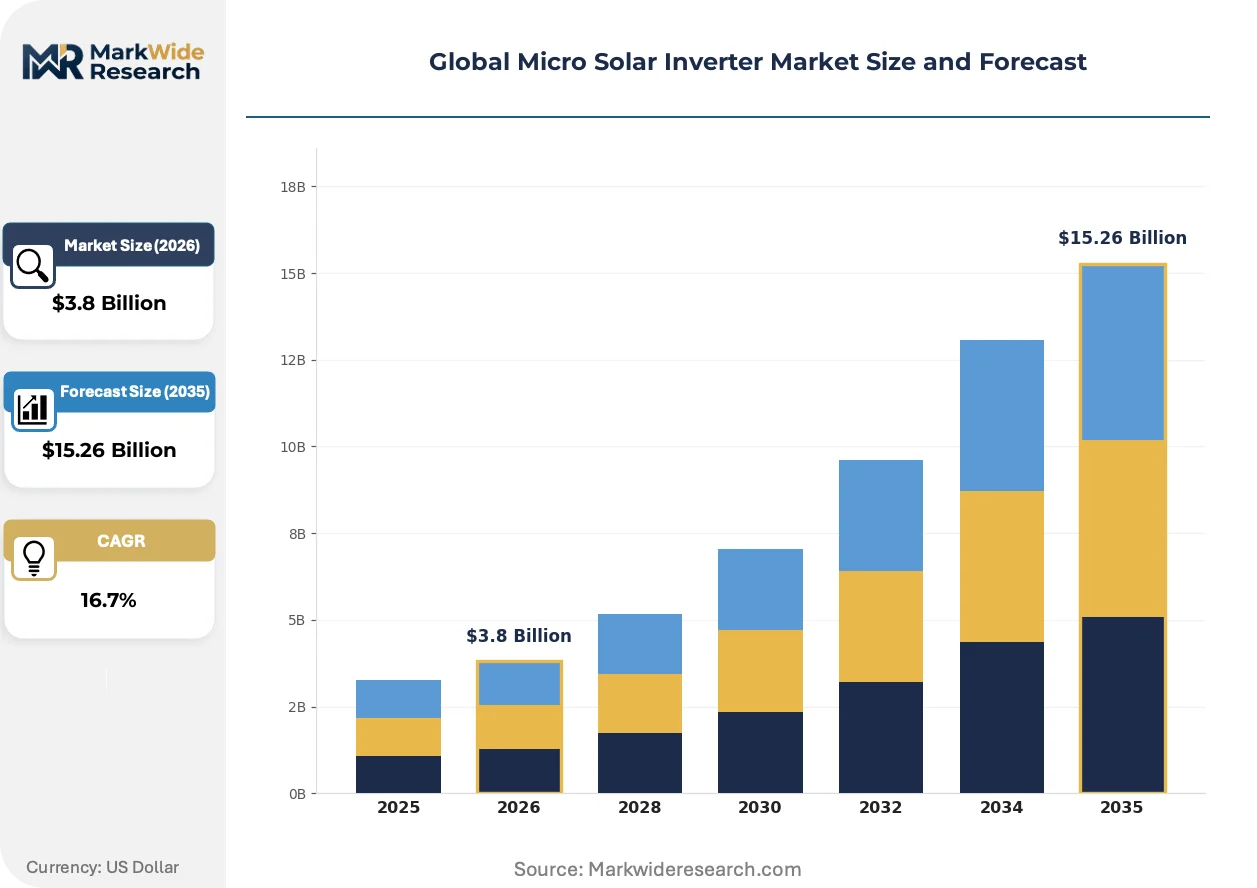
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverter, Micro Inverter, Power Optimizer, Hybrid Inverter End User: Residential, Commercial, Industrial, Utility Installation Type: On-grid, Off-grid, Hybrid, Standalone Technology: Grid-tied, Battery-based, Centralized, Decentralized |
| Companies Covered | Enphase Energy, APsystems, Darfon Electronics Corporation, Ningbo Deye Inverter Technology Co., Ltd, Sparq Systems, Hoymiles, Solis Solar, Hoymiles Power Electronics, Chilicon Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro Solar Inverter Market Strategic Shifts
Silicon carbide power semiconductors and cloud-native monitoring platforms are compressing cost-performance tradeoffs while expanding operational visibility for distributed solar asset managers.
Gallium nitride switching devices are bifurcating efficiency and thermal performance benchmarks in next-generation micro inverter designs. Residential installers in California and Texas are specifying GaN-based units for compact form factors that reduce rooftop labor hours. This semiconductor transition is bifurcating the competitive landscape between captive foundry players and fabless designers dependent on merchant wafer supply.
The EU F-Gas Regulation and associated CE marking requirements are mandating fluorinated gas phase-out timelines for cooling systems in power electronics enclosures. Equipment manufacturers are redesigning thermal management architectures to maintain IP ratings without conventional refrigerants. German and Dutch distributors are prioritizing compliant SKUs ahead of enforcement deadlines, compressing inventory turnover for legacy product lines.
Installer procurement patterns are consolidating around vertically integrated distributors offering bundled design software, permitting services, and fleet monitoring subscriptions. Regional solar wholesalers in the US Southwest are displacing traditional electrical supply houses by embedding financing pre-qualification tools in their digital platforms. This channel evolution is most visible in Arizona and Colorado, where residential deployment velocity depends on streamlined customer acquisition economics.
Global Micro Solar Inverter Market Segmentation
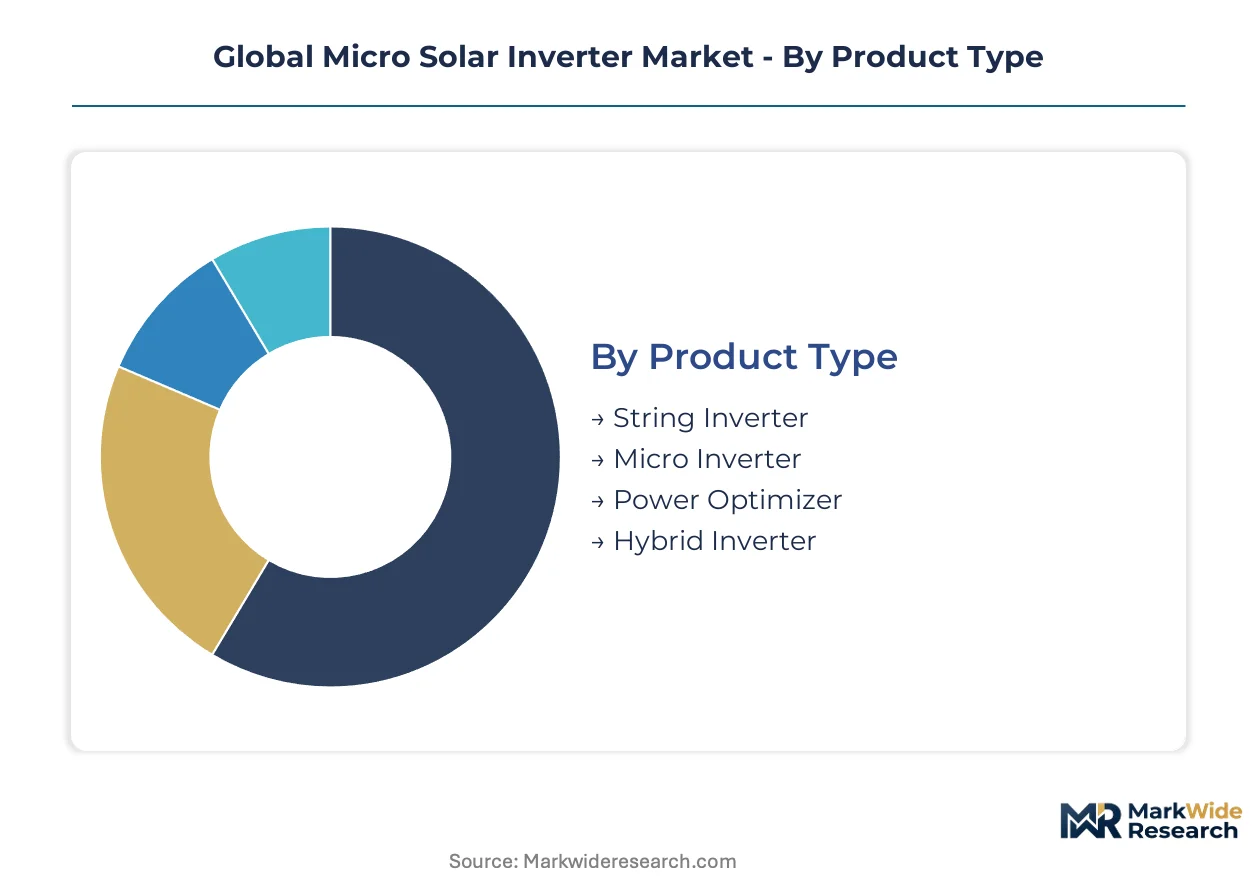
Module-level power electronics fragment across competing architectures that trade off upfront cost against lifetime energy yield and monitoring granularity. Installers select configurations based on shading profiles, retrofit constraints, and local interconnection standards that favor specific technical approaches.
Product Type:
Margin pools concentrate in semiconductor-integrated designs where captive wafer supply buffers raw material volatility.
- Micro Inverter:Panel-level DC-to-AC conversion with per-module maximum power point tracking eliminates string mismatch losses. California and Texas residential installers specify these for complex roof geometries where partial shading degrades centralized architectures.
- Power Optimizer:DC-to-DC conditioning at the module feeds centralized string inverters, preserving retrofit economics in commercial installations where existing inverter infrastructure remains functional. Australian C&I deployments favor this hybrid path for shade resilience without full inverter replacement.
- String Inverter:Centralized DC-to-AC conversion for series-connected modules dominates utility-scale ground-mount economics in India and Brazil.
- Hybrid Inverter:Integrated battery management enables DC-coupled storage for time-of-use arbitrage in deregulated US electricity markets.
Micro Inverter holds installed capacity. Power Optimizer is rotating up the share rankings.
End User:
Volume concentration follows rooftop retrofit velocity where net metering policy structures determine payback periods.
- Residential:Behind-the-meter installations in Germany and Australia drive module-level electronics adoption as grid parity improves for distributed generation. Shade resilience and granular monitoring justify premium pricing over string alternatives.
- Commercial:Flat-roof warehouses and retail facilities in the southwestern United States balance optimizer economics against full micro inverter conversion costs.
- Industrial:Large manufacturing rooftops with uniform exposure favor string architectures where inverter redundancy matters less than capital efficiency.
- Utility:Ground-mount solar farms in India pilot module-level electronics for soiling resilience and operational visibility in high-dust environments.
Residential dominates addressable volume. Commercial is climbing the fastest as optimizer retrofit economics improve.
Installation Type:
Grid interconnection rules in major markets privilege architectures that support export compensation and anti-islanding protection.
- On-grid:Synchronous connection to distribution infrastructure enables net metering revenue streams under FERC and state PUC standards across the United States.
- Off-grid:Standalone systems with battery storage serve remote residential applications in Australia and rural Brazil where grid extension costs prove prohibitive.
- Hybrid:Grid-connected with backup capability captures structural importance as California NEM 3.0 and Texas volatile pricing reward self-consumption optimization.
- Standalone:Agricultural water pumping and telecom tower applications in India deploy DC-coupled configurations without grid synchronization requirements.
On-grid retains deployment leadership. Hybrid is gaining share fastest as battery integration becomes standard specification.
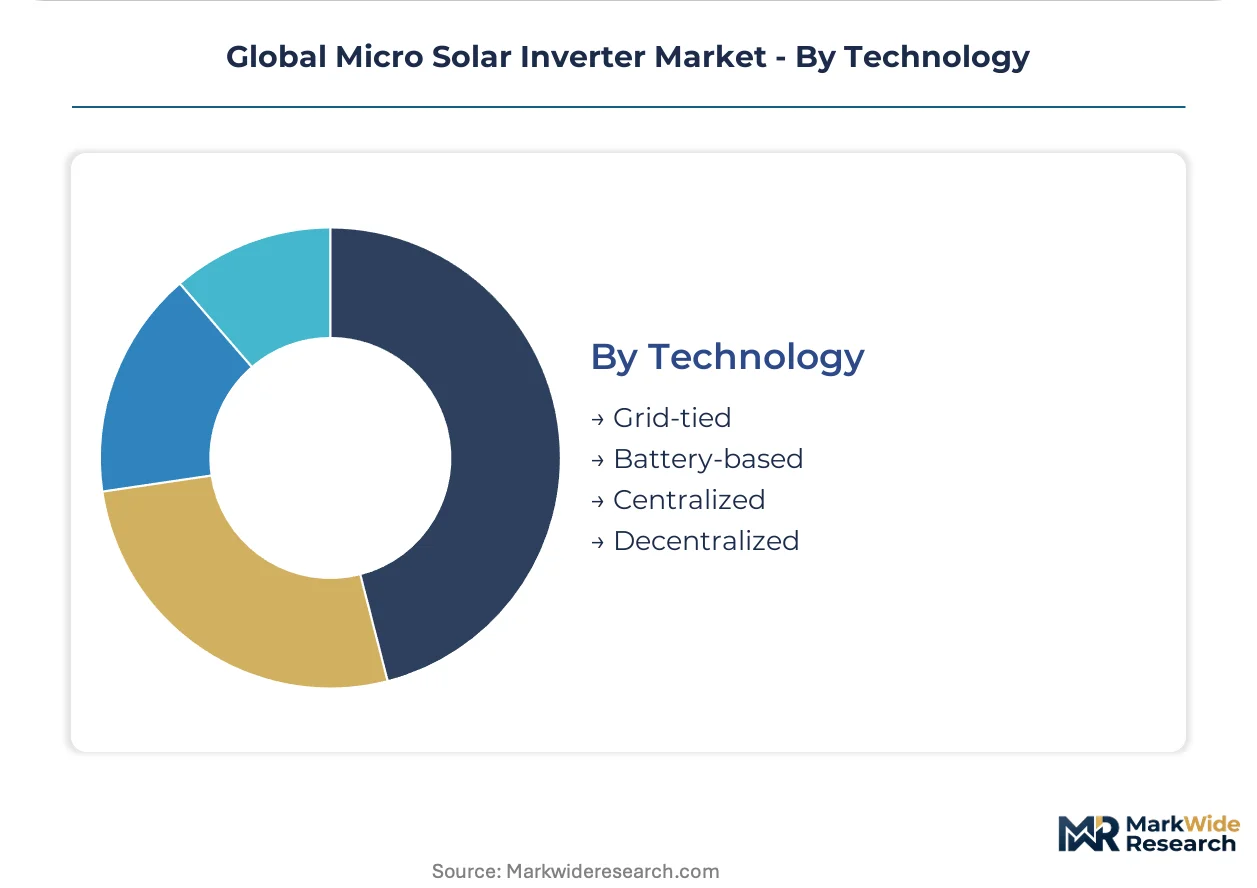
Technology:
Silicon carbide and gallium nitride switching devices are bifurcating efficiency benchmarks between incumbent silicon and next-generation wide-bandgap designs.
- Grid-tied:Synchronous inverters meeting IEEE 1547 and UL 1741-SA standards dominate US residential procurement where utility interconnection approval determines product eligibility.
- Battery-based:DC-coupled storage integration enables backup power and arbitrage functionality as German and Australian markets evolve beyond pure feed-in-tariff structures.
- Centralized:String and central inverter architectures persist in utility-scale deployments where module-level electronics cost premiums face procurement scrutiny.
- Decentralized:Panel-level power electronics with independent MPPT maximize energy harvest in shaded or soiled conditions across distributed rooftop portfolios.
Grid-tied maintains volume concentration. Battery-based is expanding most quickly as storage attachment rates rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and Australian buyers absorb premium pricing for module-level electronics, while Indian and Brazilian procurement remains tethered to string inverter economics despite improving grid parity.
United States
California and Texas residential retrofits drive specification of battery-ready micro inverters as NEM 3.0 and volatile wholesale pricing reward self-consumption optimization. FERC Order 2222 and state PUC interconnection standards determine product eligibility across deregulated electricity markets. The Southwest corridor from Phoenix to Denver concentrates installer procurement through vertically integrated distributors embedding financing tools.
Germany
Behind-the-meter rooftop deployments accelerate as feed-in-tariff structures evolve toward market premium mechanisms. The EU Green Deal and F-Gas Regulation impose CE marking compliance and fluorinated gas phase-out timelines for power electronics enclosures. Bavaria and Baden-Württemberg host dense installer networks specifying efficiency-optimized units for residential retrofits.
Australia
High-insolation markets in Queensland and New South Wales favor module-level power electronics for shade resilience and granular monitoring in distributed portfolios. The national Clean Energy Regulator administers SRES certificate mechanisms that influence equipment upgrade cycles. Sydney and Melbourne installer channels consolidate procurement around bundled design software and fleet monitoring subscriptions.
China
Export manufacturing protocols under MIIT-administered GB standards shape production configurations for equipment destined for European and North American markets. The Yangtze River Delta and Pearl River Delta concentrate foundry capacity for silicon carbide and gallium nitride wafer supply. Domestic distributed generation uptake lags export volumes as centralized utility-scale architectures dominate procurement.
India
Agricultural and commercial ground-mount installations in Gujarat and Rajasthan pilot module-level electronics for operational resilience in high-soiling environments. CEA technical standards and state-level net metering policies determine interconnection economics for behind-the-meter generation. Bangalore and Hyderabad engineering clusters develop firmware capabilities for maximum power point tracking algorithms serving export markets.
Global Micro Solar Inverter Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in micro solar inverter manufacturing. Captive semiconductor sourcing distinguishes the upper tier from fabless competitors exposed to raw material volatility. Three archetypes populate the landscape: vertically integrated players with captive foundry relationships, R&D-anchored specialists with dedicated facilities, and cost-engineered challengers targeting emerging market price points. Capacity expansion and backward integration into power semiconductor supply represent the dominant competitive moves.
Among North American-anchored integrated players, Enphase Energy exemplifies the captive-sourcing archetype. APsystems occupies a position within the R&D-specialist tier through its Taiwan-based engineering footprint. Hoymiles represents the cost-engineered challenger archetype competing on aggressive price positioning for emerging market penetration.
| Leading Market Players |
|---|
| Enphase Energy |
| APsystems |
| Darfon Electronics Corporation |
| Ningbo Deye Inverter Technology Co., Ltd |
| Sparq Systems |
| Hoymiles |
| Solis Solar |
| Hoymiles Power Electronics |
| Chilicon Power |
| Others |
Value Chain & Pricing Dynamics
Foundry-scale economies in silicon carbide wafer fabrication concentrate margin control among captive-sourcing players while compressing price floors for fabless competitors exposed to merchant supply volatility. This scale asymmetry shapes procurement negotiations across California and Texas residential installer channels where module-level power electronics specifications are tightening.
Pricing Analysis
After-sales revenue from fleet monitoring subscriptions and extended warranty contracts drives lifetime value differentiation across manufacturer tiers. Pricing stratifies across premium GaN-based units with embedded battery management, standard silicon IGBT designs for retrofit compatibility, and economy-tier alternatives for emerging market penetration. Cost compression in the economy tier is intensifying as Hoymiles and challengers pursue aggressive price positioning for Southeast Asian residential segments. Commercial installers exhibit highest price sensitivity due to string inverter retrofit economics, while residential buyers in Germany and Australia absorb premiums for shade resilience and granular monitoring capabilities.
Supply Chain Analysis
Strategic stockpiling of silicon carbide and gallium nitride wafers distinguishes vertically integrated players from just-in-time dependent competitors during raw material cycle fluctuations. Taiwan, South Korea, and China concentrate foundry capacity for wide-bandgap semiconductor substrates that feed micro inverter assembly operations. Manufacturing rests on gallium nitride-on-silicon wafers, silicon carbide MOSFETs, and magnetics components subject to East Asian supply concentration. Single-source vulnerability in Taiwanese foundry relationships exposes margin stability to geopolitical disruption. Distribution runs through vertically integrated solar distributors in the US Southwest and dedicated electrical wholesalers in Germany and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module-level power electronics are approaching a platform-economics inflection as proprietary communication protocols give way to open monitoring standards and interoperable battery management interfaces.
For Market Incumbents: Secure captive foundry relationships for silicon carbide and gallium nitride wafer supply to buffer margin stability against raw material volatility from East Asian concentration. Deepen backward integration into power semiconductor supply chains as fabless competitors face procurement cost disadvantages. Prioritize certification investment for UL 1741-SA and IEC 62109 grid-code compliance to defend position against emerging challengers exploiting parallel approval timelines. For New Entrants and Emerging Players: Installer-facing software gaps in fleet monitoring and permitting workflow integration represent underserved white-space where incumbents under-serve mid-scale residential contractors. Target Latin American and Southeast Asian residential segments where string inverter legacy dominance remains entrenched and price-sensitive procurement favors aggressive cost engineering. Pursue white-label partnerships with regional solar wholesalers as the primary go-to-market angle to bypass incumbent channel control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated players with captive monitoring platform subscriptions and long-term service contracts. Long-term viability over the next decade favors manufacturers with backward integration into power semiconductor supply and diversified geographic production footprints. Acquisition target archetype: mid-scale specialists with R&D-anchored positions in Taiwan or China and established certification portfolios for European and North American markets. Watch silicon carbide wafer supply allocation announcements as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Partnership | Silicon carbide wafer supply security buffers margin volatility from East Asian concentration. |
| Hybrid Inverter Platform Launch | DC-coupled battery integration captures California NEM 3.0 self-consumption optimization demand. |
| Open Protocol Certification | IEEE 2030.5 compliance reduces installer switching friction in heterogeneous fleet deployments. |
| Emerging Market Cost Engineering | Aggressive price positioning unlocks volume channels in Brazil and India where string alternatives dominate. |
| Vertical Distributor Integration | Embedded financing tools in Arizona and Colorado channels compress customer acquisition economics. |
Study Parameters
Operator-level perspectives from residential installer procurement managers, utility interconnection engineers, EPC project developers, and power electronics firmware architects anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC interconnection filings, EIA distributed generation databases, IEC standard revision drafts, and EU F-Gas Regulation compliance bulletins. Bottom-up equipment shipment estimates triangulated against top-down addressable market calculations across the analysis window.
Sensitivity analysis tested demand elasticity under varying net metering policy scenarios and raw material cost assumptions throughout the forecast period. Segmentation modeling incorporated product architecture, end-user category, installation type, and switching technology as core dimensions. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and policy-driven inflection points. Key forecast inputs included residential retrofit velocity in California and Texas, EU Green Deal implementation timelines, and silicon carbide foundry capacity expansion announcements.
Underlying assumptions cover grid parity trajectory in target markets, F-Gas Regulation enforcement consistency, and Taiwan-China supply chain stability, with deviation risk concentrated in semiconductor input volatility and state-level net metering revisions. Revision becomes warranted when battery attachment rates in residential installations or silicon carbide wafer allocation ratios cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Solar PV Panels Market