
 Solar Photovoltaic (PV) Market | 2026-2036
Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Photovoltaic (PV) Market Intelligence
The bundling of PV panels with energy storage and management software into integrated residential systems is expanding the addressable market for homeowners. LONGi Solar leverages its massive scale in monocrystalline wafer and cell production to maintain cost leadership. Jinko Solar differentiates through its global distribution network and focus on high-efficiency n-type technologies. Canadian Solar sustains a strong position by operating across both module manufacturing and downstream project development.
Solar photovoltaic technology converts sunlight directly into electricity through the photovoltaic effect within semiconductor materials, typically silicon-based p-n junctions. Its primary purpose is clean power generation for applications ranging from small off-grid systems to large-scale power plants. Monocrystalline silicon products dominate new installations due to superior efficiency and performance. Ground-mounted utility projects represent the largest installation segment by capacity, while rooftop residential systems are pivotal for distributed energy resources.
Government policies like the US Inflation Reduction Act (IRA) and the EU Green Deal provide significant financial incentives and long-term deployment targets. Concurrently, China's dual carbon goals mandate massive renewable energy expansion, shaping global supply and demand dynamics. The critical challenge for manufacturers will be managing the rapid technological transition from PERC to next-generation cell architectures like TOPCon and HJT.
Market Dynamics
The rapid technological transition from PERC to next-generation cell architectures like TOPCon and HJT acts as the central structural force. This shift compels significant capital investment and redefines competitive advantage based on manufacturing process control and efficiency gains.
Growth Catalysts
- Policy Support:Incentives like the US Inflation Reduction Act and India's PLI scheme directly reduce project costs, accelerating utility-scale and residential solar installations.
- Corporate Procurement:Companies are increasingly signing Power Purchase Agreements (PPAs) to meet ESG goals, creating a stable demand channel for new solar capacity.
- Economic Competitiveness:The falling levelized cost of energy (LCOE) for solar makes it a financially viable alternative to fossil fuels for new power generation in many regions.
Market Restraints
- Grid Integration Hurdles:The intermittent nature of solar generation requires significant investment in grid modernization and energy storage to ensure system stability, creating bottlenecks in high-penetration areas.
- Supply Chain Concentration:Heavy reliance on China for key materials like polysilicon and for wafer and cell manufacturing creates geopolitical and logistical risks for global developers.
- Land Use Conflicts:Large-scale, ground-mounted utility projects face increasing opposition and lengthy permitting processes due to competition for land with agriculture and conservation efforts.
Strategic Opportunities
- Emerging Applications:Agrivoltaics, which co-locates solar panels with agricultural activities, and building-integrated photovoltaics (BIPV) open new avenues for deployment in land-constrained areas.
- Green Hydrogen Production:Coupling large-scale solar farms with electrolyzers offers a pathway to produce green hydrogen at competitive costs, unlocking a major new industrial end-use.
- Underpenetrated Markets:Many countries in Africa and Southeast Asia represent significant growth potential, driven by rising energy demand, favorable solar irradiance, and off-grid power needs.
Industry Challenges
- Technology Transition Capex:Manufacturers face immense capital requirements to retool production lines from PERC to newer TOPCon and HJT cell technologies to remain competitive on efficiency.
- End-of-Life Management:The lack of a scaled, cost-effective recycling infrastructure for decommissioned PV panels presents a significant long-term environmental and logistical challenge.
- Skilled Labor Gaps:A deficit of trained installers and technicians constrains deployment speed, particularly for distributed residential and commercial systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Photovoltaic (PV) Market |
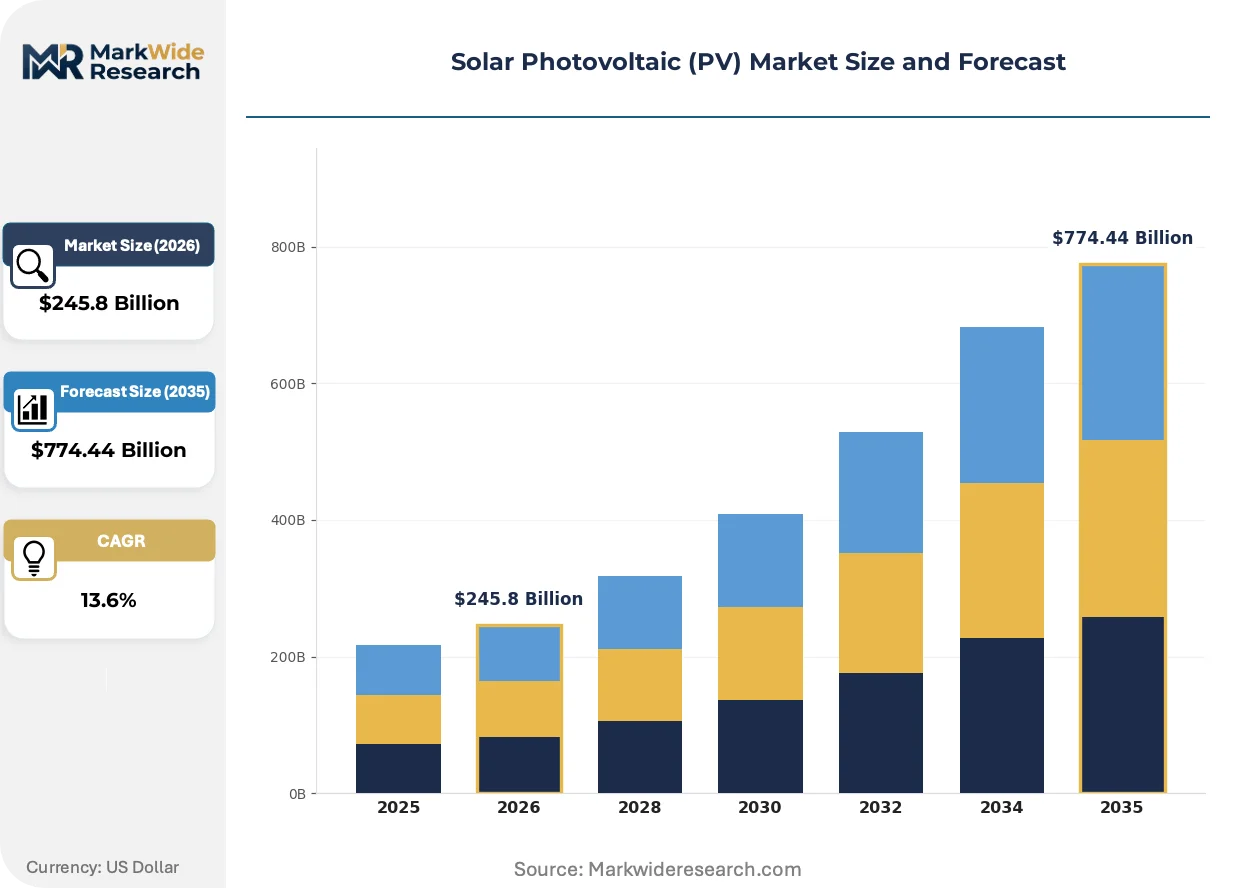
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $774.44 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial, Concentrated PV Installation: Rooftop Residential, Ground-Mounted Utility, Floating, Building-Integrated, Carport Application: Power Generation, Off-Grid Systems, Telecom Towers, Agriculture, Military End User: Independent Power Producers, Commercial Establishments, Government Agencies, Rural Electrification Projects, Non-Governmental Organizations |
| Companies Covered | LONGi Solar, Trina Solar, Tongwei Solar, Hanwha Q CELLS, Canadian Solar, JA Solar, Aiko Solar, DAS Solar, Jinko Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Photovoltaic (PV) Market Strategic Shifts & Innovations
The industry is undergoing a fundamental re-evaluation of value, moving beyond pure panel efficiency. This shift prioritizes system-level integration, supply chain resilience, and the bankability of next-generation technologies to meet decarbonization goals.
TOPCon and HJT cell architectures are advanced semiconductor designs that improve electron capture, boosting module efficiency beyond PERC technology. Major manufacturers are rapidly shifting production to these platforms to secure premium market segments. This pivot is rewriting the cost-performance calculus for utility-scale project developers and asset owners.
Policy frameworks like the EU Green Deal mandate aggressive carbon emission reductions, creating durable support for renewable energy. This accelerates permitting for solar projects and provides financial backing through mechanisms like the REPowerEU plan. The policy's impact is most pronounced in utility and commercial rooftop segments across Germany, Spain, and the Netherlands.
Residential customers are adopting integrated home energy solutions combining solar panels with battery storage and smart management software. This trend bypasses the traditional component-based sale, favoring installers offering a single system. The shift is most advanced in markets with high electricity rates, such as California and parts of Australia.
Solar Photovoltaic (PV) Market Segmentation
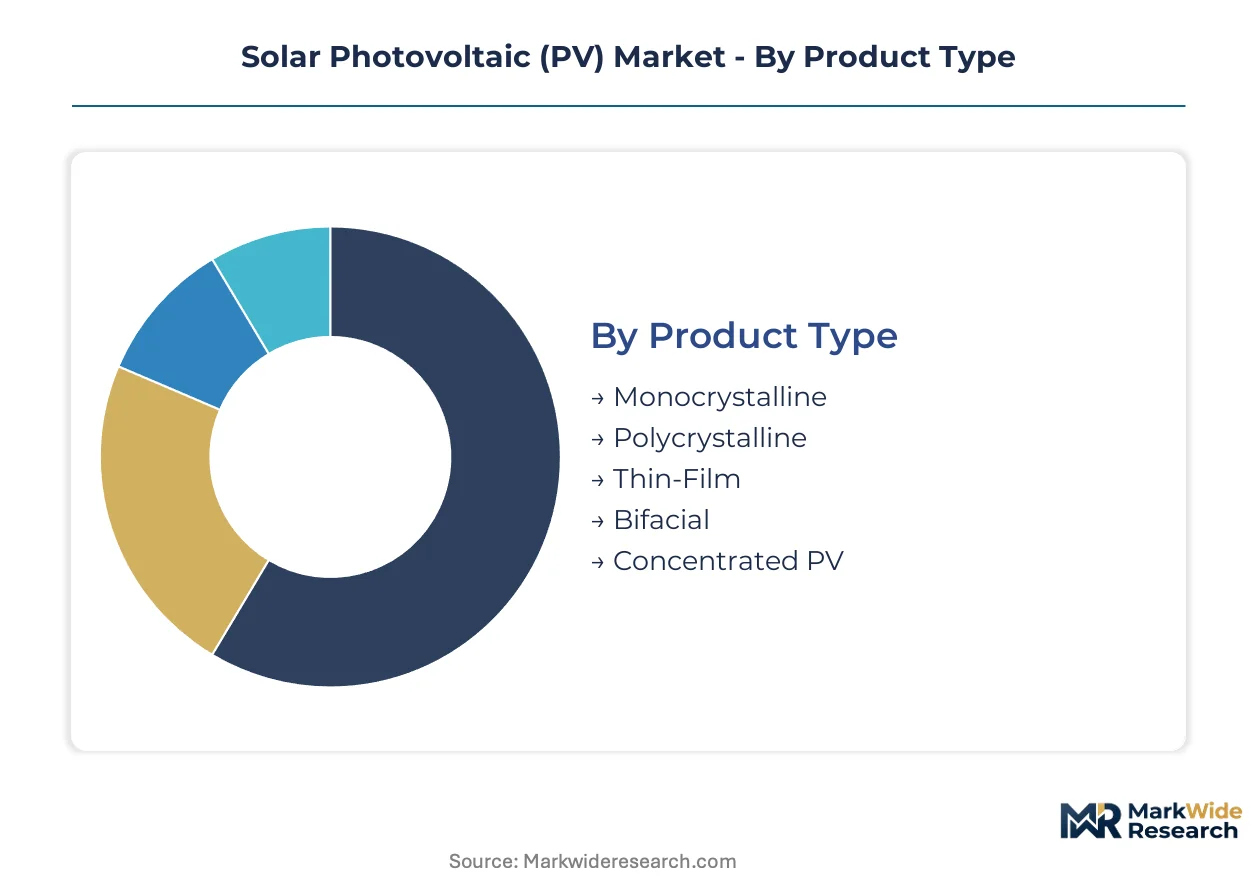
The solar photovoltaic market segments across various dimensions, reflecting diverse technological pathways and deployment models. Understanding these distinctions is crucial for identifying specific growth pockets and competitive advantages. Each segment responds differently to policy incentives and technological advancements, shaping investment priorities.
Product Type:
The supply chain for solar PV products is heavily concentrated around specific manufacturing technologies, influencing global availability and cost structures.
- Monocrystalline:These panels utilize single-crystal silicon, offering superior efficiency and performance, making them dominant in new installations. Demand concentrates in utility-scale projects and premium residential systems due to their high power output per square meter.
- Bifacial:Bifacial modules capture sunlight from both front and rear sides, increasing energy yield, especially over reflective surfaces like white roofs or ground. Their adoption expands in ground-mounted utility projects seeking maximum land utilization and higher power density.
- Polycrystalline:Polycrystalline panels, made from multiple silicon crystals, offer a cost-effective alternative for budget-conscious projects.
- Thin-Film:Thin-film technologies use semiconductor layers, offering flexibility and aesthetic integration in niche applications.
- Concentrated PV:CPV systems focus sunlight onto small, high-efficiency cells, primarily deployed in high-direct-irradiance regions.
Today's leader: Monocrystalline. Tomorrow's challenger: Bifacial.
Installation:
Deployment methodologies vary significantly based on available land, grid infrastructure, and specific application requirements for solar energy systems.
- Ground-Mounted Utility:These large-scale installations deploy panels on open land, generating power for the grid, often developed by independent power producers. Their expansion is driven by the falling levelized cost of energy (LCOE) and corporate procurement for ESG goals.
- Rooftop Residential:Panels are installed on residential building rooftops, providing distributed energy for homeowners and reducing electricity bills. High electricity rates in markets like California and Australia stimulate homeowner adoption alongside battery storage.
- Floating:Floating solar arrays on water bodies reduce land use and offer cooling benefits to panels.
- Building-Integrated:BIPV systems integrate panels directly into building materials, serving aesthetic and power generation purposes.
- Carport:Carport solar panels form canopies over parking, providing shade and generating electricity for EV charging or grid.
Ground-mounted projects currently command the largest capacity, while residential systems are gaining share rapidly.
Application:
The volume of solar PV deployment is primarily dictated by its intended use, ranging from large-scale grid supply to specialized niche requirements.
- Power Generation:This represents the largest application, where solar arrays directly feed electricity into national or regional grids for widespread consumption. Government policies like the US IRA and the EU Green Deal consistently support this segment's expansion.
- Off-Grid Systems:These systems provide electricity to remote areas without grid access, crucial for rural electrification and energy independence. Demand for these solutions is high in underpenetrated markets across Africa and Southeast Asia.
- Telecom Towers:Solar power provides reliable, cost-effective energy for remote cellular base stations, reducing diesel reliance.
- Agriculture:Agrivoltaics combines solar panels with farming, providing energy for irrigation and optimizing land use for crops.
- Military:Solar solutions offer tactical advantages for military operations, providing silent, portable power for field equipment.
Grid-connected power generation drives the bulk of installations, with off-grid solutions expanding most quickly in emerging economies.
End User:
Different customer types drive solar PV adoption based on their energy needs, investment capabilities, and sustainability objectives.
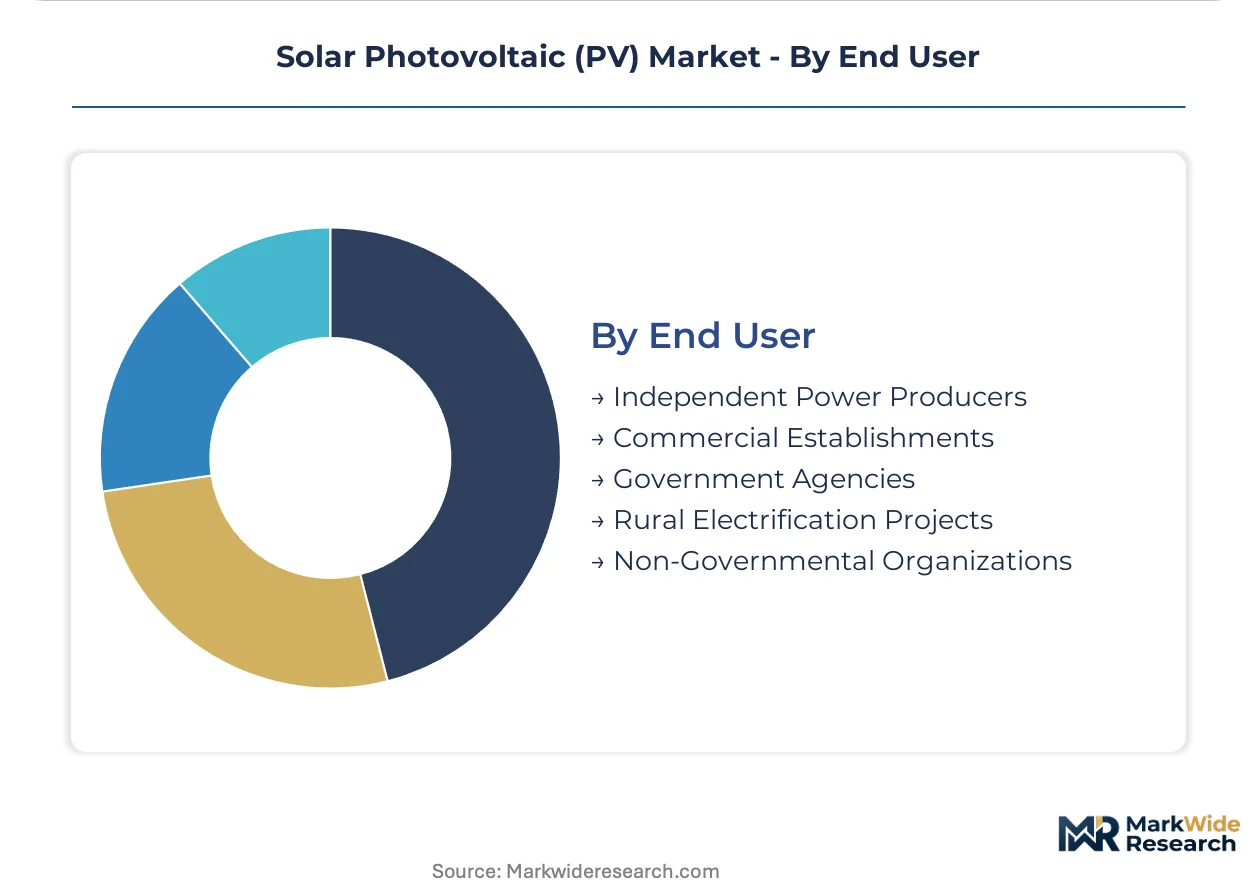
- Independent Power Producers:IPPs develop, own, and operate solar power plants, selling electricity to utilities or directly to large consumers via Power Purchase Agreements. Their activity is concentrated in utility-scale projects, driven by long-term revenue streams and favorable policy frameworks.
- Commercial Establishments:Businesses install solar on their premises to reduce operating costs, enhance energy security, and meet corporate ESG goals. This segment sees strong uptake in regions with high commercial electricity prices and supportive net-metering policies.
- Government Agencies:Government agencies deploy solar for facilities and infrastructure, demonstrating commitment to renewable energy and sustainability targets.
- Rural Electrification Projects:Rural electrification initiatives bring electricity to remote communities through decentralized solar solutions, often with development funds.
- Non-Governmental Organizations:NGOs utilize solar power for humanitarian aid, community development, and disaster relief where grid access is unreliable.
Independent Power Producers represent the largest purchasing power, while commercial entities are increasingly investing in onsite generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The solar photovoltaic industry's foundational scaling occurred in Germany and Japan, driven by early government support and R&D investments. These nations pioneered feed-in tariffs and significant deployment targets, establishing initial manufacturing capabilities. This early momentum laid the groundwork for subsequent global expansion and technological advancements.
China
Demand for solar PV in China is fueled by massive utility-scale projects and ambitious dual carbon goals. The Chinese government's "dual carbon" targets mandate extensive renewable energy expansion, shaping global supply and demand dynamics. Production gravity centers on provinces like Jiangsu and Zhejiang, where major manufacturers rapidly scale TOPCon and HJT cell architectures.
United States
The United States experiences strong demand for both utility-scale and residential solar installations, driven by decarbonization efforts. The US Inflation Reduction Act (IRA) provides significant financial incentives and long-term deployment targets for domestic manufacturing. California and Texas lead in new capacity additions, with major project development concentrated in these sun-rich states.
Germany
Germany's solar market benefits from high electricity rates and a strong commitment to the EU Green Deal. The EU Green Deal mandates aggressive carbon emission reductions, accelerating permitting for solar projects. Bavaria and North Rhine-Westphalia are key regions for commercial rooftop installations and innovative energy storage integration.
India
India's solar deployment is propelled by rising energy demand and the need for energy independence. The Production Linked Incentive (PLI) scheme accelerates domestic manufacturing and deployment of high-efficiency modules. Rajasthan and Gujarat attract large-scale solar parks, becoming hubs for independent power producers.
Japan
Japan's solar market prioritizes energy security and technological innovation following previous energy crises. The Ministry of Economy, Trade and Industry (METI) supports advanced PV research and deployment incentives. Regions like Fukushima and Hokkaido are seeing new utility-scale projects, often integrating advanced grid stabilization technologies.
Solar Photovoltaic (PV) Market Key Industry Players
Premium-margin players sit above commodity-margin players across efficiency and technological advancement within the solar PV market. The industry structure is tiered, featuring large, vertically integrated manufacturers alongside specialized component suppliers and downstream project developers. Strategic archetypes include scale-driven module producers, high-efficiency cell innovators, and full-service project integrators. Dominant competitive moves involve rapid capacity expansion and strategic partnerships for technology co-development, often targeting next-generation cell architectures.
At the scale-driven end, LONGi Solar exemplifies a manufacturer leveraging massive production capabilities in monocrystalline wafers and cells. Jinko Solar, a Chinese-based Co., Ltd., represents companies focused on global distribution networks and the rapid adoption of high-efficiency n-type technologies. Canadian Solar, a Canada-based Inc., occupies a position as a vertically diversified player, integrating module manufacturing with downstream project development. These companies anchor their respective strategic approaches through consistent investment in manufacturing scale and technological differentiation.
| Leading Market Players |
|---|
| LONGi Solar |
| Trina Solar |
| Tongwei Solar |
| Hanwha Q CELLS |
| Canadian Solar |
| JA Solar |
| Aiko Solar |
| DAS Solar |
| Jinko Solar |
Cost & Logistics Intelligence
The rapid technological transition from PERC to next-generation cell architectures like TOPCon and HJT simultaneously reshapes cost economics and supply concentration. This shift compels significant capital investment for manufacturers, redefining competitive advantage based on process control and efficiency gains.
Pricing Analysis
Project-based and long-term contract pricing dominates the utility-scale solar PV market, driven by Power Purchase Agreements. Price differentiation stems from module efficiency, with premium n-type technologies commanding higher prices, and brand reputation influencing buyer decisions. Pricing pressure stems from intense competition and oversupply, particularly from Chinese manufacturers, impacting commodity-grade PERC modules. Utility-scale Independent Power Producers exhibit the highest price sensitivity, prioritizing the lowest levelized cost of energy, while residential customers value integrated system performance over raw component cost.
Supply Chain Analysis
Direct sales to large Independent Power Producers and distribution networks serving residential and commercial installers define the solar PV supply chain. Geographic supply concentration centers heavily on China for polysilicon, silicon wafers, and cell manufacturing, with emerging module assembly capacity in the United States and India. The industry draws from critical raw material dependencies including polysilicon, glass, and silver paste. Geopolitical risks associated with this concentration create a structural supply chain vulnerability, particularly for developers outside Asia. Distribution runs through a mix of direct OEM sales to large projects and a fragmented network of regional distributors and installers for smaller systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, as demand shifts decisively toward premium, high-efficiency n-type modules and integrated energy solutions.
For Market Incumbents:
Hedge against technological obsolescence by accelerating R&D and capital investment in TOPCon and HJT cell architectures. Diversify manufacturing footprints geographically, establishing capacity in regions like India and the United States to mitigate geopolitical supply chain risks and leverage local incentives. Consolidate market share through strategic partnerships for energy storage and smart software integration, addressing the threat of fragmented residential solutions. Reinforce brand equity through proven long-term performance and bankability for utility-scale project developers.
For New Entrants and Emerging Players:
Underserved off-grid communities in Africa and Southeast Asia represent a significant entry point for new players. Target niche applications like agrivoltaics and building-integrated photovoltaics (BIPV) in land-constrained regions with high energy demand. Focus on offering integrated residential energy solutions, bundling panels with battery storage and smart management software, to differentiate from component-based competitors. A go-to-market angle emphasizing localized service and tailored financing models can penetrate these under-served markets effectively.
For Investors and Strategic Acquirers:
Valuations sit cheapest among specialized component suppliers and software providers enabling grid integration and energy management. Focus on long-term viability in the context of global decarbonization goals and national energy independence mandates. Identify acquisition targets with strong intellectual property in next-generation cell technologies or proven expertise in integrated energy solutions. The signal to watch is the sustained increase in grid modernization investments across developed and emerging economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (TOPCon/HJT) | Secures market share in high-efficiency segments for major manufacturers globally. |
| Vertical Integration (Storage/Software) | Captures higher value by offering integrated residential energy solutions to homeowners. |
| Geographic Diversification (Manufacturing) | Mitigates supply chain risks and geopolitical dependencies on Chinese production. |
| Power Purchase Agreement (PPA) Structuring | Ensures stable long-term demand for utility-scale solar projects for IPPs. |
| R&D Investment (Perovskite/Tandem Cells) | Positions companies for future efficiency leadership beyond current silicon technologies. |
Research Approach
Bottom-up power generation modeling reconciled against top-down module supply tracking forms the analytical core of this study. Primary interviews with Independent Power Producer project developers, module manufacturers, residential installers, and government policy makers provided critical qualitative insights. Secondary validation drew from IEA reports, EIA data, company 10-K filings, and national energy agency reports, ensuring data robustness and market context.
An input-output matrix frames the forecast framework, projecting market trajectories across the analysis window. This model incorporates segmentation dimensions including product type, installation, application, end user, and regional policy environment. Compound Annual Growth Rates were derived through regression analysis and market share projections, integrating key industry-specific forecast inputs such as Levelized Cost of Energy trends and national renewable energy targets.
Inputs from public financial filings and national energy statistics were available through the study window; gaps in emerging market deployment data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological advancement. Periodic stress-testing of base assumptions is recommended to account for geopolitical trade policies, raw material price volatility, and grid integration challenges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Third Generation Solar Cell Sales Market