
 South America Solar Photovoltaic Market | 2026-2036
South America Solar Photovoltaic Market Size, Share, and Industry Trends Forecast 2026-2036
South America Solar Photovoltaic Market Analytics
Turnkey engineering-procurement-construction bundling is consolidating buyer choice across the South America solar photovoltaic landscape. Enel Américas leverages its integrated development platform to capture utility-scale contracts in Chile and Peru. Neoenergia S.A. anchors its position through transmission access and distributed generation franchises in Brazil's regulated markets. Atlas Renewable Energy differentiates via long-term power purchase agreements with corporate offtakers across the Andean region.
Solar photovoltaic systems convert sunlight into direct-current electricity through semiconductor p-n junctions, with monocrystalline silicon cells achieving conversion efficiencies above 22% under standard test conditions. The technology serves grid-connected power generation, off-grid rural electrification, and industrial self-consumption applications. Bifacial modules command premium positioning due to dual-side energy yield gains in high-albedo environments. Utility end users represent the dominant value pool, though residential rooftop segments accelerate through net metering frameworks. Ground-mounted installations sustain the largest capacity share, while floating solar emerges in hydropower reservoir environments.
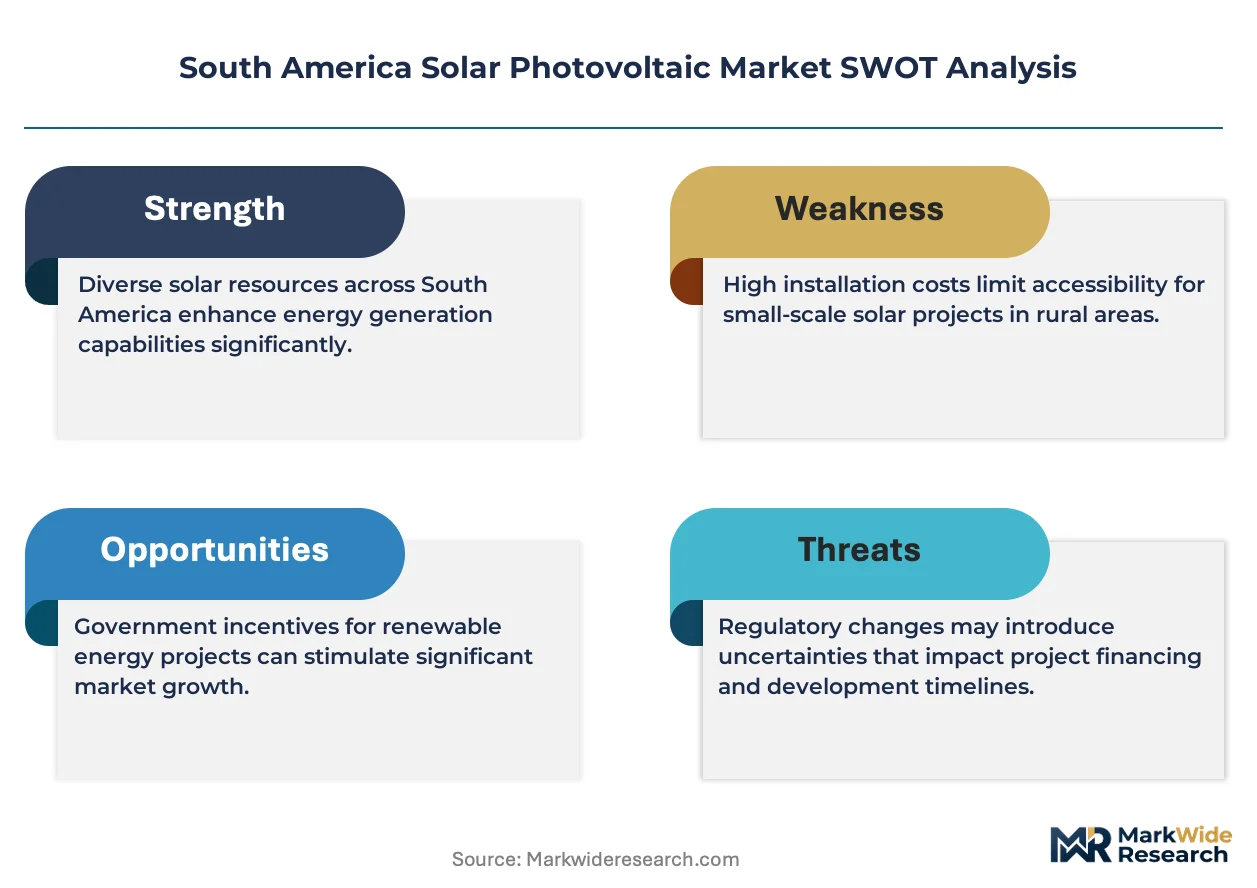
Brazil's ANEEL net metering protocols and Argentina's renewable energy auction terms shape project economics and interconnection timelines. Chile's environmental impact assessment requirements under SEIA influence siting decisions for large-scale developments. Stakeholders must monitor auction schedule volatility, currency hedging costs, and local content rule evolution to preserve returns across the project development cycle.
Market Dynamics
Utility-scale procurement consolidation is reshaping competitive positioning across South America, as integrated developers leverage transmission access rights and long-term power purchase agreements to lock out modular competitors from Brazil's northeast corridor.
Growth Catalysts
- ANEEL Net Metering Framework:Brazil's distributed generation regulations enable residential and commercial self-consumption with simplified interconnection, accelerating rooftop deployment in high-irradiance states.
- Corporate PPA Structuring:Mining and data center offtakers in Chile and Peru are signing direct contracts with solar developers, bypassing regulated utility tariffs and creating stable revenue baselines for project finance.
- Bifacial Module Performance:Dual-side energy capture technology delivers 8-12% yield gains in the Atacama Desert's high-albedo terrain, improving project returns without expanding land footprints.
Market Restraints
- Polysilicon Supply Concentration:Raw material sourcing depends on a narrow supplier base concentrated in specific Asian manufacturing clusters, exposing developers to input cost volatility and logistics bottlenecks.
- Local Content Thresholds:Brazil's ANEEL mandates for domestic equipment procurement extend project development timelines and limit module supplier selection for auction-qualified developments.
- Grid Interconnection Queues:Transmission access requests in Argentina's wholesale electricity market face multi-year approval delays, freezing project execution schedules regardless of permit status.
Strategic Opportunities
- Floating Solar Deployment:Hydropower reservoir environments in Brazil and Colombia offer combined generation potential with reduced land use conflicts and enhanced module cooling efficiency.
- Agrivoltaics Integration:Dual land-use models pairing ground-mounted arrays with cattle grazing or shade-tolerant crops are unlocking previously excluded rural properties in Paraguay's Chaco region.
- Green Hydrogen Offtake:Chile's national hydrogen strategy and Peru's emerging electrolyzer pipeline are creating dedicated demand centers for dedicated solar supply contracts with 24/7 operation requirements.
Industry Challenges
- Grid Code Compliance Expertise:Brazil's ONS requirements for inverter fault-ride-through capabilities and reactive power control demand specialized engineering talent scarce in regional labor markets.
- Currency Hedging Complexity:Dollar-denominated equipment procurement against local-currency power sales requires sophisticated financial structuring that exceeds capabilities of mid-scale developers.
- Environmental Licensing Delays:Chile's SEIA assessment timelines for large-scale projects in protected areas extend pre-construction phases by 18-24 months, compressing returns on development capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Solar Photovoltaic Market |
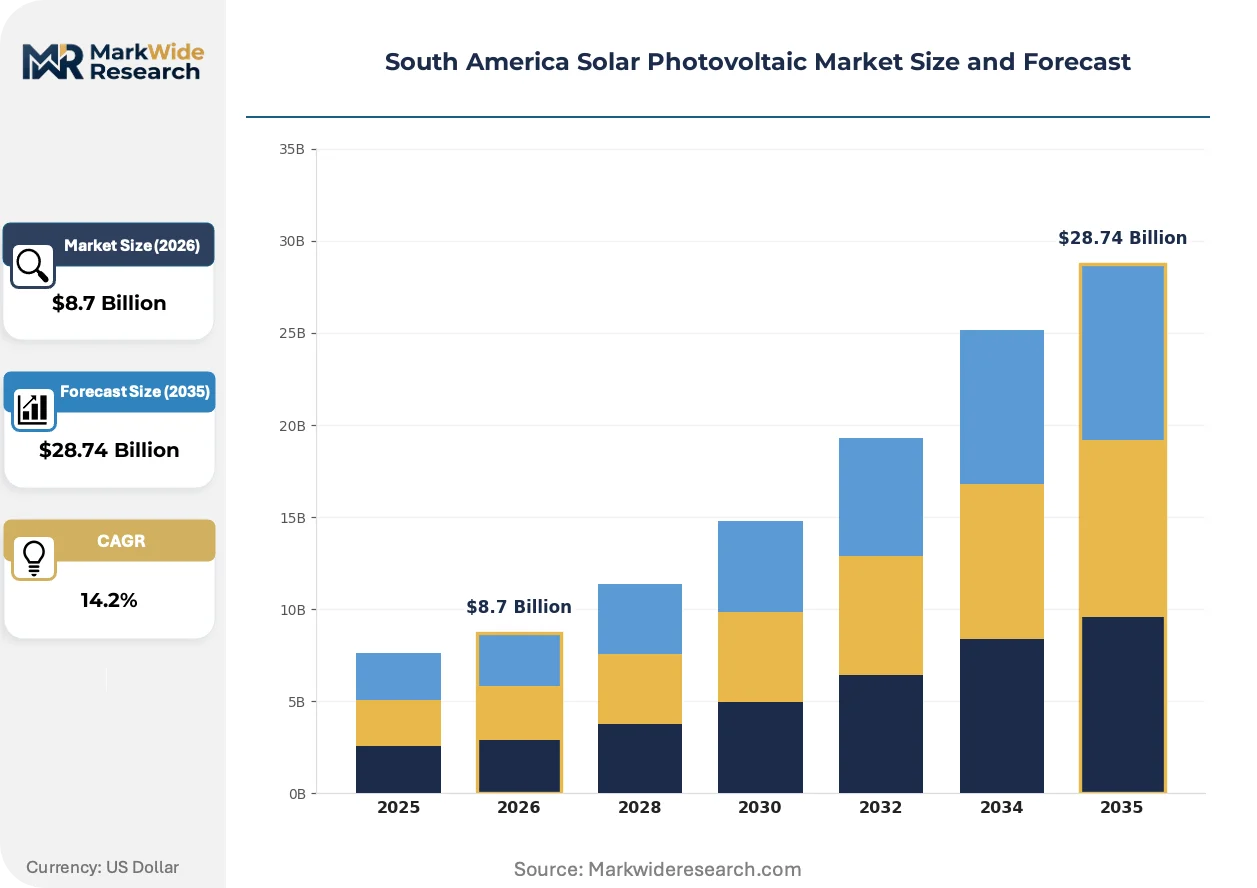
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin Film, Bifacial End User: Residential, Commercial, Industrial, Utility Installation Type: Ground-mounted, Rooftop, Building-integrated, Floating Technology: Grid-tied, Off-grid, Hybrid, Concentrated Solar Power |
| Companies Covered | ENGIE Brasil Energia S.A., Enel Américas, Enel Green Power S.p.A., Atlas Renewable Energy, CEMIG, Iberdrola S.A., Neoenergia S.A., Invenergy LLC, AES Andes S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Solar Photovoltaic Market Evolving Landscape
Technology convergence and procurement model evolution are compressing development cycles across South America's solar landscape. Module efficiency gains, regulatory digitization, and corporate buyer sophistication are collectively raising performance thresholds for competitive participation.
Bifacial photovoltaic modules with tracking systems are converging with high-albedo ground preparation techniques to maximize energy yield per hectare. Mining operators in Chile's Atacama and Peru's southern coast are deploying these configurations for 24/7 desalination and crushing operations. The technology pairing is compressing levelized cost thresholds and displacing diesel generation in remote extraction sites previously deemed uneconomic for solar.
Brazil's ANEEL has digitized distributed generation registration through its Sistema de Informações de Geração Distribuída portal, collapsing interconnection approval timelines from months to weeks. The regulatory streamlining eliminates paper-based documentation and enables real-time monitoring of cumulative capacity caps by distribution zone. Residential and commercial segments in Minas Gerais and São Paulo are responding with accelerated system deployment ahead of tariff schedule revisions.
Corporate offtakers are consolidating procurement through aggregated power purchase agreements that bundle multiple facilities under single contractual frameworks. Data center and industrial manufacturing buyers in Brazil's northeast are displacing bilateral utility negotiations with multi-site solar contracts that transfer development risk to specialized IPPs. The model is most visible in Ceará and Pernambuco, where land availability and irradiance density support clustered project development serving single anchor tenants.
South America Solar Photovoltaic Market Segmentation
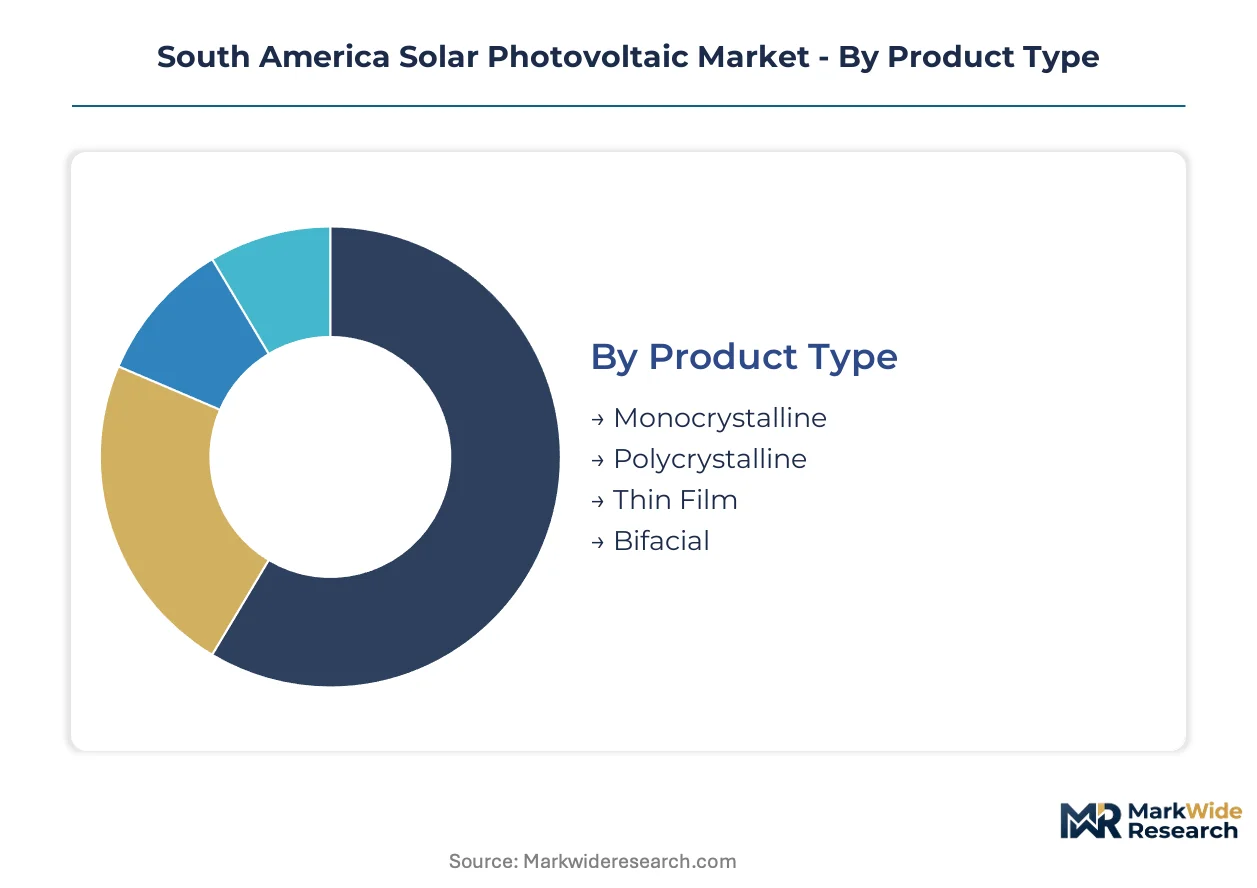
Solar photovoltaic deployment across South America fragments across four distinct segmentation axes. Each category reflects divergent capital intensity, regulatory exposure, and customer sophistication that shapes vendor positioning and project returns.
Product Type:
Module selection spans a customization spectrum from standardized commodity silicon to engineered bifacial configurations optimized for specific albedo conditions.
- Monocrystalline:Single-crystal silicon cells deliver conversion efficiencies exceeding 22% under standard test conditions. Brazilian utility-scale developers in Pernambuco and Ceará specify monocrystalline modules for auction-qualified projects where land constraints favor maximum output density.
- Bifacial:Dual-side energy capture technology harvests reflected light from high-albedo ground surfaces. Chilean mining operators in the Atacama Desert deploy bifacial tracking systems to achieve 8-12% yield gains without expanding land footprints.
- Polycrystalline:Multi-crystal silicon construction offers lower unit costs for price-sensitive distributed generation markets.
- Thin Film:Cadmium-telluride and amorphous silicon technologies suit building-integrated applications where weight and flexibility matter.
Most installed capacity flows through Monocrystalline. Expansion is steepest in Bifacial.
End User:
Customer archetypes distribute across a volume-to-margin continuum, from fragmented residential rooftops to concentrated utility procurement with stringent offtake requirements.
- Utility:Large-scale power plants selling into wholesale markets or under long-term power purchase agreements anchor regional capacity additions. Brazil's northeast corridor attracts the largest project pipelines where solar irradiance and transmission access converge.
- Industrial:Mining, data center, and manufacturing offtakers in Chile and Peru sign direct corporate PPAs bypassing regulated utility tariffs. These contracts create stable revenue baselines for project finance and displace diesel generation in remote extraction sites.
- Residential:Net metering frameworks enable self-consumption with simplified interconnection protocols.
- Commercial:Mid-scale rooftop and ground-mounted systems serve retail, logistics, and office facilities.
Utility-scale procurement commands the dominant value pool. Industrial self-consumption is climbing the fastest as corporate buyers consolidate renewable energy strategies.
Installation Type:
Physical deployment configurations reflect site constraints, land economics, and cooling efficiency trade-offs across diverse South American terrains.
- Ground-mounted:Fixed-tilt and tracking systems on dedicated land parcels sustain the largest capacity share. Paraguay's Chaco region and Brazil's semi-arid northeast offer expansive flat terrain with minimal land-use conflicts.
- Rooftop:Distributed generation on residential and commercial buildings accelerates through Brazil's ANEEL net metering digitization, which collapsed interconnection timelines from months to weeks.
- Floating:Reservoir-mounted arrays in Brazil and Colombia reduce land competition and enhance module cooling efficiency through water contact.
- Building-integrated:Facade and canopy installations serve aesthetic and dual-purpose functions in urban environments.
Ground-mounted infrastructure carries the majority of megawatt deployment. Floating solar is expanding most quickly as hydropower operators seek complementary generation assets.
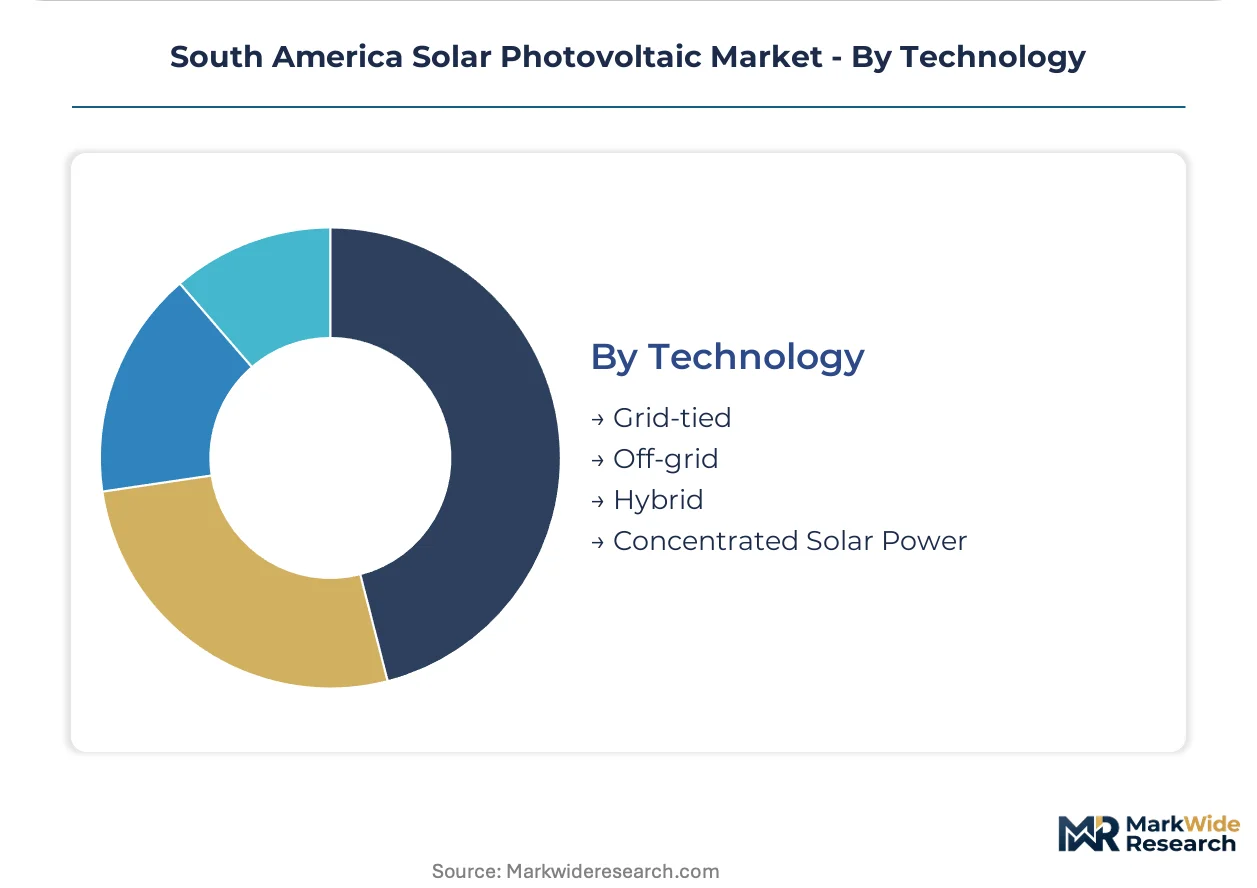
Technology:
System architecture spans a maturity gradient from proven grid-tied configurations to emerging hybrid and concentrated designs with specialized applications.
- Grid-tied:Direct connection to distribution or transmission networks without storage dominates utility-scale and commercial installations. Brazil's ONS grid codes for inverter fault-ride-through and reactive power control shape equipment specification.
- Hybrid:Solar-plus-storage configurations pair photovoltaic arrays with battery systems to enable dispatchable output. Chile's green hydrogen strategy and Peru's emerging electrolyzer pipeline are creating dedicated demand centers for 24/7 solar supply contracts.
- Off-grid:Standalone systems serve rural electrification and remote industrial sites beyond network reach.
- Concentrated Solar Power:Thermal collection with molten salt storage occupies a niche role in specific high-direct-normal-irradiance locations.
Grid-tied configurations handle the preponderance of current capacity. Hybrid systems are gaining share fastest as storage economics improve and hydrogen offtake materializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solar photovoltaic deployment in South America traces its commercial roots to Chile's 2008 non-conventional renewable energy law, which established the region's first bankable auction mechanism and attracted early European utility capital.
Brazil
ANEEL's net metering protocols and local content mandates reshape developer strategies across the northeast corridor. Pernambuco and Ceará host the largest project pipelines where irradiance density and transmission access converge. Minas Gerais accelerates distributed generation through digitized interconnection portals.
Chile
Corporate PPAs from mining and data center operators bypass regulated utility tariffs in the Atacama Desert. SEIA environmental assessments extend pre-construction timelines for large-scale developments. Antofagasta and Tarapacá regions attract bifacial tracking deployments for high-albedo yield optimization.
Argentina
Wholesale electricity market reforms and renewable energy auctions create procurement channels despite macroeconomic volatility. Grid interconnection queues in Buenos Aires province freeze execution schedules regardless of permit status. Mendoza's high irradiance zones remain underdeveloped due to transmission constraints.
Peru
Electrolyzer pipeline development under emerging green hydrogen strategies generates dedicated solar demand centers. Southern coastal mining operations sign direct supply contracts for 24/7 desalination and crushing energy. Arequipa and Moquegua anchor the largest corporate offtake concentrations.
Colombia
Floating solar deployment in hydropower reservoirs reduces land competition and enhances module cooling efficiency. The country's national mining and energy planning unit streamlines environmental licensing for complementary generation assets. Antioquia and Valle del Cauca lead pilot installations on existing dam infrastructure.
South America Solar Photovoltaic Market Competitive Landscape
The competitive structure tilts toward integrated utility platforms with transmission access rights and long-term power purchase agreement capabilities. Turnkey engineering-procurement-construction bundling consolidates buyer choice across auction-qualified developments. Two strategic archetypes dominate: European-headquartered multinationals leveraging balance sheet scale, and regional specialists capturing distributed generation franchises through regulatory relationships. Capacity expansion and strategic partnerships constitute the primary competitive moves, with developers securing land banks and interconnection reservations ahead of auction schedules.
Among European-headquartered platforms, Enel Américas and Enel Green Power S.p.A. exemplify the integrated development archetype spanning multiple jurisdictions. Iberdrola S.A. occupies a comparable position within the Spain-origin utility tier. Neoenergia S.A. represents the Brazil-domiciled specialist model, anchoring market presence through transmission access and regulated market franchises. Atlas Renewable Energy sits within the corporate PPA-focused segment, differentiating via long-term offtake structures with mining and industrial buyers.
| Leading Market Players |
|---|
| ENGIE Brasil Energia S.A. |
| Enel Américas |
| Enel Green Power S.p.A. |
| Atlas Renewable Energy |
| CEMIG |
| Iberdrola S.A. |
| Neoenergia S.A. |
| Invenergy LLC |
| AES Andes S.A. |
| Others |
Value Network & Pricing Analysis
Bifacial module manufacturing scale-up across Chinese and Southeast Asian production hubs simultaneously compresses per-watt production costs and concentrates supply leverage among integrated cell-to-module producers. This technology transition reshapes procurement economics for South American developers who must navigate dollar-denominated equipment purchases against local-currency power sales.
Pricing Analysis
Long-term power purchase agreement contracting dominates developer revenue structures across Brazil's northeast corridor and Chile's mining regions. Price differentiation separates premium-tier bifacial tracking systems with enhanced yield guarantees from standard fixed-tilt monocrystalline configurations and economy-grade polycrystalline modules for distributed generation. Pricing pressure stems from polysilicon input volatility and logistics bottlenecks at Pacific ports. Utility-scale offtakers exhibit lowest price sensitivity due to cost-plus tariff pass-through mechanisms, while residential rooftop segments in Minas Gerais and São Paulo demonstrate highest elasticity to upfront system costs.
Supply Chain Analysis
Polysilicon feedstock draws from Chinese, Malaysian, and German chemical processing facilities before cell fabrication concentrates in Vietnam, Thailand, and mainland China. Wafer slicing and module assembly hinge on high-purity silicon ingots, silver metallization paste, and ethylene-vinyl acetate encapsulant supply. Single-source vulnerability runs through polysilicon purification capacity controlled by a narrow producer base. Distribution runs through regional EPC contractors who bundle engineering, procurement, and construction services for auction-qualified developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in bifacial module deployment and corporate PPA structuring as technology premiums capture value from mining and data center offtakers seeking 24/7 renewable supply.
For Market Incumbents: Cement transmission access rights in Brazil's Pernambuco and Ceará corridors through early interconnection queue positioning and land bank accumulation. Defend against modular competitors by securing long-term power purchase agreements with anchor tenants before auction schedule volatility disrupts project finance timelines. Prioritize backward integration into module supply through strategic partnerships with Southeast Asian cell manufacturers to hedge currency exposure on dollar-denominated equipment procurement. For New Entrants and Emerging Players: The premium-to-economy price gap in distributed generation systems creates entry opportunity for specialized installers targeting residential and commercial rooftop segments underserved by utility-scale incumbents. White-space targets include agrivoltaic deployments in Paraguay's Chaco region and floating solar pilot installations on Colombian hydropower reservoirs. Go-to-market positioning should emphasize rapid interconnection completion through Brazil's digitized ANEEL registration portal. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale developers holding permitted project pipelines without secured offtake contracts. Long-term viability across the analysis window favors platforms with demonstrated corporate PPA execution capability and transmission interconnection relationships. The signal to watch is auction schedule acceleration from Brazil's ANEEL and Argentina's wholesale electricity market reforms as inflection indicators for development capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Corporate PPA Aggregation | Bundles multiple facilities under single contractual frameworks serving data center and mining offtakers in Chile's Atacama. |
| Bifacial Module Procurement | Captures 8-12% yield gains in high-albedo terrain without expanding land footprints for utility-scale developers. |
| Transmission Access Securing | Locks interconnection rights in Brazil's northeast corridor where irradiance density and grid capacity converge. |
| Floating Solar Deployment | Reduces land competition and enhances module cooling efficiency through water contact in Colombian reservoirs. |
| Green Hydrogen Offtake Structuring | Creates dedicated demand centers for 24/7 solar supply contracts under Chile's national hydrogen strategy. |
Research Methodology
Bottom-up utility and industrial offtake modeling reconciled against top-down module shipment tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators combine with secondary validation from ANEEL auction databases, SEIA environmental filings, and corporate PPA registries. Customs data on module imports by country of origin and interconnection queue filings with Brazil's ONS provide supply-side triangulation against demand projections.
Input-output matrices map capacity additions by technology type, project scale tier, and regulatory framework across the projection horizon. Segmentation modeling spans module efficiency category, end-user archetype, installation configuration, and grid interconnection architecture. CAGRs derive from installed capacity buildout trajectories, capacity factor assumptions by region, and tariff evolution under net metering and auction mechanisms. Forecast inputs incorporate polysilicon price indices, currency hedging cost structures, and environmental licensing timeline distributions.
Caveats apply where polysilicon supply disruptions, ANEEL local content rule revisions, or Argentine macroeconomic volatility could materially shift the outlook. Forecasts reflect assumptions on auction schedule regularity, transmission expansion pacing, and corporate offtake appetite for unbundled renewable supply. A small set of triggers—currency hedging cost spikes, grid code compliance delays, and environmental licensing backlogs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Saudi Arabia Solar Energy Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Egypt Solar Energy Market