
 Solar Microinverter and Power Optimizer Market | 2026-2036
Solar Microinverter and Power Optimizer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Microinverter and Power Optimizer Market Analysis
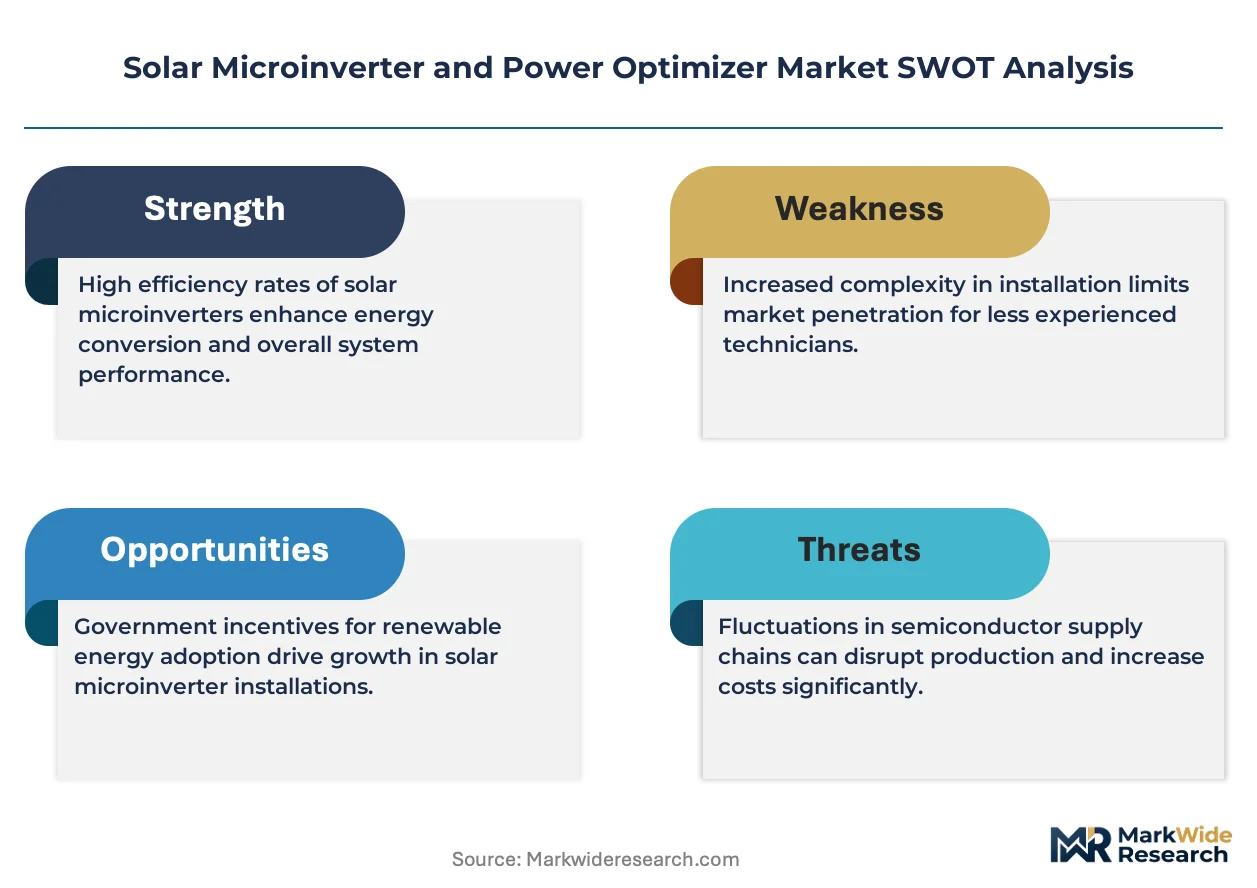
Third-party leasing and power-purchase agreement structures is reconfiguring how residential and commercial buyers access module-level power electronics, lowering upfront capital barriers for smaller installers. Enphase Energy leverages its integrated ecosystem of microinverters and battery storage to dominate the North American residential channel. SolarEdge Technologies anchors the commercial and utility-scale segments through its power optimizer architecture and in-house production of key semiconductor components. SMA Solar Technology competes across European markets with grid-tied inverter platforms that accommodate both optimizer and string configurations.
Solar microinverters and power optimizers are semiconductor-based power electronics devices that perform maximum power point tracking at the individual photovoltaic module level, typically operating at conversion efficiencies exceeding 97 percent and enabling granular monitoring of system performance. Their primary purpose is to mitigate mismatch losses from shading, soiling, or manufacturing tolerance variations while improving safety through rapid shutdown compliance. Microinverters and hybrid systems command the highest margin pools in residential applications where installation complexity and monitoring value justify premium positioning. Power optimizers paired with string inverters represent the fastest-growing configuration in utility-scale deployments where balance-of-system cost reduction drives procurement decisions.
The US Federal Energy Regulatory Commission and state-level public utility commissions shape interconnection standards that determine whether module-level power electronics qualify for net metering and grid services compensation. California's Title 24 building standards and the EU Green Deal's renewable energy directives mandate performance monitoring and rapid shutdown capabilities that effectively require power optimizer or microinverter architectures in new construction. Stakeholders must monitor evolving inverter efficiency standards from IEC and IEEE working groups, as these specifications will determine product eligibility across major procurement channels and utility interconnection queues.
Market Dynamics
Module-level power electronics architectures are displacing centralized string inverter configurations as rapid shutdown mandates and shade tolerance requirements harden across major solar markets. Semiconductor integration and gallium nitride adoption compress power conversion losses while tightening supply chains around specialized foundry capacity.
Growth Catalysts
- California Title 24 mandates:New residential construction must incorporate solar-ready electrical infrastructure and rapid shutdown capabilities, effectively requiring power optimizer or microinverter installations. This regulatory floor expands addressable market for module-level electronics in the largest US state market.
- Third-party ownership models:Leasing and power-purchase agreement structures reduce upfront capital barriers for residential adopters, accelerating deployment velocity among credit-constrained homeowner segments.
- Gallium nitride semiconductors:Wide-bandgap devices enable higher switching frequencies and reduced thermal management overhead, shrinking unit economics for power conversion electronics.
Market Restraints
- Silicon carbide substrate shortages:Specialized wafer supply concentrates among Japanese and US substrate manufacturers, creating input cost volatility and allocation constraints for high-efficiency inverter designs.
- String inverter residual cost advantage:Centralized architectures retain 15-25% balance-of-system cost edge in unshaded utility-scale deployments, limiting power optimizer penetration in price-sensitive procurement.
- Interconnection queue backlogs:US Federal Energy Regulatory Commission jurisdictional delays extend project commissioning timelines, compressing near-term equipment demand visibility.
Strategic Opportunities
- EU Green Deal renovation wave:Building retrofit mandates across Germany, Spain, and Italy create distributed generation retrofit demand for residential power optimizers paired with existing string inverter infrastructure.
- Agrivoltaic dual-use installations:Agricultural land constraints in Japan and South Korea drive elevated mounting configurations where module-level monitoring and mismatch mitigation prove essential.
- Virtual power plant aggregation:Grid services compensation frameworks in Australia and Texas reward granular inverter control, creating software-layer value capture beyond hardware margins.
Industry Challenges
- IEC 62109 safety certification timelines:Evolving arc-fault detection and isolation requirements extend product validation cycles, delaying revenue recognition for new platform introductions.
- Firmware cybersecurity hardening:IEEE 1547-2018 grid interconnection standards mandate encrypted communication protocols, requiring ongoing engineering investment to maintain compliance.
- Installer certification fragmentation:Jurisdictional licensing requirements vary across US states and Australian territories, constraining labor pool scalability for residential channel expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Microinverter and Power Optimizer Market |
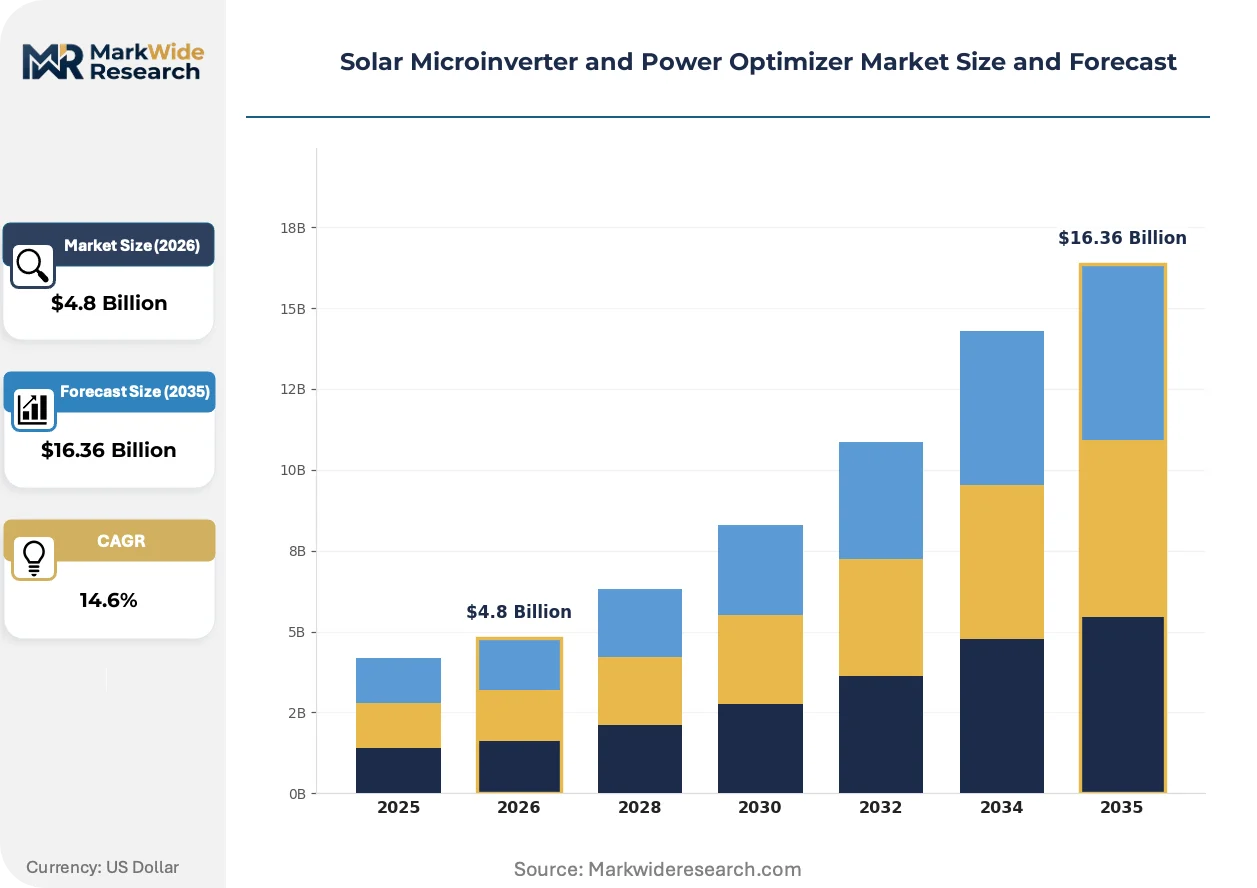
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microinverters, Power Optimizers, Hybrid Systems, Energy Storage Installation Type: Residential, Commercial, Industrial, Utility Scale End User: Homeowners, Businesses, Government, Developers Technology: Grid-Tied, Off-Grid, Battery Integrated, Smart Monitoring |
| Companies Covered | Tigo Energy, SMA Solar Technology, Enphase Energy, Delta Electronics, Sungrow Power Supply, SolarEdge Technologies, Huawei Technologies, Ampt LLC, APsystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Microinverter and Power Optimizer Market Emerging Trajectories
Power semiconductor materials and grid-interaction protocols are converging to redefine conversion efficiency benchmarks and system-level monitoring capabilities. Three developments merit particular attention.
Gallium nitride high-electron-mobility transistors are migrating from consumer power supplies into solar microinverter designs, enabling switching frequencies above 100 kHz that shrink magnetics and thermal management overhead. Residential installers in California and Australia are specifying GaN-based units for retrofit applications where rooftop space constraints demand maximum energy density. This materials transition compresses bill-of-materials costs while tightening dependency on specialized foundry capacity at TSMC and GlobalFoundries.
The EU F-Gas Regulation phase-down is accelerating refrigerant transition in hybrid inverter-heat pump combinations, forcing manufacturers to redesign thermal management for propane and CO2 working fluids. Industrial consequence includes extended qualification timelines and recertification costs for integrated storage systems targeting European residential markets. German and Dutch distributors are prioritizing inventory positions with manufacturers holding updated CE conformity documentation.
Installer procurement patterns are fragmenting across direct OEM relationships, wholesale electrical distributors, and emerging digital procurement platforms. Smaller residential contractors in Texas and Florida are bypassing traditional distribution markups through manufacturer-direct volume commitments, compressing channel margins and forcing distributor consolidation. This disintermediation pressure concentrates in states with high distributed generation penetration where installer density supports direct fulfillment economics.
Solar Microinverter and Power Optimizer Market Segmentation
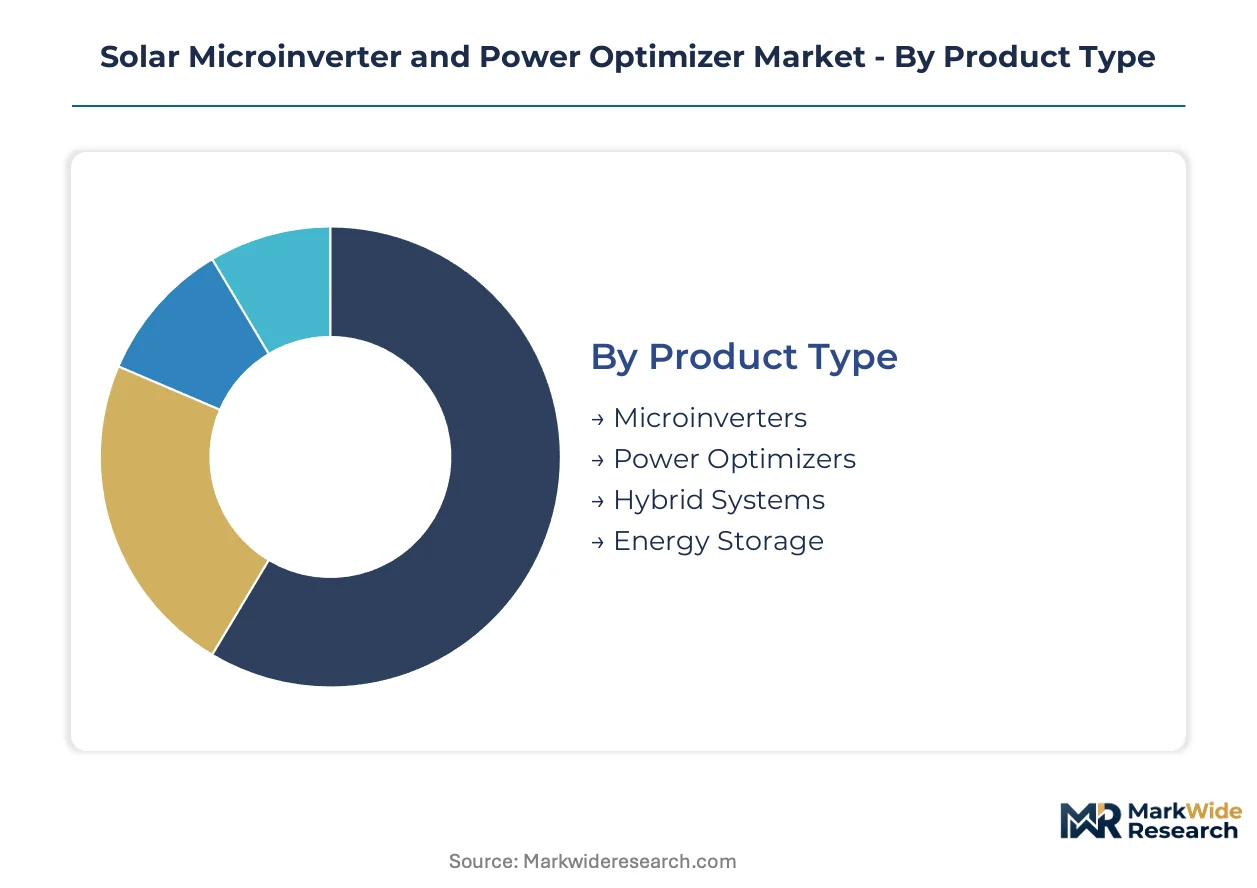
Module-level power electronics vendors configure product portfolios across four distinct segmentation axes. Each axis carries different margin profiles, replacement cycles, and regulatory exposure that determine capital allocation and R&D prioritization.
Product Type:
Microinverters turn inventory fastest in residential retrofit channels where rapid shutdown compliance deadlines compress procurement windows, while energy storage attachments extend sales cycles through permitting complexity.
- Microinverters:These semiconductor-based units perform DC-to-AC conversion at the individual photovoltaic module level, operating at conversion efficiencies exceeding 97 percent. Demand concentrates in California and Australia where Title 24 and state-level safety mandates require module-level rapid shutdown capabilities. Enphase Energy's integrated ecosystem anchors this segment through installer certification programs and direct-to-contractor fulfillment.
- Power Optimizers:These devices perform maximum power point tracking at the module level while feeding DC power to a centralized string inverter. Procurement concentrates in utility-scale deployments across Texas and Florida where balance-of-system cost reduction drives procurement decisions and shading tolerance provides incremental energy yield.
- Hybrid Systems:Combined microinverter-battery architectures with integrated energy management.
- Energy Storage:Battery attachment sales extending module-level electronics into dispatchable capacity.
Power optimizers anchor the volume base in utility procurement while microinverters gain share at the steepest rate through residential channel expansion.
Installation Type:
Cost tiers separate residential premiums from utility-scale procurement discipline, with commercial installations occupying a contested middle ground where financing structures matter more than hardware specifications.
- Residential:Rooftop deployments under 20kW capacity where third-party ownership models reduce upfront capital barriers. California's Title 24 mandates and Australian state-level solar feed-in tariffs concentrate demand in these geographies.
- Commercial:Behind-the-meter installations for businesses seeking demand charge reduction.
- Industrial:Large on-site generation for manufacturing facilities with high load factors.
- Utility Scale:Ground-mounted arrays where power optimizer penetration faces string inverter cost competition.
Residential installations command the highest margin pool while utility-scale deployments expand most quickly through renewable portfolio standard procurement.
End User:
Customer sophistication determines service intensity, with developers requiring engineering support and homeowners prioritizing monitoring interfaces and warranty terms.
- Homeowners:Distributed generation adopters in Germany, Australia, and the United States seeking module-level monitoring and shade tolerance. Leasing and power-purchase agreement structures dominate in credit-constrained segments.
- Businesses:Commercial entities pursuing electricity cost reduction and sustainability commitments.
- Government:Public sector procurement with prevailing wage and domestic content requirements.
- Developers:Project finance sponsors optimizing for construction timeline and interconnection certainty.
Businesses anchor current revenue concentration while developers drive the steepest expansion trajectory through utility-scale pipeline buildout.
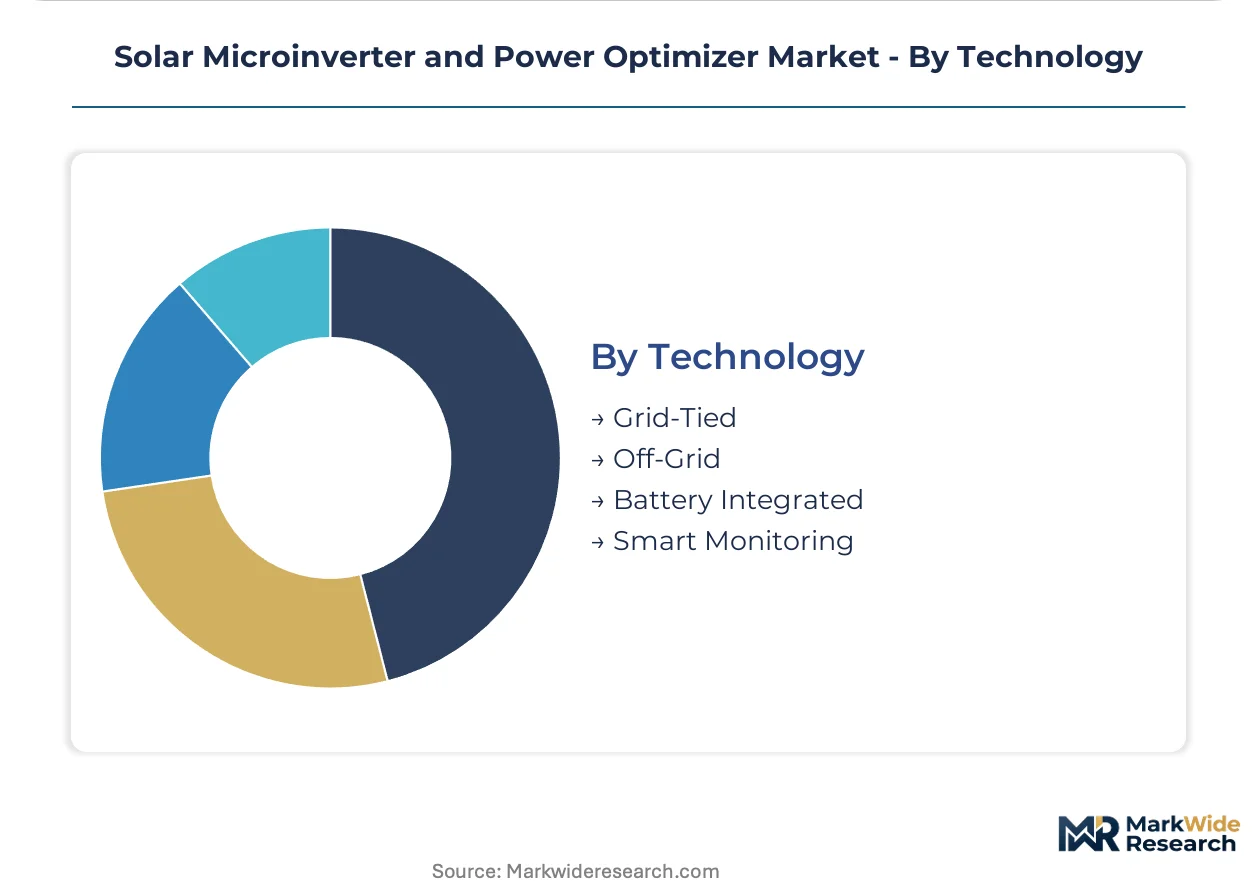
Technology:
Application context determines architecture selection, with grid-tied dominance giving way to battery-integrated growth as time-of-use rate structures spread.
- Grid-Tied:Synchronous inverter operation with IEEE 1547-2018 compliance for voltage and frequency ride-through. Concentrates in markets with net metering availability and stable interconnection standards.
- Off-Grid:Standalone systems with battery charging management for remote or unreliable grid contexts.
- Battery Integrated:Hybrid inverters with DC-coupled storage attachment capability.
- Smart Monitoring:Granular module-level telemetry with cloud-based performance analytics and predictive maintenance alerts.
Grid-tied configurations anchor installed base volume while battery integrated systems climb the fastest through solar-plus-storage procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence for power semiconductors and specialized magnetics tilts procurement geography toward countries with established electronics manufacturing infrastructure and distributed generation policy support.
United States
California's Title 24 building code mandates solar-ready electrical infrastructure and rapid shutdown capabilities in new residential construction, effectively requiring module-level power electronics installations. FERC interconnection standards and state-level net metering frameworks determine compensation eligibility for systems with granular inverter control. Installer density concentrates in Texas and Florida where third-party ownership models accelerate residential deployment velocity.
Germany
The EU Green Deal's building renovation wave and national solar feed-in tariff structures drive retrofit demand for power optimizers paired with existing string inverter infrastructure. ECHA REACH compliance and CE marking requirements govern semiconductor import certification timelines. Industrial clusters in Bavaria and North Rhine-Westphalia host distribution operations serving residential contractors across German-speaking Europe.
Australia
State-level distributed generation incentives and virtual power plant aggregation frameworks reward module-level monitoring and grid services participation. The country's national energy regulator sets interconnection standards that favor rapid shutdown-compliant architectures. Queensland and New South Wales installer networks specify microinverter systems for residential retrofits where rooftop space constraints demand maximum energy yield per module.
Japan
Agrivoltaic dual-use installation mandates and agricultural land constraints drive elevated mounting configurations where shade tolerance proves essential. METI grid codes and feed-in tariff structures determine compensation for systems with module-level electronics. Industrial operations in the Kanto and Kansai regions concentrate procurement for residential and commercial channel fulfillment.
China
Domestic inverter manufacturing capacity and gallium nitride semiconductor foundry investments compress unit economics for power conversion electronics. MIIT efficiency standards and GB certification requirements shape product eligibility for grid-connected deployment. Yangtze River Delta and Pearl River Delta manufacturing clusters supply both domestic distributed generation projects and export markets.
Solar Microinverter and Power Optimizer Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers with captive semiconductor sourcing and installer certification ecosystems. Tiered competitive positioning separates premium ecosystem vendors from optimizer specialists and scale-driven string inverter manufacturers. Three archetypes dominate: integrated residential platform providers, commercial-utility optimizer specialists, and diversified power electronics conglomerates. Capacity expansion in wide-bandgap semiconductor foundries and direct-to-installer fulfillment models represent the dominant competitive moves reshaping channel economics.
Within the integrated platform tier, Enphase Energy and SolarEdge Technologies exemplify divergent architectural approaches to module-level power electronics. Enphase anchors residential channel positioning through microinverter-centric ecosystems, while SolarEdge occupies optimizer-string inverter hybrid configurations. SMA Solar Technology represents European-scale diversification across optimizer-compatible and traditional string platforms. Chinese power electronics specialists including Sungrow Power Supply and Huawei Technologies sit within scale-driven manufacturing archetypes serving utility procurement channels.
| Leading Market Players |
|---|
| Tigo Energy |
| SMA Solar Technology |
| Enphase Energy |
| Delta Electronics |
| Sungrow Power Supply |
| SolarEdge Technologies |
| Huawei Technologies |
| Ampt LLC |
| APsystems |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster anchors global power semiconductor capacity, and its foundry allocation dynamics directly compress downstream pricing power for microinverter OEMs competing on conversion efficiency metrics. California's Title 24 compliance deadlines and Australian rapid shutdown mandates create procurement urgency that partially offsets this supplier leverage.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IEC 62109 certification grade and volume scale commitments above ten thousand units. Cost compression in the standard tier is intensifying because gallium nitride foundry capacity constraints limit supply elasticity. Residential installers in credit-constrained segments exhibit highest price sensitivity, while utility-scale developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Gallium nitride wafers and silicon carbide substrates feed from specialized foundries in Taiwan, Japan, and the United States. Raw material dependencies center on high-purity silicon substrates, rare-earth magnetics for inductors, and epoxy molding compounds for thermal management. Single-source vulnerability concentrates in TSMC's advanced node capacity for GaN HEMT production. Distribution runs through direct OEM relationships, wholesale electrical distributors, and emerging digital procurement platforms serving residential contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward utility-scale developers and aggregator-backed residential installers as procurement concentrates among fewer channel gatekeepers with volume commitment leverage.
For Market Incumbents: Pre-empt optimizer-string hybrid erosion by deepening backward integration into gallium nitride foundry partnerships and securing captive wafer supply from Japanese substrate manufacturers. Channel control through installer certification ecosystems defends margin position against direct-to-contractor disintermediation. R&D investment in firmware cybersecurity hardening addresses IEEE 1547-2018 compliance as a competitive moat. For New Entrants and Emerging Players: Mid-market commercial buildings in Germany and Spain represent the most penetrable entry point where EU Green Deal retrofit mandates outpace incumbent service capacity. Agrivoltaic installations in Japan and South Korea offer specialized mismatch mitigation applications with limited competition. A white-label power optimizer strategy targeting existing string inverter retrofit channels minimizes certification timeline exposure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated platform providers with captive semiconductor sourcing and software-layer grid services capabilities. Long-term viability hinges on virtual power plant aggregation revenue streams beyond hardware margins. The signal to watch is FERC interconnection queue reform accelerating project commissioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Partnership | TSMC and GlobalFoundries capacity allocation secures switching frequency advantages for residential microinverters. |
| Installer Certification Ecosystem Expansion | California and Texas contractor density supports direct fulfillment economics bypassing distributor markups. |
| Virtual Power Plant Software Platform | Australian and Texas grid services compensation frameworks reward granular inverter control beyond hardware sales. |
| EU Green Deal Retrofit Channel Development | German and Spanish building renovation mandates create power optimizer demand for existing string inverter infrastructure. |
| Cybersecurity Compliance Investment | IEEE 1547-2018 encrypted communication protocols extend product validation cycles for new platform introductions. |
Methodological Framework
Cross-validation between primary interviews with EPC contractors, utility planning officers, residential installer networks, and semiconductor procurement leads anchors the qualitative findings. Secondary validation draws from FERC interconnection filings, EIA project development databases, IEC standard working group disclosures, and IEA distributed generation deployment tracking. Bottom-up unit shipment modeling and top-down addressable market sizing triangulate volume estimates across the analysis window.
Calibration against historical capacity expansion announcements and foundry utilization disclosures refines the projection framework. Segmentation dimensions include product architecture, installation scale tier, end-user sophistication, and regional regulatory cluster. CAGRs derive from slope-intercept modeling of adoption curve inflection points, with gallium nitride cost reduction trajectories and interconnection queue clearance rates as key forecast inputs.
Practitioners should monitor silicon carbide substrate allocation constraints and FERC Order 2023 implementation timelines for early signals of supply-side compression or demand acceleration. Forecasts reflect assumptions about wide-bandgap semiconductor yield improvements and state-level net metering stability. Cross-checking against IEA distributed generation outlook revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Portugal Distributed Solar Energy Market