
 Global Solar Microinverter Market | 2026-2036
Global Solar Microinverter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Microinverter Market Intelligence
Demand for solar microinverters is rotating from large-scale commercial projects toward individual residential installations as homeowner-driven distributed generation gains momentum. Enphase dominates the module-level power electronics space with its established channel partnerships. SolarEdge competes through its power optimizer and inverter systems, offering a differentiated architecture. Hoymiles leverages its strength in high-density microinverter designs for multi-panel arrays.
A solar microinverter is a plug-and-play device that converts direct current (DC) from a single solar panel into alternating current (AC). Each unit incorporates Maximum Power Point Tracking (MPPT) technology to optimize the energy harvest from individual panels, unlike traditional string inverters. Single-phase microinverters command the largest share, aligning with their primary use in the residential application segment. Within technology, integrated digital monitoring capabilities are becoming a standard feature, allowing homeowners to track performance via wireless communication.
Safety and grid-interconnection standards, such as the US National Electrical Code (NEC) rapid shutdown requirements, mandate module-level control. In Europe, CE marking and RoHS compliance govern product safety and materials, while China's dual carbon goals incentivize distributed solar development. Future success for manufacturers depends on navigating evolving grid-support functionality requirements and managing semiconductor supply chain volatility.
Market Dynamics
The fundamental shift from centralized string inverters to module-level power electronics defines the market's structure. This transition is driven by a convergence of stringent electrical safety regulations, such as rapid shutdown requirements, and residential consumer demand for optimized energy generation.
Growth Catalysts
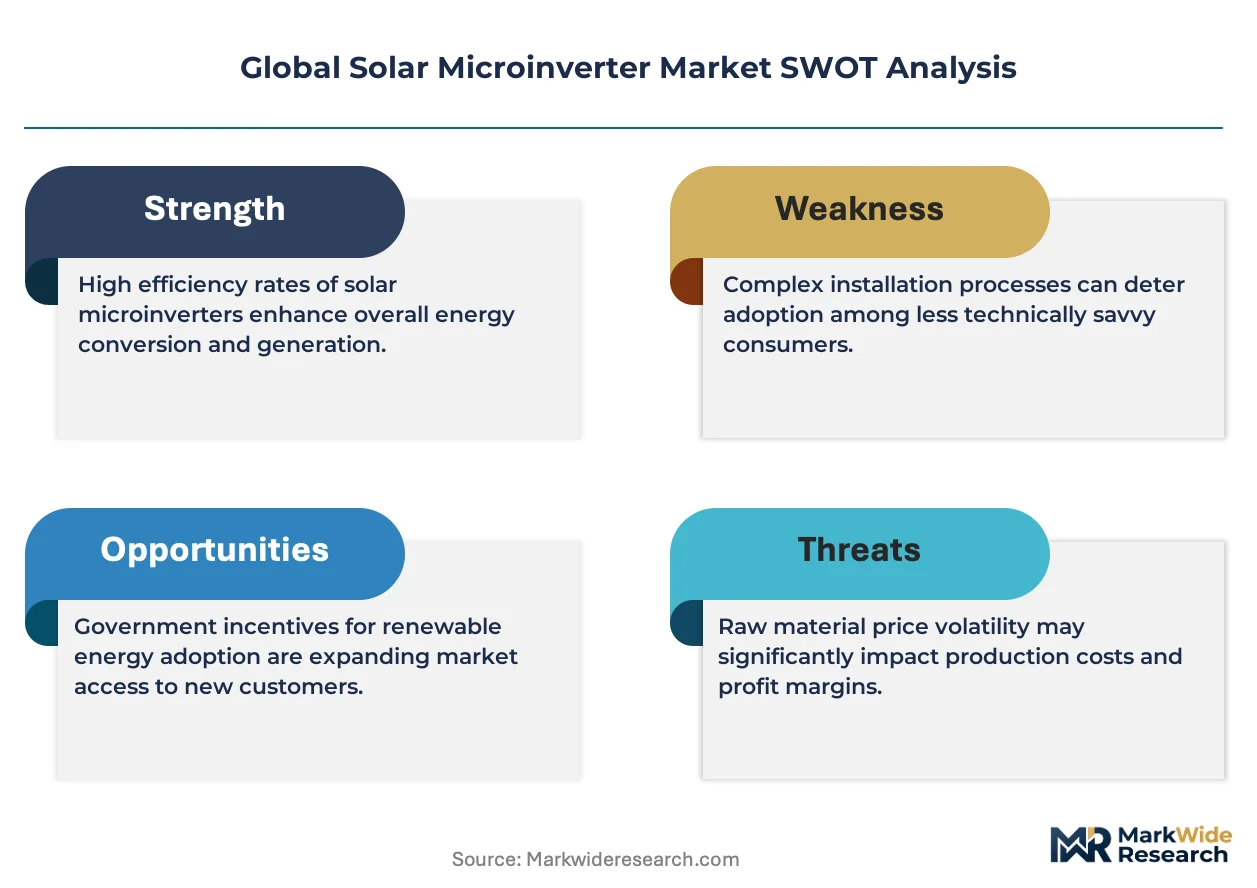
- Regulatory Safety Mandates:The US National Electrical Code's (NEC) rapid shutdown rules and equivalent safety standards in other regions compel the use of module-level control, directly benefiting microinverter adoption for firefighter and homeowner safety.
- Government Incentives:Tax credits under the US Inflation Reduction Act (IRA) and subsidies in European countries like Germany are lowering the financial barrier for homeowners, accelerating residential solar installations that favor microinverter architectures.
- Energy Harvest Optimization:The integration of Maximum Power Point Tracking (MPPT) at the individual panel level maximizes energy output, especially on complex roofs with shading issues, offering a clear performance advantage over traditional systems.
Market Restraints
- Semiconductor Supply Volatility:The reliance on a concentrated supply chain for essential power semiconductors and microcontrollers exposes manufacturers to price fluctuations and potential shortages, impacting production schedules and cost stability.
- Higher Initial Capital Outlay:A higher per-watt cost compared to string inverters remains a significant barrier, particularly for large-scale residential projects or in cost-sensitive developing markets where upfront expense is the primary decision factor.
- Increased System Complexity:A distributed architecture with numerous electronic devices on a rooftop increases the number of potential failure points and can complicate installation and troubleshooting compared to a single, ground-level string inverter.
Strategic Opportunities
- Advanced Grid-Support Functions:Developing microinverters with integrated software for voltage and frequency ride-through (VFRT) capabilities opens new revenue streams by providing ancillary services to utilities and enhancing grid stability.
- Expansion into Emerging Solar Markets:Targeting high-growth residential solar markets in regions like Southeast Asia, Latin America, and Australia presents a significant opportunity as distributed generation policies and consumer awareness expand.
- Factory-Integrated AC Modules:Collaborating with photovoltaic panel manufacturers to produce AC solar modules with pre-installed microinverters simplifies logistics, reduces installation labor, and provides a streamlined solution for distributors and installers.
Industry Challenges
- Navigating Grid Interconnection Standards:Adhering to a fragmented and evolving landscape of utility-specific interconnection requirements for communication protocols and grid-interactive functions creates significant compliance hurdles and development costs for manufacturers.
- Long-Term Reliability and Warranty:Ensuring microinverter operational lifespans and warranty periods align with the 25-year-plus life of solar panels is a critical engineering and financial challenge, impacting brand reputation and long-term viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Microinverter Market |
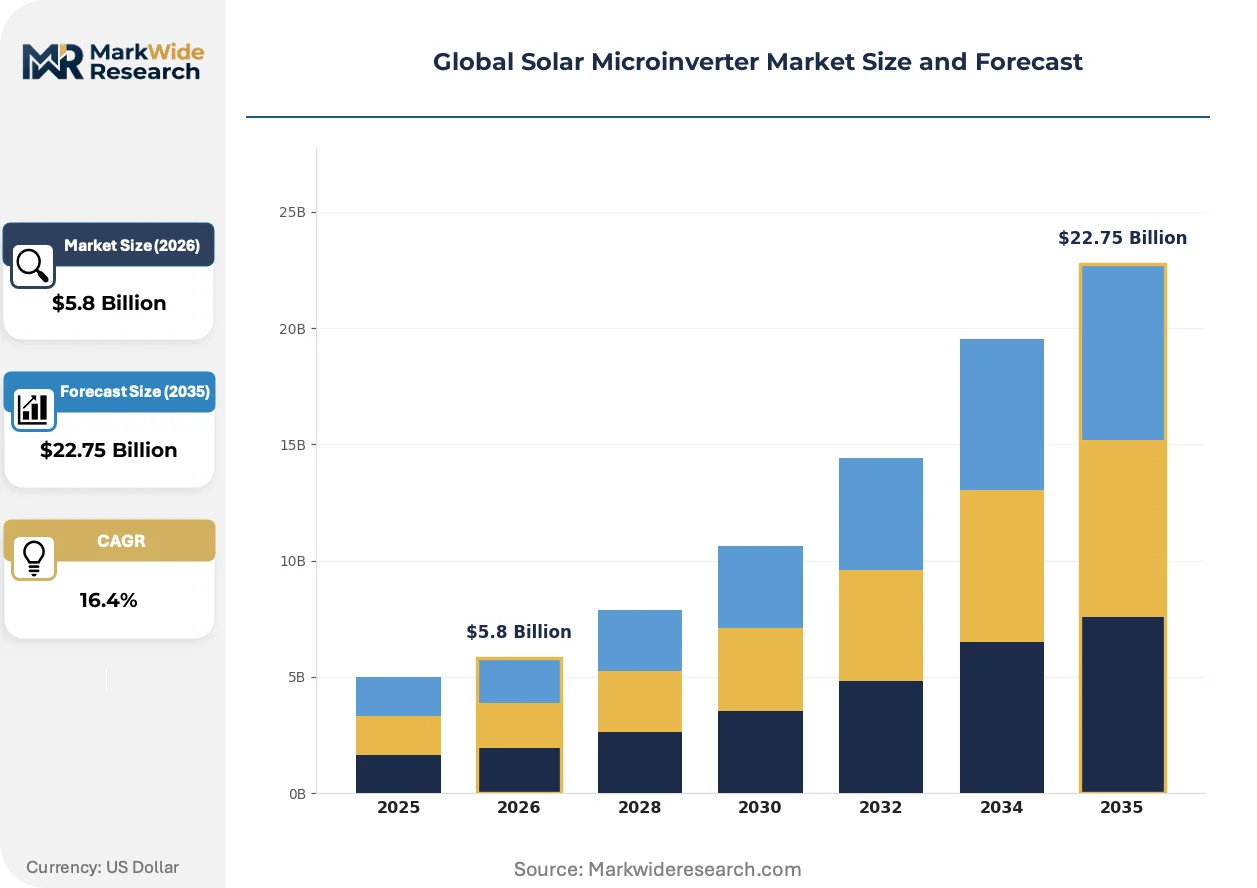
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $22.75 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Hybrid, String, Central Application: Residential, Commercial, Utility-Scale, Agricultural, Off-Grid Technology: MPPT Control, Digital Monitoring, Wireless Communication, Anti-Islanding, Integrated Battery Management End User: Homeowners, Business Owners, Energy Providers, Government Facilities, Non-Profit Organizations |
| Companies Covered | SolarEdge, GoodWe, Enphase, Chilicon, Fronius, Hoymiles, HIITIO, SPARQ, APsystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Microinverter Market Strategic Shifts & Innovations
The evolution of microinverters from simple DC-to-AC converters into intelligent, grid-aware devices is the central theme. This transformation is driven by advancements in semiconductor technology, new regulatory frameworks for distributed energy resources, and changing homeowner expectations for energy management.
Power semiconductor technology is a key area of innovation, with Gallium Nitride (GaN) components enabling new design possibilities. High-end residential and commercial installers are adopting these advanced devices for their superior efficiency and thermal performance. This trend is bifurcating the market into premium, high-power-density units based on wide-bandgap semiconductors and conventional, cost-effective models using traditional silicon components.
Grid-interconnection regulations are becoming more sophisticated, demanding active grid participation from distributed energy resources. Rules like IEEE 1547 in the United States and VDE standards in Germany mandate that microinverters provide grid-support functions like voltage regulation. The residential segment is most affected, as manufacturers must now embed advanced communication and control software into what was once a simple hardware device.
Homeowner buying behavior is shifting from purchasing standalone solar components to acquiring integrated home energy management systems. This disrupts the traditional installer channel, which is increasingly competing with service providers offering bundled packages of solar, battery storage, and EV charging. This integrated approach is most prominent in mature solar markets such as California and Germany, where energy self-sufficiency is a primary motivator.
Global Solar Microinverter Market Segmentation
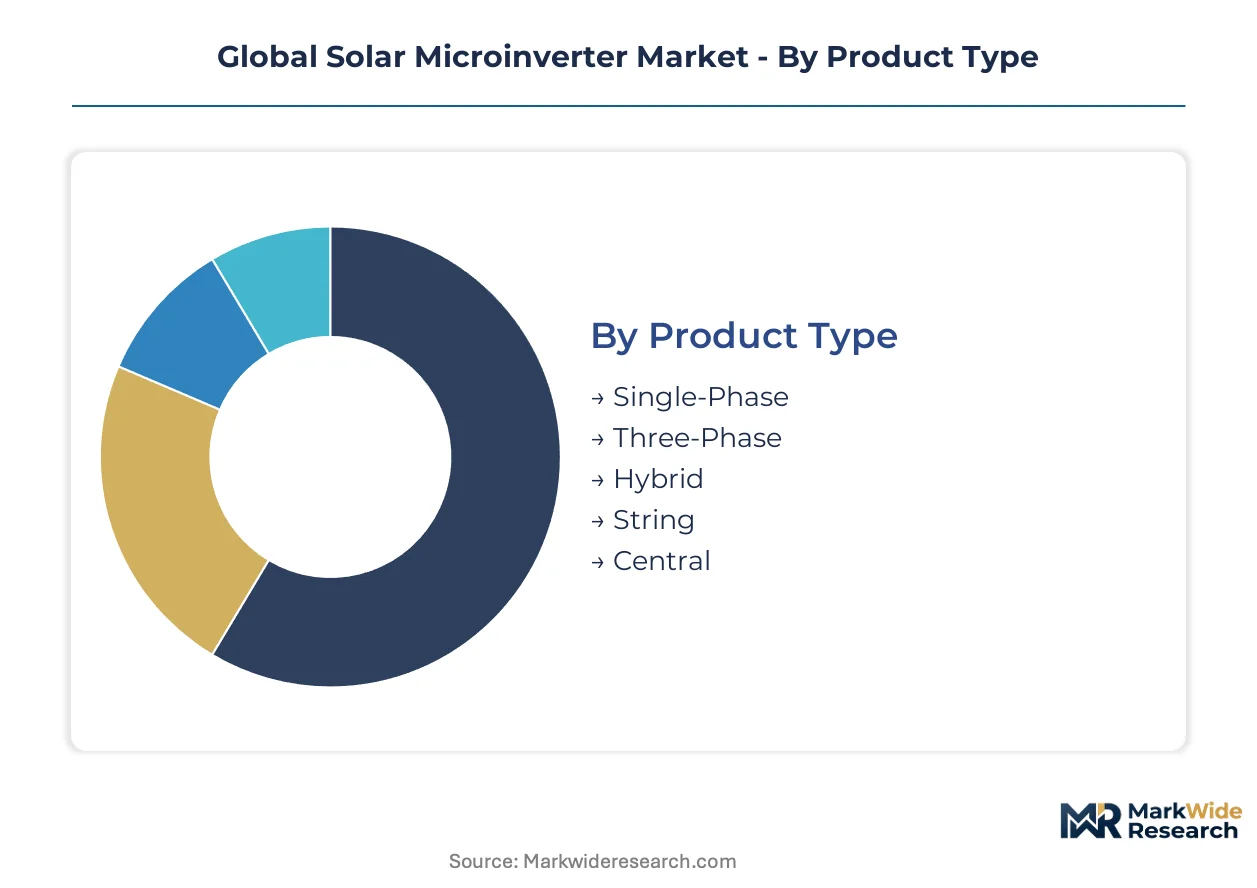
Market segmentation for solar microinverters provides a granular view of demand drivers and technological adoption across diverse applications. Understanding these distinct segments helps manufacturers tailor product development and market strategies effectively. This analysis highlights specific areas of revenue concentration and evolving technological requirements.
Product Type:
Margin pools within the product type segment often concentrate in specialized, high-power-density designs that address complex installation requirements.
- Single-Phase:These microinverters convert DC power from individual solar panels into AC suitable for standard residential electrical systems. Demand is concentrated in the US and Germany, driven by homeowner investments in rooftop solar.
- Three-Phase:Designed for larger commercial installations, these units connect to three-phase electrical grids, handling higher power outputs efficiently. Adoption is accelerating in European commercial buildings, particularly in industrial zones.
- Hybrid:These systems integrate microinverter functionality with battery storage management, offering enhanced energy independence. Homeowners in California increasingly seek these solutions for grid resilience.
- String:Traditional string inverters connect multiple panels in series, converting DC from the entire array at a central point. They remain a cost-effective option for large, unshaded arrays.
- Central:Large-scale central inverters are employed in utility-scale solar farms, handling megawatts of power from vast panel arrays. Their use is limited to very large ground-mount projects.
The dominant share belongs to Single-Phase microinverters, while Three-Phase units are closing the gap fastest.
Application:
Volume concentration within applications heavily skews towards distributed residential power generation, driven by homeowner investment.
- Residential:This segment includes rooftop solar installations on single-family homes, prioritizing energy self-sufficiency and reduced utility bills. The US Inflation Reduction Act significantly boosts installations in this sector.
- Commercial:Encompassing solar systems on businesses, factories, and public buildings, this segment focuses on energy cost reduction and sustainability initiatives. European businesses are rapidly expanding commercial rooftop solar capacity.
- Utility-Scale:Large ground-mounted solar farms generating power for the grid fall into this category, requiring robust and efficient power conversion solutions. These projects often utilize central or string inverters due to scale.
- Agricultural:Solar microinverters power irrigation systems, farm buildings, and remote agricultural equipment, enhancing operational efficiency. Farmers in Australia are increasingly adopting these solutions.
- Off-Grid:Installations in remote areas without grid access rely on microinverters for reliable power generation, often paired with battery storage. Developing regions in Southeast Asia show demand for these systems.
Residential applications hold the largest share, with Commercial installations showing significant expansion.
Technology:
Functional differentiation across technology features dictates value proposition, with core optimization capabilities forming the baseline.
- MPPT Control:Maximum Power Point Tracking optimizes energy harvest from each individual solar panel, crucial for shaded or uneven arrays. This technology is a standard feature in all modern microinverters.
- Digital Monitoring:Integrated wireless communication allows homeowners to track individual panel performance and system health via online platforms or mobile apps. This capability is becoming a standard expectation.
- Wireless Communication:Enables seamless data exchange between microinverters, monitoring systems, and grid operators, supporting advanced grid services. This feature enhances system diagnostics and control.
- Anti-Islanding:Safety protocols ensure microinverters automatically disconnect from the grid during power outages, protecting utility workers. This is a critical safety standard mandated by regulations like IEEE 1547.
- Integrated Battery Management:Microinverters with built-in capabilities to manage and optimize energy flow to and from battery storage systems. This feature is gaining traction in markets focused on energy independence.
MPPT Control remains a foundational technology, while Integrated Battery Management is experiencing accelerated integration.
End User:
Demand drivers from end-users reflect varying scales of energy consumption and investment priorities across different customer types.
- Homeowners:Individuals investing in solar power for their residences to reduce electricity bills and increase energy self-sufficiency. Tax incentives in the US directly target this user group.
- Business Owners:Commercial enterprises seeking to lower operating costs, meet sustainability goals, and enhance their public image through solar adoption. Small and medium-sized businesses show strong interest.
- Energy Providers:Utilities and independent power producers integrating distributed solar generation into their grids for stability and renewable energy mandates. Grid-support functions are critical for these entities.
- Government Facilities:Public sector entities installing solar on municipal buildings, schools, and infrastructure to achieve energy efficiency and environmental targets. China's dual carbon goals incentivize such projects.
- Non-Profit Organizations:Charitable and community groups deploying solar to reduce operational expenses and fund their missions, often through grants or community solar programs. These organizations focus on long-term cost savings.
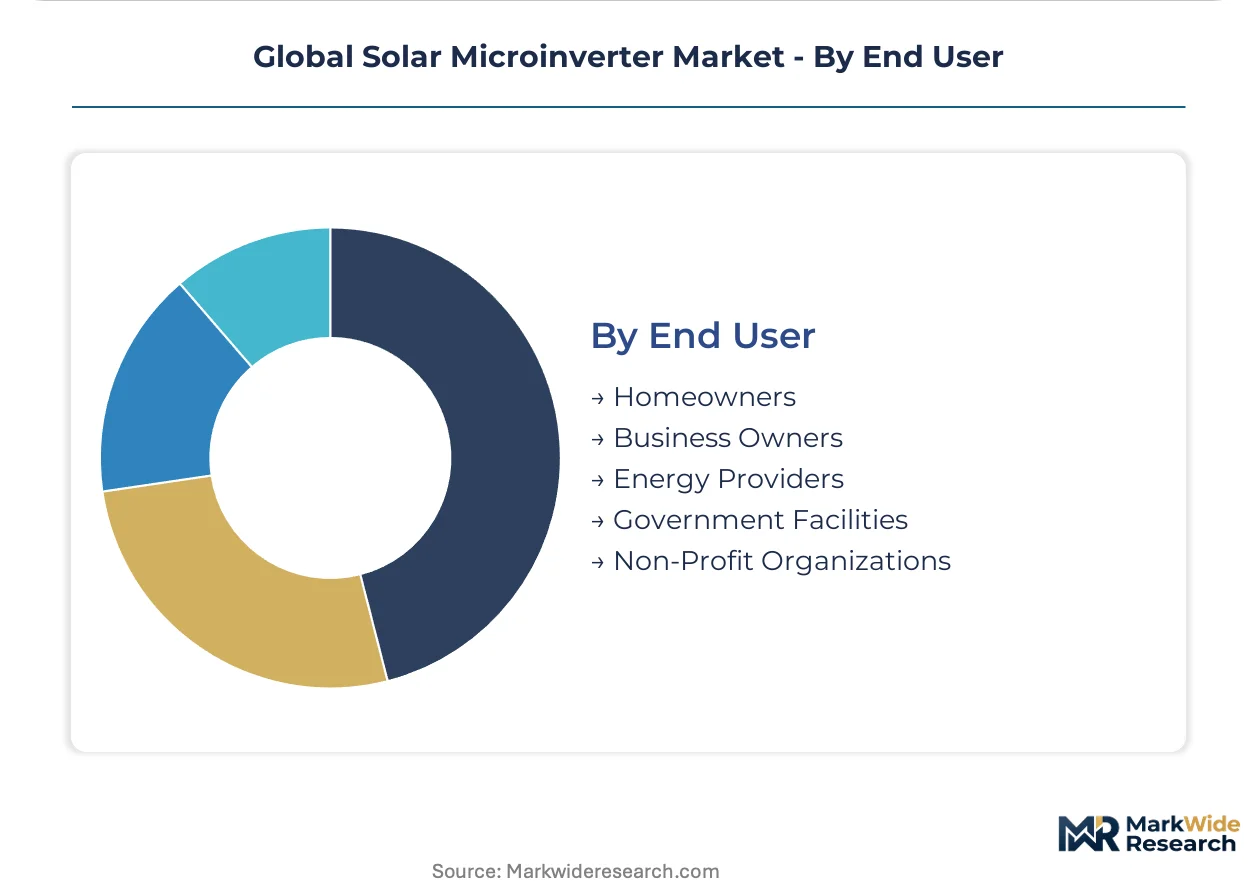
Homeowners represent the primary end-user segment, with Business Owners driving substantial commercial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing prowess supplies solar microinverters to diverse global markets, including Europe and North America. This trade flow supports widespread residential and commercial solar adoption. Demand drivers vary significantly across these key regions.
United States
Homeowner investments in distributed power generation drive significant demand for microinverters in the United States. The US Inflation Reduction Act (IRA) provides substantial tax incentives, accelerating residential installations. California's solar market, particularly in the Bay Area, actively integrates advanced microinverter solutions for grid resilience.
Germany
Germany exhibits strong demand for single-phase microinverters due to rapid rooftop solar expansion. German government subsidies lower financial barriers for homeowners, while VDE standards ensure product safety. Bavaria's solar initiatives, concentrated around Munich, promote widespread adoption of integrated home energy systems.
Australia
Australian homeowners seek microinverters for energy independence and reduced utility bills. State-level solar rebates and favorable grid connection standards support residential and agricultural installations. Queensland's farming regions, particularly near Brisbane, increasingly adopt microinverters for remote agricultural equipment.
China
China's dual carbon goals incentivize distributed solar development, fostering microinverter demand. GB standards ensure product quality and safety for domestic and export markets. The Yangtze River Delta region, including Shanghai, sees significant investment in commercial and residential solar projects.
Netherlands
The Netherlands demonstrates high demand concentration for solar microinverters, particularly in residential rooftop installations. European CE marking ensures product compliance, supported by national incentive schemes for solar adoption. The Randstad urban area, including Amsterdam, drives significant residential microinverter deployment.
Global Solar Microinverter Market Key Industry Players
Player mix skews toward established module-level power electronics specialists and integrated energy solution providers, reflecting the shift towards distributed generation. The market structure exhibits a tiered consolidation, with a few major players holding significant channel partnerships and technological advantages. Three strategic archetypes include dedicated microinverter manufacturers, power optimizer specialists, and integrated home energy management system providers. Companies primarily engage in technology licensing, strategic partnerships, and continuous product development to expand their market reach and address evolving grid requirements.
Specialists in module-level power electronics include Enphase, which represents the established channel partnership archetype, dominating the residential segment with its comprehensive offerings. SolarEdge, known for its differentiated power optimizer and inverter systems, occupies a position as a leading competitor in both residential and commercial applications by focusing on system-level optimization. Hoymiles exemplifies strength in high-density microinverter designs, particularly for multi-panel arrays, anchoring its presence in diverse global markets through innovative product configurations. These companies collectively drive innovation in energy harvest optimization and grid-support functions.
| Leading Market Players |
|---|
| SolarEdge |
| GoodWe |
| Enphase |
| Chilicon |
| Fronius |
| Hoymiles |
| HIITIO |
| SPARQ |
| APsystems |
| Others |
Cost & Logistics Intelligence
CE marking standards in Europe gate component qualification and influence price differentiation across microinverter product lines. These regulations ensure product safety and performance, directly impacting manufacturing costs and market access for suppliers.
Pricing Analysis
The pricing gap between conventional silicon-based microinverters and advanced Gallium Nitride (GaN) models is pronounced in the market. Transactional per-unit pricing dominates the sector, with brand premium and integrated software features driving price differentiation. Pricing softness stems from intense competition among manufacturers for residential market share. Homeowners remain highly price-sensitive, while commercial installers prioritize long-term reliability and advanced features.
Supply Chain Analysis
China anchors global microinverter production, supplying a substantial volume of finished goods and critical components. The supply chain sources power semiconductors and microcontrollers from Taiwan and South Korea. Semiconductor supply volatility represents a significant structural risk, impacting production schedules and material costs. Distribution primarily runs through established solar distributors and direct installer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global solar microinverter market is in an early-cycle expansion phase, driven by accelerating residential solar installations. Homeowner demand for energy independence and optimized generation provides a significant tailwind for continued growth.
For Market Incumbents: Fortify channel partnerships with installers to counter emerging threats from integrated home energy system providers. Invest in advanced grid-support functions, such as voltage and frequency ride-through capabilities, to meet evolving utility requirements. Deepen vertical integration into semiconductor manufacturing to mitigate supply chain volatility. Enphase and SolarEdge must protect their established market positions.
For New Entrants and Emerging Players: Differentiate on high-power-density designs for complex multi-panel arrays, targeting niche residential and commercial segments. Focus go-to-market strategies on emerging solar markets in Southeast Asia, where distributed generation policies are expanding. Offer factory-integrated AC modules in collaboration with panel manufacturers, simplifying logistics for installers. The Australian agricultural sector presents a penetrable segment for specialized solutions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the microinverter manufacturing segment due to investments in advanced wide-bandgap semiconductor production. Long-term viability extends over a 5-10 year window, favoring companies with robust R&D pipelines for grid-interactive features. Acquisition targets include specialized firms with patented MPPT algorithms or strong regional distribution networks. The signal to watch is the adoption rate of integrated battery management solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop GaN-based Microinverters | Advanced power semiconductors improve efficiency and thermal performance for residential and commercial applications. |
| Partner for AC Module Integration | Collaboration with PV panel manufacturers streamlines installation and logistics for distributors and homeowners. |
| Expand Grid-Support Software | Integrated software for voltage regulation provides ancillary services to utilities and enhances grid stability. |
| Target Southeast Asian Markets | Expanding into high-growth regions leverages increasing consumer awareness and distributed generation policies. |
| Invest in Battery Management Features | Integrated capabilities for energy storage appeal to homeowners seeking greater energy independence and resilience. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during primary research to gather qualitative insights. Interviews included solar installers, utility grid planners, residential homeowners, and commercial project developers. Secondary validation drew from national energy agency reports, manufacturer financial disclosures, and industry association publications. A rigorous bottom-up and top-down triangulation process ensured data accuracy.
The forecasting framework employed a robust quantitative model to project market evolution across the analysis window. Segmentation dimensions included product type, application, technology, end-user, and regional adoption patterns. Compound annual growth rates were derived through regression analysis of historical trends and projected future demand. Key forecast inputs included residential installation rates and government incentive program uptake.
Material uncertainties — such as semiconductor supply chain disruptions or sudden policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological advancements and regulatory stability within the solar sector. Recalibration cycles align with material shifts in these underlying market drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Global Micro Solar Inverter Market