
 Marine Solar Panel Market | 2026-2036
Marine Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Solar Panel Market Analysis
A shortage of certified marine electricians is redrawing how manufacturers scale service networks across ports. JinkoSolar leverages its wafer-to-module integration to control cost structures for saltwater-rated products. Canadian Solar anchors North American distribution through dedicated marine channel partners. Solbian specializes in Italian-designed flexible panels that dominate Mediterranean yacht retrofit demand.
Marine solar panels are photovoltaic modules engineered with corrosion-resistant encapsulants, tempered glass rated for salt spray, and junction boxes meeting IP67 standards to sustain continuous maritime exposure. Their primary purpose is converting solar energy into electrical power for auxiliary systems, battery charging, and hybrid propulsion aboard watercraft and offshore structures. Flexible panels command premium positioning in yacht applications where curved deck surfaces prohibit rigid mounting, while monocrystalline variants lead efficiency benchmarks for commercial ferry operators prioritizing space constraints. Integrated installation systems are capturing margin pools as shipyards specify factory-embedded routing during new-build construction.
The International Maritime Organization enforces carbon intensity indicators that mandate documented efficiency improvements for vessels above gross tonnage thresholds. ISO 16315 standards govern electrical installations on small craft, while the EU Green Deal's maritime fuel regulations push European operators toward hybrid solar-diesel architectures. Stakeholders must monitor how port electrification infrastructure investments reshape panel sizing requirements for shore-power-independent vessels.
Market Dynamics
The International Maritime Organization's carbon intensity indicator (CII) framework is forcing vessel operators to document annual efficiency gains or face operational penalties, creating structural pull for auxiliary solar systems that offset diesel generator runtime.
Growth Catalysts
- EU Green Deal maritime fuel regulations:European ferry operators must cut greenhouse gas intensity by specific thresholds, accelerating hybrid solar-diesel retrofits on Baltic and Mediterranean routes.
- Salt spray corrosion engineering advances:New encapsulant chemistries extend panel lifespan in high-humidity marine environments, reducing replacement frequency for offshore platform operators.
- Port electrification infrastructure gaps:Shore-power-independent vessels in Southeast Asian manufacturing clusters require larger onboard solar arrays to maintain operations during extended anchorage.
Market Restraints
- High-purity silicon price volatility:Polysilicon input costs fluctuate with energy-intensive smelting operations concentrated in specific manufacturing zones, compressing module margins unpredictably.
- Certified marine electrician scarcity:Specialized installation labor pools remain shallow across major port cities, extending project timelines and inflating commissioning costs.
- Flexible panel efficiency ceiling:Crystalline alternatives deliver superior wattage per square meter, limiting addressable market for curved-deck yacht applications where rigid mounting is impossible.
Strategic Opportunities
- Indonesian archipelago ferry electrification:Thousands of short-haul vessels connecting island populations lack grid access, creating captive demand for standalone solar-battery systems.
- Integrated factory-embedded routing:Shipyards in South Korea and Germany now specify solar conduit pre-installation during hull construction, capturing margin pools previously lost to aftermarket retrofit.
- Battery-solar hybrid convergence:Lithium iron phosphate storage systems paired with photovoltaic generation enable overnight auxiliary power, displacing overnight generator operation in cruise ship galleys and crew quarters.
Industry Challenges
- IP67 junction box certification bottlenecks:Testing laboratory capacity constraints delay product launches, particularly for manufacturers seeking simultaneous IEC and UL marine listings.
- Legacy 12V/24V electrical architecture incompatibility:Older vessel fleets require voltage conversion hardware that adds cost, complexity, and failure points to solar integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Solar Panel Market |
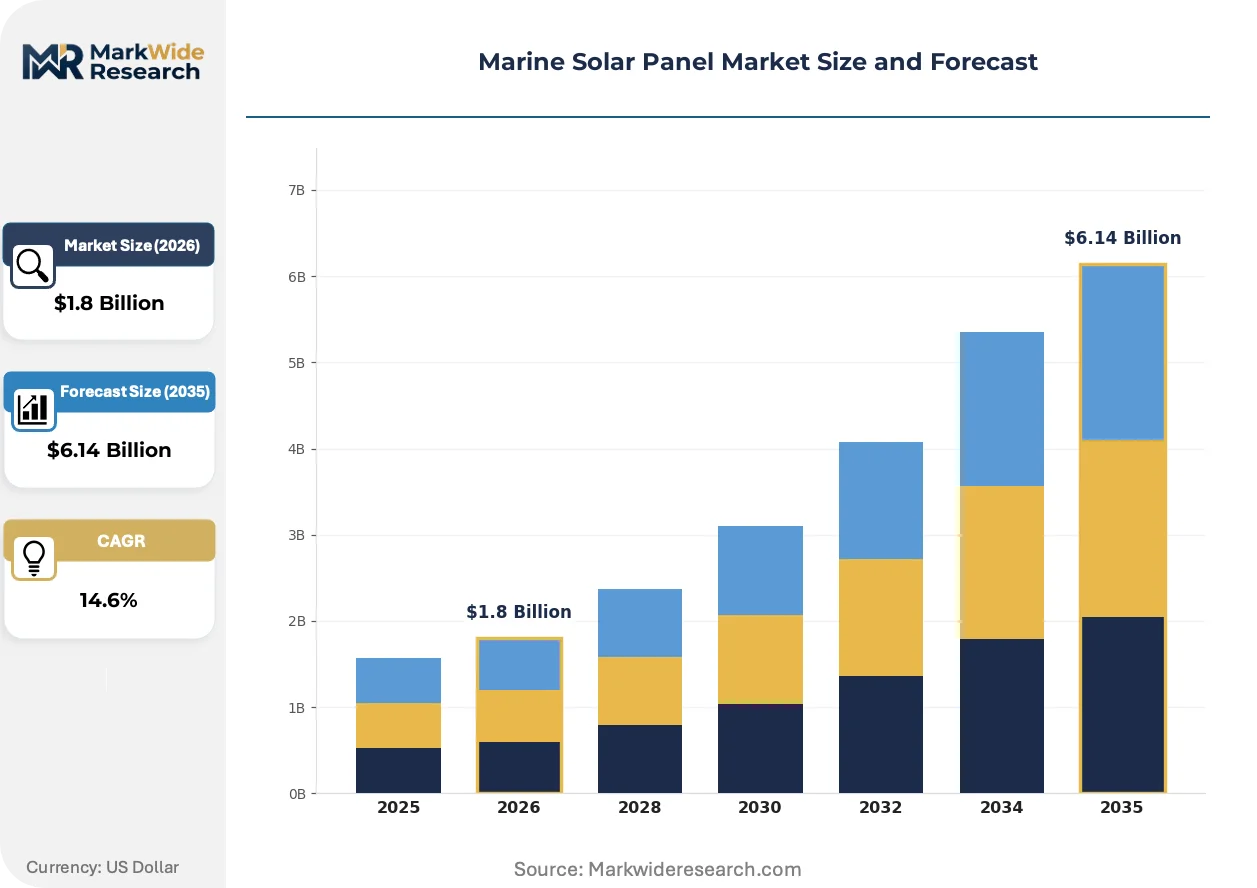
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Panels, Monocrystalline Panels, Polycrystalline Panels, Bifacial Panels Application: Yachts, Boats, Ferries, Offshore Platforms Installation: Roof Mount, Deck Mount, Portable Systems, Integrated Systems End User: Private Users, Commercial Operators, Government Agencies, NGOs |
| Companies Covered | JinkoSolar, JA Solar Technology, Renogy, Hanwha Q CELLS, Canadian Solar, Suaoki SunPower, Trina Solar, LONGi Green Energy Technology, Solbian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Solar Panel Market Emerging Trajectories
Marine photovoltaic technology is compressing into lighter, more conformable formats while regulatory pressure intensifies documentation requirements for carbon accounting. Installation practices are shifting toward factory integration rather than deck-mounted aftermarket systems.
Perovskite-silicon tandem cell development is miniaturizing high-efficiency generation into flexible substrates previously limited to lower-output amorphous silicon. Superyacht builders in Italian and Dutch shipyards are specifying these ultra-thin panels for curved superstructure surfaces where rigid glass modules cannot conform. The structural consequence is a bifurcation in supplier tiers, with specialized thin-film manufacturers capturing premium retrofit contracts while crystalline producers dominate commercial ferry new-build specifications.
REACH regulation amendments governing persistent organic pollutants in electrical equipment are restricting certain flame-retardant encapsulant chemistries previously standard in marine-rated junction boxes. European panel assemblers must reformulate potting compounds or source alternative certification pathways, adding months to product development cycles. Baltic Sea operators face the tightest compliance windows, with Danish and Swedish flag registries enforcing early adoption timelines ahead of broader EU implementation.
Shipyard procurement departments are consolidating vendor relationships around turnkey solar-battery-inverter packages rather than sourcing components separately. This bundling compresses supplier margins while shifting technical liability to integrated system providers. The pattern is most pronounced in German and Chinese coastal manufacturing clusters, where large ferry and offshore support vessel contracts now specify single-source responsibility for auxiliary power system performance warranties.
Marine Solar Panel Market Segmentation
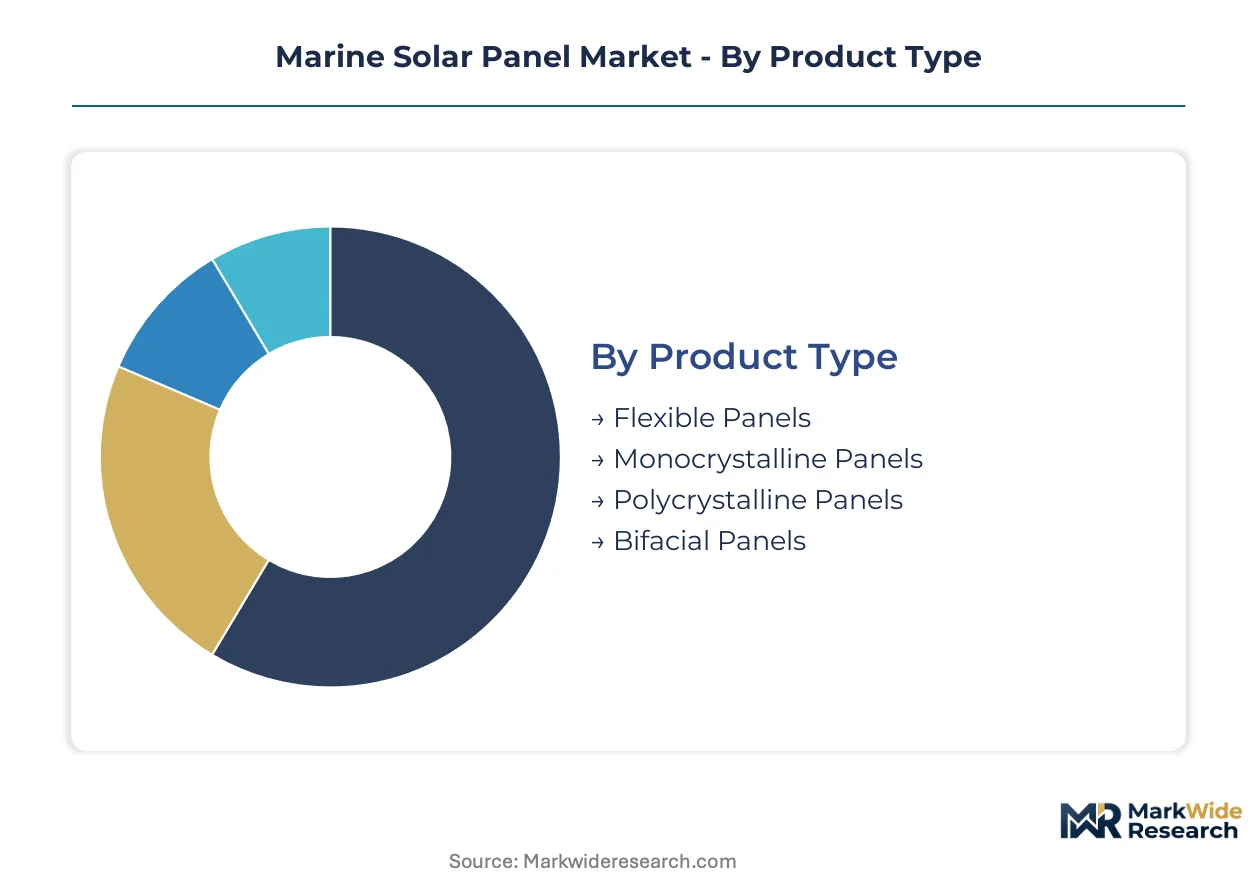
Marine solar panel segmentation reveals divergent engineering requirements across vessel architectures and operational profiles. Understanding substitution pressures between rigid and flexible formats, integrated versus aftermarket installation, and commercial versus private demand concentration enables targeted positioning against regulatory deadlines and port infrastructure gaps.
Product Type:
Flexible panels face acute substitution pressure from advancing bifacial crystalline designs that deliver superior wattage density for flat-deck commercial applications.
- Flexible Panels:Thin-film or crystalline silicon bonded to polymer substrates that conform to curved yacht superstructures. Mediterranean and Caribbean charter fleets specify these for aesthetic integration where rigid glass would compromise deck lines, though efficiency penalties limit commercial ferry adoption.
- Monocrystalline Panels:Single-crystal silicon cells delivering maximum conversion efficiency in space-constrained installations. Baltic Sea and North Sea ferry operators prioritize these for auxiliary power systems where deck area is strictly limited by passenger capacity requirements.
- Polycrystalline Panels:Multi-crystal silicon construction offering moderate efficiency at reduced cost points. Southeast Asian fishing vessel retrofits favor these for battery charging systems where capital constraints outweigh space optimization.
- Bifacial Panels:Dual-sided cell architecture capturing reflected light from water surfaces. Offshore platform operators in the North Sea deploy these on elevated support structures to maximize yield from albedo effects.
Monocrystalline panels anchor the volume base while bifacial designs gain share at the steepest rate.
Application:
Cost tier stratification separates premium yacht specifications from utility-driven offshore platform procurement, with ferry electrification occupying a mid-tier efficiency-cost balance.
- Yachts:Recreational vessels under 24 meters requiring auxiliary power for hospitality systems. Italian and Dutch superyacht builders specify factory-integrated solar routing during hull construction to preserve interior volume.
- Boats:Small commercial and private craft under 12 meters with basic electrical demands. Indonesian inter-island passenger boats represent concentrated retrofit demand where grid independence is mandatory.
- Ferries:Scheduled passenger vessels operating fixed routes with predictable duty cycles. EU Green Deal compliance deadlines are accelerating hybrid solar-diesel installations on Baltic and Mediterranean routes.
- Offshore Platforms:Fixed and floating production facilities requiring continuous auxiliary power. North Sea operators are expanding photovoltaic arrays to reduce diesel generator runtime and helicopter resupply frequency.
Ferries represent the most rapidly expanding application trajectory while offshore platforms maintain the highest average system value per installation.
Installation:
Volume concentration in shipyard new-build specifications is displacing aftermarket retrofit as the primary channel, shifting margin capture toward factory-embedded routing.
- Roof Mount:Rigid panel arrays secured to vessel superstructure via aluminum rail systems. Commercial ferry operators in Germany and South Korea favor these for structural simplicity and maintenance access.
- Deck Mount:Low-profile framing systems preserving passenger circulation space. Mediterranean yacht charter fleets specify these for removable seasonal installation.
- Portable Systems:Temporary foldable or rollable panels for emergency or supplemental power. Recreational sailors in Australian coastal waters deploy these for anchorages beyond shore power range.
- Integrated Systems:Factory-embedded conduit and mounting hardware specified during hull construction. South Korean shipyards are capturing margin pools previously lost to aftermarket installers by bundling solar pre-installation into new-build contracts.
Roof mount configurations dominate current installed base while integrated systems are climbing the fastest in new-build procurement specifications.
End User:
Customer type determines procurement sophistication, with commercial operators driving standardization and government agencies mandating performance verification protocols.
- Private Users:Individual vessel owners prioritizing energy independence and operating cost reduction. Australian and Mediterranean recreational sailors represent concentrated demand for flexible panel retrofits.
- Commercial Operators:Fleet owners with documented carbon intensity obligations under IMO frameworks. European ferry companies are consolidating vendor relationships around turnkey solar-battery-inverter packages.
- Government Agencies:Public maritime authorities specifying renewable systems for patrol, research, and transport vessels. Danish and Swedish flag registries enforce early REACH compliance timelines for auxiliary electrical systems.
- NGOs:Non-governmental organizations deploying solar-powered vessels for conservation and humanitarian missions. Pacific Island health outreach boats rely on standalone solar-battery architectures beyond grid reach.
Commercial operators anchor procurement volume while government agencies are expanding specifications most aggressively under regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization's carbon intensity framework is redrawing procurement patterns across coastal manufacturing zones. Shipyards in China, South Korea, and Germany now specify factory-embedded solar routing during hull construction to preserve certification timelines.
China
Yangtze River Delta shipyards dominate new-build solar specifications for commercial ferries and offshore support vessels. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate photovoltaic integration in state-owned fleet renewals. Ningbo and Shanghai manufacturing clusters supply salt-spray-rated junction boxes to domestic yards and Southeast Asian retrofit markets.
South Korea
Busan-Ulsan shipbuilders capture margin pools by bundling solar pre-installation into new-build contracts for Baltic Sea and Mediterranean ferry operators. The Korea Maritime and Ocean University certifies marine electricians under MFDS-aligned standards, addressing labor scarcity that delays commissioning. Geoje Island yards specialize in integrated solar-battery systems for offshore platform auxiliary power.
Germany
North Sea ferry operators under EU Green Deal deadlines drive monocrystalline panel procurement for hybrid solar-diesel architectures. The KBA enforces early REACH compliance timelines for flame-retardant encapsulant chemistries in auxiliary electrical systems. Hamburg and Bremen shipyards consolidate vendor relationships around turnkey solar-battery-inverter packages with single-source performance warranties.
Italy
Mediterranean yacht builders in Lombardy and Veneto specify flexible panel integration for curved superstructure surfaces where rigid mounting compromises deck lines. The EU Green Deal's maritime fuel regulations push charter fleets toward documented efficiency improvements. Viareggio and La Spezia clusters anchor demand for Italian-designed thin-film retrofit systems.
Indonesia
Inter-island ferry operators across the archipelago lack grid access, creating captive demand for standalone solar-battery architectures. The national maritime regulator mandates safety certification for auxiliary electrical systems under SOLAS-aligned protocols. Surabaya and Makassar shipyards retrofit thousands of short-haul vessels with polycrystalline charging systems for battery-dependent operations.
Marine Solar Panel Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with crystalline silicon producers controlling cost structures and thin-film manufacturers capturing premium retrofit positioning. The market structure bifurcates between wafer-to-module integrators and application-specific designers. Three archetypes dominate: integrated photovoltaic giants, flexible panel specialists, and marine-channel distributors. Competitive moves concentrate on factory-embedded routing partnerships with shipyards and backward integration into corrosion-resistant encapsulant supply.
Among Chinese wafer-to-module integrators, JinkoSolar and Trina Solar exemplify the scale-driven tier that supplies crystalline panels for commercial ferry new-builds. Canadian Solar anchors North American distribution through dedicated marine channel structures. Solbian occupies a position within the flexible panel specialist tier, representing Italian-designed thin-film positioning for Mediterranean yacht retrofit demand where curved deck surfaces prohibit rigid mounting.
| Leading Market Players |
|---|
| JinkoSolar |
| JA Solar Technology |
| Renogy |
| Hanwha Q CELLS |
| Canadian Solar |
| Suaoki SunPower |
| Trina Solar |
| LONGi Green Energy Technology |
| Solbian |
| Others |
Supply Flow & Price Mechanics
Ninety-day certification lead times for IP67 junction boxes concentrate pricing power with testing laboratories in Germany and South Korea, compressing module margins for manufacturers awaiting dual IEC-UL listings while amplifying premiums for pre-certified inventory holders serving Baltic ferry retrofit deadlines.
Pricing Analysis
Price spreads between Chinese crystalline modules and Italian flexible panels exceed threefold, reflecting bifurcation between commodity-scale ferry procurement and yacht retrofit customization. Pricing stratifies across premium, standard, and economy tiers driven by salt-spray certification grade and factory-embedded installation bundling. Cost compression in polycrystalline segments is intensifying because Indonesian fishing vessel operators prioritize capital efficiency over efficiency benchmarks. Commercial ferry fleet managers exhibit lowest price sensitivity due to EU Green Deal compliance penalties, while Southeast Asian independent boat owners anchor the economy tier.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant encapsulants dominates procurement behavior as REACH amendment timelines compress reformulation windows for European assemblers. Polysilicon smelting concentrates in China, high-purity wafer slicing in South Korea, and salt-spray-rated junction box assembly in Germany. Raw material dependencies span metallurgical-grade silicon, fluoropolymer encapsulants, and marine-grade aluminum framing systems. Single-source vulnerability in certified marine electrician labor pools across major port cities threatens installation throughput. Distribution runs through shipyard procurement departments consolidating around turnkey solar-battery-inverter packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-embedded installation services and performance warranty extensions are expanding faster than hardware unit sales, repositioning margin capture toward recurring-revenue architectures in ferry new-build contracts.
For Market Incumbents: Consolidate certification asset control by acquiring testing laboratory capacity or securing exclusive queue positions for IP67 junction box validation, defending against thin-film specialists capturing yacht retrofit premiums. Deepen backward integration into corrosion-resistant encapsulant supply to offset REACH reformulation cost spikes. For New Entrants and Emerging Players: Lead with standalone solar-battery system architectures for Indonesian archipelago ferry operators lacking grid access, the most penetrable white-space segment. Target government agency procurement channels through pre-certified SOLAS-aligned safety documentation, bypassing commercial operator vendor consolidation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because IMO carbon intensity indicators and EU Green Deal maritime fuel regulations structurally embed solar auxiliary systems into vessel operating economics. Acquisition targets should display factory-embedded routing partnerships with South Korean or German shipyards. Watch IP67 certification backlog duration as the signal for pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Embedded Routing Partnership | Shipyards in Geoje and Hamburg capture margin pools previously lost to aftermarket installers. |
| Corrosion-Resistant Encapsulant Backward Integration | REACH amendment compliance compresses reformulation timelines for Baltic Sea operators. |
| IP67 Testing Laboratory Capacity Expansion | Dual IEC-UL listing bottlenecks delay product launches for crystalline module manufacturers. |
| Turnkey Solar-Battery-Inverter Packaging | Commercial ferry operators consolidate vendor relationships under single-source performance warranties. |
| Certified Marine Electrician Training Program | Busan-Ulsan clusters address labor scarcity delaying commissioning across port cities. |
Methodological Framework
Desk research of customs trade data, shipyard procurement disclosures, and IMO regulatory filings preceded structured interviews with shipyard procurement directors, marine electrical system engineers, ferry fleet operations managers, and certified marine electrician training program administrators. Secondary validation drew from IEC certification databases, EU Green Deal implementation timelines, and port electrification infrastructure investment records. Bottom-up vessel installation estimates triangulated against top-down module production and trade flow analysis.
Variance decomposition across product type, application, installation method, and end user dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion constraints. Forecast inputs incorporated IMO carbon intensity indicator penalty schedules, EU Green Deal maritime fuel regulation compliance deadlines, and shipyard new-build contract pipeline visibility.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of IMO frameworks or accelerated REACH amendment implementation would require recalibration. Forecasts reflect assumptions regarding certification laboratory capacity expansion and polysilicon price stabilization. Revision becomes warranted when IP67 testing backlog duration or certified marine electrician graduation rates cross thresholds that structurally constrain installation throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar EVA Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Bifacial Solar Market