
 Solar PV Module Market | 2026-2036
Solar PV Module Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Module Market Analysis
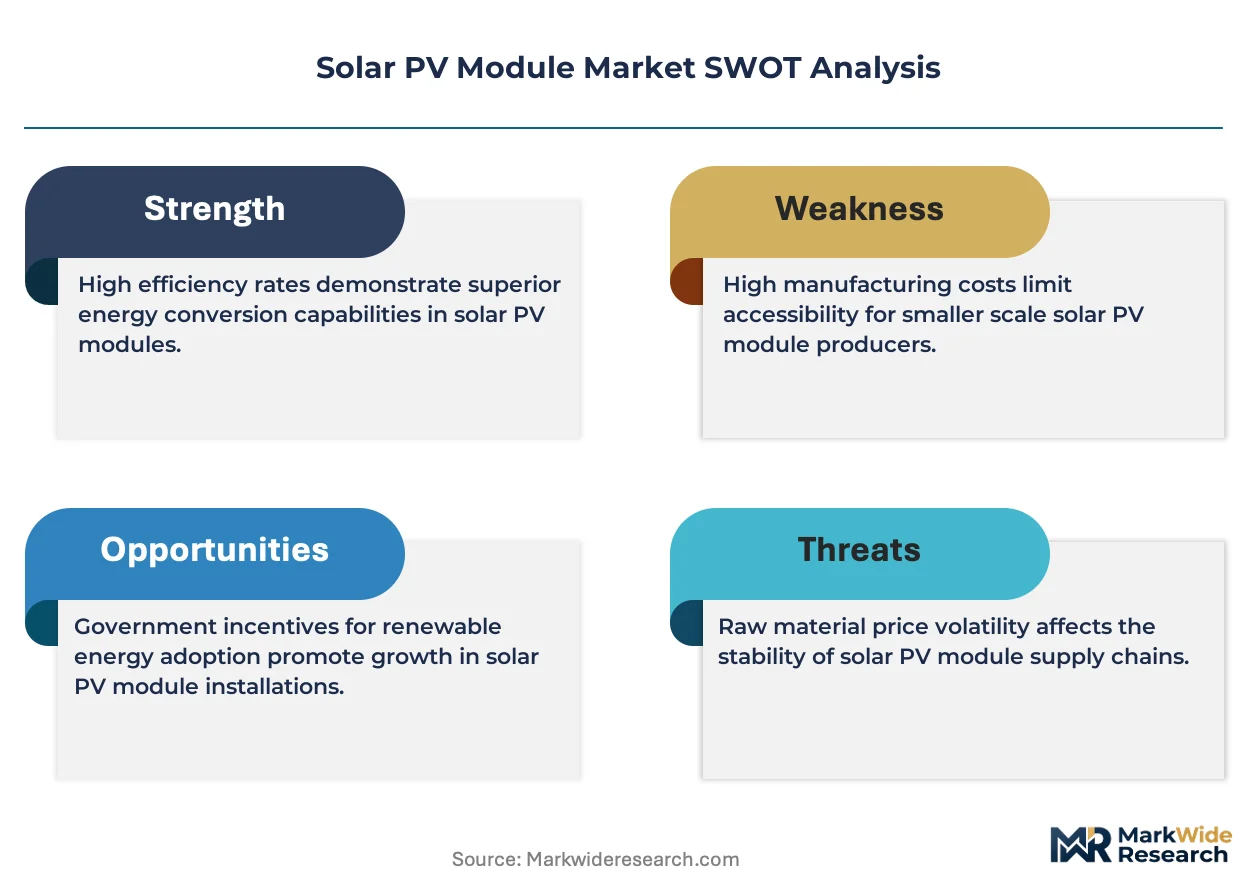
Photovoltaic engineering talent is collapsing across Southeast Asian contract manufacturing hubs, constraining module assembly expansion just as gigawatt-scale orders from European and Middle Eastern developers surge. LONGi Green Energy Technology anchors its competitive position through captive polysilicon and wafer capacity that insulates margin structures from raw material volatility. First Solar differentiates via its vertically integrated CdTe thin-film platform purpose-built for utility-scale deployment in North American desert climates. JinkoSolar extends its manufacturing footprint across Malaysia and Vietnam to navigate tariff and origin-rule complexities affecting module shipments into the United States and European Union.
A solar PV module is an interconnected assembly of photovoltaic cells laminated between encapsulant layers, tempered glass, and a weatherproof backsheet, designed to convert incident solar irradiance into direct-current electricity at system voltages typically ranging from 600V to 1500V. The device serves as the fundamental energy-harvesting unit within rooftop arrays, commercial installations, and centralized solar power stations. Monocrystalline silicon modules dominate installed capacity owing to record laboratory efficiencies exceeding 26% and declining wafer thicknesses that reduce silicon consumption per watt. Bifacial modules represent the fastest-expanding product category as tracking system operators capture reflected albedo gains from ground surfaces. HJT technology leads the next-generation cell architecture race by combining high open-circuit voltages with simplified low-temperature processing that preserves wafer quality.
Federal Investment Tax Credit provisions administered by the US Internal Revenue Service, European Union F-Gas Regulation restrictions on fluorinated greenhouse gases used in module manufacturing, and China's National Energy Administration renewable portfolio obligations collectively shape product certification requirements, carbon intensity benchmarks, and market access conditions across major demand centers. Module suppliers must maintain IEC 61215 and IEC 61730 certifications for mechanical load and electrical safety while adapting to emerging country-of-origin documentation demands affecting tariff exposure. Stakeholders should monitor evolving domestic content thresholds in US Inflation Reduction Act implementation and corresponding European Union response mechanisms that will determine competitive positioning of Asian versus Western manufacturing footprints.
Market Dynamics
Passivated Emitter and Rear Contact cell architectures are accelerating manufacturing consolidation toward integrated polysilicon-to-module facilities as aluminum-back surface field designs face obsolescence.
Growth Catalysts
- US Inflation Reduction Act domestic content bonuses:The IRS-administered Investment Tax Credit adders reward module assembly within North American supply chains, redirecting procurement toward certified origin documentation.
- European F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in manufacturing processes force module suppliers toward low-carbon production certifications that unlock utility-scale tenders.
- Bifacial module albedo capture:Tracking system operators in desert climates extract reflected ground gains that boost effective capacity factors beyond monofacial equivalents.
Market Restraints
- Polysilicon price volatility:Metallurgical-grade silicon feedstock and energy-intensive purification expose margin structures to electricity cost swings in Xinjiang and Inner Mongolia production zones.
- Wafer-thinning technical floor:Monocrystalline silicon approaching 130-micron thickness limits risks mechanical breakage during cell fabrication and module lamination.
- Country-of-origin tariff exposure:US Customs and Border Protection enforcement against Southeast Asian transshipment creates documentation burdens that delay project financing close.
Strategic Opportunities
- India PLI scheme manufacturing scale-up:Production-linked incentive allocations for integrated cell and module capacity attract capital toward Gujarat and Tamil Nadu industrial corridors.
- Agrivoltaic dual-use installations:Elevated bifacial arrays over agricultural land generate electricity while preserving crop cultivation, opening rural zoning previously restricted to pure generation.
- Heterojunction-TOPCon convergence:Low-temperature processing architectures combining high open-circuit voltages with tunnel oxide passivated contacts promise efficiency breakthroughs without laser-induced damage.
Industry Challenges
- Photovoltaic engineering talent scarcity:Southeast Asian contract manufacturing hubs face collapsing technical workforce pipelines just as gigawatt-scale orders from European and Middle Eastern developers surge.
- IEC certification timeline compression:Mechanical load testing under IEC 61215 and electrical safety validation per IEC 61730 create bottlenecks when multiple product variants launch simultaneously.
- Supply chain reconfiguration friction:Shifting wafer sourcing from Chinese ingot producers to alternative polysilicon purification facilities requires recalibrating cell efficiency baselines and warranty terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Module Market |
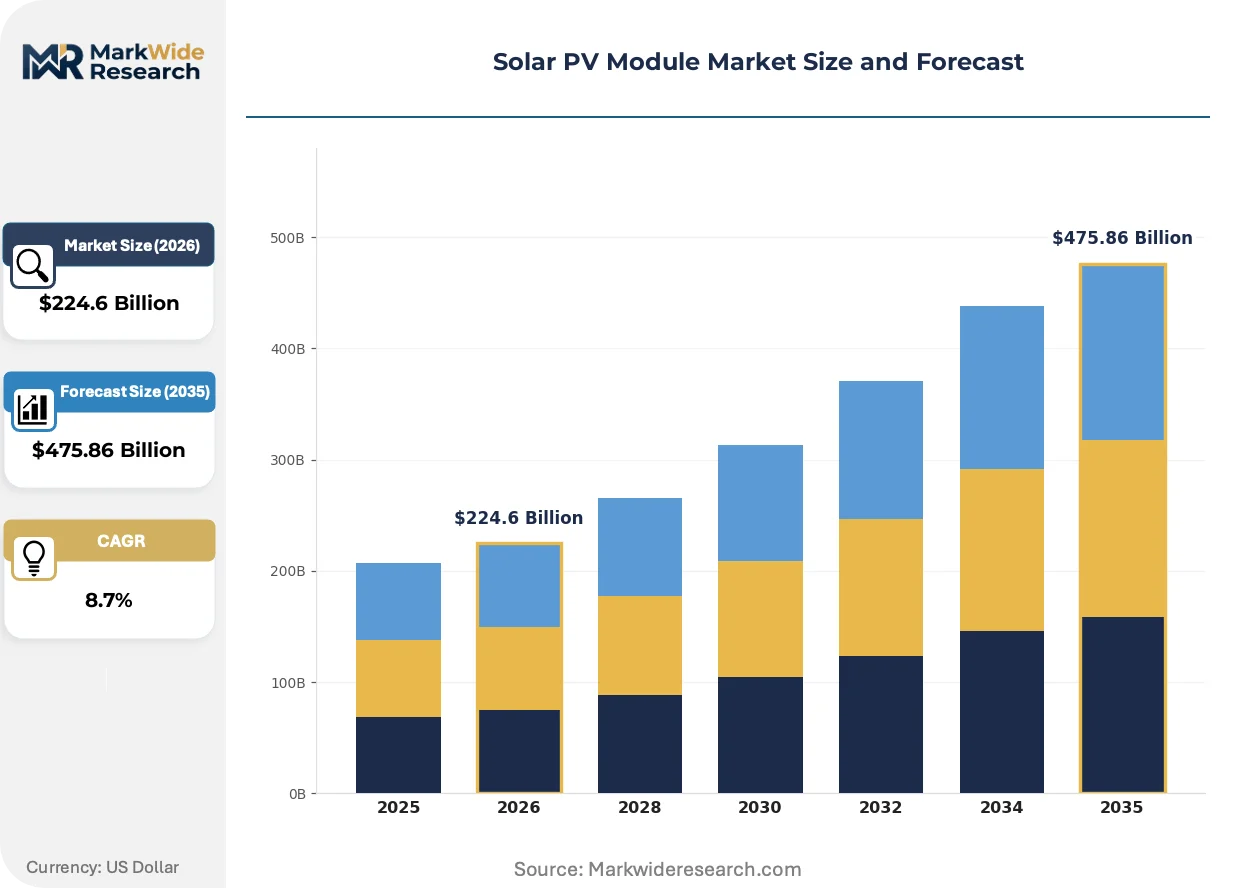
| Market Size in 2026 | $224.6 Billion |
| Market Size in 2035 | $475.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Utility Technology: PERC, HJT, CdTe, CIGS End User: Homeowners, Businesses, Energy Providers, Government |
| Companies Covered | Trina Solar, Canadian Solar, JinkoSolar, Aiko Solar, Risen Energy, LONGi Green Energy Technology, Tongwei Solar, First Solar, JA Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Module Market Emerging Trajectories
Cell metallization patterns and encapsulant chemistries are undergoing simultaneous revision as module suppliers chase higher efficiency tiers while satisfying emerging carbon intensity disclosure requirements.
Heterojunction architectures employing intrinsic thin-film silicon layers on crystalline substrates achieve open-circuit voltages above 750 millivolts. Utility-scale developers in North American desert climates are specifying HJT modules for temperature coefficient advantages. This technology is displacing conventional PERC dominance in premium procurement tenders where levelized cost of energy margins are tight.
The European Union F-Gas Regulation mandates progressive reduction in hydrofluorocarbon emissions from module lamination and cleaning processes. Manufacturers must retrofit production lines or absorb carbon border adjustment costs that affect export competitiveness. Module suppliers serving European utility tenders are accelerating fluorine-free backsheet and encapsulant qualifications to maintain market access.
Direct power purchase agreements between data center operators and solar developers are compressing traditional utility intermediary roles. Hyperscale cloud computing campuses in Arizona, Nevada, and Virginia are contracting dedicated offtake from adjacent solar farms rather than procuring through regulated tariffs. This bypasses legacy renewable energy credit aggregation structures that previously dominated corporate clean power procurement.
Solar PV Module Market Segmentation
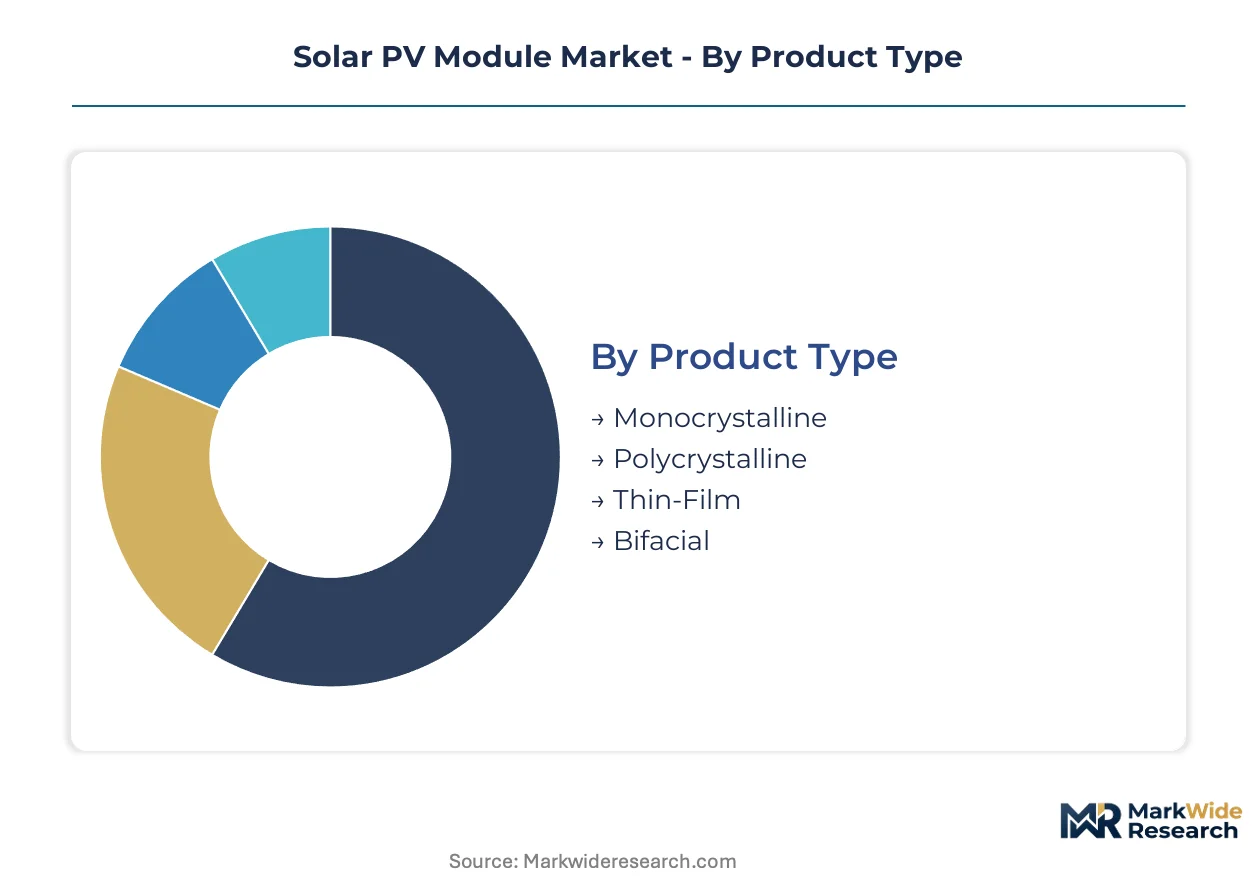
Technology pathways and customer procurement patterns fragment the Solar PV Module Market into distinct competitive arenas. Each segment carries unique certification requirements, margin structures, and geographic demand centers that reshape supplier positioning.
Product Type:
Domestic rooftop installations favor standardized formats while export-led utility procurement drives specialized high-output variants.
- Monocrystalline:Single-crystal silicon wafers cut from cylindrical ingots achieve laboratory efficiencies above 26%. Utility-scale developers in Arizona and Rajasthan specify these modules for space-constrained installations where watt-density maximizes land yield.
- Bifacial:Dual-glass constructions capture direct irradiance plus ground-reflected albedo, boosting effective output 10-20% on tracking systems. Desert climate operators in Nevada and Saudi Arabia are accelerating procurement as albedo modeling improves project finance certainty.
- Polycrystalline:Multi-crystal silicon formed from molten silicon feedstock offers cost advantages in price-sensitive emerging markets.
- Thin-Film:Cadmium telluride and CIGS layers deposited on glass substrates deliver superior temperature coefficients for hot-climate utility deployment.
Monocrystalline commands the established base. The steepest expansion runs through Bifacial.
Application:
Volume concentration tilts toward megawatt-scale procurement while margin retention favors distributed generation channels.
- Utility:Centralized solar power stations exceeding 100MW capacity deploy high-voltage 1500V module strings with tracking infrastructure. Grid interconnection queues in Texas and Gujarat are accelerating procurement timelines for independent power producers.
- Residential:Rooftop arrays sized 5-20kW serve homeowner self-consumption and net-metering regimes. California NEM 3.0 reforms are compressing payback calculations and shifting demand toward battery-coupled installations.
- Commercial:Behind-the-meter systems for manufacturing facilities and retail chains target demand charge reduction.
- Industrial:Large on-site generation for data centers and heavy manufacturing seeks 24/7 renewable matching.
Utility-scale procurement absorbs the dominant share of module volume. Residential applications are gaining share fastest as financing mechanisms mature.
Technology:
Cell architecture selection determines capital intensity and efficiency ceiling, with migration patterns diverging between incumbent and next-generation platforms.
- PERC:Passivated Emitter and Rear Contact designs add dielectric layers to reduce electron recombination, dominating current manufacturing capacity. Chinese producers in Jiangsu and Anhui are maximizing equipment utilization before technology transition costs accelerate.
- HJT:Heterojunction architectures sandwich crystalline silicon between amorphous silicon layers, achieving open-circuit voltages above 750mV with simplified low-temperature processing. European and Japanese equipment suppliers are capturing retrofit demand as lines convert from PERC.
- CdTe:Cadmium telluride thin-film deposition enables vertical integration from semiconductor feedstock through module assembly.
- CIGS:Copper indium gallium selenide flexible substrates target building-integrated and specialty applications.
PERC retains the installed capacity base. HJT deployment is climbing the fastest as efficiency premiums justify capital replacement.
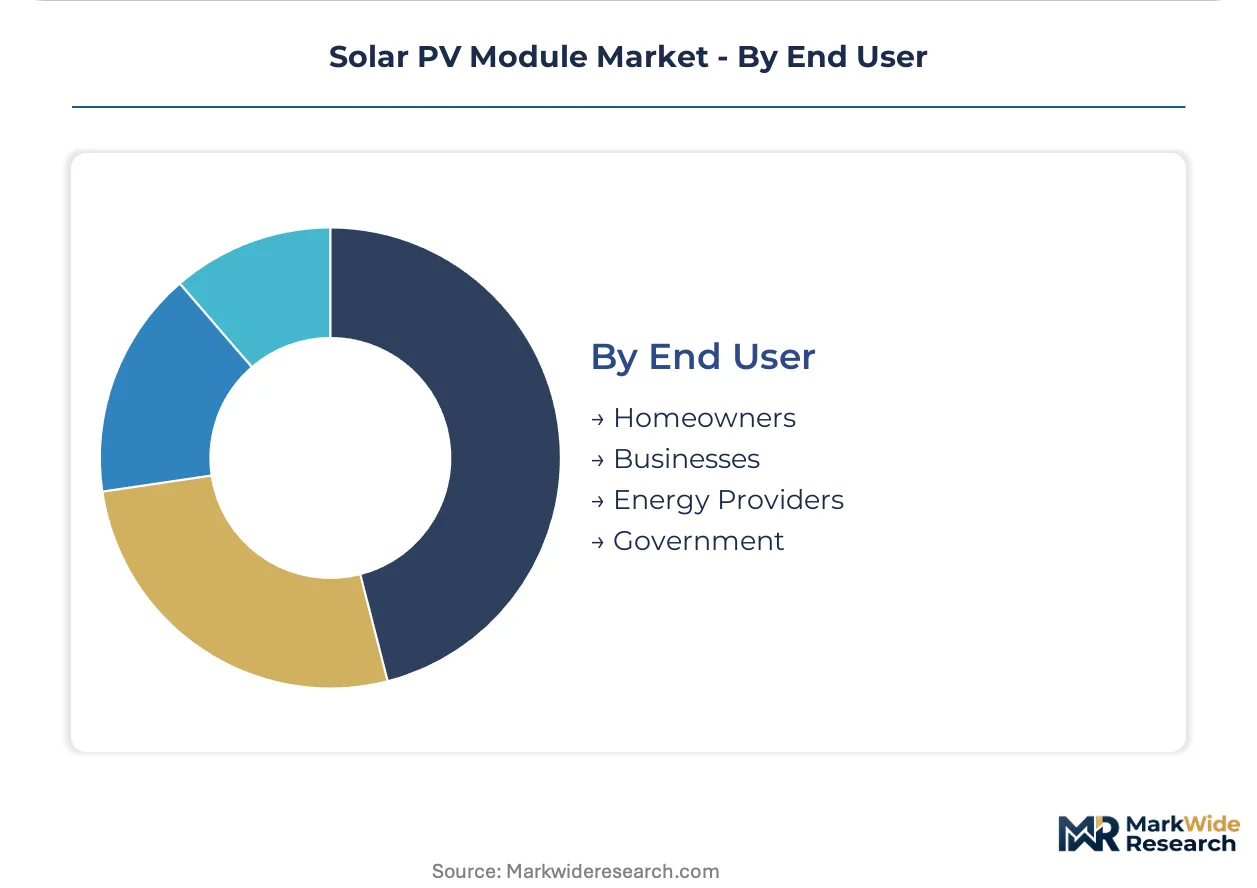
End User:
Procurement sophistication varies sharply across customer categories, with institutional buyers extracting terms unavailable to fragmented purchasers.
- Energy Providers:Electric utilities and independent power producers negotiate multi-gigawatt supply agreements with origin documentation for tariff compliance. European utilities under REPowerEU obligations are accelerating contract execution to secure 2025-2027 delivery slots.
- Businesses:Corporate offtakers under science-based targets contract virtual or physical PPAs directly with solar developers. Hyperscale cloud operators in Virginia and Iowa are bypassing traditional utility intermediaries for dedicated solar farm output.
- Homeowners:Distributed generation adopters respond to net-metering economics and installer financing availability.
- Government:Public procurement for military installations, federal facilities, and state renewable mandates specifies domestic content thresholds.
Energy Providers command the established procurement volume. Business direct contracting is expanding most quickly as corporate sustainability targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale procurement dominates module deployment in desert climates, while distributed rooftop systems concentrate in high-electricity-price jurisdictions with favorable net-metering regimes.
United States
Data center operators in Virginia and Arizona are contracting dedicated solar capacity under direct power purchase agreements. The IRS-administered Investment Tax Credit domestic content bonuses redirect procurement toward North American assembly documentation. Module suppliers cluster in Ohio and Texas industrial corridors to satisfy origin requirements for tariff-exempt delivery.
China
National Energy Administration renewable portfolio obligations mandate utility-scale deployment across western provinces. The country's dual carbon goals accelerate polysilicon-to-module integration in Xinjiang and Inner Mongolia production zones. Jiangsu and Anhui provinces retain dominant PERC cell fabrication capacity ahead of heterojunction transition.
Germany
REPowerEU obligations drive European utilities to accelerate contract execution for 2025-2027 delivery slots. The EU F-Gas Regulation restricts fluorinated greenhouse gases in module lamination processes. Industrial buyers in Bavaria and North Rhine-Westphalia specify low-carbon production certifications for utility-scale tenders.
India
Production-linked incentive allocations attract integrated cell and module capacity toward Gujarat and Tamil Nadu industrial corridors. Central Electricity Authority mandates tighten renewable purchase obligations for distribution utilities. Rajasthan and Karnataka states host gigawatt-scale solar parks with domestic content requirements.
Vietnam
Contract manufacturing hubs face collapsing photovoltaic engineering talent pipelines as European developer orders surge. Module assembly facilities in Bac Ninh and Hai Phong industrial zones navigate US Customs origin documentation demands. Suppliers recalibrate wafer sourcing to avoid tariff exposure on Southeast Asian transshipment.
Solar PV Module Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the current market structure. Captive polysilicon and wafer capacity insulates margin structures from raw material volatility among vertically positioned players. Specialist fabricators concentrate on regional tariff navigation and certification compliance. Dominant competitive moves include capacity expansion in India PLI scheme corridors and technology licensing for heterojunction cell architecture conversion.
Among Chinese-integrated producers, LONGi Green Energy Technology and Tongwei Solar occupy positions representing upstream control over polysilicon feedstock. First Solar exemplifies the thin-film archetype purpose-built for utility-scale deployment. These three anchors illustrate divergent strategic pathways: crystalline silicon integration versus cadmium telluride verticalization versus Southeast Asian tariff-optimized assembly.
| Leading Market Players |
|---|
| Trina Solar |
| Canadian Solar |
| JinkoSolar |
| Aiko Solar |
| Risen Energy |
| LONGi Green Energy Technology |
| Tongwei Solar |
| First Solar |
| JA Solar |
| Others |
Supply Flow & Price Mechanics
Gigawatt-scale polysilicon purification in Xinjiang and Inner Mongolia generates cost advantages that cascade through wafer slicing, cell fabrication, and module lamination, compressing price floors for crystalline silicon architectures while concentrating supply-side leverage among integrated Chinese producers. This scale dynamic simultaneously enables aggressive bidding in utility-scale tenders and squeezes margin structures for non-integrated assemblers in Vietnam and Malaysia.
Pricing Analysis
Long-term offtake contracts dominate utility-scale procurement, with independent power producers in Texas and Rajasthan locking in fixed-price deliveries spanning multi-gigawatt volumes. Three-tier pricing structure across premium HJT, standard PERC, and economy polycrystalline levels reflects efficiency differentiation and certification grade. Pricing pressure stems from wafer-thinning yield losses and polysilicon electricity cost volatility. Distributed residential buyers exhibit highest price sensitivity, while hyperscale data center operators absorb premiums for domestic content documentation.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian module assembly, with polysilicon feedstock drawn from Xinjiang purification zones and wafer slicing concentrated in Jiangsu and Anhui provinces. Metallurgical-grade silicon, silver paste for cell metallization, and tempered glass represent critical input dependencies. Tariff exposure on Southeast Asian transshipment creates documentation burdens that delay project financing. Distribution runs through EPC contractors and direct developer relationships for utility-scale deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar PV Module Market constitutes a high-growth disruption driven by heterojunction cell architecture maturation and US Inflation Reduction Act domestic content enforcement redirecting procurement flows.
For Market Incumbents: Shield margin structures through captive polysilicon and wafer capacity that insulates against raw material volatility from Xinjiang electricity cost swings. Accelerate PERC-to-HJT line conversion ahead of efficiency premium erosion. Defend positioning by securing IEC 61215 and IEC 61730 certifications ahead of timeline compression bottlenecks. For New Entrants and Emerging Players: Differentiate on low-carbon production certifications that unlock European utility tenders under F-Gas Regulation compliance requirements. Target India PLI scheme corridors in Gujarat and Tamil Nadu where production-linked incentives offset capital intensity. Pursue agrivoltaic dual-use installations as a white-space channel with relaxed rural zoning constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cell-and-module producers with long-term offtake visibility from European utilities under REPowerEU obligations. Over the medium-term horizon, prioritize acquisition targets with heterojunction technology licenses and Southeast Asian tariff-optimized assembly footprints. Monitor US Customs and Border Protection enforcement intensity as the inflection signal for supply chain reconfiguration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Heterojunction Technology Licensing | European and Japanese equipment suppliers capture retrofit demand as PERC lines convert. |
| India PLI Scheme Manufacturing Scale-Up | Production-linked incentives attract capital toward Gujarat and Tamil Nadu industrial corridors. |
| Domestic Content Certification Investment | North American assembly documentation satisfies IRA bonus requirements for utility developers. |
| Low-Carbon Production Retrofit | Fluorine-free backsheet qualifications maintain European market access under F-Gas Regulation. |
| Agrivoltaic Channel Development | Elevated bifacial arrays open rural zoning previously restricted to pure generation installations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, independent power producer project developers, EPC contractors, and module procurement leads at European and Middle Eastern developers. Secondary validation drew from EIA project databases, IEA renewable energy reports, FERC interconnection filings, and IEC certification records. Bottom-up capacity and shipment estimates were triangulated against top-down demand projections from national renewable portfolio obligations.
Across the analysis window, the forecasting framework modeled technology pathway migration between PERC and HJT architectures, application splits across utility and residential deployment, and regional regulatory clusters shaped by domestic content requirements. CAGRs were derived from installed capacity buildout trajectories and module pricing elasticity assumptions. Forecast inputs incorporated polysilicon purification capacity utilization rates and tracking system deployment penetration in desert climates.
The analysis sits within stated boundaries; outcomes outside sustained IRA domestic content enforcement or accelerated F-Gas Regulation phase-down timelines would require recalibration. Forecasts reflect assumptions regarding heterojunction efficiency improvement curves and Southeast Asian engineering talent pipeline recovery. Practitioners should keep alternative scenarios live as US Customs origin documentation demands and European carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Module Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
India Solar Photovoltaic (PV) Market