
 Connected Energy Market | 2026-2036
Connected Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Energy Market Analysis
Market Context
ISO 50001 energy management certification is unwinding competitive barriers for suppliers seeking utility procurement contracts. Tesla leverages its integrated ecosystem of solar, storage, and software to sustain pricing power across residential and utility segments. GE Vernova anchors large-scale grid automation deployments through its hardware-software hybrid offerings. Siemens Gamesa competes in renewable integration by combining wind turbine connectivity with grid-edge control systems.
Technical Definition and Segment Structure
Connected energy encompasses digitally linked generation, storage, and consumption assets coordinated through real-time communication protocols such as IEEE 2030.5 to optimize power flows, reduce curtailment, and enable transactive energy markets. Smart meters and grid automation devices capture the dominant share of product-type revenue as utilities modernize aging infrastructure. Demand response solutions and renewable integration applications are expanding fastest, driven by wholesale market reforms that compensate flexible load and distributed generation for grid services.
Regulatory Framework and Outlook
FERC in the United States, the EU Green Deal framework in Europe, and METI in Japan are tightening interoperability standards and carbon accounting rules that determine which connected energy assets qualify for grid services markets. These regulations shape demand by mandating open-API architectures and time-stamped emissions data that favor vendors with certified platforms. Stakeholders must monitor how pending interconnection queue reforms and dynamic tariff structures alter the economic viability behind-the-meter versus front-of-the-meter asset configurations.
Market Dynamics
Grid-edge intelligence is compressing control loops from hours to milliseconds, forcing utilities to rebuild procurement specifications around real-time interoperability rather than hardware durability alone.
Growth Catalysts
- EU Green Deal carbon accounting:Mandatory time-stamped emissions data for grid-connected assets is expanding addressable market for certified energy management platforms in Germany and France.
- Behind-the-meter solar-plus-storage:Residential and commercial building owners in California and Texas are deploying integrated systems that qualify for wholesale market participation under FERC Order 2222.
- Virtual power plant aggregation:Software platforms coordinating distributed batteries and flexible loads are capturing new revenue streams from ancillary services markets in Japan and Australia.
Market Restraints
- Lithium supply concentration:Battery cell production concentrates in China, creating geopolitical exposure for utilities scaling storage procurement across North America and Europe.
- Cybersecurity compliance costs:IEC 62351 standards for substation communication security are adding certification overhead that slows deployment timelines for smaller grid operators.
- Silicon carbide wafer scarcity:Power electronics manufacturers face input bottlenecks for next-generation inverters, constraining supply of high-efficiency grid-tie equipment.
Strategic Opportunities
- India's renewable integration mandate:Central Electricity Authority regulations requiring forecasting and scheduling for solar and wind farms are opening demand for grid-edge control software.
- Building-to-grid bidirectional charging:Convergence of electric vehicle batteries with home energy management systems is creating new transactive energy participation models.
- Industrial heat electrification:Food processing and chemical plants in Germany and the Netherlands are procuring flexible thermal loads that can provide demand response services.
Industry Challenges
- Systems integration engineering scarcity:Utilities and technology vendors compete for talent capable of bridging legacy SCADA protocols with modern API-driven architectures.
- Interconnection queue backlogs:Grid operators in California, Texas, and New York face 3-5 year delays for distributed resource approvals, freezing capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Energy Market |
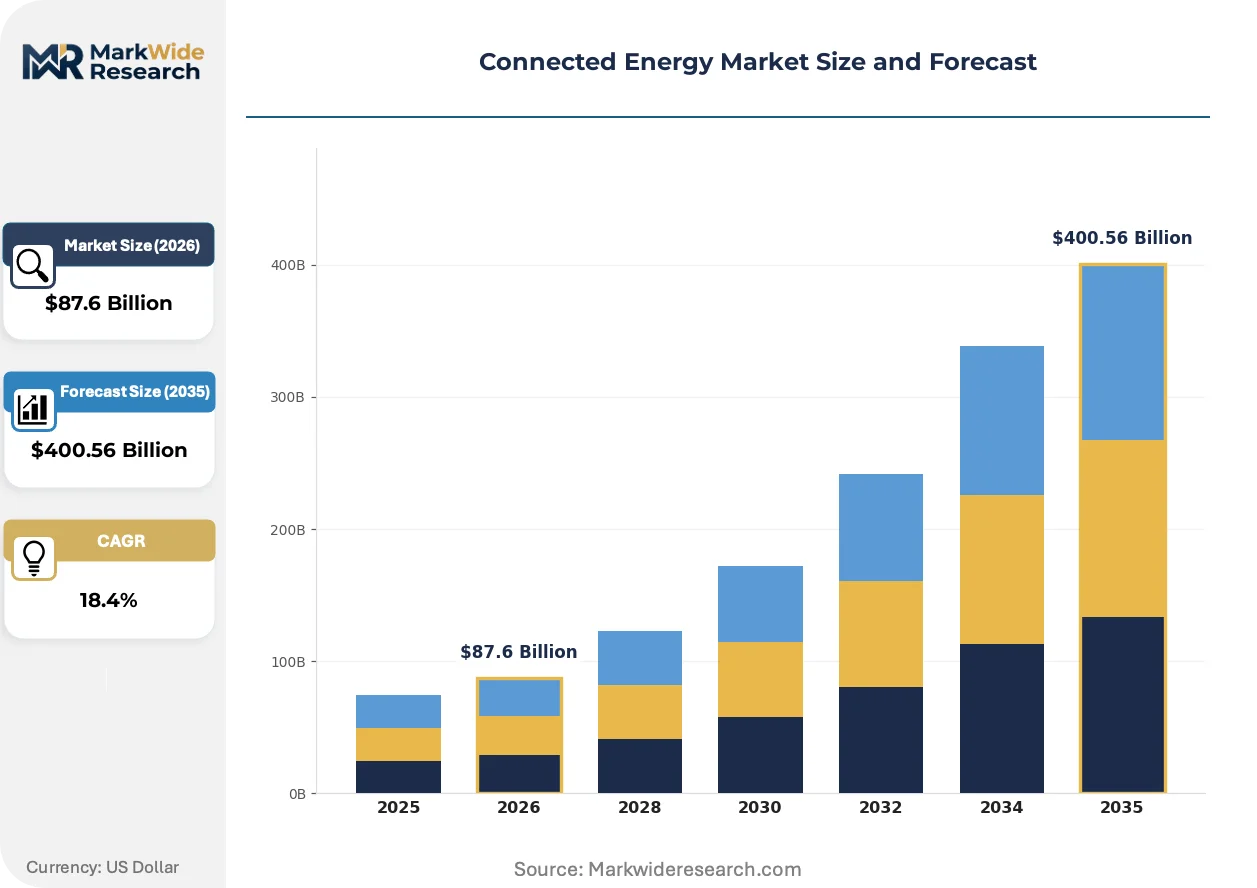
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Energy Management Systems, Demand Response Solutions, Grid Automation Devices End User: Utilities, Industrial Facilities, Residential Consumers, Commercial Buildings Technology: IoT Platforms, Cloud Computing, Data Analytics, Wireless Communication Application: Energy Monitoring, Load Forecasting, Grid Optimization, Renewable Integration |
| Companies Covered | NextEra Energy, Tesla, GE Vernova, Panasonic Holdings Corporation, Siemens Gamesa, Itron, Enphase Energy, Sonnen GmbH, Connected Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Energy Market Emerging Trajectories
Digital twin technology and edge computing are collapsing the distance between physical assets and market signals, enabling sub-second optimization that was technically impossible five years ago.
Solid-state transformer topology is miniaturizing substation footprints while enabling direct medium-voltage connection for distributed solar and storage. European transmission operators in Denmark and the Netherlands are piloting these units for offshore wind integration. The technology is compressing land acquisition requirements and accelerating permitting timelines for urban grid upgrades.
FERC Order 2222 implementation is forcing regional transmission organizations to redesign market rules for aggregated distributed resources. Wholesale operators must now compensate virtual power plants for capacity, energy, and ancillary services on comparable terms with centralized generation. PJM and CAISO are revising their software stacks to accommodate heterogeneous asset fleets with sub-hourly telemetry.
Building owners are unbundling energy performance contracts from equipment procurement, separating hardware capex from ongoing optimization services. Commercial real estate firms in Tokyo and Singapore are engaging specialized software vendors for continuous commissioning rather than one-time efficiency retrofits. This shift compresses vendor sales cycles while expanding recurring revenue pools for analytics providers.
Connected Energy Market Segmentation
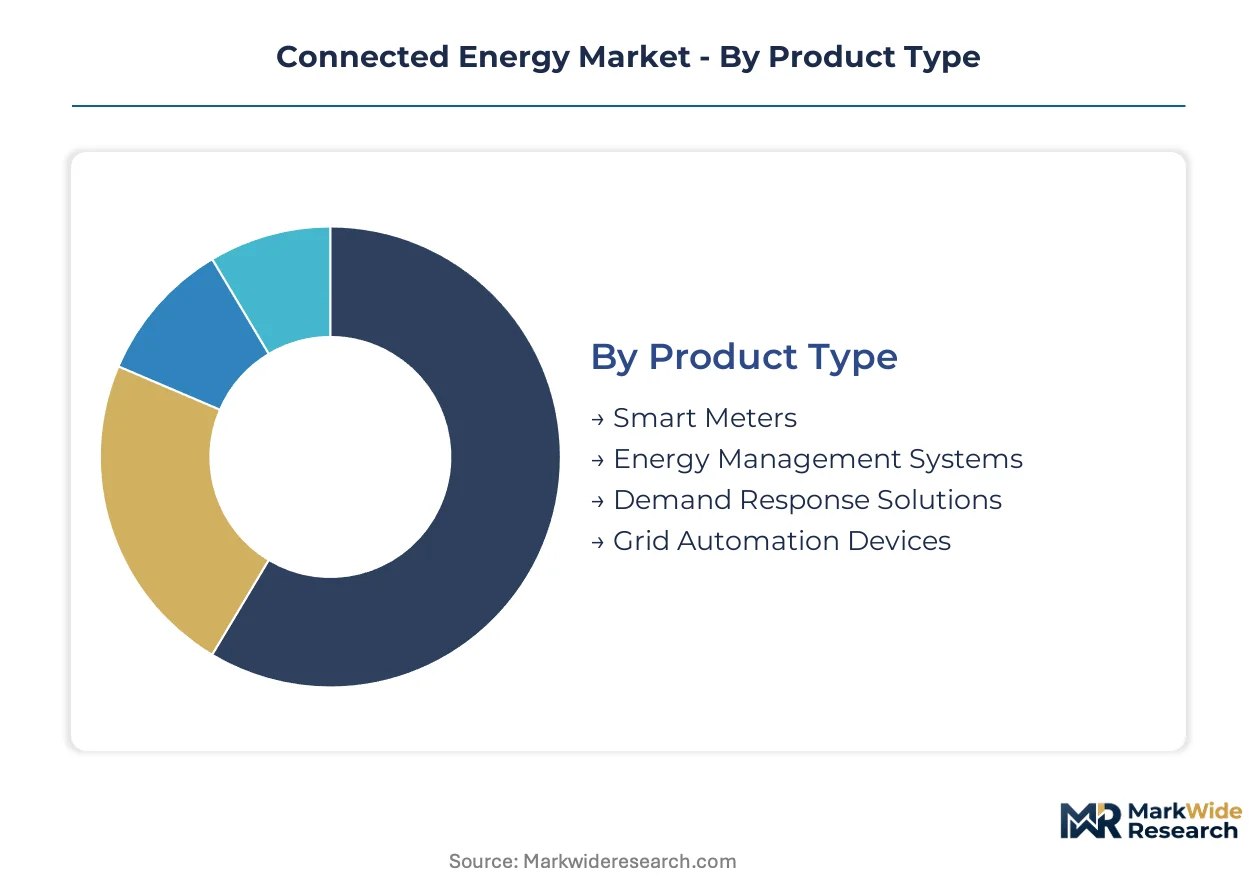
Segmentation in connected energy reveals how procurement priorities diverge between regulated utilities and unregulated commercial operators. Understanding these splits enables vendors to align certification roadmaps with the specific interoperability standards each buyer tier demands.
Product Type:
Smart meters dominate domestic procurement cycles across Germany, Japan, and the United States, while grid automation devices and demand response platforms increasingly serve export-led technology licensing markets.
- Smart Meters:These devices measure real-time consumption and communicate via IEEE 2030.5 protocols to utility back-office systems. Demand concentrates in California, Tokyo, and Bavaria where regulators mandate AMI 2.0 upgrades under decarbonization timelines.
- Grid Automation Devices:Intelligent switches, reclosers, and capacitor controllers that enable self-healing distribution networks. Procurement is accelerating in Texas and New York as utilities rebuild for bi-directional power flows from distributed solar and storage.
- Energy Management Systems:Software platforms integrating building-level controls with wholesale market signals.
- Demand Response Solutions:Aggregated load curtailment systems qualifying for ancillary services compensation under FERC Order 2222.
Smart meters hold the largest share; momentum sits with grid automation devices.
End User:
Cost tier separation runs deepest between capital-constrained residential consumers and institutional buyers with dedicated sustainability procurement budgets.
- Utilities:Vertically integrated and deregulated power providers modernizing transmission and distribution infrastructure. Investment focuses in Germany and Japan on substation automation and virtual power plant aggregation platforms.
- Commercial Buildings:Office and retail property owners in Tokyo and Singapore unbundling energy performance contracts from equipment procurement. These buyers prioritize continuous commissioning services over one-time efficiency retrofits.
- Industrial Facilities:Food processing and chemical plants procuring flexible thermal loads for demand response participation.
- Residential Consumers:Homeowners deploying behind-the-meter solar-plus-storage systems enabled by California and Texas market reforms.
Utilities command the highest contract values; commercial buildings are climbing the fastest as service models displace hardware-centric sales.
Technology:
Application intensity separates edge-deployed wireless stacks from centralized cloud architectures serving forecasting and market optimization workloads.
- IoT Platforms:Device connectivity middleware enabling telemetry from distributed sensors and actuators. Deployment concentrates in grid-edge control systems across Denmark and the Netherlands where offshore wind integration demands sub-second response.
- Data Analytics:Predictive algorithms for load forecasting, asset health monitoring, and transactive energy pricing. Demand is steepest in India where Central Electricity Authority regulations mandate forecasting and scheduling for renewable farms.
- Cloud Computing:Scalable compute infrastructure for virtual power plant orchestration and wholesale market participation.
- Wireless Communication:Cellular, mesh, and proprietary RF protocols connecting field devices to control centers.
IoT platforms anchor current deployment volumes; data analytics is gaining share fastest as forecasting mandates proliferate.
Application:
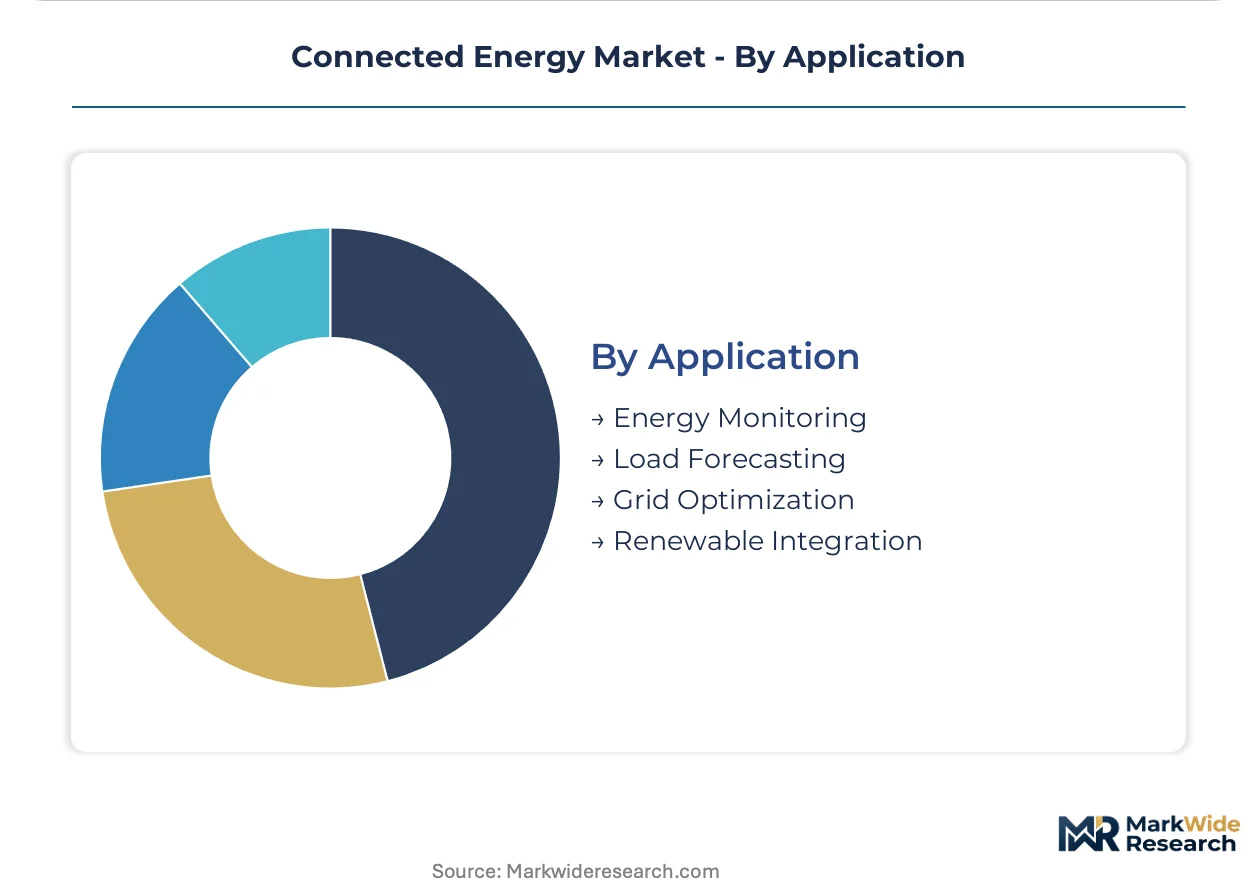
Customer type stratification shows grid operators prioritizing stability applications while commercial and industrial buyers favor cost-reduction and sustainability tracking tools.
- Grid Optimization:Real-time power flow management reducing congestion and curtailment. Implementation is accelerating in California and Texas where interconnection queue backlogs force maximal utilization of existing infrastructure.
- Renewable Integration:Forecasting, scheduling, and control systems for variable solar and wind generation. European transmission operators in Denmark and the Netherlands are piloting solid-state transformer topologies for direct medium-voltage connection.
- Energy Monitoring:Consumption visibility and carbon accounting for compliance and efficiency tracking.
- Load Forecasting:Predictive models for demand planning and procurement optimization.
Grid optimization captures the largest installed base; renewable integration shows the steepest expansion trajectory as decarbonization mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration varies sharply by buyer archetype. Utilities in Germany, Japan, and the United States drive grid-scale automation contracts. Commercial building operators in Tokyo and Singapore prioritize continuous commissioning services over hardware capex. Residential solar-plus-storage adoption clusters in California and Texas where market reforms enable wholesale participation.
United States
Behind-the-meter solar-plus-storage deployment accelerates in California and Texas as FERC Order 2222 enables aggregated distributed resources to compete in wholesale markets. PJM and CAISO are rebuilding software stacks to accommodate heterogeneous asset fleets with sub-hourly telemetry. The Pacific Northwest sees growing utility procurement of grid automation devices for bi-directional power flow management.
Germany
Industrial heat electrification in food processing and chemical plants creates demand for flexible thermal loads providing demand response services. The EU Green Deal's mandatory time-stamped emissions data expands addressable market for certified energy management platforms. Bavaria anchors utility-scale battery storage deployment under tightening decarbonization mandates for grid modernization.
Japan
METI regulations are tightening interoperability standards for distributed energy resources qualifying for grid services markets. Virtual power plant aggregation platforms capture new revenue streams from ancillary services markets in the Kanto region around Tokyo. Kansai utilities prioritize substation automation and forecasting systems for variable renewable integration.
India
Central Electricity Authority regulations mandating forecasting and scheduling for solar and wind farms open demand for grid-edge control software. Data analytics for load forecasting shows steepest demand growth as renewable mandates proliferate. Karnataka and Gujarat industrial clusters drive procurement of energy management systems for compliance and efficiency tracking.
Netherlands
European transmission operators pilot solid-state transformer topologies for direct medium-voltage connection of offshore wind. The technology compresses land acquisition requirements and accelerates permitting timelines for urban grid upgrades. Randstad metropolitan utilities deploy IoT platforms for sub-second response in grid-edge control systems.
Connected Energy Market Vendor Landscape
Player mix skews toward integrated technology conglomerates with hardware-software hybrid offerings. Consolidation pressure intensifies as utilities rebuild procurement specifications around real-time interoperability rather than hardware durability alone. Two strategic archetypes dominate: vertically integrated energy majors combining generation, storage, and software ecosystems; and specialized grid automation vendors with certified platform architectures. Competitive moves concentrate on strategic partnerships for systems integration capability and portfolio diversification into behind-the-meter segments.
Within the integrated ecosystem tier, Tesla leverages its solar-storage-software stack to sustain pricing power across residential and utility segments. GE Vernova anchors large-scale grid automation deployments through its hardware-software hybrid offerings, representing the industrial conglomerate archetype with deep utility relationships. Siemens Gamesa occupies a position combining wind turbine connectivity with grid-edge control systems, exemplifying renewable integration specialists. These three companies sit within distinct competitive vectors—residential ecosystem penetration, utility-scale automation, and renewable generation integration—rather than direct head-to-head competition.
| Leading Market Players |
|---|
| NextEra Energy |
| Tesla |
| GE Vernova |
| Panasonic Holdings Corporation |
| Siemens Gamesa |
| Itron |
| Enphase Energy |
| Sonnen GmbH |
| Connected Energy |
| Others |
Supply Flow & Price Mechanics
ISO 50001 energy management certification gates both supplier qualification and price differentiation simultaneously, separating certified platform vendors from commodity hardware providers in utility procurement cycles across Germany, Japan, and California.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate utility-scale battery procurement, insulating vendors from raw material volatility while passing through semiconductor cost escalations. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels tracks directly to IEC 62351 cybersecurity certification status. Pricing pressure stems from silicon carbide wafer scarcity constraining high-efficiency inverter supply. Commercial building operators in Tokyo and Singapore exhibit lowest price sensitivity, prioritizing continuous commissioning service bundles over hardware capex minimization.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Long Beach port congestion inflate landed costs for European and North American grid automation deployments, compressing margins on time-sensitive substation upgrade timelines. Battery cell production concentrates in China, South Korea, and Japan, drawing from lithium spodumene feedstock anchored in Australia and Chile. Single-source vulnerability runs through Chinese cathode active material supply. Distribution runs through authorized systems integrators with FERC Order 2222 compliance certification, bypassing direct utility sales for complex aggregation platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Systems integration engineering scarcity—specifically talent bridging legacy SCADA protocols with modern API-driven architectures—constrains deployment velocity and inflates implementation costs across utility and commercial segments.
For Market Incumbents: Secure certified platform architectures under tightening EU Green Deal and METI interoperability mandates before smaller competitors achieve compliance. Deepen backward integration into power electronics manufacturing to mitigate silicon carbide wafer scarcity exposure. Acquire specialized grid-edge software vendors to fill API-driven architecture capability gaps threatening large-scale automation contract capture.
For New Entrants and Emerging Players: Behind-the-meter solar-plus-storage aggregation software in Texas and California represents the most penetrable white-space target, where FERC Order 2222 market reforms outpace incumbent platform adaptation. Industrial heat electrification in German chemical and food processing plants offers second-tier entry with lower competitive density. Pursue continuous commissioning service models rather than hardware-centric sales to bypass capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across virtual power plant software sub-segments as recurring revenue models displace project-based engineering. Five-to-ten year viability favors vertically integrated energy majors with captive storage supply and software ecosystems over pure-play hardware vendors. Monitor interconnection queue reform progress in California, Texas, and New York as the critical inflection signal for distributed resource deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid Automation Certification Program | IEC 62351 compliance unlocks utility procurement contracts in Germany and Japan. |
| Virtual Power Plant Platform Integration | FERC Order 2222 qualification enables CAISO and PJM wholesale market participation. |
| Silicon Carbide Supply Agreement | Long-term wafer commitments secure high-efficiency inverter production capacity. |
| Behind-the-Meter Aggregation Partnership | Residential solar-storage coordination captures California and Texas market reforms. |
| Continuous Commissioning Service Launch | Tokyo and Singapore commercial real estate firms prioritize ongoing optimization over retrofits. |
Methodological Framework
Desk research of FERC interconnection filings, EIA project databases, and EU Green Deal regulatory texts preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Germany, Japan, California, and Texas. Primary fieldwork with systems integration specialists and energy management software vendors was validated against secondary sources including IEA renewable integration reports and METI interoperability guidelines. Bottom-up project pipeline analysis was triangulated with top-down market sizing across product type, end user, technology, and application dimensions.
Variance decomposition across the projection horizon isolates volume drivers (deployment scale, regulatory mandate timing) from value drivers (software content share, service attach rates). Segmentation modeling incorporated product type, end user archetype, technology stack, and application intensity with regional regulatory framework as an overlay dimension. CAGRs were derived from fitted adoption curves calibrated to historical deployment trajectories and policy implementation schedules. Forecast inputs included interconnection queue processing rates, battery cost learning curves, and cybersecurity certification adoption timelines.
Forecasts assume regulatory continuity in FERC Order 2222 implementation, EU Green Deal carbon accounting mandates, and METI interoperability standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Global Energy Consumption Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Industrial Energy Management System Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Energy Harvesting System Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Energy Security Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Microgrid Control System Market
Energy Management
Energy ESO Market
Energy Management
Smart Energy Solutions Market