
 New Zealand Solar Energy Market | 2026-2036
New Zealand Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Solar Energy Market Foresight
Commercial establishment demand is consolidating as the fastest-expanding end-user category in New Zealand's solar landscape. Meridian Energy leverages its generation portfolio to bundle solar offerings with retail electricity contracts. Contact Energy competes through grid-scale solar development paired with firming capacity. Tesla differentiates via integrated battery storage systems that address New Zealand's winter peak demand patterns.
New Zealand solar energy encompasses photovoltaic systems that convert sunlight into direct current electricity through silicon-based cells, typically operating at 15-22% conversion efficiency depending on panel technology, then conditioning it through inverters for grid or off-grid use. Photovoltaic panels dominate product type revenue due to declining module costs and improved performance ratios in temperate maritime climates. Rooftop installations lead installation type deployment in urban centers where land scarcity elevates distributed generation economics. Energy storage systems represent the fastest-growing product segment as battery pairing addresses New Zealand's hydro-thermal generation mix and dry-year risk.
The Electricity Authority governs distribution pricing and grid connection standards that determine solar export economics for residential and commercial generators. EECA (Energy Efficiency and Conservation Authority) administers grants and technical standards that shape system sizing and equipment eligibility across installation categories. The RMA (Resource Management Act) consenting framework influences ground-mounted project timelines and land-use trade-offs. Stakeholders must monitor how the ongoing RMA reform and potential distribution network investment plans reshape locational value for distributed solar assets.
Market Dynamics
Distribution pricing reforms by the Electricity Authority are restructuring export economics for distributed generators across New Zealand's solar landscape. These changes compress payback periods for commercial arrays while forcing network operators to recalibrate connection standards and capacity allocation frameworks.
Growth Catalysts
- EECA grant programs:Direct capital subsidies for commercial and industrial installations reduce upfront system costs and accelerate deployment timelines for dairy processing and irrigation applications.
- Dry-year hydro risk:New Zealand's hydro-thermal generation mix creates seasonal price volatility that solar-plus-storage configurations hedge effectively for energy-intensive rural operations.
- Canterbury irrigated farmland:Concentrated electricity demand from center-pivot irrigation systems drives ground-mounted array development with favorable land availability and grid access profiles.
Market Restraints
- Silicon module supply concentration:Import dependency on East Asian photovoltaic manufacturing creates exposure to shipping cost fluctuations and trade policy shifts.
- RMA consenting timelines:Resource Management Act processes for ground-mounted projects introduce 12-24 month approval delays that compress developer returns and deter institutional capital.
- Winter generation trough:Temperate maritime climate limits December-July irradiance to 2-3 equivalent peak sun hours, constraining annual capacity factors below 15% for unpaired systems.
Strategic Opportunities
- South Island alpine regions:High-altitude installations above 800 meters capture enhanced solar resource with reduced atmospheric attenuation and snow albedo effects.
- Agrivoltaic configurations:Dual-use land models combining sheep grazing with elevated panel arrays unlock marginal pastureland for generation without displacing agricultural output.
- Transpower grid investment plans:Proposed transmission upgrades to renewable zones create locational value for utility-scale solar development with firming capacity co-location.
Industry Challenges
- Certified installer pipeline:Electrical Workers Registration Board licensing requirements and specialized solar competency gaps constrain workforce scaling to match deployment targets.
- Legacy meter infrastructure:Distribution networks in regional areas lack smart metering penetration that enables time-of-use export pricing and dynamic demand response integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Solar Energy Market |
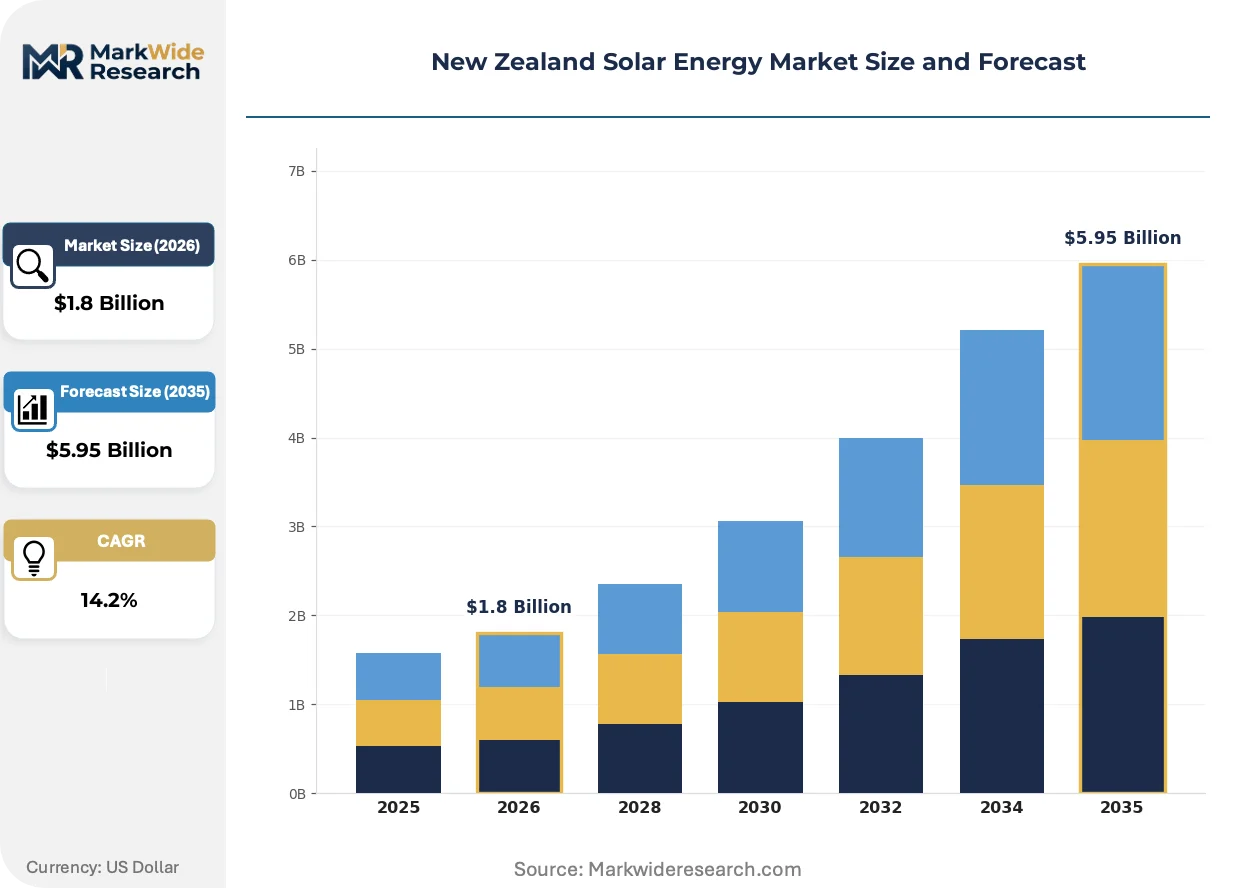
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Mounting Systems, Energy Storage Systems End User: Residential Users, Commercial Establishments, Industrial Facilities, Government Entities Installation Type: Rooftop Installations, Ground-mounted Systems, Off-grid Solutions, Hybrid Setups Service Type: Consulting Services, Installation Services, Maintenance Services, Financing Options |
| Companies Covered | Sungrow, Meridian Energy, Contact Energy, Tesla, Elecnor, Harmony Energy, Lightsource bp, OurEnergy, Clarus (First Renewables), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Solar Energy Market Shifts & Advancements
Bifacial module technology and agrivoltaic system designs are altering land-use economics for New Zealand's solar developers. These innovations expand deployable site categories while reshaping competitive positioning between rooftop and ground-mounted segments.
Bifacial photovoltaic panels capture reflected irradiance from ground surfaces and ambient light from rear-side cells, lifting energy yield 8-20% over monofacial equivalents in high-albedo environments. Canterbury dairy operations with concrete feedpads and light-colored gravel are adopting these modules at accelerating rates. This technology is expanding into previously marginal sites where single-sided economics failed to clear hurdle rates.
The Electricity Authority's distribution pricing methodology review is revising how network costs allocate between energy and capacity components. Industrial solar generators face revised export tariffs that reward peak-shaving behavior over volumetric energy sales. Auckland commercial precincts are responding with battery-paired systems sized to minimize demand charges rather than maximize annual generation.
Corporate power purchase agreements are displacing traditional retail contracting for large energy users. Fonterra processing facilities and irrigation cooperatives are negotiating 10-15 year solar supply contracts with developers who retain asset ownership and operational risk. This shift concentrates in Canterbury and Waikato where load profiles align with solar generation patterns and land access permits ground-mounted development at scale.
New Zealand Solar Energy Market Segmentation
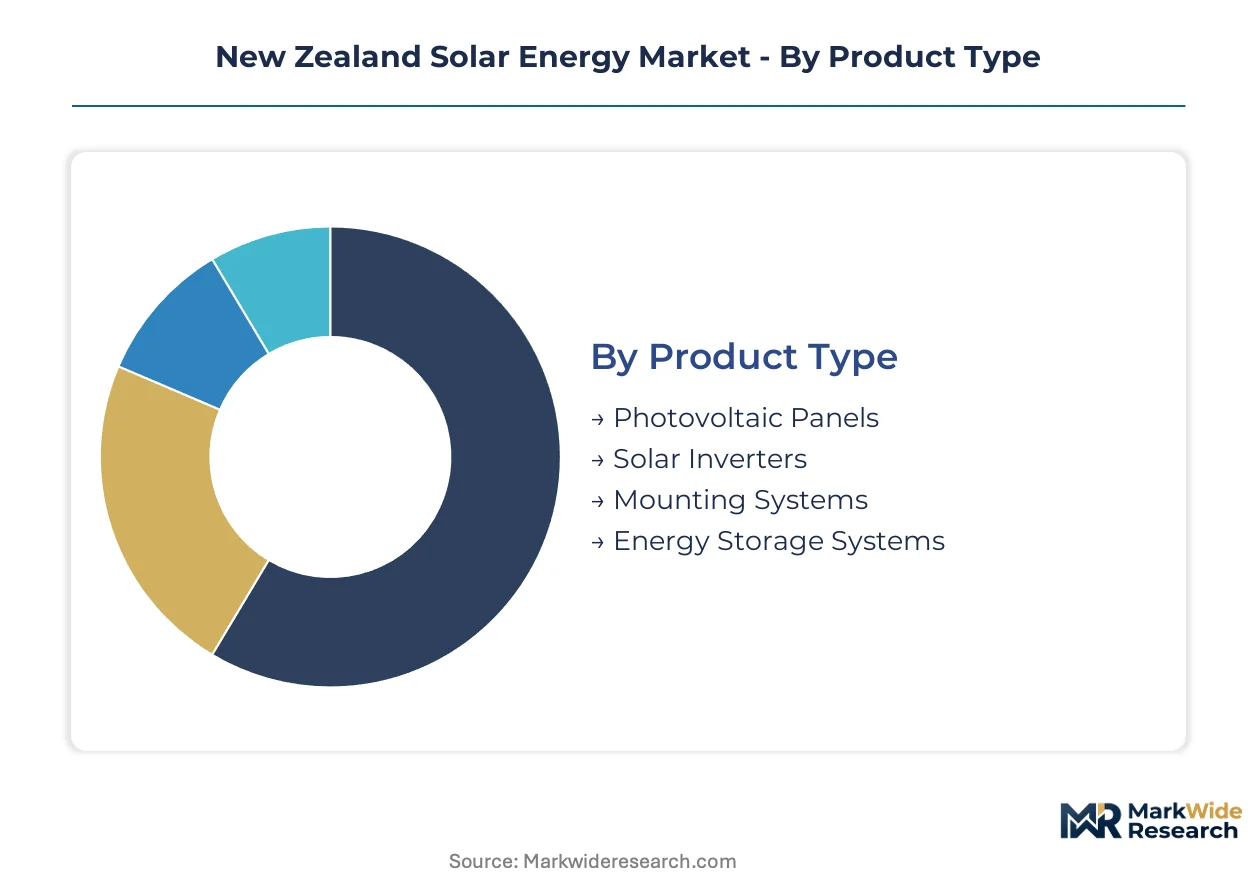
New Zealand's solar market segments reveal how technology specifications, installation constraints, and customer economics interact. Understanding these divisions illuminates why photovoltaic panels dominate hardware revenue while energy storage systems capture accelerating investment.
Product Type:
Silicon cell efficiency ratings and inverter topology specifications determine system performance across New Zealand's temperate maritime climate zones.
- Photovoltaic Panels:Monocrystalline and polycrystalline silicon cells convert sunlight at 15-22% efficiency, with bifacial modules gaining traction in Canterbury dairy operations where concrete feedpads provide high albedo reflection. Auckland commercial rooftops specify these for space-constrained deployments where wattage density drives returns.
- Energy Storage Systems:Lithium-ion battery configurations paired with solar arrays address dry-year hydro risk and winter peak demand patterns. Canterbury irrigated farmland and Waikato processing facilities are deploying these systems to hedge seasonal price volatility from the hydro-thermal generation mix.
- Solar Inverters:String and central inverter architectures condition DC output for grid synchronization, with power electronics manufacturers targeting export tariff optimization under Electricity Authority distribution pricing reforms.
- Mounting Systems:Fixed-tilt and tracking structures anchor panels to rooftops or ground arrays, with elevated agrivoltaic designs enabling dual-use sheep grazing in South Island pastoral regions.
Mature deployment sits with Photovoltaic Panels. Newer deployment is concentrated in Energy Storage Systems.
End User:
Load profile characteristics and capital access differentiate customer economics across installation scales.
- Commercial Establishments:Auckland office precincts and retail centers deploy rooftop arrays to offset demand charges under revised distribution pricing methodologies. Battery pairing optimizes for peak-shaving rather than volumetric generation.
- Industrial Facilities:Fonterra processing plants and irrigation cooperatives negotiate corporate power purchase agreements spanning 10-15 years. Canterbury and Waikato concentrate this activity where load profiles align with solar generation patterns.
- Residential Users:Grid-tied rooftop systems dominate urban centers, with EECA grant programs reducing upfront capital barriers for household installations.
- Government Entities:Public building portfolios and infrastructure projects specify solar under procurement frameworks administered by EECA technical standards.
Established deployment centers on Industrial Facilities. Expanding most quickly are Commercial Establishments responding to export tariff restructuring.
Installation Type:
Land availability and grid proximity shape site selection economics across New Zealand's varied topography.
- Rooftop Installations:Distributed generation dominates Auckland, Wellington, and Christchurch urban cores where land scarcity elevates building-integrated economics. Commercial precincts favor these for accelerated permitting relative to ground-mounted alternatives.
- Ground-mounted Systems:Canterbury irrigated farmland hosts utility-scale arrays serving center-pivot irrigation loads with favorable grid access and land availability profiles. RMA consenting timelines of 12-24 months constrain developer returns.
- Off-grid Solutions:Remote rural properties and alpine stations deploy standalone systems where distribution network extension proves uneconomic.
- Hybrid Setups:Grid-connected configurations with battery backup address winter generation troughs and dry-year supply security for critical operations.
Volume concentrates in Rooftop Installations. Steepest expansion trajectory belongs to Ground-mounted Systems as agrivoltaic designs unlock marginal pastureland.
Service Type:
Value chain participation ranges from technical advisory through asset lifecycle management.
- Installation Services:Electrical Workers Registration Board licensing requirements constrain certified installer pipeline scaling. Specialized solar competency gaps limit workforce expansion to match deployment targets.
- Maintenance Services:Performance ratio optimization and inverter replacement contracts extend asset operating life for commercial and industrial generators.
- Consulting Services:System sizing, grid connection navigation, and EECA grant application support guide developers through regulatory complexity.
- Financing Options:Power purchase agreements and lease structures transfer capital burden from end-users to project developers retaining operational risk.
Revenue concentrates in Installation Services. Gaining share fastest are Financing Options as corporate PPA structures displace direct ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland's commercial precincts function as the primary tax-incentive concentration zone, with distribution pricing reforms compressing payback periods for rooftop arrays across the metropolitan area.
Auckland Metropolitan Area
Office towers and retail centers drive distributed generation deployment, with the Electricity Authority's export tariff restructuring rewarding peak-shaving behavior. EECA grant programs reduce upfront capital barriers for commercial installations. The central business district concentrates battery-paired systems sized to minimize demand charges under revised network pricing methodologies.
Canterbury Region
Dairy processing facilities and center-pivot irrigation systems anchor ground-mounted array development across the plains. The Resource Management Act consenting framework governs project timelines for utility-scale installations. Christchurch and surrounding farmland host corporate power purchase agreements spanning 10-15 years for Fonterra processing plants.
Waikato Region
Irrigation cooperatives and agricultural processors negotiate long-term solar supply contracts with developers retaining asset ownership. EECA technical standards shape system sizing and equipment eligibility for rural industrial applications. Hamilton and the surrounding dairy belt concentrate agrivoltaic configurations combining sheep grazing with elevated panel arrays.
Wellington Region
Government building portfolios and public infrastructure projects specify solar under procurement frameworks administered by national agencies. The Electricity Authority governs grid connection standards that determine export economics for distributed generators. The capital city and nearby urban centers favor rooftop installations where land scarcity elevates building-integrated economics.
New Zealand Solar Energy Market Competitive Landscape
Top-tier vendors anchor generation and retail integration, while mid-tier specialists concentrate on installation services and project development. The competitive structure reflects a bifurcation between vertically integrated energy retailers and technology-focused equipment suppliers. Three archetypes dominate: utility-backed solar developers, independent power producers, and integrated storage system providers. Capacity expansion through corporate power purchase agreements and strategic partnerships for grid-scale development represent the dominant competitive moves reshaping market positioning.
Within the utility-backed developer tier, Meridian Energy and Contact Energy exemplify generation portfolio leverage to bundle solar offerings with retail electricity contracts. Tesla occupies a position representing integrated battery storage systems that address winter peak demand patterns. These three companies anchor the competitive landscape through distinct strategic positioning around retail integration, grid-scale development, and storage pairing respectively.
| Leading Market Players |
|---|
| Sungrow |
| Meridian Energy |
| Contact Energy |
| Tesla |
| Elecnor |
| Harmony Energy |
| Lightsource bp |
| OurEnergy |
| Clarus (First Renewables) |
| Others |
Supply & Pricing Matrix
EECA technical standards certification gates both qualified installer supply and premium-tier pricing access for commercial solar arrays, compressing margins for uncertified competitors while rewarding compliant providers with tariff optimization opportunities under Electricity Authority distribution pricing reforms.
Pricing Analysis
Short lead-time premiums for certified installation crews command pricing advantages during Canterbury irrigation season peaks, while spot inventory of polysilicon modules trades at discounts. Project-based contracting dominates, with price differentiation driven by EECA grant eligibility tier and Meridian Energy retail bundling. Pricing pressure stems from silicon module import cost volatility. Residential users show highest price sensitivity; Fonterra processing facilities demonstrate lowest due to corporate PPA structures.
Supply Chain Analysis
Warehouse-distribution layers concentrate through Auckland and Christchurch regional hubs serving North and South Island demand clusters respectively. Manufacturing concentrates in China, Vietnam, and Malaysia for silicon cells and module assembly. Raw material dependencies span polysilicon feedstock, lithium carbonate, and aluminum framing. Single-source vulnerability to East Asian shipping chokepoints elevates inventory carrying costs. Distribution runs through EPC contractor networks with Electrical Workers Registration Board certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as RMA consenting timeline compression forces undercapitalized developers toward acquisition or exit.
For Market Incumbents: Acquire ground-mounted project development pipelines in Canterbury and Waikato to secure land-access positions ahead of Transpower grid investment completion. Contact Energy and Meridian Energy should deepen backward integration into battery storage assembly to counter Tesla's integrated system positioning. EPC contractor certification capacity represents the critical bottleneck constraining deployment scaling. For New Entrants and Emerging Players: Mid-scale commercial establishments in Wellington government precincts present underserved buyer concentration with standardized procurement frameworks and accelerated permitting relative to ground-mounted alternatives. Agrivoltaic configurations in South Island alpine regions offer penetrable white-space with dual-use land economics. Go-to-market through EECA grant application advisory services builds relationship access ahead of equipment specification. For Investors and Strategic Acquirers: Corporate PPA announcement velocity for Fonterra and irrigation cooperatives is the leading indicator that utility-scale solar development economics have crossed institutional return thresholds. Five-to-ten year viability favors developers with locked land positions and firming capacity co-location rights. Watch for Electricity Authority distribution pricing methodology finalization as the signal for battery-paired system investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Corporate PPA Structuring | Long-term offtake contracts with Fonterra processing facilities transfer operational risk to developers while securing financing. |
| Battery Storage Integration | Lithium-ion pairing addresses dry-year hydro risk and winter peak demand patterns for Canterbury irrigation loads. |
| Agrivoltaic Development | Elevated panel arrays with sheep grazing unlock marginal South Island pastureland without agricultural displacement. |
| EECA Certification Investment | Technical standards compliance grants access to capital subsidies and premium export tariff optimization. |
| Transpower Grid Co-location | Transmission upgrade alignment creates locational value for utility-scale solar with firming capacity pairing. |
Research Methodology
Multi-period observation of EECA grant disbursement patterns, Electricity Authority tariff filing timelines, and Transpower grid investment announcements anchored the trend analysis, supplemented by interviews with IPP project developers, EPC contractors, utility planning officers, and dairy cooperative energy managers. Secondary validation drew from EECA technical standards documentation, Electricity Authority distribution pricing determinations, RMA consenting databases, and customs import records for photovoltaic modules. Bottom-up project pipeline tracking triangulated against top-down generation capacity modeling.
Segment-weighting across product type, end user, installation type, and service type dimensions shaped volume allocation, with regional clustering by grid zone and irradiance profile. CAGRs derived from installation cost trajectory modeling and export tariff restructuring impact assessment. Forecast inputs incorporated dry-year hydro probability distributions and RMA reform legislative timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon module supply chain disruptions and RMA consenting process reforms. Outputs reflect documented assumptions regarding EECA grant continuity and Transpower transmission upgrade sequencing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Photovoltaic Mounting System Market