
 Airport Charging Stations Market | 2026-2036
Airport Charging Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Charging Stations Market Analysis
Project finance and operational leasing for charging infrastructure is tilting competitive dynamics toward asset-light providers that avoid heavy balance-sheet exposure. ABB Ltd. leverages its power electronics heritage to dominate high-reliability fast charge installations at tier-one aviation hubs. ChargePoint Inc. sustains its position through software-integrated payment platforms that reduce airport operator complexity. Siemens AG anchors European deployment with modular hardware architectures that simplify retrofit projects in aging terminals.
Airport charging stations are electromechanical systems that convert grid or battery-stored electricity into standardized DC or AC outputs for passenger electronic devices, typically operating at 5V to 20V with USB-C Power Delivery or Qi wireless protocols up to 15W, designed to maintain continuous service under high-cyclical passenger loads. Fast charge units command the dominant share of capital allocation as travelers prioritize speed over convenience during brief layovers. Integrated kiosks represent the fastest-expanding installation category because they bundle advertising revenue, wayfinding, and retail touchpoints into a single footprint. Mobile payments are displacing cash and card interfaces across new deployments, concentrating margin pools with platform providers that capture transaction data.
The FAA mandates electrical safety compliance under National Electrical Code standards for all passenger-facing infrastructure in US commercial airports, while the EU AI Act and GDPR impose data-handling requirements on biometric payment authentication at charging kiosks. ECHA REACH restrictions on hazardous substances in electronics manufacturing are elevating material costs for enclosure and cable assemblies. Stakeholders must weigh payment platform interoperability against evolving cybersecurity mandates as passenger data flows through airport networks intensify.
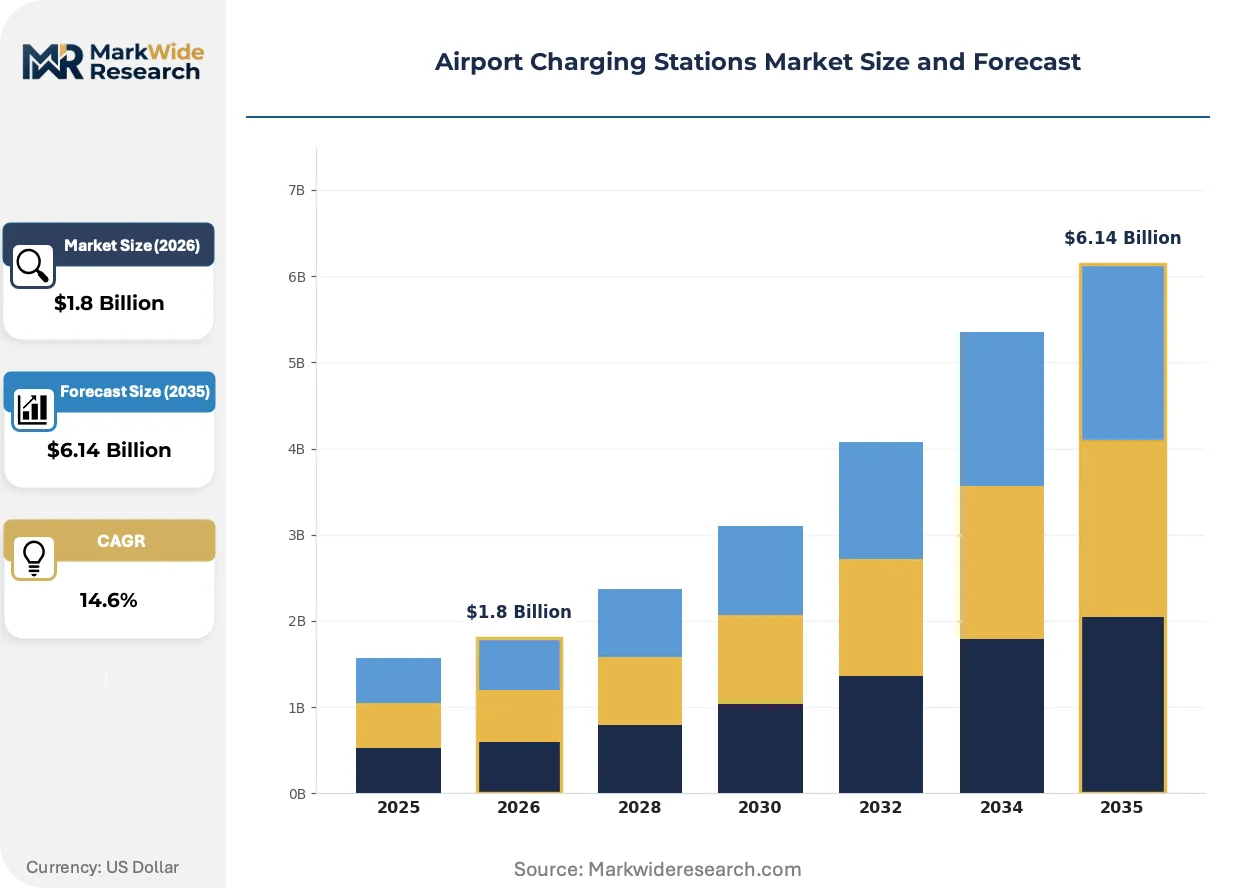
Market Dynamics
Passenger dwell-time compression at hub airports is forcing terminal operators to prioritize speed over amenity density, redirecting capital toward fast-charge infrastructure that minimizes gate congestion while maximizing per-square-foot revenue capture.
Growth Catalysts
- EU Green Deal infrastructure mandates:The F-Gas Regulation and associated decarbonization frameworks require energy-efficient terminal upgrades, embedding charging stations into mandatory retrofit programs at major aviation hubs.
- Business traveler device dependency:Corporate road warriors now carry 3-4 chargeable devices per trip, creating baseline demand that justifies premium fast-charge deployment in business lounges and gate areas.
- Qi wireless protocol maturation:Inductive charging pads eliminate cable wear failures and reduce maintenance calls, improving uptime metrics that determine operator contract renewals.
Market Restraints
- ECHA REACH substance restrictions:Hazardous material limits on flame-retardant enclosures and cable jacketing elevate unit production costs while extending supplier qualification timelines.
- Power electronics supply concentration:Gallium nitride semiconductors for high-efficiency conversion remain concentrated among Asian foundries, exposing deployment schedules to single-source fragility.
- Biometric payment authentication friction:GDPR and EU AI Act data-handling requirements complicate kiosk deployments that capture passenger identity for transaction processing.
Strategic Opportunities
- Retrofit-ready modular architectures:Aging terminals in Germany and France require non-disruptive installation paths, rewarding hardware designs that minimize electrical infrastructure rework.
- Advertising-integrated kiosk formats:Digital display bundling transforms charging hardware into media revenue platforms, capturing marketing budgets from airport retail concessionaires.
- Mobile payment platform convergence:Software providers that unify QR, NFC, and app-based settlement capture transaction data streams valuable to terminal commercial planning teams.
Industry Challenges
- Cybersecurity certification complexity:Payment Card Industry Data Security Standard compliance for passenger-facing terminals demands specialized engineering talent scarce in airport facilities departments.
- Legacy electrical infrastructure incompatibility:Pre-1990 terminal buildings often lack dedicated circuits for high-amperage fast-charge banks, forcing expensive electrical room expansions.
- Interoperability standard fragmentation:Competing fast-charge protocols create inventory complexity for operators managing mixed-device passenger populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Charging Stations Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Chargers, USB Charging Stations, Fast Charge Units, Portable Chargers Installation Type: Wall-mounted, Standalone, Integrated Kiosks, Modular Solutions Payment Method: Cash, Credit/Debit Cards, Mobile Payments, Subscription Services End User: Business Travelers, Leisure Travelers, Airport Operators, Airlines |
| Companies Covered | Delta Electronics, Inc., EVBox Group, ChargePoint Inc., Eaton Corporation plc, Webasto Group, ABB Ltd., Blink Charging Co., Schneider Electric, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Charging Stations Market Emerging Trajectories
Terminal electrification is converging with passenger data monetization, transforming charging infrastructure from passive utility into active revenue architecture that captures behavioral insights while delivering power.
GaN-based power conversion is hybridizing traditional silicon designs in next-generation fast-charge cabinets. Tier-one hub operators in Germany and the United Arab Emirates are piloting these systems to reduce thermal footprint and enable denser kiosk placement. The technology is compressing electrical room requirements by forty percent versus legacy installations, freeing premium terminal real estate for retail expansion.
The EU AI Act biometric governance framework is restructuring payment authentication architectures at charging kiosks. Operators must now segment data processing between edge devices and cloud infrastructure to comply with GDPR purpose-limitation requirements. European deployments are responding by adopting tokenized transaction systems that minimize raw biometric retention.
Airline lounge procurement teams are consolidating charging infrastructure under single-source facilities management contracts. This displaces fragmented vendor relationships where individual concessionaires sourced standalone units. The shift is most visible in Frankfurt and Munich, where Fraport and Munich Airport have centralized hardware procurement through integrated terminal service agreements.
Airport Charging Stations Market Segmentation
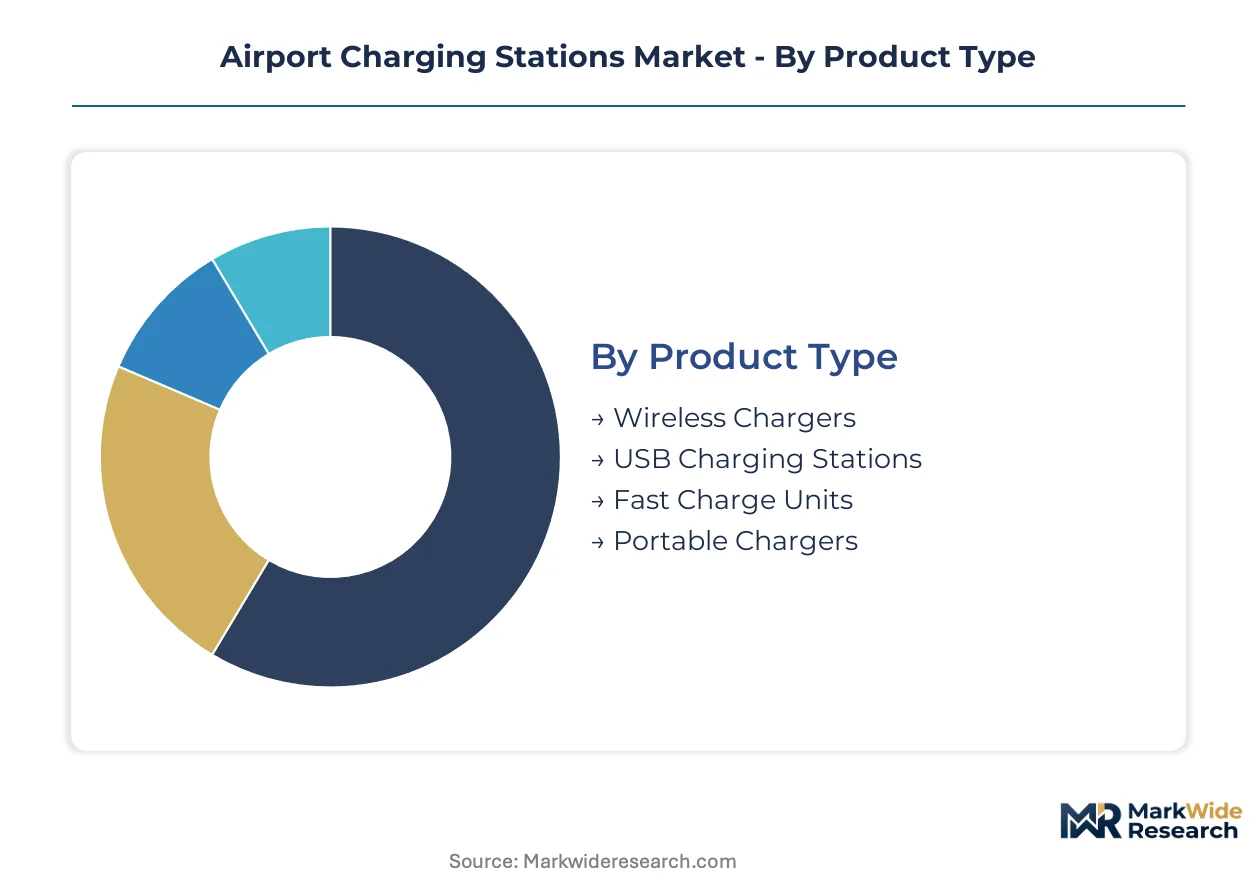
Segmentation in airport charging stations reveals how hardware specifications, installation constraints, and user payment preferences fragment procurement decisions across terminal operators. Each dimension carries distinct margin profiles and regulatory touchpoints that reshape competitive positioning.
Product Type:
Cost tier stratification separates commodity USB hardware from premium fast-charge and wireless systems that command higher per-unit margins.
- Wireless Chargers:Qi-standard inductive pads eliminate cable wear failures and reduce maintenance call volumes by removing mechanical connection points. Deployment concentrates in Germany's Frankfurt and Munich hub expansions where Fraport and Munich Airport prioritize uptime metrics in lounge and gate seating areas. EU Green Deal efficiency mandates favor these units for their lower standby power draw versus active-cable alternatives.
- Fast Charge Units:GaN-semiconductor cabinets deliver 60W-100W USB-C Power Delivery outputs that compress charging cycles for business travelers facing compressed dwell times. Demand clusters at tier-one aviation hubs in the United Arab Emirates and Germany where gate congestion pressures force speed-optimized infrastructure investments. These units dominate capital allocation despite gallium nitride supply concentration risks among Asian foundries.
- USB Charging Stations:Standard 5V-12V multi-port banks serve baseline passenger needs in budget terminals and secondary gates.
- Portable Chargers:Rental locker systems with retrieval kiosks address emergency demand spikes during flight delays.
Fast Charge Units hold installed capacity. Wireless Chargers is rotating up the share rankings.
Installation Type:
Application context determines whether charging infrastructure integrates with existing terminal architecture or demands greenfield electrical work.
- Integrated Kiosks:Combined power delivery, digital advertising displays, and wayfinding touchpoints transform charging hardware into media revenue platforms. These bundles capture marketing budgets from airport retail concessionaires while reducing per-function footprint requirements. Deployment accelerates in aging European terminals where retrofit constraints favor consolidated infrastructure.
- Modular Solutions:Plug-and-play electrical architectures minimize disruption during installation in pre-1990 terminal buildings lacking dedicated high-amperage circuits. German and French operators prioritize these designs to avoid expensive electrical room expansions while meeting EU F-Gas Regulation retrofit timelines.
- Wall-mounted:Fixed-position units anchor gate seating areas and corridor waypoints with minimal floor space consumption.
- Standalone:Pedestal-format towers serve open concourse zones and temporary terminal extensions without structural mounting requirements.
Wall-mounted retains volume concentration. Integrated Kiosks expands most quickly as advertising revenue integration deepens.
Payment Method:
Customer transaction preferences are fragmenting across generational and geographic lines, forcing operators to maintain multi-modal settlement infrastructure.
- Mobile Payments:QR code, NFC tap-to-pay, and app-based settlement capture transaction data streams valuable to terminal commercial planning teams. GDPR and EU AI Act requirements complicate biometric authentication deployments, pushing European operators toward tokenized systems that minimize raw identity retention. These platforms concentrate margin pools with software providers.
- Credit/Debit Cards:EMV chip and contactless card interfaces remain essential for international passenger populations with limited mobile wallet adoption. PCI DSS compliance demands specialized engineering talent scarce in airport facilities departments, elevating total cost of ownership.
- Cash:Coin and bill acceptors persist in emerging market terminals and low-cost carrier gates serving unbanked passenger segments.
- Subscription Services:Airline lounge membership and frequent flyer program bundling shifts payment upstream to annual contracts.
Credit/Debit Cards maintains transaction volume leadership. Mobile Payments climbs the fastest as passenger data monetization intensifies.
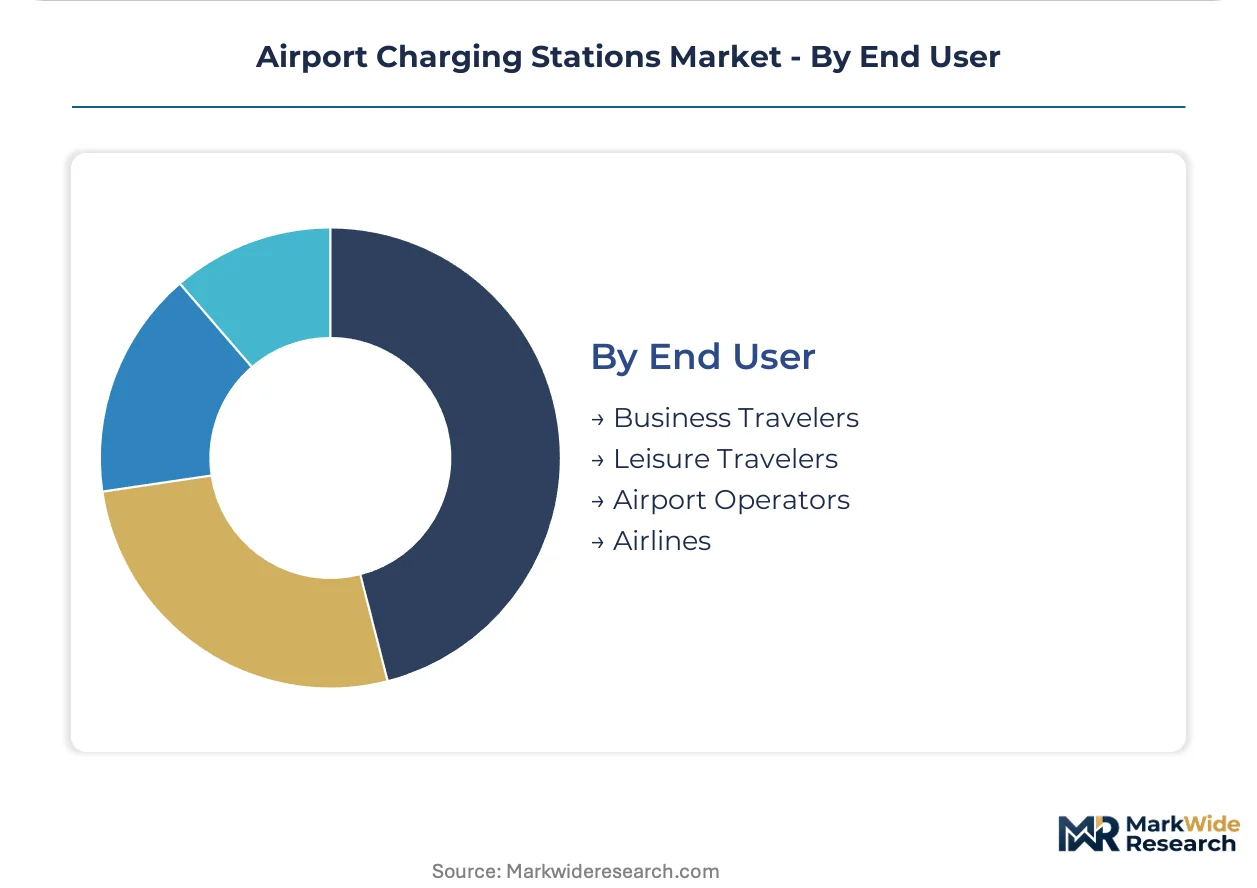
End User:
Volume concentration and margin sensitivity diverge sharply between passenger-facing and operator-procurement segments.
- Business Travelers:Corporate road warriors carrying 3-4 chargeable devices per trip create inelastic demand that justifies premium fast-charge deployment in business lounges and priority gate areas. Their time-compressed itineraries prioritize speed over cost, enabling operators to capture higher per-use revenue.
- Airport Operators:Terminal management entities consolidate charging infrastructure under single-source facilities management contracts that displace fragmented vendor relationships. This procurement shift is most visible in Germany where Fraport and Munich Airport have centralized hardware sourcing through integrated terminal service agreements.
- Leisure Travelers:Price-sensitive passengers with flexible dwell times accept slower charge speeds and shared access points.
- Airlines:Carrier-specific lounge procurement teams specify branded charging hardware aligned with passenger experience strategies.
Airport Operators hold procurement volume. Business Travelers is gaining share fastest as device dependency deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are accelerating terminal electrification across major aviation hubs, embedding charging infrastructure into mandatory energy-efficiency retrofit programs. Germany anchors European deployment through hub expansions at Frankfurt and Munich, while the United States, United Arab Emirates, China, and Japan concentrate procurement through tier-one airport operators prioritizing fast-charge speed over amenity density.
Germany
Fraport and Munich Airport are consolidating charging hardware procurement under single-source facilities management contracts that displace fragmented vendor relationships. The F-Gas Regulation mandates energy-efficient terminal upgrades, embedding Qi wireless and GaN-based fast-charge units into mandatory retrofit timelines. Frankfurt's Terminal 3 expansion and Munich's satellite terminal projects are deploying integrated kiosks that bundle advertising revenue with power delivery.
United States
The FAA mandates electrical safety compliance under National Electrical Code standards for all passenger-facing infrastructure in commercial airports. Business travelers carrying multiple chargeable devices per trip create inelastic demand justifying premium fast-charge deployment in priority gate areas. Atlanta Hartsfield-Jackson and Dallas-Fort Worth are piloting GaN-semiconductor cabinets to compress electrical room requirements and free retail real estate.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International are prioritizing speed-optimized infrastructure investments to minimize gate congestion during compressed dwell times. The country's central aviation regulator enforces stringent electrical safety standards for passenger-facing terminal systems. Dubai's Terminal 3 and the new Midfield Terminal are deploying advertising-integrated kiosks that capture marketing budgets from airport retail concessionaires.
China
Beijing Capital and Shanghai Pudong are retrofitting aging terminals with modular plug-and-play architectures that minimize disruption during installation. The Ministry of Industry and Information Technology oversees standards for power electronics and wireless charging protocols in public infrastructure. Guangzhou Baiyun's terminal expansion is concentrating procurement through state-owned airport operators centralizing hardware sourcing under integrated service agreements.
Japan
Tokyo Haneda and Narita International are consolidating charging infrastructure under airline lounge procurement teams specifying branded hardware aligned with passenger experience strategies. The Ministry of Economy, Trade and Industry governs technical standards for inductive charging and power conversion efficiency in public facilities. Osaka Kansai's terminal renovation is deploying tokenized transaction systems to comply with data-handling requirements while minimizing raw biometric retention.
Airport Charging Stations Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement tiers, with tier-one aviation hubs consolidating vendor relationships under single-source facilities management contracts. The vendor base fragments between asset-light platform providers and integrated hardware manufacturers, creating a tiered structure where scale advantages concentrate with established power electronics heritage. Three archetypes dominate: GaN-semiconductor specialists, software-integrated payment platform providers, and modular hardware architects. M&A activity targets payment platform interoperability capabilities, while strategic partnerships focus on retrofit-ready electrical architectures for aging terminal infrastructure.
Among European-headquartered industrial conglomerates, ABB Ltd., Siemens AG, and Schneider Electric exemplify the integrated hardware-manufacturer archetype, leveraging power electronics heritage and modular system architectures to anchor deployment at tier-one hubs. ChargePoint Inc. represents the software-platform specialist model, occupying a position where payment-integrated systems reduce airport operator complexity. Delta Electronics, Inc. and EVBox Group sit within the fast-charge technology tier, with Eaton Corporation plc and Webasto Group anchoring the industrial power-systems segment. Blink Charging Co. exemplifies the asset-light service provider archetype competing on operational leasing structures that avoid heavy balance-sheet exposure.
| Leading Market Players |
|---|
| Delta Electronics, Inc. |
| EVBox Group |
| ChargePoint Inc. |
| Eaton Corporation plc |
| Webasto Group |
| ABB Ltd. |
| Blink Charging Co. |
| Schneider Electric |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Undercapacity in gallium nitride semiconductor foundries across Taiwan and South Korea is tightening supply availability for fast-charge cabinet manufacturers while simultaneously elevating input costs that cascade through tier-one aviation hub procurement contracts.
Pricing Analysis
Certification level creates the primary spread across the product spectrum, with UL-listed and CE-marked fast-charge units commanding substantial premiums over uncertified commodity USB hardware. Three-tier pricing structure across premium, standard, and economy levels reflects this divergence, where GaN-based 100W cabinets with full regulatory documentation capture margins far above basic 5V multi-port banks. Cost compression in the standard tier is intensifying because REACH-compliant flame-retardant enclosures and cable assemblies carry elevated material expenses. Airport operators with single-source facilities management contracts exhibit the lowest price sensitivity, while budget terminal procurement teams in secondary markets remain highly elastic to unit cost fluctuations.
Supply Chain Analysis
Export control regimes restricting gallium nitride wafer technology flows from the United States and Japan to Chinese power electronics manufacturers are fragmenting procurement routes for high-efficiency conversion components. Taiwan, South Korea, and China anchor global GaN semiconductor fabrication, while Germany and the United States concentrate precision enclosure manufacturing and power systems integration. The supply chain draws from specialized gallium nitride substrates, flame-retardant polymer compounds, and EMV-certified payment modules as critical inputs. Single-source vulnerability around Asian foundry capacity exposes deployment schedules to disruption. Distribution runs through direct terminal service agreements with hub operators, displacing fragmented concessionaires.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent for PCI DSS-compliant payment terminal design remains scarce across airport facilities departments, creating a persistent capability gap that rewards vendors with pre-certified platform architectures.
For Market Incumbents: Pre-empt consolidation of procurement relationships by anchoring integrated terminal service agreements before competitors establish facilities management contracts at expanding hubs like Frankfurt Terminal 3 and Munich's satellite terminal. Defend against modular retrofit specialists by deepening backward integration into REACH-compliant cable assembly production, securing supply continuity as ECHA substance restrictions tighten. Certification investment in tokenized biometric payment systems offers channel control leverage as GDPR and EU AI Act requirements harden. For New Entrants and Emerging Players: Pursue white-space deployment in aging French terminals requiring non-disruptive electrical architectures, where legacy infrastructure incompatibility blocks incumbent fast-charge cabinets. Target advertising-integrated kiosk formats as the most penetrable segment, capturing media revenue budgets from airport retail concessionaires seeking consolidated footprint solutions. A software-first go-to-market angle with mobile payment platform convergence minimizes hardware capital requirements while concentrating data monetization margins. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-services play because terminal electrification mandates under EU Green Deal frameworks embed recurring retrofit demand across the European aviation network. Acquisition candidates with modular hardware architectures and pre-established Fraport or Munich Airport relationships offer defensive positioning. Watch gallium nitride supply diversification announcements as the inflection signal indicating margin pressure relief or intensification.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Supply Agreement | Secures priority wafer allocation from Taiwan foundries ahead of competitor procurement cycles. |
| REACH-Compliant Material Certification | Unlocks EU terminal retrofit contracts as ECHA restrictions eliminate non-compliant vendors. |
| Tokenized Payment Platform Development | Aligns kiosk authentication with GDPR purpose-limitation and EU AI Act biometric governance. |
| Integrated Terminal Service Contract | Consolidates fragmented vendor relationships under single-source facilities management at Fraport. |
| Advertising Revenue Module Integration | Captures marketing budgets from retail concessionaires while reducing per-function footprint. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airport facilities directors, airline lounge procurement managers, charging hardware engineering leads, and terminal commercial planning teams. Secondary validation drew from FAA electrical safety directives, EU F-Gas Regulation implementation guidance, ECHA REACH substance restriction updates, and SEC filings of publicly traded power electronics manufacturers. Bottom-up unit deployment estimates across Frankfurt, Munich, Dubai, and Atlanta were triangulated against top-down market size calibration.
Calibration against historical deployment velocity at tier-one hubs anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, installation architecture, payment modality, and end-user procurement channel, supplemented by regional regulatory cluster differentiation. CAGRs were derived from installed base expansion trajectories and replacement cycle compression. Forecast inputs incorporated GaN semiconductor supply elasticity and EU Green Deal retrofit timeline acceleration.
Macroeconomic conditions sit as an overlay; deviation in aviation passenger recovery trajectories, semiconductor capital expenditure cycles, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding gallium nitride foundry capacity expansion and REACH compliance cost pass-through. Material shifts in export control regime stringency or biometric data governance interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market