
 Solar Panels for Home Market | 2026-2036
Solar Panels for Home Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panels for Home Market Insights
Silicon wafer sourcing from polysilicon to metallurgical-grade silicon alternatives is shifting cost curves for residential module producers. LONGi leverages captive polysilicon capacity to sustain margin compression across upstream supply chains. Jinko Solar anchors its competitiveness through vertically integrated cell-to-module manufacturing spanning Southeast Asian production bases. Qcells differentiates via PERC and TOPCon R&D intensity concentrated in its Malaysian and South Korean facilities.
Solar panels for home use are photovoltaic modules engineered with crystalline silicon cells or thin-film semiconductor layers, typically rated between 300 and 550 watts per panel, designed to convert sunlight into direct current electricity for on-site residential consumption or grid export. Monocrystalline modules command premium positioning due to higher conversion efficiencies and space-constrained rooftop applications, while bifacial designs capture reflected irradiance and represent the fastest-expanding product category among new residential deployments. Grid-tied technology dominates installed base economics through net metering monetization, though hybrid inverter configurations pairing battery storage are capturing disproportionate interest from homeowners seeking backup power resilience.
The US IRA production tax credits and accelerated depreciation schedules reshape domestic manufacturing location decisions, while EU CE marking and F-Gas Regulation constrain module import specifications and fluorinated gas use in manufacturing processes. China's GB standards and MIIT efficiency benchmarks set minimum performance thresholds for modules entering its distributed generation programs. Stakeholders must monitor evolving interconnection standards and local permitting timelines that determine effective deployment velocity regardless of module cost trajectories.
Market Dynamics
PERC cell technology is displacing conventional aluminum back-surface field designs across residential module production, compressing manufacturing cost curves while elevating minimum efficiency thresholds for competitive positioning.
Growth Catalysts
- Net Metering Policy Evolution:Feed-in tariff structures in Germany and the United States are accelerating suburban rooftop deployment by monetizing surplus generation exports.
- Building Code Amendments:California's Title 24 energy standards mandate solar readiness in new residential construction, embedding photovoltaic infrastructure into housing development pipelines.
- Bifacial Module Technology:Dual-sided cell architectures capture reflected irradiance from residential surfaces, expanding yield per installed square meter in space-constrained applications.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-based polysilicon refining capacity creates geographic single-point vulnerability for crystalline silicon feedstock.
- Interconnection Queue Backlogs:Distribution utility approval timelines in the United States extend project commissioning by 6-18 months regardless of module availability.
- Fluorinated Gas Constraints:EU F-Gas Regulation limits sulfur hexafluoride use in semiconductor manufacturing processes for cell production equipment.
Strategic Opportunities
- Hybrid Inverter-Battery Convergence:Grid-tied systems paired with lithium-ion storage address backup power resilience demand from suburban homeowners.
- Metallurgical-Grade Silicon Alternatives:Upgraded metallurgical silicon purification reduces polysilicon dependency for cost-sensitive module producers.
- Accelerated Depreciation Schedules:US IRA production tax credits reshape domestic manufacturing location decisions toward vertically integrated cell-to-module facilities.
Industry Challenges
- Certification Timeline Compression:IEC 61215 and IEC 61730 testing protocols require 3-6 months for new module variants, delaying product market entry.
- Skilled Installation Labor Scarcity:NABCEP-certified electrician availability constrains deployment velocity in high-growth US metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panels for Home Market |
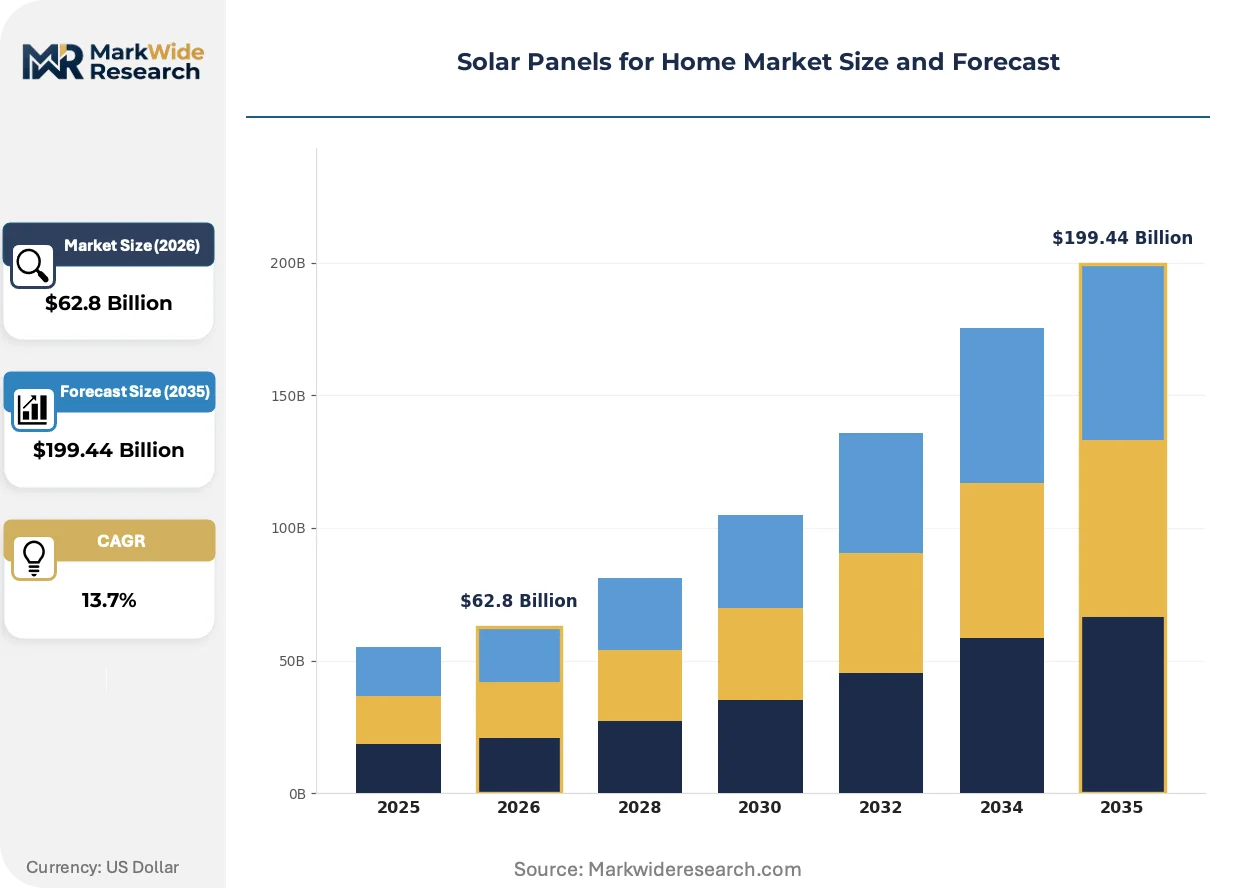
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $199.44 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Installation Type: Roof-mounted, Ground-mounted, Building-integrated, Floating Technology: Grid-tied, Off-grid, Hybrid, Concentrated Solar Power End User: Homeowners, Property Developers, Contractors, Eco-conscious Consumers |
| Companies Covered | Maxeon, REC Group, Canadian Solar, Silfab Solar, Jinko Solar, Qcells, Trina Solar, JA Solar, LONGi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panels for Home Market Trends and Innovations
Cell architecture standardization and inverter topology evolution are compressing system integration complexity while elevating residential performance benchmarks across distributed generation markets.
TOPCon tunnel oxide passivated contact cells are unifying the efficiency gap between monocrystalline and legacy PERC architectures. Premium module manufacturers in South Korea and Malaysia are transitioning production lines to n-type silicon substrates. This unification is collapsing the price premium previously commanded by heterojunction alternatives.
EU F-Gas Regulation amendments are tightening sulfur hexafluoride phase-down schedules for photovoltaic manufacturing equipment. Module producers serving European markets must retrofit cell production lines with fluorinated gas alternatives or face import restriction. Southeast Asian contract manufacturers are accelerating plasma-enhanced chemical vapor deposition equipment upgrades to maintain CE marking eligibility.
Direct-to-installer procurement platforms are consolidating residential module distribution channels. Regional solar contractors in Texas and Florida are bypassing traditional distributor markups through manufacturer-integrated logistics portals. This channel compression is most visible in Sun Belt states where installation volume density supports consolidated freight economics.
Solar Panels for Home Market Segmentation
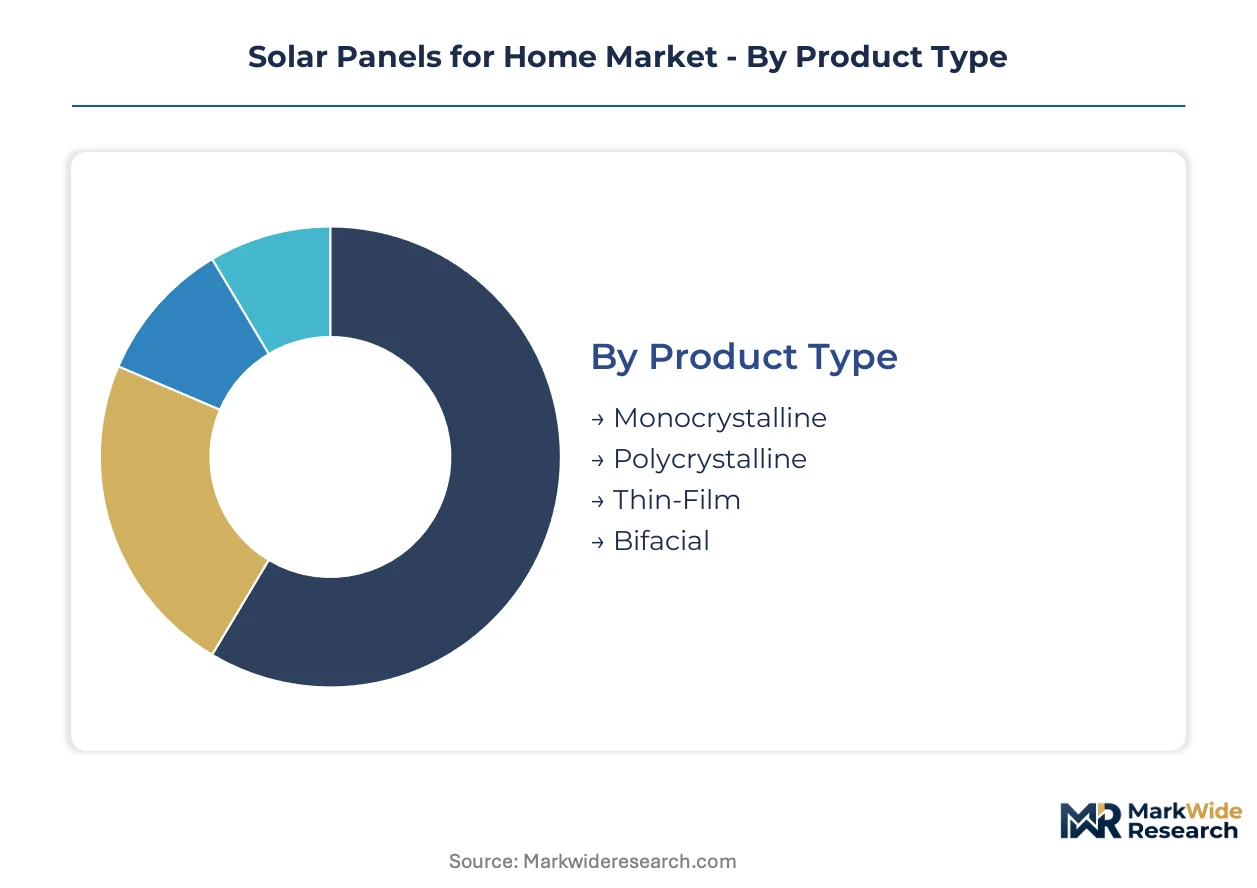
Residential solar segmentation reveals how module specifications, mounting configurations, and system architectures align with distinct homeowner priorities. Each dimension captures a different axis of technology trade-offs between efficiency, cost, and installation complexity.
Product Type:
Monocrystalline modules command premium positioning through superior conversion efficiency, while polycrystalline alternatives serve price-sensitive volume segments.
- Monocrystalline:Silicon ingots sliced from single-crystal boules deliver conversion efficiencies exceeding 20 percent. Space-constrained suburban rooftops in California and Germany drive disproportionate demand for these higher-wattage panels.
- Bifacial:Dual-sided cell architectures capture reflected irradiance from residential surfaces, expanding yield per installed square meter. New construction deployments in Arizona and Texas favor this technology for its enhanced kWh generation density.
- Polycrystalline:Multi-crystal silicon structures offer moderate efficiency at lower per-watt manufacturing cost.
- Thin-Film:Cadmium telluride or CIGS semiconductor layers enable flexible form factors and reduced weight.
Today's leader: Monocrystalline. Tomorrow's challenger: Bifacial.
Installation Type:
Mounting configuration determines structural engineering requirements, permitting pathways, and aesthetic integration with residential architecture.
- Roof-mounted:Rail-based attachment systems dominate suburban retrofit installations, leveraging existing structural capacity. California Title 24 mandates and German feed-in tariff structures accelerate this configuration across single-family housing stock.
- Building-integrated:Photovoltaic tiles and solar shingles replace conventional roofing materials, eliminating separate mounting hardware. Custom home developments in Florida and Colorado increasingly specify these products for aesthetic continuity.
- Ground-mounted:Elevated racking systems serve properties with sufficient land area and suboptimal roof orientation.
- Floating:Pontoon-based arrays address niche applications including residential pond coverage and reservoir-adjacent properties.
Roof-mounted configurations anchor current deployment volumes. Building-integrated products are climbing the fastest as new construction mandates proliferate.
Technology:
System topology choices reflect homeowner priorities across grid independence, backup resilience, and export monetization.
- Grid-tied:Inverter-synchronized systems without battery storage minimize capital outlay while enabling net metering revenue. Texas and Florida contractors concentrate procurement on these configurations where interconnection approval timelines remain manageable.
- Hybrid:Grid-connected architecture paired with lithium-ion storage addresses backup power demand from suburban homeowners facing grid instability. Hurricane-prone markets in the southeastern United States show disproportionate adoption of this technology.
- Off-grid:Battery-dependent systems serve remote properties beyond utility distribution infrastructure.
- Concentrated Solar Power:Parabolic trough or dish concentrator designs remain absent from residential applications due to scale and maintenance requirements.
Grid-tied systems retain volume leadership. Hybrid configurations represent the steepest expansion trajectory as battery cost curves compress.
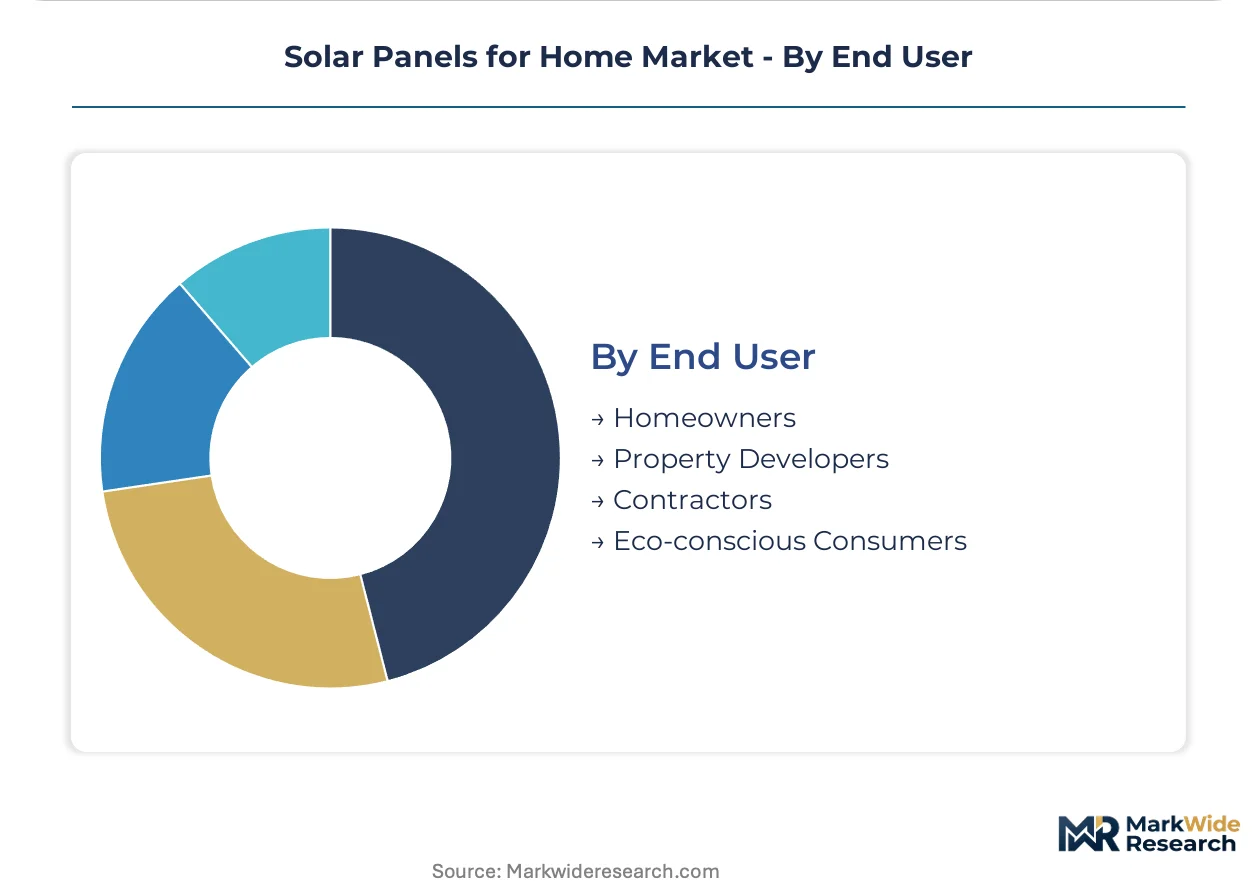
End User:
Customer archetypes span direct homeowners, intermediary developers, and installation professionals with divergent procurement behaviors.
- Homeowners:Direct purchasers evaluate total cost of ownership, warranty terms, and installer reputation. Suburban markets in Arizona and Nevada exhibit strong research-intensive purchasing patterns with extended decision cycles.
- Property Developers:Volume procurement at master-planned community scale prioritizes standardization and supply security. California production builders negotiate direct manufacturer relationships to meet Title 24 compliance deadlines.
- Contractors:Installation professionals select modules based on inventory availability, training requirements, and margin structure.
- Eco-conscious Consumers:Sustainability-motivated buyers prioritize supply chain transparency and embodied carbon metrics.
Homeowners dominate transaction volume. Property developers are gaining share fastest as solar-ready building codes embed photovoltaics into construction pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang polysilicon refining clusters anchor upstream crystalline silicon supply chains for residential module production. Distributed generation deployment concentrates in jurisdictions with net metering frameworks and building code mandates that monetize rooftop generation. Germany, the United States, China, Australia, and India each exhibit distinct regulatory architectures shaping installation velocity.
United States
Suburban homeowners in Arizona and Texas drive retrofit rooftop demand through net metering monetization. The IRA production tax credits and accelerated depreciation schedules reshape domestic manufacturing location decisions toward vertically integrated facilities. California Title 24 energy standards mandate solar readiness in new residential construction across the San Diego and Los Angeles metropolitan clusters.
Germany
Feed-in tariff evolution accelerates single-family rooftop deployment in Bavaria and Baden-Württemberg. The EU F-Gas Regulation constrains sulfur hexafluoride use in cell production equipment serving European markets. Manufacturing R&D intensity concentrates in Thuringia and Saxony-Anhalt where PERC and TOPCon process development occurs.
China
MIIT efficiency benchmarks and GB standards set minimum performance thresholds for modules entering distributed generation programs. Building-integrated photovoltaic mandates in Jiangsu and Zhejiang provinces accelerate solar tile adoption in master-planned communities. Yangtze River Delta production bases anchor cell-to-module manufacturing for domestic and export markets.
Australia
Queensland and New South Wales homeowners exhibit research-intensive purchasing patterns with extended decision cycles around total cost of ownership. The national renewable energy target and state-level feed-in tariffs support suburban deployment economics. Sydney and Melbourne installation contractor networks concentrate procurement through direct-to-installer logistics portals.
India
Gujarat and Rajasthan residential consumers respond to state-level solar rooftop subsidies and net metering frameworks. The CEA technical standards and state electricity regulatory commission interconnection protocols determine project commissioning timelines. Bangalore and Hyderabad metropolitan clusters emerge as distributed generation adoption centers in the southern region.
Solar Panels for Home Market Competitive Landscape
Global majors compete with regional champions across technology licensing and manufacturing scale. The vendor base organizes around three tiers: integrated polysilicon-to-module producers, cell-specialized contract manufacturers, and regional distribution-focused assemblers. Two strategic archetypes dominate competitive positioning: upstream-integrated cost leaders and R&D-intensive premium specialists. Capacity expansion and backward integration into wafer and cell production represent the dominant competitive moves.
Within the integrated cost-leader tier, LONGi and Jinko Solar exemplify upstream-captive supply chain architectures. Qcells occupies a position representing R&D-intensive premium positioning through n-type substrate development. These three anchors illustrate the competitive tension between manufacturing scale economies and technology differentiation in residential module supply.
| Leading Market Players |
|---|
| Maxeon |
| REC Group |
| Canadian Solar |
| Silfab Solar |
| Jinko Solar |
| Qcells |
| Trina Solar |
| JA Solar |
| LONGi |
| Others |
Pricing and Supply Chain Analysis
TOPCon cell architecture migration is compressing manufacturing cost curves while concentrating production among n-type silicon substrate specialists in Malaysia and South Korea. This technology transition simultaneously elevates efficiency benchmarks and tightens supplier qualification requirements, reshaping how module producers negotiate polysilicon offtake terms.
Pricing Analysis
Polysilicon cost pass-through dominates module pricing dynamics, with Xinjiang-sourced metallurgical-grade silicon alternatives creating divergence between premium and standard tiers. Price differentiation separates IEC 61215-certified premium modules from economy-grade polycrystalline alternatives lacking bifacial capability. Cost compression in the standard tier is intensifying because Southeast Asian contract manufacturers are absorbing margin pressure to maintain CE marking eligibility. Property developers exhibit lowest price sensitivity due to Title 24 compliance deadlines, while direct homeowners in Texas and Florida drive procurement through cost-per-watt comparison.
Supply Chain Analysis
CE marking and IEC certification requirements gate module entry into European and North American distribution channels, forcing retrofit investments across Southeast Asian production lines. Geographic supply concentration centers on China, Malaysia, and Vietnam for cell-to-module manufacturing, with South Korea anchoring premium n-type substrate development. Raw material dependencies rest on polysilicon ingots, silver paste for metallization, and aluminum framing extrusions. Single-source vulnerability in Xinjiang polysilicon refining creates geographic concentration risk. Distribution runs through direct-to-installer logistics portals consolidating regional contractor procurement in Sun Belt states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
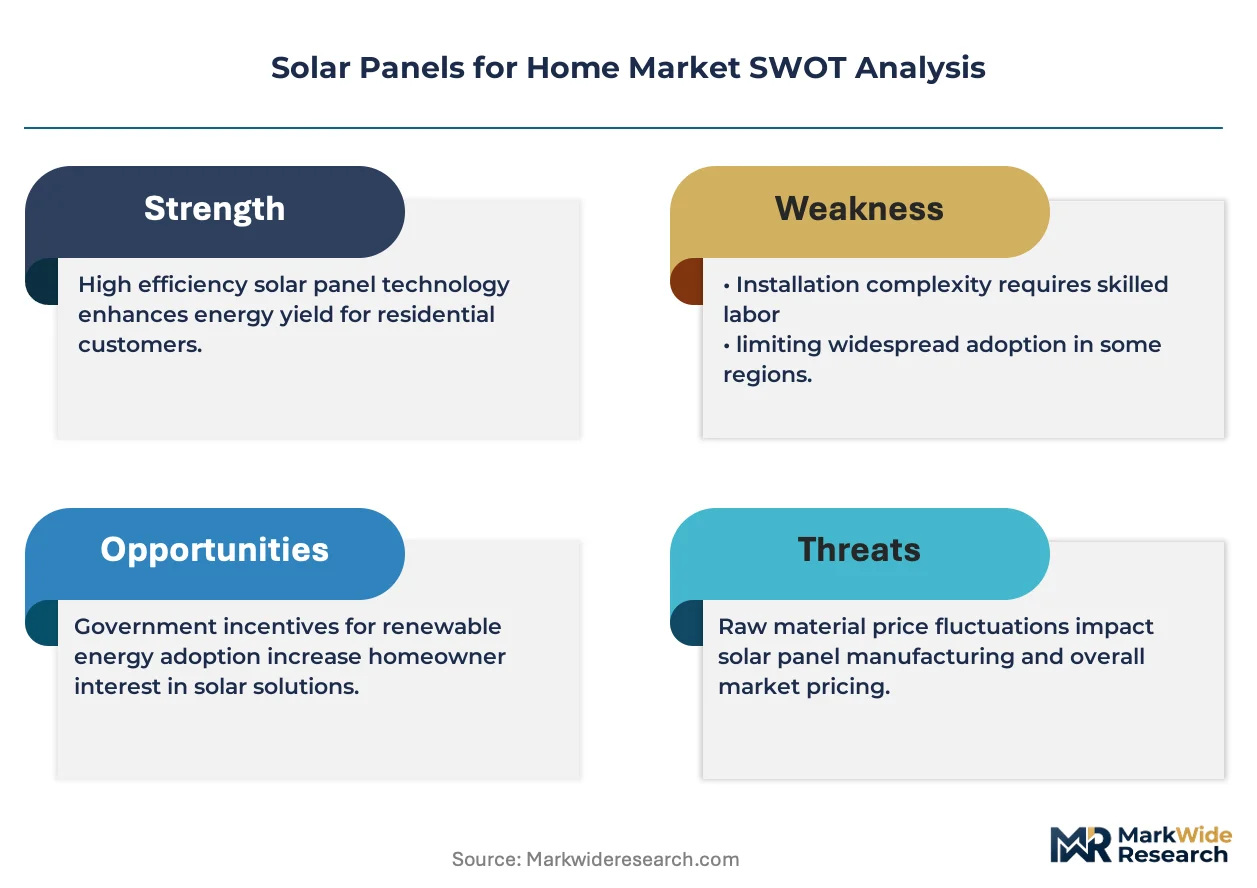
Residential solar module procurement functions as a geographic-arbitrage play, with US IRA production tax credits creating manufacturing cost differentials against EU F-Gas Regulation compliance burdens.
For Market Incumbents: Extend backward integration into captive polysilicon capacity to defend margin position against LONGi's upstream cost leadership. Accelerate TOPCon line conversions in Malaysian facilities before IEC 61730 certification timelines delay product market entry. Lock in NABCEP-certified installer training partnerships to constrain deployment velocity for emerging competitors.
For New Entrants and Emerging Players: Begin with building-integrated photovoltaic tiles targeting Florida and Colorado custom home developments where aesthetic continuity commands premium positioning. Focus initial penetration on solar-ready building code jurisdictions embedding photovoltaics into construction pipelines. Pursue direct manufacturer relationships with California production builders facing Title 24 compliance deadlines.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution-focused assemblers lacking cell production capabilities. Long-term viability favors integrated polysilicon-to-module producers with Southeast Asian manufacturing footprints. Watch for inflection when EU F-Gas Regulation amendments trigger plasma-enhanced chemical vapor deposition equipment upgrade cycles among contract manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive Xinjiang metallurgical-grade silicon supply secures margin resilience against feedstock volatility. |
| TOPCon Line Conversion | N-type substrate production in Malaysian facilities collapses heterojunction price premiums. |
| CE Marking Compliance Investment | F-Gas Regulation retrofit maintains European market access against sulfur hexafluoride phase-down. |
| Direct-to-Installer Platform Launch | Manufacturer-integrated logistics portals bypass distributor markups in Texas and Florida. |
| Hybrid Inverter-Battery Partnership | Grid-tied storage convergence addresses hurricane-prone southeastern US backup power demand. |
Research Methodology
Direct dialogue with module procurement directors, EPC contractors, utility interconnection planners, and NABCEP-certified installation professionals grounded qualitative findings. Secondary validation drew from EIA generation data, IEA renewable energy reports, FERC interconnection filings, and IEC certification databases. Bottom-up and top-down triangulation reconciled project-level deployment velocities with national installation capacity estimates.
Bottom-up modeling segmented residential solar across technology type, installation configuration, system architecture, and end-user archetype. Top-down constraints incorporated IRA production tax credit utilization rates, state-level net metering policy evolution, and building code amendment timelines. CAGRs were derived from regression analysis of historical installation data against regulatory driver indices. Forecast inputs included polysilicon price trajectories and skilled electrician labor availability by metropolitan market.
Several conditions sit outside the modeled scope, including hypothetical federal net metering policy preemption and breakthrough perovskite commercialization timelines. Forecasts reflect assumptions around interconnection queue processing rates and tariff continuity. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or MIIT efficiency benchmark revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Greece Solar Energy Market