
 Portugal Distributed Solar Energy Market | 2026-2036
Portugal Distributed Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Distributed Solar Energy Market Analytics
Portuguese module assembly lines is broadening output for distributed project pipelines. EDP leverages its utility-scale procurement muscle to secure panel supply for smaller commercial installations. Iberdrola anchors its southern European portfolio with distributed assets clustered near transmission substations. Sunaitec specializes in integrated inverter-storage packages that reduce soft costs for agricultural end users.
Distributed solar energy denotes photovoltaic systems generating electricity at or near the point of consumption, typically ranging from kilowatt-scale residential arrays to multi-megawatt commercial rooftops with string inverters or power optimizers. These installations reduce transmission losses and defer grid upgrade expenditures while serving baseload displacement or peak-shaving functions for host consumers. Photovoltaic technology dominates installed capacity due to silicon module cost declines and standardized mounting hardware. Roof-mounted systems capture margin pools in urban zones where land scarcity inflates ground-mounted alternatives. Agricultural applications represent the fastest-growing application segment as irrigation loads and cold-chain facilities seek tariff hedges against volatile wholesale electricity prices.
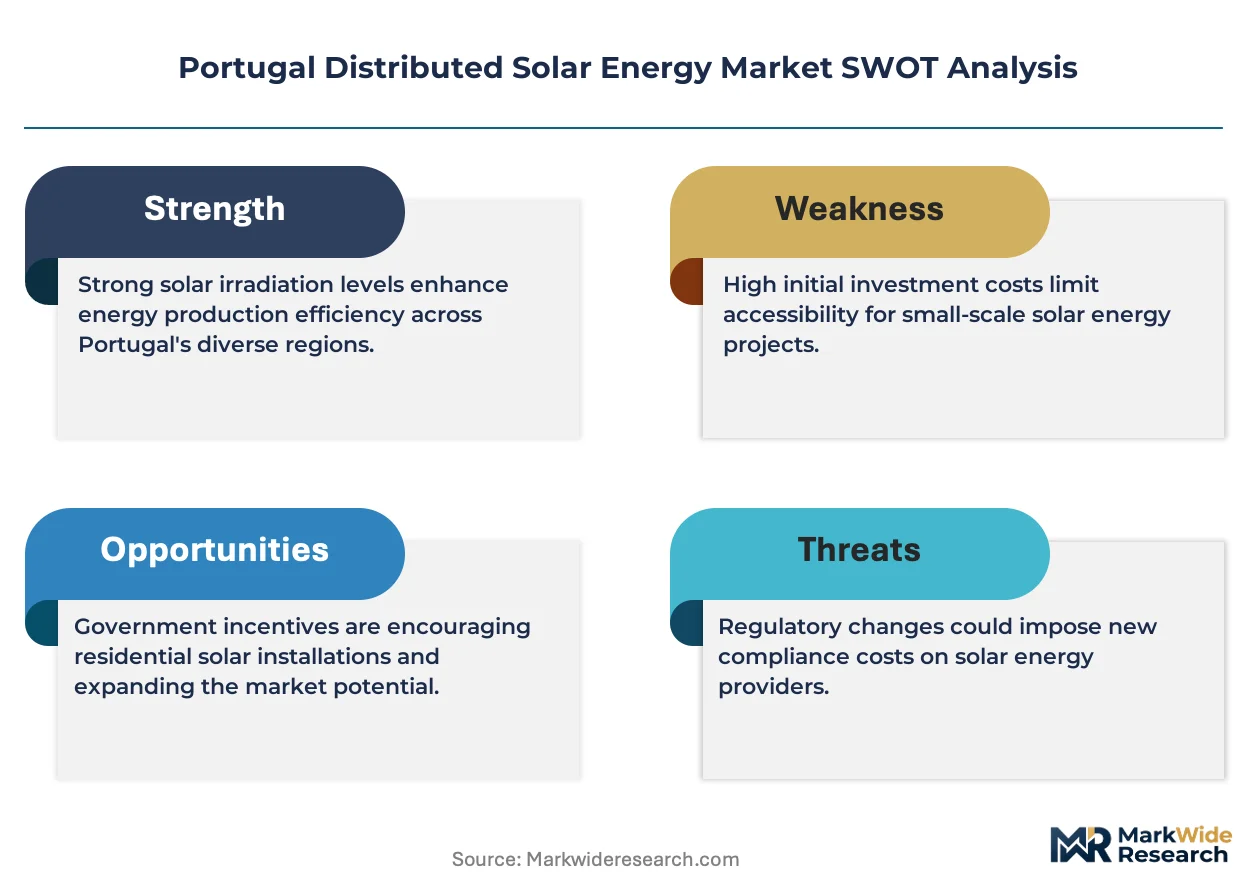
Portugal's Direção Geral de Energia e Geologia administers licensing timelines for self-consumption projects under the Decreto-Lei n.º 162/2019 framework, while Banco de Portugal supervises green credit lines that reduce weighted average cost of capital for cooperative ownership structures. EU Green Deal national recovery allocations channel structural funds toward municipal rooftop programs, tightening local installer capacity during peak construction seasons. Stakeholders must track interconnection queue reforms and storage co-location mandates as the next regulatory inflection points shaping project economics.
Market Dynamics
Grid congestion across Portugal's Lisbon metropolitan corridor is forcing commercial consumers toward behind-the-meter solar installations that bypass transmission bottlenecks entirely. This structural pressure reconfigures project economics around self-consumption optimization rather than export revenue.
Growth Catalysts
- Decreto-Lei n.º 162/2019:Portugal's self-consumption framework enables net metering without feed-in tariffs, eliminating administrative complexity that previously stalled commercial adoption.
- Agro-industrial irrigation loads:Alentejo region farms deploy rooftop arrays to hedge volatile wholesale electricity prices driving cold-chain and pumping operations.
- EU Green Deal structural funds:National recovery allocations channel capital toward municipal rooftop programs, tightening installer capacity during peak construction seasons.
Market Restraints
- Silicon module supply concentration:Portuguese developers remain exposed to Asian polysilicon volatility that disrupts project commissioning timelines.
- Direção Geral de Energia e Geologia licensing:Administrative processing creates 6-12 month queues for commercial interconnection approvals.
- Grid upgrade deferral limits:Distribution network capacity constraints cap behind-the-meter expansion in saturated Lisbon suburbs.
Strategic Opportunities
- Storage co-location mandates:Anticipated regulatory requirements for inverter-storage integration create premium service margins for technical specialists.
- Cooperative ownership structures:Banco de Portugal green credit lines reduce weighted average cost of capital for community solar aggregations.
- Alentejo agricultural cold-chain:Underpenetrated processing facilities represent untapped demand for tariff-hedged solar plus storage configurations.
Industry Challenges
- Certified electrician scarcity:Peak construction seasons expose insufficient trained workforce for string inverter commissioning across distributed commercial sites.
- Legacy meter integration:Bi-directional smart meter deployment lags behind self-consumption project registrations, creating billing reconciliation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Distributed Solar Energy Market |
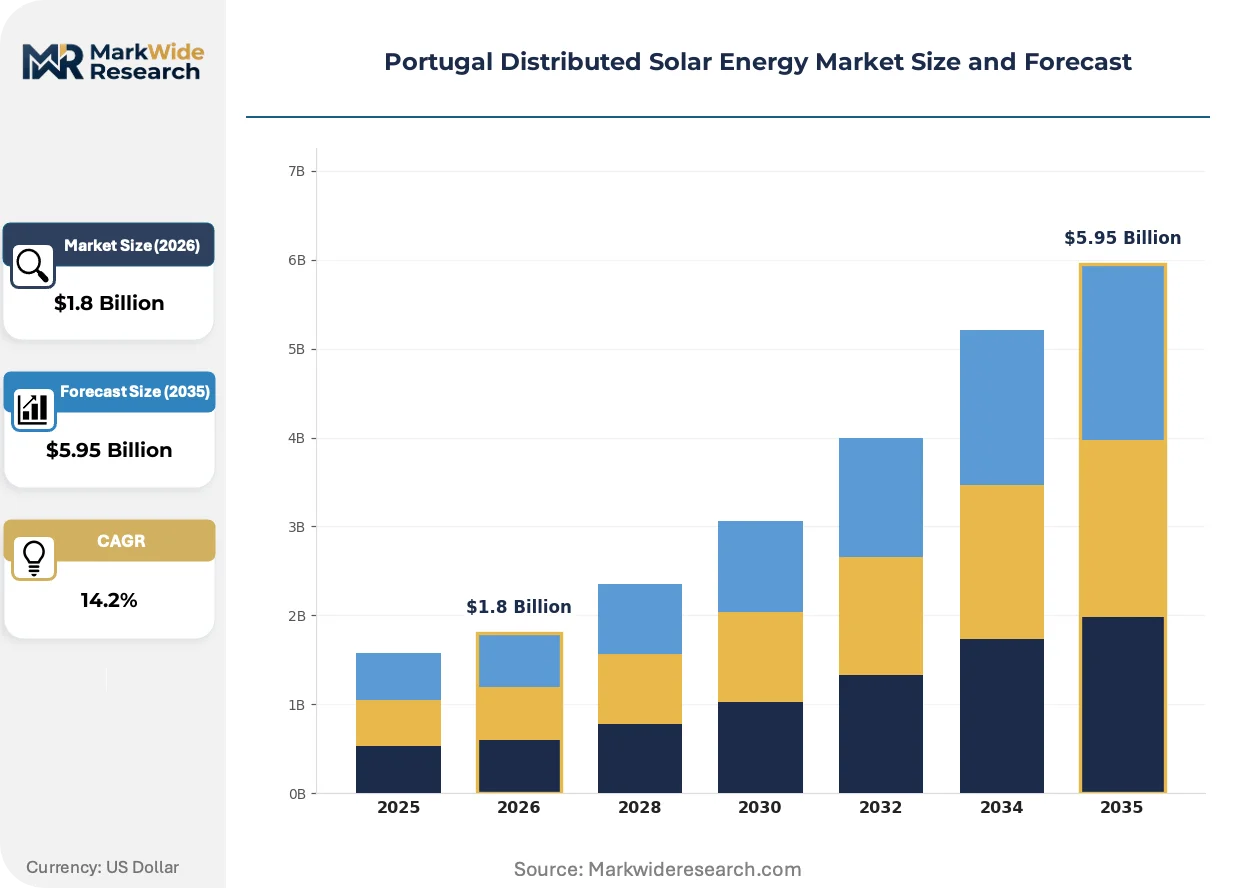
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Panels, Solar Thermal Application: Residential, Commercial, Industrial, Agricultural Installation Type: Roof-mounted, Ground-mounted, Carport-mounted, Floating Systems End User: Consumers, Businesses, Municipalities, Energy Cooperatives |
| Companies Covered | Solar 2 Power, Solcor, DAPE, FF Solar, Sunaitec, SolarImpact, EDP, Lightsource BP, Iberdrola, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Distributed Solar Energy Market Evolving Landscape
Technology convergence between photovoltaic generation and battery storage is compressing soft costs for agricultural end-users while regulatory pressure accelerates standardization of interconnection protocols across Portuguese distribution networks.
Power optimizers paired with module-level electronics are automating shade mitigation and performance monitoring for Alentejo agro-industrial rooftops with irregular structural geometries. Sunaitec and integrated inverter-storage specialists deploy these packages to agricultural cooperatives seeking to minimize engineering-procurement-construction overhead. The technology is automating commissioning workflows that previously required manual string balancing and iterative performance tuning.
EU Green Deal national recovery allocations are tightening local installer capacity through accelerated municipal rooftop program deployment. Portugal's Direção Geral de Energia e Geologia faces pressure to reform interconnection queue management as structural fund deadlines compress project timelines. Agricultural processing facilities in the Alentejo region respond by pre-qualifying engineering firms before formal licensing submission.
Direct equipment procurement from module assembly lines is displacing traditional distributor channels for mid-scale commercial developers. EDP leverages utility-scale procurement relationships to secure panel supply for smaller installations, compressing margin capture for independent distributors. Lisbon metropolitan corridor developers increasingly source integrated inverter-storage packages through manufacturer-direct arrangements rather than wholesale electrical supply houses.
Portugal Distributed Solar Energy Market Segmentation
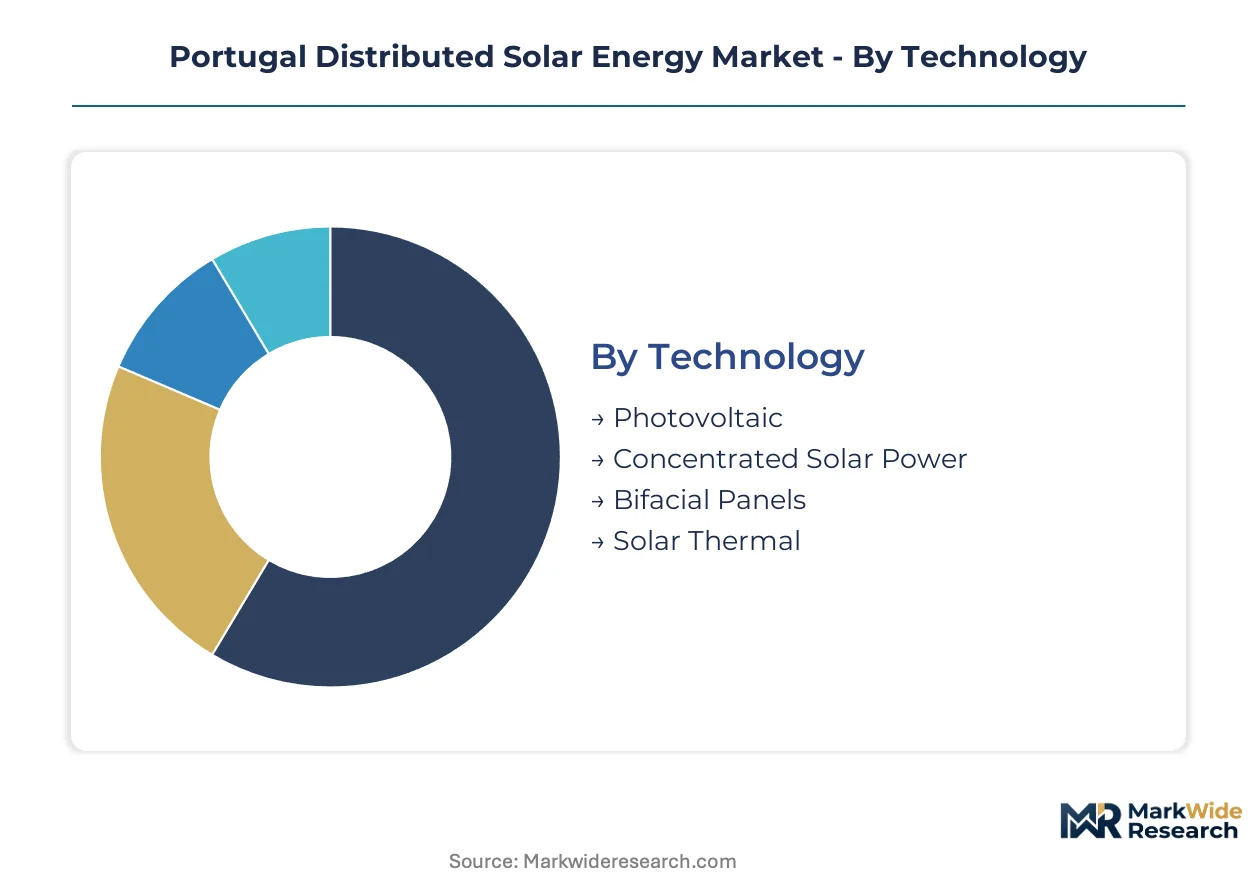
Segmentation reveals how Portugal's distributed solar market stratifies across technical architectures, deployment contexts, and ownership structures. Each dimension carries distinct regulatory implications and margin profiles that shape competitive positioning.
Technology:
Standardization dominates at the module level while differentiation concentrates in inverter electronics and mounting hardware.
- Photovoltaic:Crystalline silicon modules account for the bulk of installed capacity, with monocrystalline PERC cells displacing polycrystalline alternatives in Lisbon metropolitan corridor projects. Alentejo agro-industrial facilities favor these systems for their proven degradation curves and standardized procurement terms.
- Bifacial Panels:Dual-glass constructions capture reflected irradiance from rooftops and ground surfaces, boosting yield by 8-20% depending on albedo conditions. Ground-mounted commercial installations in the Alentejo region increasingly specify these for irrigation load matching.
- Concentrated Solar Power:Parabolic trough and tower configurations remain marginal in distributed applications due to scale economies favoring utility-scale deployment.
- Solar Thermal:Flat-plate and evacuated tube collectors serve hot water preheating for agricultural processing facilities, though photovoltaic dominance limits expansion.
Leading the category by volume: Photovoltaic. Expanding most quickly: Bifacial Panels.
Application:
Customer archetypes range from price-sensitive households to sophisticated energy managers seeking tariff optimization.
- Agricultural:Irrigation pumping, cold-chain refrigeration, and processing loads drive the steepest expansion trajectory as Alentejo farms hedge volatile wholesale electricity prices. Decreto-Lei n.º 162/2019 net metering provisions enable hour-by-hour consumption matching without feed-in tariff complexity.
- Commercial:Retail, hospitality, and logistics facilities across the Lisbon metropolitan corridor deploy behind-the-meter systems to bypass grid congestion and defer demand charges. String inverter configurations with power optimizers dominate this segment for shade mitigation on irregular rooftops.
- Industrial:Manufacturing loads with high consumption continuity favor larger system sizes and storage co-location to maximize self-consumption ratios.
- Residential:Single-family and multi-unit dwellings concentrate in suburban Lisbon and Porto corridors, constrained by roof ownership fragmentation and installer capacity limits.
Dominating by deployment scale: Commercial. Gaining share fastest: Agricultural.
Installation Type:
Site constraints and land economics determine mounting architecture selection across Portugal's varied topography.
- Roof-mounted:Ballasted and penetrating systems capture margin pools in urban zones where land scarcity inflates ground-mounted alternatives. Lisbon metropolitan corridor commercial projects favor this architecture for proximity to load centers and simplified permitting.
- Ground-mounted:Fixed-tilt and tracking arrays serve larger agricultural and industrial loads in Alentejo's open terrain, though land use licensing adds complexity.
- Carport-mounted:Dual-purpose structures providing vehicle shelter and generation capacity gain traction in commercial parking facilities.
- Floating Systems:Pontoon-mounted arrays on irrigation reservoirs and quarry lakes remain nascent, constrained by specialized engineering requirements.
Highest volume concentration: Roof-mounted. Steepest growth trajectory: Ground-mounted.
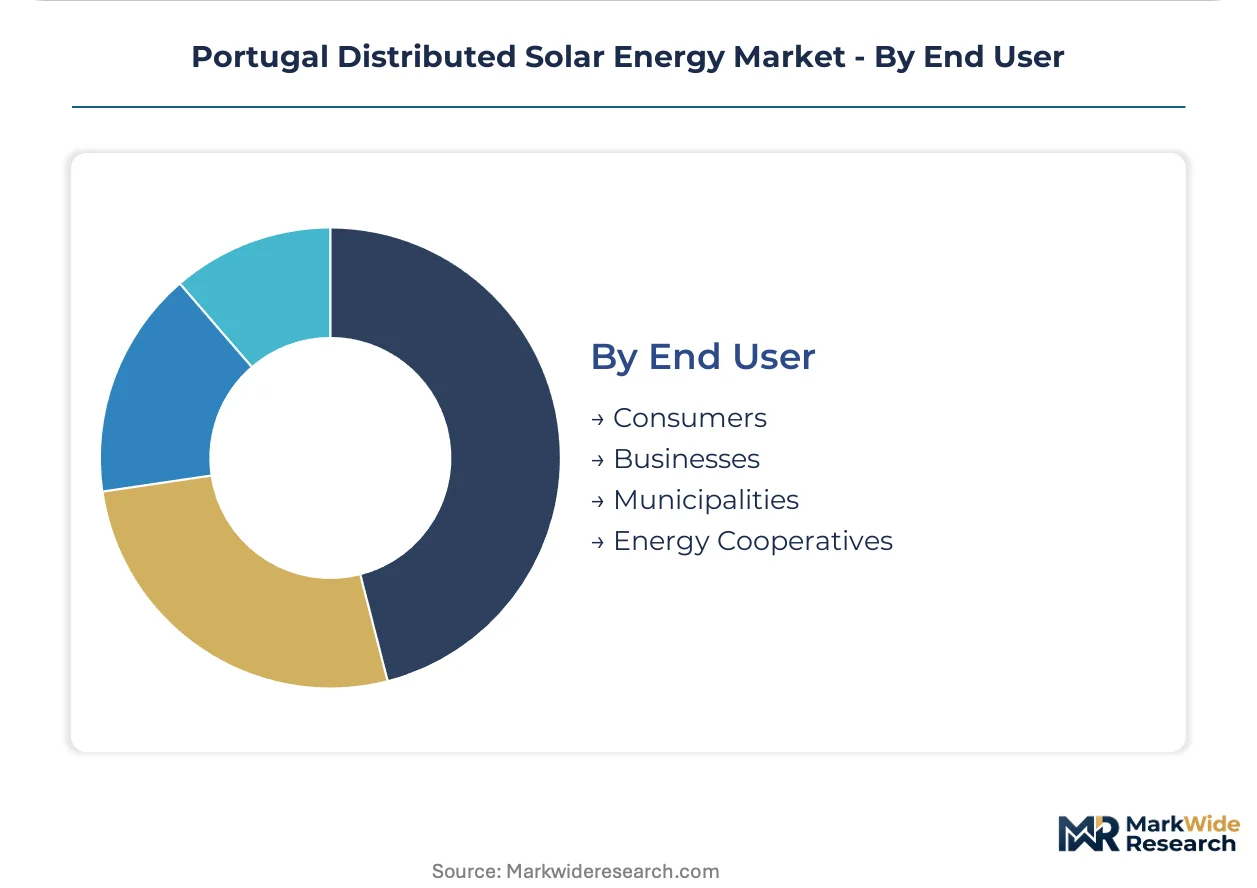
End User:
Ownership structures determine financing channels and regulatory compliance burdens.
- Businesses:Corporate balance sheet and third-party PPA arrangements dominate commercial and industrial deployment, with EDP and Iberdrola leveraging utility-scale procurement relationships for distributed supply security.
- Energy Cooperatives:Community ownership aggregations access Banco de Portugal green credit lines that reduce weighted average cost of capital, tightening installer capacity during peak construction seasons.
- Consumers:Individual households face higher per-watt soft costs and longer payback periods compared to commercial scale.
- Municipalities:Public building rooftop programs channel EU Green Deal structural funds, though interconnection queue delays compress project timelines.
Largest deployment volume: Businesses. Fastest ownership model expansion: Energy Cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon feedstock from the Alentejo region anchors Portugal's distributed solar manufacturing base. The Lisbon metropolitan corridor concentrates installation demand where grid congestion accelerates behind-the-meter deployment. Regional variations reflect divergent land economics and regulatory processing capacity across sub-national markets.
Lisbon Metropolitan Corridor
Commercial rooftop installations dominate this sub-region as logistics and retail facilities bypass transmission bottlenecks through self-consumption systems. Decreto-Lei n.º 162/2019 net metering provisions eliminate feed-in tariff complexity for urban developers. The corridor's saturated distribution network caps expansion in suburban belts while driving storage co-location adoption.
Alentejo Region
Agricultural irrigation loads and cold-chain refrigeration drive the steepest capacity growth as farms hedge volatile wholesale electricity prices. EU Green Deal structural funds channel capital toward cooperative ownership structures that access Banco de Portugal green credit lines. Évora and Beja districts cluster agro-industrial rooftop arrays serving olive processing and wine storage facilities.
Porto Metropolitan Area
Industrial manufacturing loads with high consumption continuity favor larger system sizes and integrated inverter-storage configurations. Direção Geral de Energia e Geologia licensing timelines create 6-12 month interconnection queues that compress project development calendars. Matosinhos and Vila Nova de Gaia host the densest concentration of commercial-scale deployments.
Central Portugal
Coimbra and Leiria districts exhibit emerging demand from municipal building rooftop programs funded by national recovery allocations. Energy cooperatives aggregate residential and small commercial installations to achieve scale economies in procurement and installation. Local installer capacity tightens during peak construction seasons as structural fund deadlines accelerate deployment timelines.
Algarve Region
Tourism and hospitality facilities deploy behind-the-meter systems to manage seasonal demand peaks and defer grid upgrade expenditures. Faro and Portimão concentrate commercial installations where land scarcity inflates ground-mounted alternatives relative to rooftop configurations. The sub-region's irradiance profile supports higher capacity factors than northern counterparts.
Portugal Distributed Solar Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated inverter-storage specialization and agricultural end-user optimization. The market structures around three distinct tiers: utility-backed developers leveraging procurement scale, regional installers with localized licensing expertise, and technology-integrated specialists compressing soft costs through equipment packaging. Competitive dynamics center on supply security arrangements and installer capacity capture during peak construction seasons.
Within the utility-backed tier, EDP and Iberdrola exemplify players deploying procurement muscle across distributed project pipelines. Among technology-integrated specialists, Sunaitec occupies a position representing inverter-storage packaging expertise for agricultural applications. These three entities anchor distinct competitive vectors: procurement scale, utility-scale-to-distributed channel leverage, and technical integration specialization.
| Leading Market Players |
|---|
| Solar 2 Power |
| Solcor |
| DAPE |
| FF Solar |
| Sunaitec |
| SolarImpact |
| EDP |
| Lightsource BP |
| Iberdrola |
| Others |
Value Network & Pricing Analysis
Polysilicon wafer costs cascade through module assembly lines into three-tier pricing structures across premium, standard, and economy levels for Portuguese distributed solar projects. Lisbon metropolitan corridor developers absorb upstream volatility through manufacturer-direct procurement contracts that compress traditional distributor margins.
Pricing Analysis
Warranty bundling separates EDP and Iberdrola utility-backed offerings from independent installer quotes that unbundle operations and maintenance coverage. Three-tier pricing structure across premium, standard, and economy levels tracks module efficiency grades and inverter integration complexity. Pricing pressure stems from Asian polysilicon spot market volatility that disrupts Portuguese project commissioning timelines. Agricultural cooperatives in Alentejo exhibit highest price sensitivity due to seasonal cash flow constraints, while industrial offtakers with balance sheet capacity accept premium tiering for storage co-location.
Supply Chain Analysis
Direct-to-installer channels displace wholesale electrical distributors as EDP leverages utility-scale procurement relationships for distributed project supply security. Module sourcing concentrates in China, Vietnam, and Malaysia, with Portuguese developers exposed to polysilicon feedstock volatility and shipping lane congestion. Inverter electronics and power optimizer components draw from Taiwanese and German manufacturing bases. Distribution runs through manufacturer-direct arrangements and regional installer networks rather than traditional electrical supply houses. Single-source vulnerability in crystalline silicon wafer supply creates commissioning timeline risk for commercial projects facing Direção Geral de Energia e Geologia licensing deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decreto-Lei n.º 162/2019 net metering compliance creates a barrier-to-entry moat that rewards players with established licensing expertise and DGEG relationship infrastructure. New entrants face 6-12 month administrative queues that incumbents navigate through pre-qualified engineering partnerships.
For Market Incumbents: Extend procurement scale advantages into storage co-location service bundling to capture premium margins as regulatory mandates approach. Anchor supply security through backward integration into module assembly partnerships that bypass distributor channels. Defensive positioning requires capturing certified electrician workforce capacity before peak construction seasons tighten labor markets. Threat substitution from integrated inverter-storage specialists like Sunaitec demands technical service differentiation beyond hardware supply. For New Entrants and Emerging Players: Agricultural cooperatives in Alentejo's cold-chain processing segment represent the most penetrable white-space target due to tariff-hedge demand and underdeveloped technical service coverage. Energy cooperative ownership structures access Banco de Portugal green credit lines that reduce capital barriers for community solar aggregations. Municipal rooftop programs channel EU Green Deal structural funds with compressed timelines that favor agile project development capabilities over incumbent scale. For Investors and Strategic Acquirers: Interconnection queue reform announcements are the leading indicator that licensing velocity will accelerate project development returns for compliant players. Long-term viability centers on storage integration capabilities and agricultural end-user optimization expertise rather than pure generation asset ownership. Acquisition targets should demonstrate DGEG pre-qualification status and established installer workforce relationships. Watch for Banco de Portugal green credit line expansion signals as inflection points for cooperative ownership model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Integration | Anticipated regulatory mandates for inverter-storage pairing create premium service margins for technical specialists. |
| Direct Module Procurement | Manufacturer-direct sourcing bypasses distributor markups and secures supply for DGEG licensing timeline compliance. |
| Agricultural Cooperative Partnership | Alentejo cold-chain facilities offer tariff-hedge demand with underpenetrated technical service coverage. |
| Certified Workforce Development | Peak season electrician scarcity constrains commissioning capacity for commercial distributed projects. |
| Green Credit Line Access | Banco de Portugal facilities reduce cooperative ownership cost of capital below commercial balance sheet alternatives. |
Research Methodology
Independent corroboration across EDP procurement officers, Iberdrola distributed development leads, Sunaitec technical directors, Alentejo agricultural cooperative managers, and DGEG licensing administrators underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EU Green Deal national recovery allocation disclosures, Banco de Portugal green credit line reporting, DGEG interconnection queue statistics, and EDP utility-scale procurement disclosures anchors the analysis. Bottom-up project pipeline enumeration and top-down regulatory framework assessment triangulate market sizing across the analysis window.
Rate-of-change decomposition separates technology cost trajectories from regulatory velocity effects and financing condition shifts across the projection horizon. Segmentation modeling incorporates technology architecture, application context, installation type, and ownership structure dimensions. CAGRs derive from installed capacity build rates, module price elasticity assumptions, and self-consumption optimization penetration curves. Forecast inputs include polysilicon supply volatility indices and DGEG licensing timeline distributions.
Several conditions sit outside the modeled scope, including retroactive regulatory changes to Decreto-Lei n.º 162/2019 net metering provisions and grid infrastructure upgrade timelines beyond distribution network deferral limits. Forecasts reflect base-case assumptions regarding EU Green Deal structural fund continuity and Asian polysilicon supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Solar Software Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Australia Solar Power Market