
 India Solar Tracker Market | 2026-2036
India Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
India Solar Tracker Market Foresight
The price-performance gap between premium and commodity solar tracker tiers is hardening in India. NexTracker Inc. leverages its global software IP to command higher margins on intelligent tracking systems, while Scorpius Trackers Private Limited anchors its position through aggressive localization of steel fabrication. Mahindra Susten Pvt. Ltd. competes on integrated EPC-tracker bundling for utility clients seeking single-contractor accountability.
A solar tracker is a mechanical racking system that orients photovoltaic modules toward the sun throughout the day, typically achieving 20-35% additional energy yield over fixed-tilt configurations through single or dual-axis rotation. The primary purpose is maximizing specific energy output per installed watt in large-scale solar installations where land and balance-of-system costs justify the mechanical complexity. Single-axis trackers dominate ground-mounted utility deployments due to favorable cost-yield ratios on flat terrain, while dual-axis systems retain niche appeal in concentrated solar thermal and high-DNI pockets. Active tracking technology leads the technology segment through sensor-driven motor control, though hybrid systems combining astronomical algorithms with minimal sensor dependency are gaining traction in dust-prone regions.
BIS certification requirements for structural steel components and CEA grid connectivity standards shape product qualification timelines and testing expenditures for tracker suppliers. The PLI scheme for solar module manufacturing indirectly stimulates tracker demand by expanding domestic PV deployment targets, while state-level renewable purchase obligations in Maharashtra, Karnataka, and Tamil Nadu create enforceable offtake pipelines. Stakeholders must monitor ALMM list revisions and state transmission capacity auctions to time manufacturing scale-up and inventory positioning.
Market Dynamics
The ALMM framework's domestic content mandate is compressing qualification timelines for tracker suppliers while concentrating procurement authority among EPCs with captive steel fabrication and in-house structural engineering capabilities.
Growth Catalysts
- CEA grid connectivity standards:Mandatory compliance testing for tracker-integrated mounting systems is filtering out unqualified fabricators and elevating procurement volumes for certified suppliers.
- Rajasthan and Gujarat utility-scale deployment:State-level land banks with high DNI ratings are accelerating single-axis tracker adoption as developers optimize land-use efficiency.
- PLI scheme for solar module manufacturing:Domestic PV capacity expansion is creating downstream demand pull for balance-of-system components including tracking infrastructure.
Market Restraints
- Steel price volatility:Galvanized structural steel constitutes the dominant input cost for tracker fabrication, exposing margins to commodity cycle swings.
- BIS certification timelines:Extended testing protocols for structural components delay product qualification and compress bidding windows for new entrants.
- Fixed-tilt racking substitution:Low-cost fixed systems retain cost advantage in land-abundant, low-labor-cost pockets of eastern India.
Strategic Opportunities
- Karnataka and Tamil Nadu underpenetration:Southern states with strong RPO enforcement but nascent tracker adoption present whitespace for technology conversion.
- Hybrid tracking algorithms:Convergence of astronomical positioning with minimal sensor dependency is opening dust-prone markets previously closed to active tracking.
- Integrated EPC-tracker bundling:Single-contractor accountability models are displacing component-separate procurement in utility-scale tenders.
Industry Challenges
- Structural engineering talent scarcity:Qualified geotechnical and wind-load analysis capacity concentrates among established EPCs, constraining new entrant scale-up.
- ALMM list revision uncertainty:Unpredictable delisting schedules force inventory positioning risks and working capital strain on component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Solar Tracker Market |
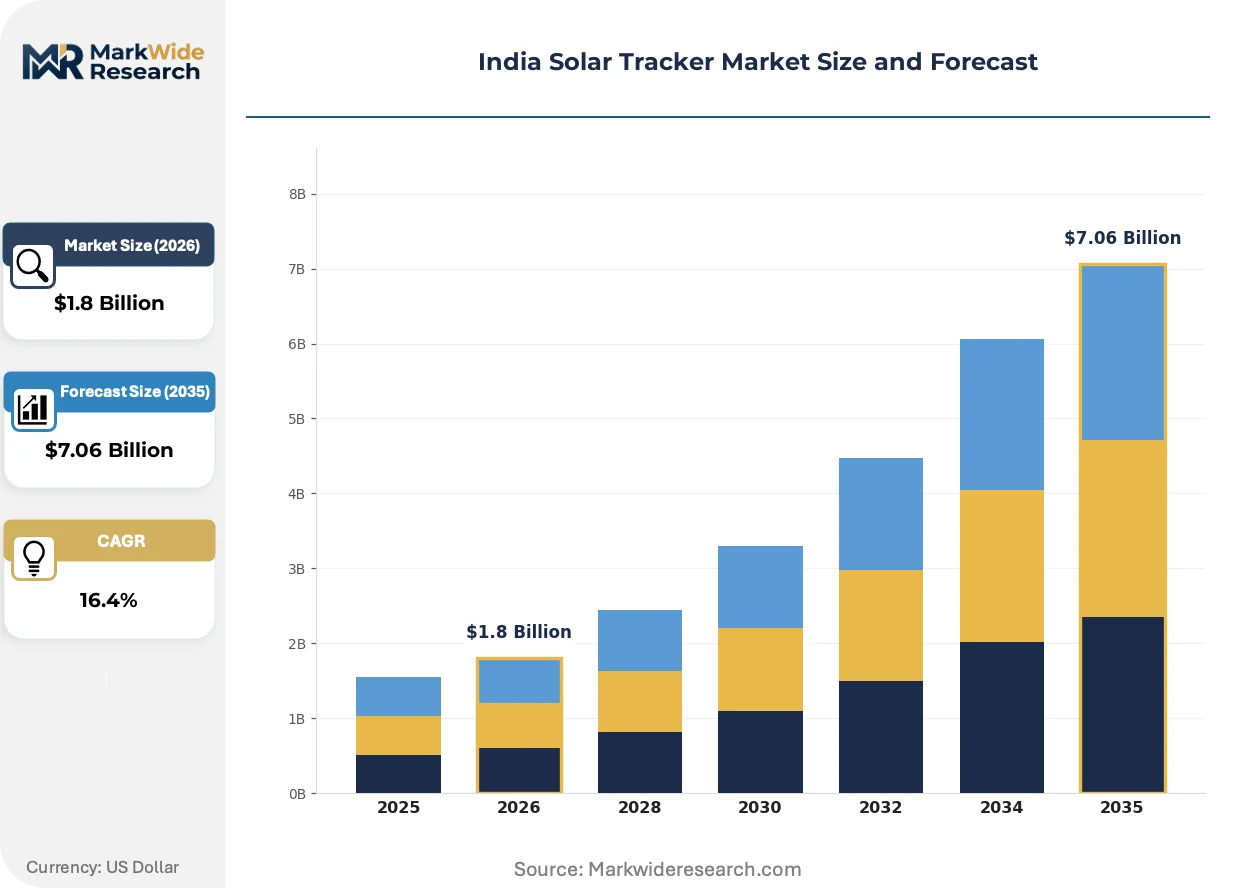
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
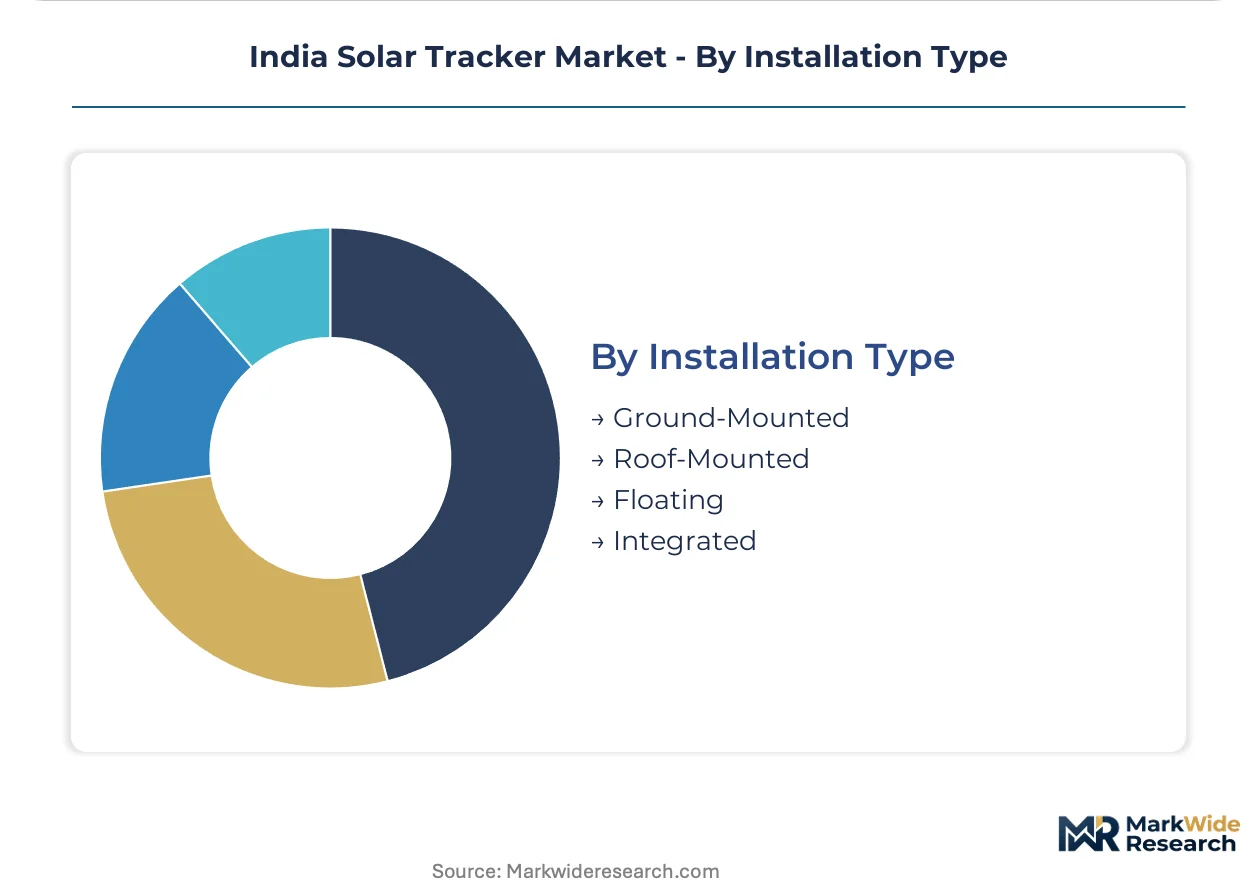
| Segmentation | Product Type: Single-Axis, Dual-Axis, Vertical Axis, Horizontal Axis End User: Utilities, Commercial, Residential, Industrial Technology: Active Tracking, Passive Tracking, Hybrid Systems, Fixed Systems Installation Type: Ground-Mounted, Roof-Mounted, Floating, Integrated |
| Companies Covered | Asun Trackers Pvt. Ltd., PV Hardware Solutions SLU, NexTracker Inc., Mahindra Susten Pvt. Ltd., Scorpius Trackers Private Limited, Arctech Solar Holding Co. Ltd, GameChange Solar, Trina Solar, Tata Power Solar Systems Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Solar Tracker Market Shifts & Advancements
Software-defined tracking control is displacing mechanical hardware as the primary value determinant, while regulatory pressure on domestic content accelerates localization of supply chains.
Backtracking algorithms integrated with site-specific weather forecasting is automating yield optimization across variable cloud-cover conditions. Developers in Rajasthan are deploying these systems at scale to minimize row-to-row shading losses. The technology is automating manual tilt-adjustment protocols previously requiring on-site intervention.
MNRE's ALMM framework revisions are tightening qualification windows for imported tracker components. Domestic fabricators with BIS-certified galvanizing lines are capturing incremental share from overseas suppliers. Western and southern state tenders are responding with accelerated domestic sourcing mandates.
Long-term service contracts unbundled from hardware supply are emerging as a distinct revenue stream. Independent power producers in Gujarat are separating O&M agreements from initial capital procurement. This shift is most pronounced among portfolios with centralized control rooms and multi-site monitoring infrastructure.
India Solar Tracker Market Segmentation
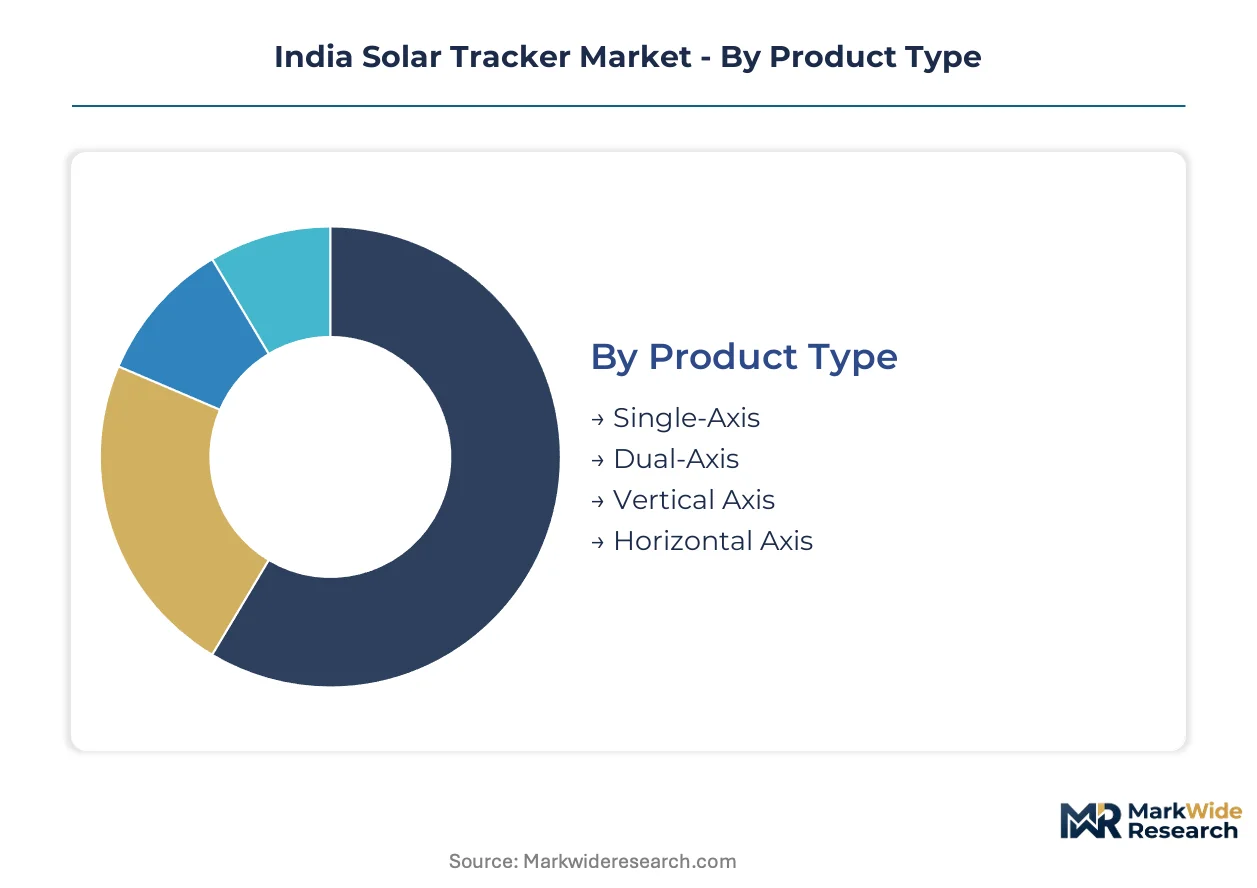
Segmentation in the India solar tracker market reveals how technology choices map to land constraints, irradiance profiles, and procurement sophistication across state-level tendering environments. Distinct product configurations dominate specific deployment contexts, from Rajasthan's flat desert terrain to Karnataka's undulated solar parks.
Product Type:
Upgrade cycles in Indian utility-scale solar are accelerating as developers replace early fixed-tilt installations with tracking systems to boost capacity utilization factors without expanding land footprints.
- Single-Axis:Horizontal rotation along one pivot point captures east-west sun movement, delivering 20-25% yield gains over fixed systems. Procurement concentrates in Gujarat and Rajasthan land banks where flat terrain minimizes foundation complexity and motor synchronization costs. MNRE's domestic content mandates under ALMM favor locally fabricated torque tube assemblies.
- Dual-Axis:Azimuth and elevation rotation tracks sun position across both horizontal and vertical planes, extracting maximum irradiance in high-DNI pockets. Niche deployment survives in concentrated solar thermal hybrids and research installations where energy density outweighs mechanical complexity premiums.
- Vertical Axis:Rotational movement around a vertical mast suits constrained footprints and distributed generation rooftops in urban Maharashtra and Tamil Nadu commercial estates.
- Horizontal Axis:Tilted plane rotation aligned with latitude angle serves specific latitude-optimized installations in southern Karnataka where terrain slope alignment reduces structural adaptation costs.
Single-Axis sits at the top of the volume ranking, with Hybrid Systems climbing the fastest as developers seek dust-resilient tracking in western Rajasthan.
End User:
Customer procurement sophistication determines technology specification depth, with integrated EPCs driving standardization while fragmented industrial offtakers demand customization.
- Utilities:Central and state gencos with multi-hundred megawatt portfolios specify tracker-integrated mounting systems through single-tender EPC contracts. NTPC and SECI auctions in Gujarat and Rajasthan mandate 25-year structural warranties and centralized SCADA integration.
- Commercial:Corporate PPA offtakers with 10-50 MW rooftop and carport installations prioritize rapid deployment and minimal civil works over yield optimization per watt.
- Residential:Individual household deployments below 10 kW rarely justify tracker mechanical complexity given rooftop space constraints and maintenance access limitations.
- Industrial:Captive power consumers in Maharashtra and Tamil Nadu textile and cement clusters evaluate trackers against diesel backup arbitrage, not grid-tariff comparisons.
Utilities command the dominant procurement volume, with Industrial end users expanding most quickly as captive power regulations tighten across western states.
Technology:
Control system architecture determines maintenance burden and dust resilience, critical differentiators in India's arid western solar corridors.
- Active Tracking:Sensor-driven motor control with real-time position correction achieves precision alignment but requires frequent cleaning and calibration in dust-heavy Rajasthan summers. CEA grid connectivity standards mandate electromagnetic compatibility testing for active control systems.
- Passive Tracking:Thermal or hydraulic actuation without electrical sensors eliminates motor failure points and suits remote installations with limited technician access.
- Hybrid Systems:Astronomical algorithms with minimal sensor dependency reduce maintenance intervals while retaining precision. Gujarat developers are deploying these at scale after monsoon season sensor degradation plagued early active-only deployments.
- Fixed Systems:Static mounting without tracking mechanics retains cost advantage in land-abundant eastern pockets where labor costs dominate levelized economics.
Active Tracking retains installed base dominance, though Hybrid Systems gain share fastest as O&M cost sensitivity rises in long-term service contract structures.
Installation Type:
Foundation and mounting topology selection follows land availability, water body access, and existing infrastructure constraints across state-specific deployment patterns.
- Ground-Mounted:Pile-driven or ballasted foundations on graded terrain constitute the standard configuration for utility-scale parks. Rajasthan's solar zones allocate contiguous land parcels optimized for north-south tracker rows with standardized inter-row spacing.
- Roof-Mounted:Ballasted or attached systems on commercial and industrial buildings face structural load limits that constrain tracker weight and wind exposure profiles.
- Floating:Pontoon-mounted installations on reservoirs and irrigation ponds gain traction in land-constrained Maharashtra and Tamil Nadu where water surface rights are available.
- Integrated:Tracker systems combined with agricultural shading or canal-top structures address dual-use land productivity requirements in Gujarat and Karnataka pilot programs.
Ground-Mounted installations anchor volume leadership, with Floating systems expanding most steeply as land acquisition timelines extend in southern states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural engineering talent pools concentrate in western and southern industrial corridors, anchoring tracker fabrication clusters near high-irradiance solar zones.
Rajasthan
Bhagwanpura and Phaseda solar parks drive single-axis procurement volumes. CEA grid connectivity standards mandate electromagnetic compatibility testing for active control systems. Jodhpur-Jaisalmer belt hosts integrated EPCs with captive steel galvanizing lines serving NTPC and SECI auctions.
Gujarat
Charanka and Dholera solar zones optimize land-use efficiency through north-south tracker row configurations. MNRE's ALMM framework revisions tighten qualification windows for imported torque tube assemblies. Kutch district fabricators with BIS-certified galvanizing capture share from overseas suppliers.
Karnataka
Pavagada and Koppal solar parks present whitespace for technology conversion from fixed-tilt to tracking systems. State renewable purchase obligations create enforceable offtake pipelines for utility-scale developers. Ballari district EPCs bundle tracker supply with 25-year O&M contracts unbundled from hardware procurement.
Tamil Nadu
Kamuthi and Neyveli solar installations face land acquisition timeline extensions pushing developers toward floating tracker configurations. State-level RPO enforcement tightens captive power regulations for textile and cement clusters. Tirunelveli district reservoirs host pilot pontoon-mounted systems with minimal civil works.
Maharashtra
Sakri and Dhule solar zones evaluate trackers against diesel backup arbitrage for industrial offtakers. PLI scheme for solar module manufacturing stimulates downstream demand for balance-of-system tracking infrastructure. Aurangabad industrial estates deploy vertical-axis systems on constrained commercial rooftops.
India Solar Tracker Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the India solar tracker market. Integrated EPCs with captive steel fabrication anchor the supply base, while specialized tracker vendors license control software IP. Three archetypes dominate: global technology licensors, domestic steel fabricators with BIS certification, and bundled EPC-tracker contractors. Competitive moves concentrate on manufacturing scale-up and strategic partnerships with state-level developers.
Among global technology licensors, NexTracker Inc. and Arctech Solar Holding Co. Ltd exemplify the software-defined control system tier. Domestic fabrication specialists include Scorpius Trackers Private Limited and Mahindra Susten Pvt. Ltd, representing the integrated EPC-tracker bundling archetype. Tata Power Solar Systems Limited occupies a position spanning both fabrication and utility-scale project development. Asun Trackers Pvt. Ltd. sits within the emerging tier of regional specialists targeting southern state whitespace.
| Leading Market Players |
|---|
| Asun Trackers Pvt. Ltd. |
| PV Hardware Solutions SLU |
| NexTracker Inc. |
| Mahindra Susten Pvt. Ltd. |
| Scorpius Trackers Private Limited |
| Arctech Solar Holding Co. Ltd |
| GameChange Solar |
| Trina Solar |
| Tata Power Solar Systems Limited |
| Others |
Supply & Pricing Matrix
MNRE's domestic content mandate under the ALMM framework gates qualified supply access and premium-tier pricing power for tracker suppliers. EPCs with captive BIS-certified galvanizing lines command margin premiums while import-dependent competitors face compressed bidding windows and qualification delays.
Pricing Analysis
Bundled hardware-O&M contracts separate from unbundled component supply as distinct pricing models across utility tenders. Premium tiers attach to 25-year structural warranties with centralized SCADA integration, while standard tiers compete on upfront capital minimization. Price differentiation hinges on BIS certification status and in-house structural engineering capacity. Pricing pressure intensifies in the standard tier as fixed-tilt racking substitutes erode tracker share in land-abundant eastern pockets. Industrial captive power buyers exhibit highest price sensitivity, prioritizing diesel arbitrage payback periods over yield optimization.
Supply Chain Analysis
Freight cost advantages anchor domestic fabrication clusters in Rajasthan and Gujarat near high-irradiance solar zones. Galvanized structural steel draws from Indian domestic mills, with torque tube assemblies sourced from Jodhpur-Jaisalmer belt fabricators. Control system electronics rest on imports from China and Taiwan. Supply chain risk concentrates in single-source vulnerability for sensor-driven motor controllers. Distribution runs through EPC-led bundling contracts rather than component-direct sales to project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India solar tracker market functions as a stable compounder, with state-level renewable purchase obligations in Maharashtra, Karnataka, and Tamil Nadu generating enforceable offtake pipelines that underpin steady deployment growth.
For Market Incumbents: Cement market position through backward integration into captive steel galvanizing capacity and BIS-certified structural fabrication. Defend against emerging unbundled O&M service providers by embedding long-term performance guarantees into initial hardware contracts. Prioritize certification investment in CEA electromagnetic compatibility testing to filter out unqualified fabricators from NTPC and SECI auction participation. For New Entrants and Emerging Players: Digital-channel route through software-defined tracking control licensing offers lowest capital barrier to market entry. Target Karnataka and Tamil Nadu whitespace where fixed-tilt conversion to tracking systems remains underpenetrated despite strong RPO enforcement. Pursue hybrid tracking algorithm development as go-to-market angle, combining astronomical positioning with minimal sensor dependency for dust-prone western markets. For Investors and Strategic Acquirers: Roll-up economics work for regional EPC specialists with captive fabrication capacity because ALMM qualification timelines concentrate procurement authority among integrated players. Five-to-ten-year viability hinges on exposure to state transmission capacity auction pipelines rather than merchant solar development. Monitor ALMM list revision schedules as inflection indicator for working capital strain and inventory positioning risk across component suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing | BIS-certified captive steel treatment secures ALMM qualification and defends margin position against import-dependent competitors. |
| Hybrid Tracking Algorithm Development | Astronomical positioning with minimal sensor dependency opens dust-prone Rajasthan markets previously closed to active tracking. |
| Unbundled O&M Service Contracts | Long-term service agreements separated from hardware supply create recurring revenue streams for Gujarat IPP portfolios. |
| Karnataka-Tamil Nadu Geographic Expansion | Technology conversion from fixed-tilt to tracking captures whitespace in southern states with enforceable RPO pipelines. |
| SCADA Integration Partnerships | Centralized control room compatibility secures NTPC and SECI auction mandates for 25-year warranty bundled tenders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged EPC project developers, utility procurement officers at NTPC and SECI, steel fabrication plant managers, and grid connectivity engineers at CEA. Secondary validation drew from MNRE policy circulars, state renewable purchase obligation filings, BIS certification registries, and CEA grid standards documentation. Bottom-up project pipeline aggregation triangulated against top-down addressable market sizing across the analysis window.
Segment-weighting approach distributed volume and value estimates across product type, end user, technology, and installation type dimensions. Single-axis ground-mounted configurations received proportional weighting reflecting Rajasthan and Gujarat deployment concentration. CAGRs derived from logistic diffusion modeling of tracker penetration against fixed-tilt baseline, with inputs from steel price volatility indices and state land bank allocation timelines.
The model assumes a particular technology adoption path; alternative pathways for passive thermal tracking would alter the outlook if dust-resilient performance exceeds hybrid system economics. Forecasts embed assumptions regarding ALMM list stability and state RPO enforcement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market