
 Middle East and Africa SLI Battery Market | 2026-2036
Middle East and Africa SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa SLI Battery Market Insights
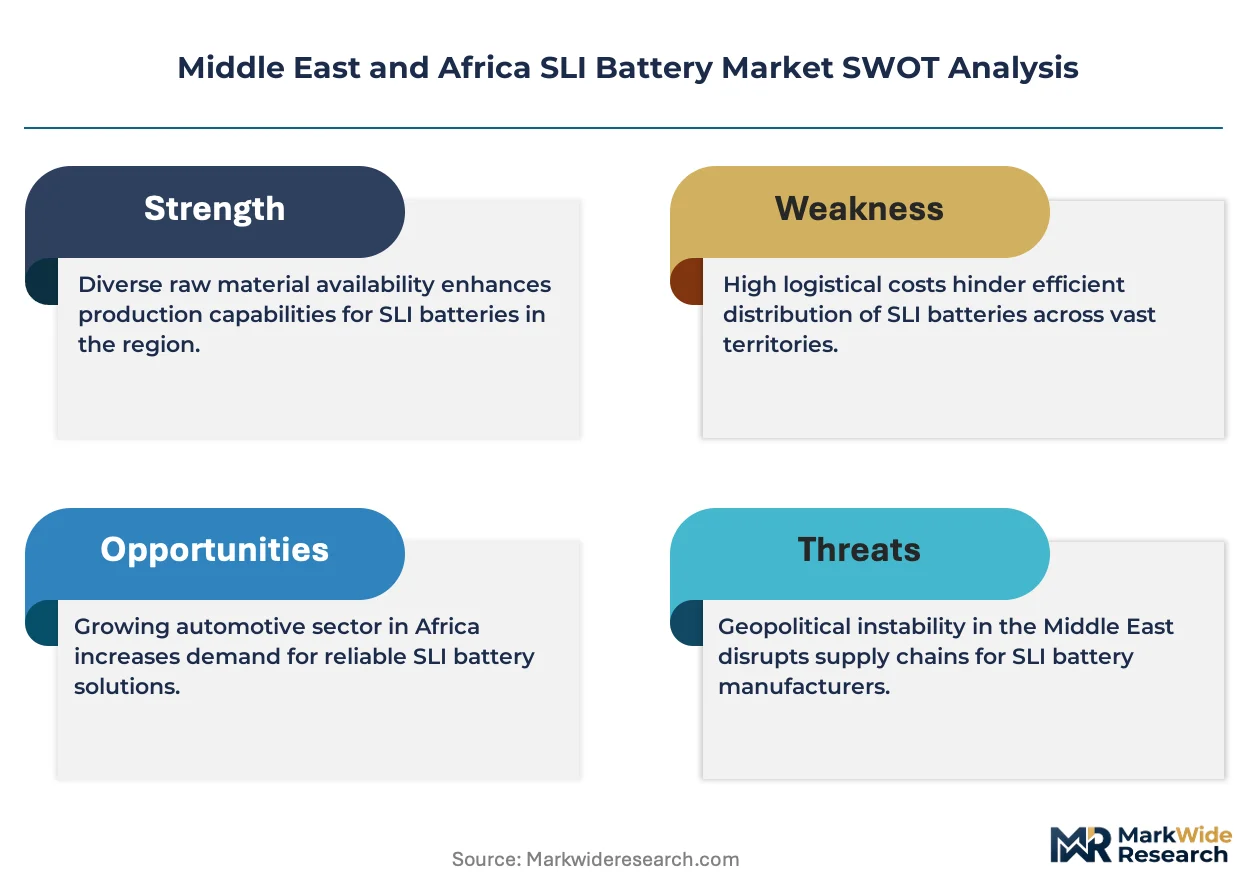
Calcium-calcium grid alloys is repositioning conventional antimony-based SLI construction across the Middle East and Africa, trimming water consumption and extending maintenance-free lifespans in hot-climate operating conditions. Clarios leverages its remanufacturing footprint to anchor aftermarket distribution in Gulf Cooperation Council states. First National Battery Corporation dominates Southern African supply through captive lead smelting and formal recycling networks. Exide Technologies competes via deep channel penetration across East African commercial vehicle fleets.
A Middle East and Africa SLI battery is a rechargeable lead-acid or advanced chemistry unit engineered for engine cranking, lighting, and ignition functions, typically delivering 12V output with cold cranking amperage ratings scaled to ambient temperature extremes. The device stores electrochemical energy through sulfuric acid electrolyte interaction with lead dioxide and sponge lead plates, releasing high-current bursts for internal combustion engine starting. Lead-acid chemistry still occupies the volume core across the region due to established recycling economics and price-sensitive fleet procurement, though absorbent glass mat variants are capturing premium passenger vehicle slots where vibration resistance and cycle durability command margin premiums. Start-stop technology penetration in Gulf-state urban taxi and ride-hail fleets is accelerating enhanced flooded battery uptake as a cost-optimized intermediate solution.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility frameworks that obligate manufacturers to finance end-of-life battery collection, while Saudi Standards, Metrology and Quality Organization (SASO) technical regulations govern import certification and product conformity for automotive electrical components. These dual compliance layers shape capital allocation toward localized recycling infrastructure and testing laboratory accreditation. Stakeholders must monitor how Gulf state local content requirements and evolving carbon border adjustment discussions redirect sourcing strategies for lead ingot and plastic casing materials.
Market Dynamics
Calcium-calcium grid alloys are displacing antimony-based construction across Middle East and Africa SLI manufacturing, trimming water loss rates and enabling maintenance-free operation in ambient temperatures exceeding 45°C. This metallurgical pivot is compressing service intervals and reshaping warranty economics for fleet operators from Riyadh to Lagos.
Growth Catalysts
- Vision 2030 fleet expansion:Saudi Arabia's industrialization targets are accelerating commercial vehicle registrations and replacement battery procurement across the Kingdom's logistics corridors.
- Extended producer responsibility frameworks:South Africa's National Environmental Management Waste Act mandates manufacturer-financed collection networks, formalizing recycling economics and stabilizing lead supply.
- Absorbent glass mat chemistry:Premium passenger segments in Gulf Cooperation Council states are adopting vibration-resistant construction for start-stop compatibility in urban taxi applications.
Market Restraints
- Lead price volatility:Battery-grade lead ingot costs fluctuate with London Metal Exchange pricing, compressing margin visibility for distributors serving price-sensitive East African commercial fleets.
- Import certification friction:Saudi Standards, Metrology and Quality Organization technical regulations create testing bottlenecks for non-Gulf suppliers seeking product conformity marks.
- Lithium-ion substitution pressure:Two-wheeler electrification in Nigerian urban centers is diverting capital from lead-acid SLI toward lithium phosphate packs for motorcycle taxi fleets.
Strategic Opportunities
- Ethiopia aftermarket penetration:Africa's second-most populous nation exhibits fragmented battery distribution with minimal organized retail presence, creating channel consolidation potential.
- Remanufacturing network expansion:Gulf Cooperation Council local content requirements are incentivizing in-region smelting and plastic casing production to satisfy circular economy procurement criteria.
- Enhanced flooded battery convergence:Start-stop system adoption in Dubai and Abu Dhabi ride-hail fleets is unifying demand for cost-optimized intermediate chemistry between conventional flooded and AGM construction.
Industry Challenges
- Lead smelter environmental compliance:Captive recycling facilities in Southern Africa face sulfur dioxide emission control upgrades requiring capital deployment amid uncertain secondary lead price spreads.
- Testing laboratory accreditation timelines:SASO certification delays for new product introductions extend inventory holding periods and compress working capital efficiency for import-dependent distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa SLI Battery Market |
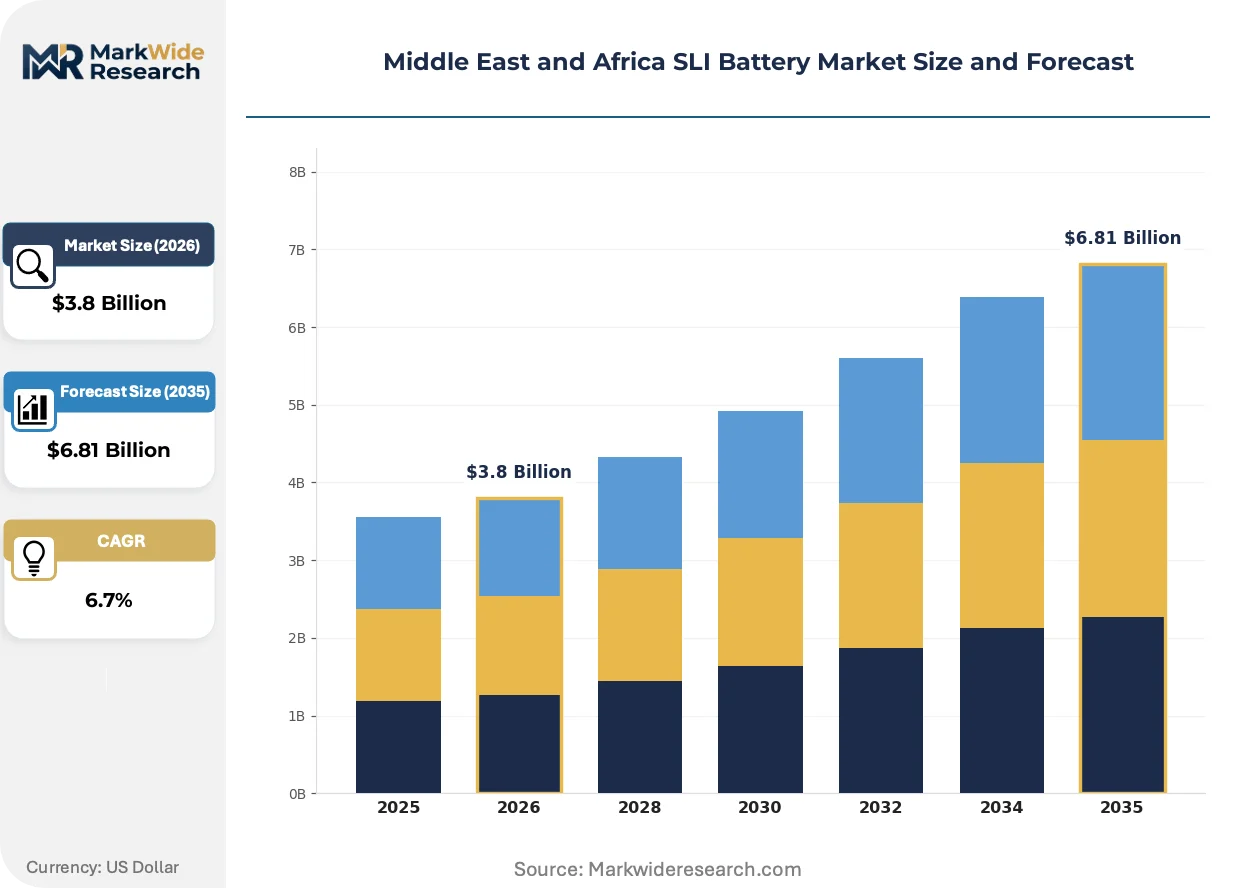
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Absorbent Glass Mat, Gel Application: Automotive, Solar Energy, UPS, Marine End User: Manufacturers, Retailers, Distributors, Consumers Technology: Start-Stop, Enhanced Flooded, AGM, Lithium |
| Companies Covered | Exide Technologies, EnerSys, East Penn Manufacturing Co., Amara Raja Batteries Ltd, Middle East Battery Company (MEBCO), GS Yuasa Corporation, Clarios, Johnson Controls International plc, First National Battery Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa SLI Battery Market Trends and Innovations
Electrification of light commercial transport and tightening environmental enforcement are compressing product lifecycles and forcing chemistry diversification across Middle East and Africa SLI supply chains. Manufacturers are repositioning around thermal resilience and circular material flows.
Calcium-calcium grid metallurgy is unifying hot-climate durability standards across conventional flooded battery production. Fleet operators in Saudi Arabia and the UAE are adopting this construction at replacement rates exceeding prior antimony-based models. The technology is compressing warranty claim frequencies and enabling extended service interval marketing.
South Africa's Department of Forestry, Fisheries and the Environment is tightening extended producer responsibility enforcement for end-of-life battery collection. Manufacturers now finance formal recycling networks under National Environmental Management Waste Act obligations. The compliance layer is concentrating supply among integrated smelter operators with accredited waste handling permits.
Aftermarket procurement through mobile-enabled distributor networks is fragmenting traditional channel control in Nigerian and Kenyan urban centers. Independent repair shops are bypassing authorized dealers via direct import relationships with Asian manufacturers. Lagos and Nairobi exhibit the most visible disintermediation, with informal retailers capturing share from established battery brand distribution.
Middle East and Africa SLI Battery Market Segmentation
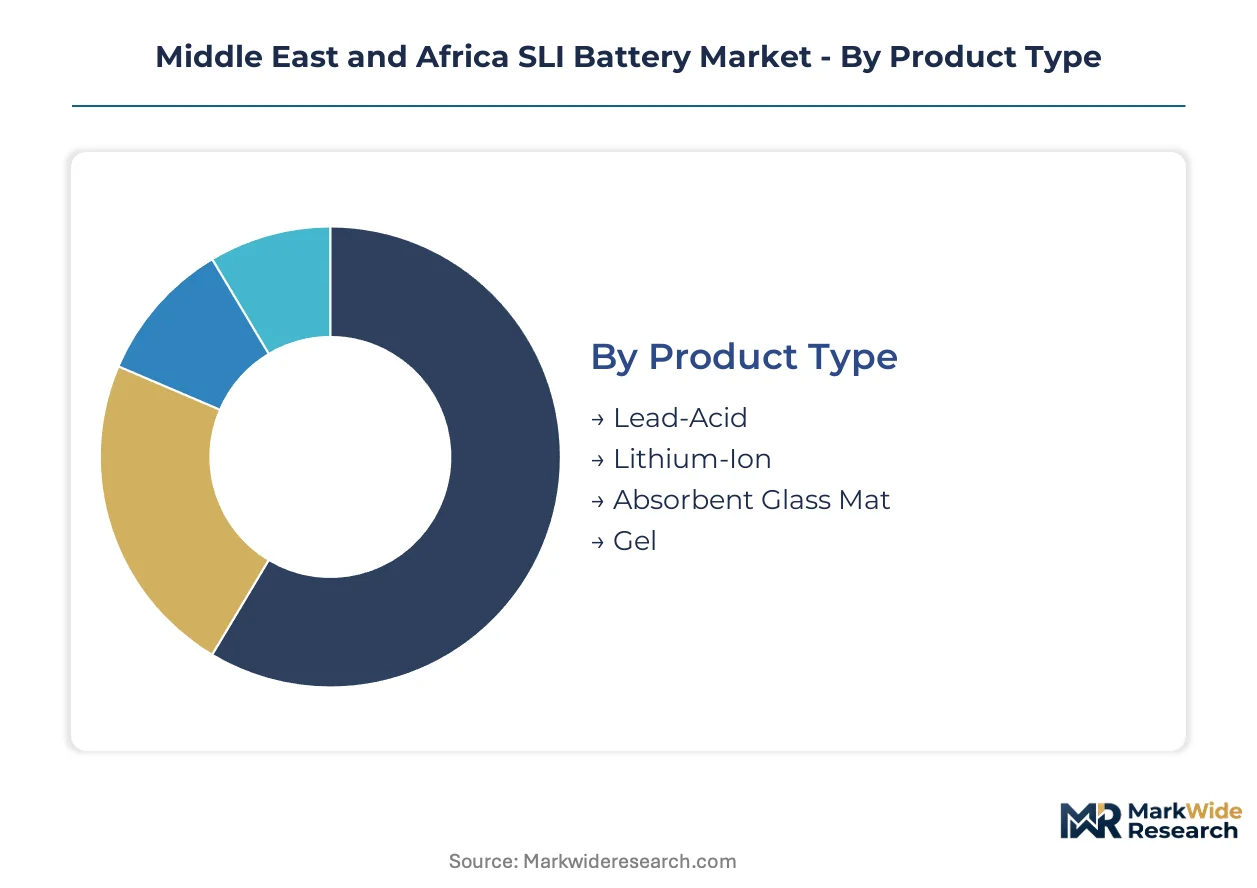
SLI battery procurement patterns across the Middle East and Africa diverge sharply by thermal environment, vehicle electrification readiness, and aftermarket channel maturity. Chemistry selection and construction standards cluster around climate extremes in Gulf Cooperation Council states versus cost-optimized fleet replacement cycles in Sub-Saharan commercial corridors.
Product Type:
Electrochemical construction determines thermal resilience and maintenance burden across ambient temperature ranges exceeding 50°C in Gulf interior regions.
- Lead-Acid:Flooded lead dioxide and sponge lead plate construction with sulfuric acid electrolyte remains the volume anchor. Nigerian and Kenyan commercial vehicle fleets prioritize this chemistry for replacement accessibility and established informal recycling networks.
- Lithium-Ion:Lithium iron phosphate cathode chemistry with battery management systems enables deep discharge tolerance and reduced weight. Dubai and Abu Dhabi ride-hail operators are piloting conversions for hybrid fleet segments where start-stop duty cycles demand faster recharge rates.
- Absorbent Glass Mat:Electrolyte suspended in fiberglass mat separators eliminates free liquid and enables vibration-resistant mounting. Saudi taxi operators specify AGM construction for premium sedan segments requiring maintenance-free operation in Riyadh summer conditions.
- Gel:Silica-thickened electrolyte construction resists stratification and enables tilted installation. Marine applications in Red Sea and Mediterranean ports specify gel construction for deep-cycle reserve capacity.
Lead-Acid leads on scale; Lithium-Ion leads on momentum.
Application:
End-use diversification is stretching SLI battery specification ranges beyond traditional automotive cranking into stationary reserve and cyclic duty profiles.
- Automotive:Engine starting, lighting, and ignition functions across passenger vehicles, light commercial trucks, and heavy-duty freight configurations. Saudi Vision 2030 logistics corridor expansion is concentrating procurement in Jeddah-Riyadh-Dammam highway networks.
- Solar Energy:Off-grid photovoltaic storage and hybrid inverter backup duties in rural electrification projects. Ethiopian and Tanzanian mini-grid developers specify deep-cycle SLI derivatives for evening discharge cycles.
- UPS:Uninterruptible power supply standby power for data centers, telecommunications, and healthcare infrastructure. Dubai Internet City and Riyadh financial district deployments demand 15-minute backup at full load.
- Marine:Dual-purpose starting and deep-cycle service for commercial fishing vessels and port handling equipment. Durban and Mombasa harbor operators prioritize corrosion-resistant terminal construction.
Automotive dominates current volume; Solar Energy is climbing fastest.
End User:
Channel structure determines pricing transparency, warranty enforcement, and technical support availability across fragmented African markets versus organized Gulf distribution.
- Manufacturers:Original equipment fitment for new vehicle assembly lines and industrial equipment production. Isuzu and Toyota assembly plants in South Africa specify calcium-calcium grid alloys for local content compliance.
- Retailers:Branded storefront and e-commerce direct-to-consumer sales with installation services. Lagos independent battery shops are bypassing authorized distribution through direct Asian import relationships.
- Distributors:Wholesale bulk procurement serving secondary markets and regional logistics networks. Clarios maintains Gulf Cooperation Council aftermarket anchoring through remanufacturing facility partnerships.
- Consumers:Individual replacement purchases driven by failure events and preventive maintenance schedules. Kenyan boda-boda motorcycle taxi operators exhibit acute price sensitivity in Nairobi and Mombasa urban corridors.
Distributors capture the largest transaction volume; Retailers are gaining share fastest.
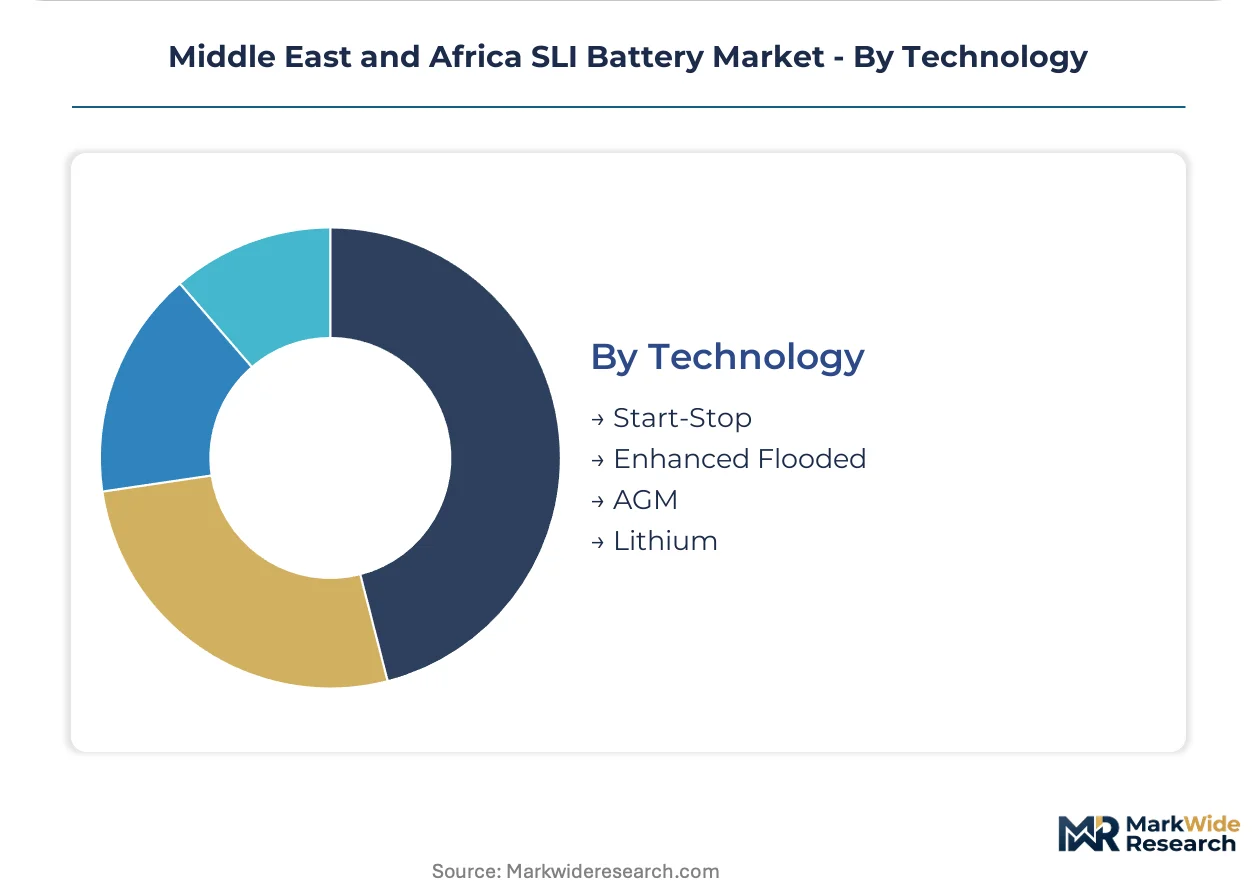
Technology:
Start-stop system proliferation and electrification intermediates are compressing the technology hierarchy between conventional flooded and full lithium conversion.
- Start-Stop:Integrated starter-generator systems demanding 5-10x cycle durability versus conventional SLI duty. UAE taxi fleet operators specify start-stop compatibility for urban idle reduction in Dubai and Sharjah congestion zones.
- Enhanced Flooded:Improved plate alloys and separator materials bridging cost and performance between conventional flooded and AGM construction. Saudi ride-hail aggregators are converging on EFB as a cost-optimized intermediate for high-temperature start-stop applications.
- AGM:Absorbent glass mat construction with compressed plate packs enabling high-rate discharge and vibration immunity. Premium European vehicle service in Gulf Cooperation Council states specifies AGM for warranty preservation.
- Lithium:Complete electrochemical substitution eliminating lead and acid chemistry. South African two-wheeler electrification pilots are diverting capital toward lithium phosphate for motorcycle taxi fleet conversions.
Enhanced Flooded leads on near-term scale; Lithium leads on long-term momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jeddah-Riyadh-Dammam logistics corridor anchors SLI battery procurement across Saudi Arabia's commercial vehicle fleet expansion. Regional demand clusters around Gulf Cooperation Council urban taxi electrification and Sub-Saharan aftermarket replacement cycles.
Saudi Arabia
Vision 2030 industrialization targets are accelerating heavy-duty freight registrations along the Kingdom's eastern logistics spine. SASO technical regulations govern import certification for automotive electrical components, tightening product conformity requirements. Riyadh's ride-hail fleet operators specify calcium-calcium grid construction for summer temperature extremes exceeding 50°C.
United Arab Emirates
Dubai and Abu Dhabi urban taxi electrification pilots are driving start-stop system penetration across premium sedan segments. MOHAP oversees product safety standards for automotive components entering the northern emirates. Sharjah's commercial vehicle service corridors concentrate aftermarket battery distribution for cross-border freight into Oman.
South Africa
Isuzu and Toyota assembly plants in Gauteng province specify calcium-calcium alloys for original equipment fitment compliance. The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility frameworks under the National Environmental Management Waste Act. Durban harbor operators prioritize corrosion-resistant terminal construction for marine dual-purpose applications.
Nigeria
Lagos commercial vehicle fleets prioritize flooded lead-acid chemistry for replacement accessibility and informal recycling network proximity. The country's national standards body governs automotive component import specifications with evolving local content requirements. Kano's motorcycle taxi corridors exhibit acute price sensitivity among boda-boda operators sourcing direct Asian imports.
Ethiopia
Addis Ababa's mini-grid developers specify deep-cycle SLI derivatives for rural photovoltaic storage and evening discharge cycles. The national energy regulator oversees off-grid electrification procurement standards for battery-backed solar installations. The capital's fragmented battery distribution landscape offers channel consolidation potential with minimal organized retail presence.
Middle East and Africa SLI Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as Gulf Cooperation Council local content requirements incentivize in-region smelting and plastic casing production. The vendor base exhibits tiered concentration with integrated lead producers, regional distributors, and Asian import specialists occupying distinct competitive positions. Three archetypes define the structure: captive smelter operators with formal recycling networks, remanufacturing-anchored aftermarket distributors, and price-focused direct importers serving informal retail channels. Geographic expansion and strategic partnerships represent the dominant competitive moves as stakeholders navigate SASO certification bottlenecks and South African environmental compliance layers.
Among integrated Southern African producers, First National Battery Corporation exemplifies the captive smelter archetype through accredited waste handling permits and formal collection network financing. Clarios occupies the remanufacturing-anchored distributor position within Gulf Cooperation Council aftermarket channels. Exide Technologies represents the deep channel penetration specialist across East African commercial vehicle corridors.
| Leading Market Players |
|---|
| Exide Technologies |
| EnerSys |
| East Penn Manufacturing Co. |
| Amara Raja Batteries Ltd |
| Middle East Battery Company (MEBCO) |
| GS Yuasa Corporation |
| Clarios |
| Johnson Controls International plc |
| First National Battery Corporation |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange battery-grade lead ingot pricing cascades through Middle East and Africa SLI supply chains, compressing distributor margins in Lagos and Nairobi while Gulf Cooperation Council buyers absorb volatility through long-term smelter offtake contracts tied to SASO-certified product tiers.
Pricing Analysis
Input-cost pass-through from lead ingot volatility dominates pricing dynamics across the value chain. Three-tier pricing structure across premium AGM, standard calcium-calcium, and economy antimony-based constructions segments buyers by thermal resilience requirements and certification grade. Cost compression in East African commercial fleet tiers intensifies because informal recycling networks undercut formal collection economics. Nigerian boda-boda operators exhibit acute price sensitivity; Saudi ride-hail fleet procurement shows lowest sensitivity due to warranty-driven specification rigidity.
Supply Chain Analysis
SASO certification and South African extended producer responsibility permitting create gating layers that concentrate supply among accredited operators. Manufacturing gravity centers on South Africa, Saudi Arabia, and China, with lead ingot, plastic casing resin, and separator materials as critical inputs. Single-source vulnerability runs through Gulf state dependence on Asian separator imports. Distribution runs through remanufacturing-anchored networks in GCC states and fragmented independent retail in Sub-Saharan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where South Africa's National Environmental Management Waste Act enforcement and Saudi SASO technical regulations are accelerating capital deployment toward accredited recycling infrastructure and conformity testing capacity.
For Market Incumbents: Cement market position through captive smelter upgrades in Gauteng province and SASO laboratory accreditation investments in Riyadh. Lithium-ion substitution pressure in Nigerian two-wheeler segments demands defensive calcium-calcium alloy R&D to preserve lead-acid core economics. Channel control via mobile-enabled distributor networks offers the strongest defensive lever against Asian direct-import disintermediation. For New Entrants and Emerging Players: Launch via direct-to-installer distribution in Ethiopia's fragmented Addis Ababa corridor, where organized retail presence remains minimal and channel consolidation potential is highest. Target solar-energy mini-grid developers in Tanzania and Kenya with deep-cycle SLI derivatives for photovoltaic storage duty. White-space penetration should prioritize aftermarket bypass of established GCC distributor hierarchies. For Investors and Strategic Acquirers: Consolidation pressure builds where informal recycling networks undercut formal collection economics and environmental enforcement tightens. Long-term viability favors integrated smelter operators with accredited waste handling permits and Gulf local content compliance. The signal to watch is SASO certification timeline compression, which would accelerate distributor margin pressure and trigger acquisition opportunities among import-dependent mid-tier players.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Smelter Capacity Expansion | First National Battery Corporation's Gauteng facility secures lead supply under South African extended producer responsibility frameworks. |
| SASO Testing Laboratory Accreditation | Clarios and Gulf partners reduce certification bottlenecks for automotive electrical component import conformity. |
| Calcium-Calcium Grid Alloy R&D Investment | Thermal resilience improvements target Riyadh summer extremes exceeding 50°C in ride-hail fleet applications. |
| Mobile-Enabled Distributor Network Deployment | Lagos and Nairobi aftermarket channels bypass traditional authorized dealer hierarchies through direct Asian import relationships. |
| Enhanced Flooded Battery Production Scale-Up | Saudi ride-hail aggregators converge on cost-optimized intermediate chemistry between conventional flooded and AGM construction. |
Research Methodology
Direct dialogue with lead smelter operations managers, aftermarket distributor principals, SASO certification laboratory directors, and fleet procurement officers across Jeddah, Lagos, and Johannesburg grounded qualitative insights. Secondary validation drew from London Metal Exchange price data, South African Department of Forestry, Fisheries and the Environment regulatory filings, Saudi Standards, Metrology and Quality Organization technical regulations, and vehicle registration databases. Bottom-up channel volume estimates and top-down macroeconomic demand drivers underwent iterative triangulation.
Bottom-up segmentation modeling across chemistry type, construction standard, thermal environment, and fleet replacement cycle density anchored the analytical lens. Value projections incorporated start-stop system penetration rates in Gulf taxi fleets, extended producer responsibility compliance cost pass-through, and lithium-ion substitution thresholds in two-wheeler segments. CAGRs derived from regression against vehicle stock growth, battery replacement frequency shifts, and regional industrialization indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lead price volatility spikes and SASO certification timeline extensions. Model assumptions reflect documented regulatory enforcement trajectories and smelter capacity expansion schedules. A model refresh is warranted upon material change in Gulf Cooperation Council local content requirements or carbon border adjustment implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Battery Separators Market
Batteries
Battery Anode Materials Market
Batteries
VRLA Batteries Market
Batteries
Stretchable Battery Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Military Battery Packs Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Vietnam Battery Market
Batteries
Wood-Based Batteries Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Europe Battery Market
Batteries
North America Battery Market
Batteries
Zinc Carbon Battery Market