
 Poland Solar Energy Market | 2026-2036
Poland Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Solar Energy Market Analytics
Transition from polycrystalline to monocrystalline PERC and TOPCon cell architectures is reshaping module supply dynamics for Polish developers. Engie SA leverages its utility-scale pipeline across central Poland to sustain gigawatt-class project origination. Better Energy Holding A/S anchors its Nordic financing model to compete in Poland's growing commercial and industrial segment. R. Power Sp. Z O.o. specializes in distributed generation, dominating the mid-sized rooftop category through direct enterprise sales channels.
Poland solar energy encompasses photovoltaic systems that convert sunlight into electricity through semiconductor junctions, typically employing crystalline silicon cells with conversion efficiencies ranging from 20% to 23% in commercial modules, serving grid-connected power generation and behind-the-meter consumption for industrial, commercial, and residential consumers. Photovoltaic panels constitute the dominant product category by installed capacity, while utility-scale application segments attract the largest capital deployment due to streamlined permitting under Poland's distance act amendments. Bifacial technology captures expanding share in ground-mounted projects, as dual-sided energy yield improves project returns on the country's moderate-albedo agricultural and post-mining sites.
Poland's Energy Regulatory Office auction mechanism and EU Green Deal alignment through the National Energy and Climate Plan shape project economics and interconnection queue priorities. BIS-equivalent grid codes and distribution system operator technical requirements dictate inverter compliance and storage co-location standards for new capacity. Developers and investors must monitor forthcoming capacity market reforms and carbon border adjustment mechanism exposure for energy-intensive offtakers.
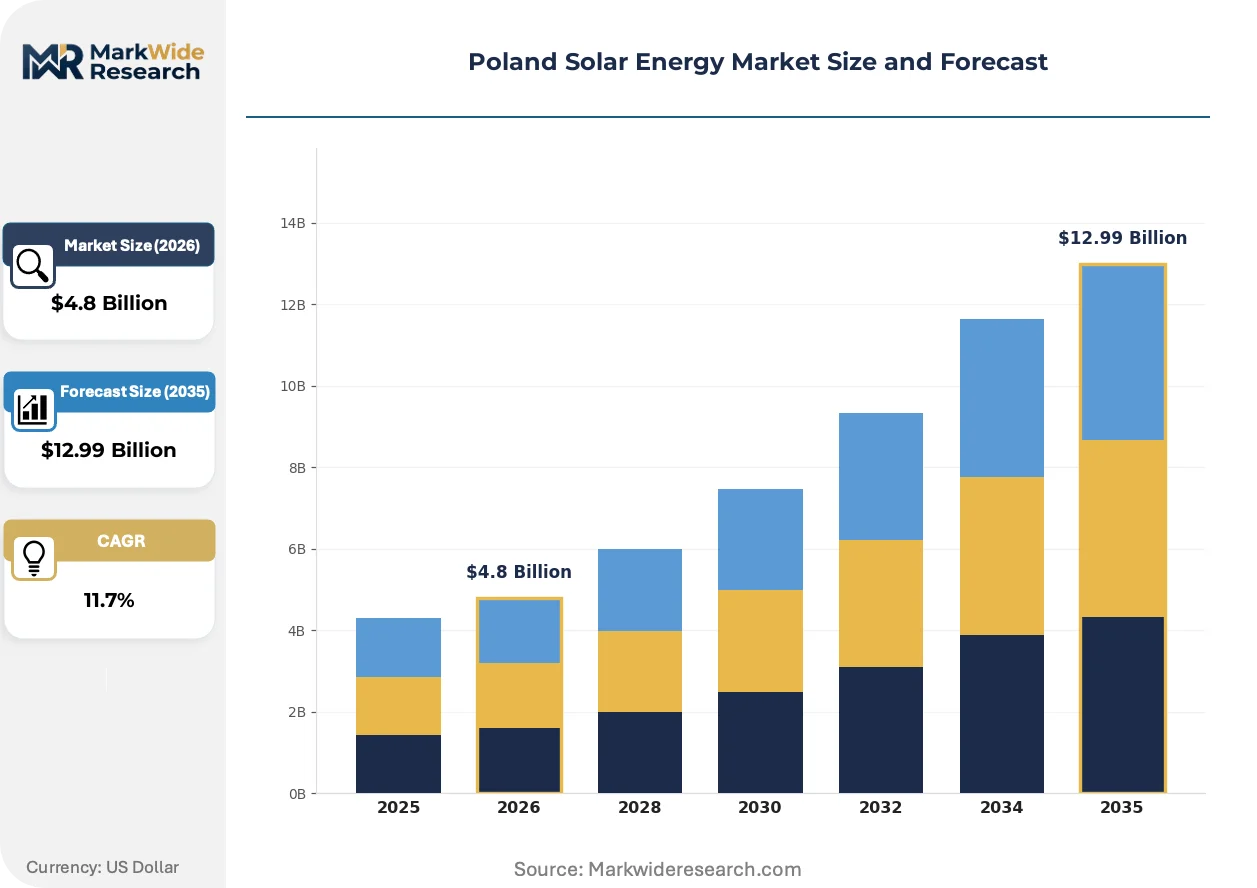
Market Dynamics
Poland's solar market pivots on the Energy Regulatory Office auction mechanism, which compresses project timelines and forces developers to secure grid-ready sites before competitive rounds open. This regulatory velocity is concentrating development in brownfield industrial zones with existing substation infrastructure.
Growth Catalysts
- URE Auction Mechanism:The auction-based renewable energy certificate system under Poland's Energy Regulatory Office accelerates commissioning timelines by pre-qualifying grid connection points.
- Industrial Rooftop Expansion:Polish manufacturing enterprises deploy behind-the-meter photovoltaic systems to hedge against volatile grid tariffs and carbon border adjustment exposure.
- TOPCon Cell Migration:Module suppliers are shipping higher-efficiency n-type cell architectures to Polish developers seeking improved energy yield on moderate-albedo post-mining sites.
Market Restraints
- Polysilicon Supply Concentration:Crystalline silicon feedstock dependency on Chinese ingot and wafer producers exposes Polish developers to input cost volatility and logistics bottlenecks.
- Distribution Grid Saturation:Local distribution system operator technical requirements limit inverter compliance pathways in rural voivodeships with aging transformer infrastructure.
- Land Use Competition:Agricultural zoning restrictions under Poland's distance act amendments constrain greenfield utility-scale siting options relative to brownfield alternatives.
Strategic Opportunities
- Energy Storage Co-location:Battery integration alongside photovoltaic installations qualifies for enhanced auction pricing tiers under evolving URE capacity market reforms.
- Greater Poland Voivodeship:Grid-ready industrial clusters in this western region offer lower interconnection queue congestion compared to saturated Silesian nodes.
- Bifacial Ground-mount Deployment:Dual-sided module technology improves project economics on Poland's post-industrial brownfields with elevated surface reflectivity.
Industry Challenges
- Grid Code Compliance Talent:Shortage of engineers certified in BIS-equivalent distribution system operator standards delays inverter commissioning and technical acceptance.
- Permitting Timeline Compression:Developers must synchronize environmental approvals, grid connection agreements, and auction qualification windows within tightening regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Solar Energy Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Batteries, Mounting Systems Application: Residential, Commercial, Industrial, Utility Scale Technology: C-Si, Thin Film, Bifacial, Concentrated Solar Power End User: Homeowners, Schools, Enterprises, Government |
| Companies Covered | Engie SA, Better Energy Holding A/S, R. Power Sp. Z O.o., Alseva Innowacje SA, Rwe AG, Sun Investment Group, Green Genius Sp. Z O.o., Corab Sp. Z O.o., Baywa AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Solar Energy Market Evolving Landscape
Cell architecture migration and procurement model evolution are restructuring competitive positioning across Poland's photovoltaic value chain. Developers now prioritize module efficiency and financing flexibility over pure capital cost minimization.
Monocrystalline PERC technology dominates utility-scale procurement in Poland, though n-type TOPCon cells are migrating from pilot demonstration to commercial ground-mount deployment. Industrial offtakers in the Silesian voivodeship specify higher-efficiency modules to maximize generation density on constrained rooftop footprints. This efficiency migration from p-type to n-type architectures is compressing project-level LCOE calculations and reshaping supplier qualification criteria for auction-eligible developments.
Poland's National Energy and Climate Plan alignment with EU Green Deal targets is tightening auction qualification standards for carbon intensity disclosure. Developers must now document supply chain emissions across polysilicon sourcing, ingot manufacturing, and module assembly stages. Utility-scale project sponsors with embedded carbon accounting capabilities are securing preferential interconnection queue positions from distribution system operators.
Enterprise buyers in Poland's manufacturing sector are consolidating photovoltaic procurement through long-term power purchase agreements rather than capital ownership structures. Energy-intensive facilities in the metals and chemicals verticals favor offtake contracts with fixed escalation clauses over balance-sheet project development. This contractual preference shift is most visible in the Greater Poland voivodeship, where industrial clusters negotiate aggregated procurement volumes to improve auction bidding leverage.
Poland Solar Energy Market Segmentation
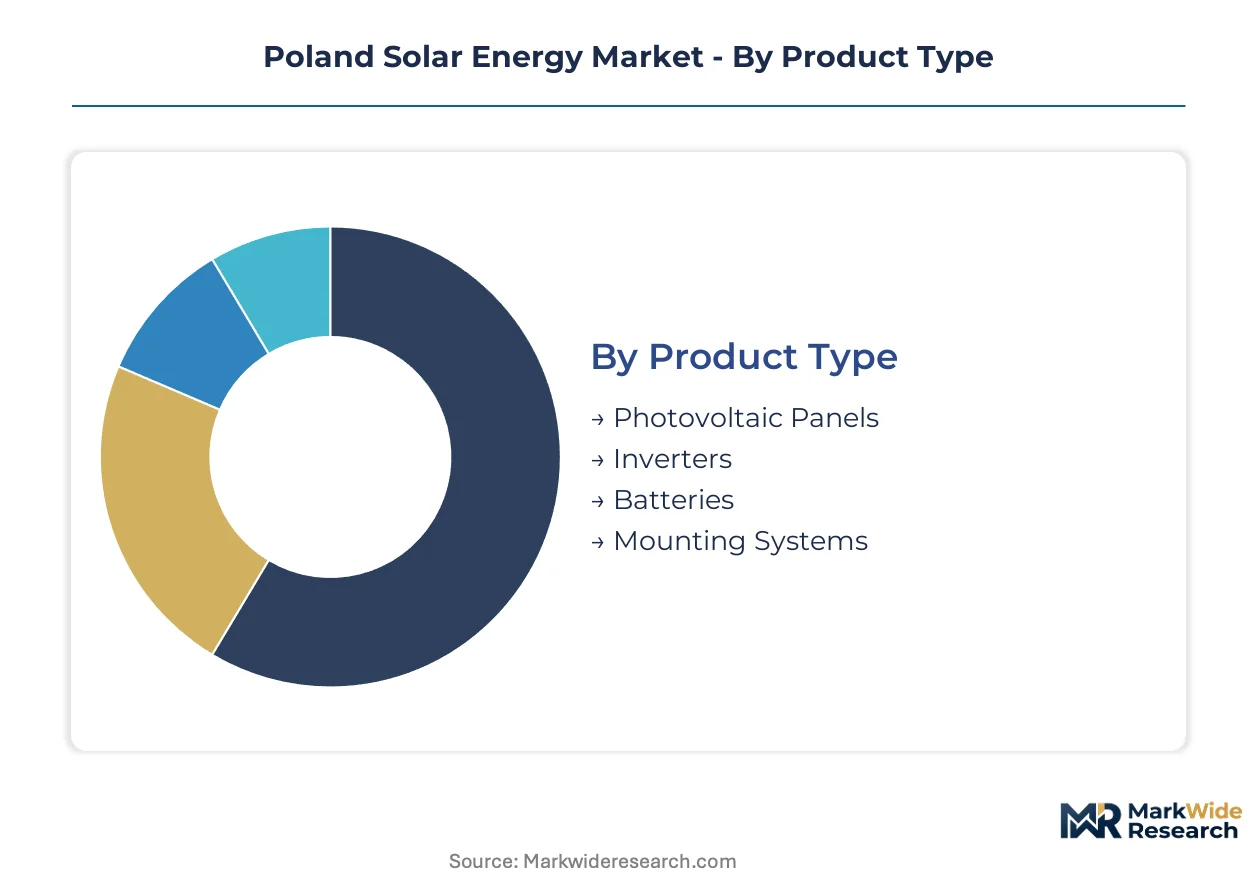
Poland's solar market stratification reveals how auction mechanics and grid constraints channel investment toward specific hardware configurations and offtake structures. Segment boundaries matter because URE qualification rules and distribution system operator technical requirements privilege certain combinations over others.
Product Type:
Cost tier determines procurement priority as developers balance module efficiency against balance-of-system expenditures under compressed auction timelines.
- Photovoltaic Panels:Crystalline silicon modules with conversion efficiencies ranging from 20% to 23% constitute the dominant hardware expenditure. Demand clusters in Silesian industrial zones where space constraints favor higher-wattage monocrystalline PERC and TOPCon architectures.
- Inverters:String and central inverter configurations must comply with BIS-equivalent grid codes for distribution system operator interconnection approval. Polish developers prioritize European-manufactured units with embedded reactive power capability to accelerate technical acceptance in saturated transformer zones.
- Batteries:Lithium-ion storage systems qualify for enhanced URE auction pricing tiers when co-located with photovoltaic generation.
- Mounting Systems:Fixed-tilt and tracking structures for ground-mount deployment on post-mining brownfields.
Photovoltaic panels hold installed capacity. Batteries are rotating up the share rankings.
Application:
Volume concentration follows grid readiness, with brownfield industrial sites offering substation proximity that greenfield alternatives cannot match.
- Utility Scale:Ground-mounted photovoltaic parks exceeding 1 MW capacity attract the largest capital deployment under Poland's distance act amendments. Project sponsors target Greater Poland voivodeship for lower interconnection queue congestion relative to saturated Silesian nodes.
- Industrial:Behind-the-meter rooftop systems serve manufacturing enterprises hedging volatile grid tariffs and carbon border adjustment exposure. Polish metals and chemicals facilities in the Silesian voivodeship specify higher-efficiency modules to maximize generation density on constrained footprints.
- Commercial:Mid-sized rooftop installations for retail and office properties.
- Residential:Distributed generation systems for single-family homeowners.
Utility scale commands capital deployment. Industrial is climbing the fastest.
Technology:
Customer type preferences are forcing migration from legacy architectures toward higher-yield cell designs that improve project returns on moderate-albedo sites.
- C-Si:Crystalline silicon technology dominates commercial procurement through established supply chains and bankable performance warranties. Polish developers specify n-type TOPCon variants for ground-mount projects on post-industrial brownfields with elevated surface reflectivity.
- Bifacial:Dual-sided modules capture expanding share by harvesting reflected irradiance from agricultural and post-mining surfaces. The technology improves energy yield calculations for auction-eligible developments without expanding land footprint.
- Thin Film:Cadmium telluride and amorphous silicon alternatives for specific building-integrated applications.
- Concentrated Solar Power:Thermal concentration systems with limited deployment in Poland's solar resource profile.
C-Si holds technology share. Bifacial is gaining share fastest.
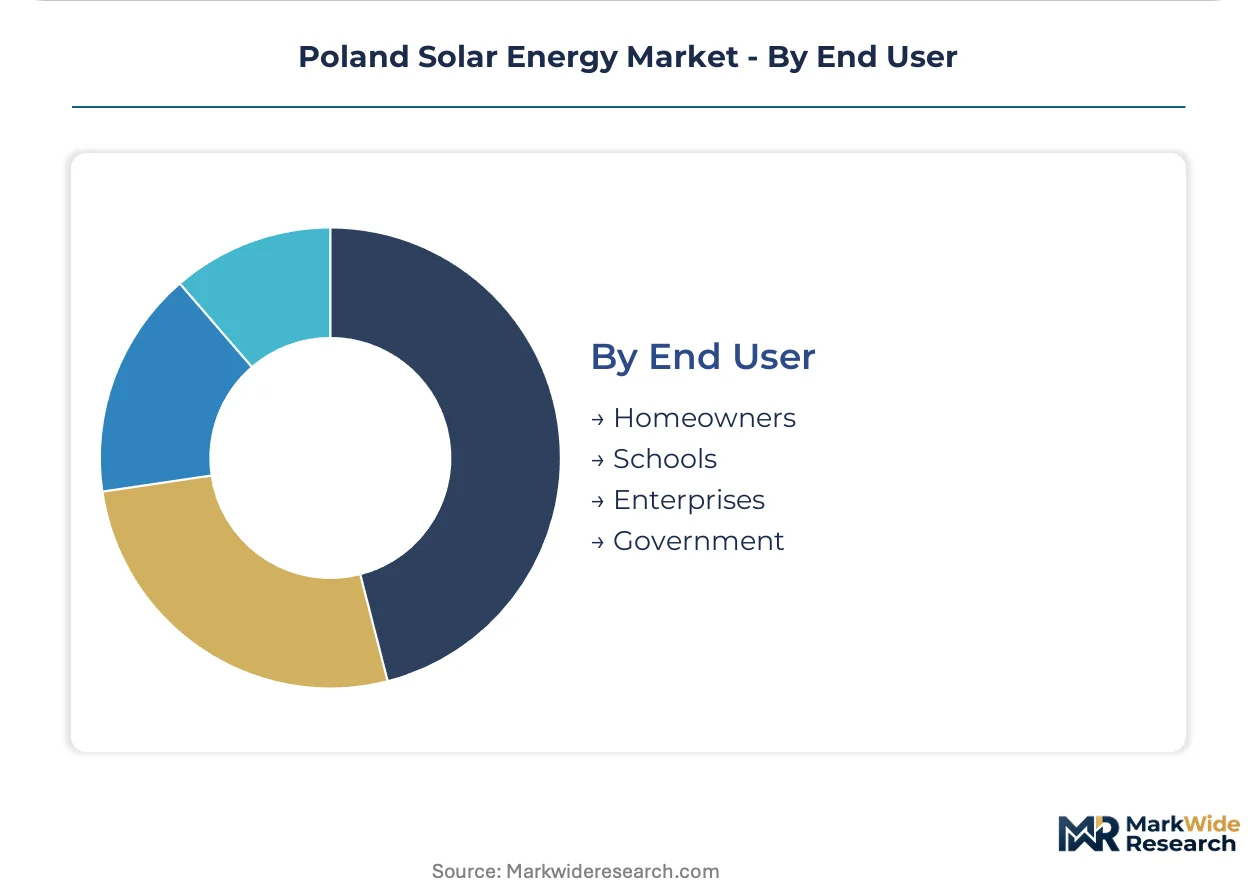
End User:
Geography within Poland shapes procurement scale, with voivodeship-level industrial clustering determining aggregated demand volumes.
- Enterprises:Energy-intensive manufacturing facilities drive the fastest-expanding demand category through long-term power purchase agreement structures. Greater Poland voivodeship industrial clusters negotiate aggregated procurement volumes to improve auction bidding leverage.
- Government:Public sector installations for municipal buildings and infrastructure.
- Homeowners:Residential consumers with distributed generation systems.
- Schools:Educational institutions with smaller-scale rooftop deployments.
Enterprises anchor demand volume. Government is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese module manufacturers supply the majority of photovoltaic hardware to Polish developers, with cargo flows routing through Rotterdam and Hamburg before final-mile distribution to Silesian and Greater Poland project sites.
Silesian Voivodeship
Industrial rooftop demand concentrates in Katowice and Gliwice manufacturing corridors where metals and chemicals enterprises seek tariff hedging. URE auction qualification requirements prioritize grid-ready brownfield substations in this historically coal-dependent region. Post-mining brownfields around Bytom and Zabrze host bifacial ground-mount arrays exploiting elevated surface albedo.
Greater Poland Voivodeship
Poznań industrial clusters negotiate aggregated procurement volumes to strengthen auction bidding leverage. Lower interconnection queue congestion relative to Silesia attracts utility-scale sponsors targeting streamlined permitting under distance act amendments. Agro-industrial facilities in Konin and Kalisz deploy behind-the-meter systems to manage carbon border adjustment exposure.
Lower Silesian Voivodeship
Wrocław technology parks anchor commercial segment demand through long-term power purchase agreement structures. Distribution system operator technical requirements here enforce stricter inverter compliance standards than northern regions. Wałbrzych and Legnica manufacturing zones specify higher-efficiency modules to maximize generation density on constrained footprints.
Masovian Voivodeship
Warsaw metropolitan commercial real estate drives mid-sized rooftop installations with fixed escalation contract terms. Government building retrofits qualify for enhanced auction pricing tiers under National Energy and Climate Plan alignment. Radom and Płock industrial suburbs represent emerging demand nodes with available transformer capacity.
Poland Solar Energy Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Poland's auction-driven procurement environment. The market exhibits tiered concentration where utility-scale sponsors with established grid relationships hold structural advantages over distributed generation entrants. Two dominant archetypes emerge: vertically integrated European energy majors with captive financing capacity, and regional specialists with direct enterprise sales channels. Competitive dynamics center on auction qualification speed and grid connection agreement security rather than pure module pricing.
Among French-based integrated utilities, Engie SA exemplifies the scale-driven archetype through utility-scale pipeline control. Danish project developers including Better Energy Holding A/S occupy positions within the Nordic financing model segment. Polish distributed generation specialists such as R. Power Sp. Z O.o. represent the direct-sales archetype dominating mid-sized rooftop categories. These three entities anchor distinct competitive vectors without overlapping segment focus.
| Leading Market Players |
|---|
| Engie SA |
| Better Energy Holding A/S |
| R. Power Sp. Z O.o. |
| Alseva Innowacje SA |
| Rwe AG |
| Sun Investment Group |
| Green Genius Sp. Z O.o. |
| Corab Sp. Z O.o. |
| Baywa AG |
| Others |
Value Network & Pricing Analysis
Rotterdam-Hamburg maritime corridors govern landed module costs for Polish developers, compressing margins when container rates spike while amplifying price gaps between premium n-type TOPCon and legacy p-type PERC shipments. This logistics chokepoint concentrates pricing power among distributors with bonded warehouse capacity near Gdańsk and Szczecin, forcing auction-qualified developers to absorb freight volatility or sacrifice grid connection timelines.
Pricing Analysis
Module pricing gaps between n-type TOPCon, p-type PERC, and pilot-stage heterojunction architectures stratify procurement tiers across Poland's auction system. Project sponsors face three-tier pricing structure across premium, standard, and economy levels, with efficiency ratings and carbon disclosure certification driving differentiation. Cost compression in standard-tier p-type modules is intensifying because Chinese ingot oversupply floods European spot markets. Industrial rooftop offtakers in Silesia exhibit highest price sensitivity, while utility-scale sponsors with secured grid agreements prioritize yield certainty over capital cost minimization.
Supply Chain Analysis
Polysilicon feedstock draws from Chinese ingot and wafer producers, South Korean cell manufacturers, and European module assemblers, creating layered dependency chains for Polish developers. Crystalline silicon wafers, silver metallization paste, and aluminum frames constitute critical component exposures. Single-source vulnerability concentrates in metallurgical-grade silicon refining capacity. Distribution runs through Rotterdam port consolidation, Hamburg intermodal hubs, and final-mile trucking to Silesian and Greater Poland project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
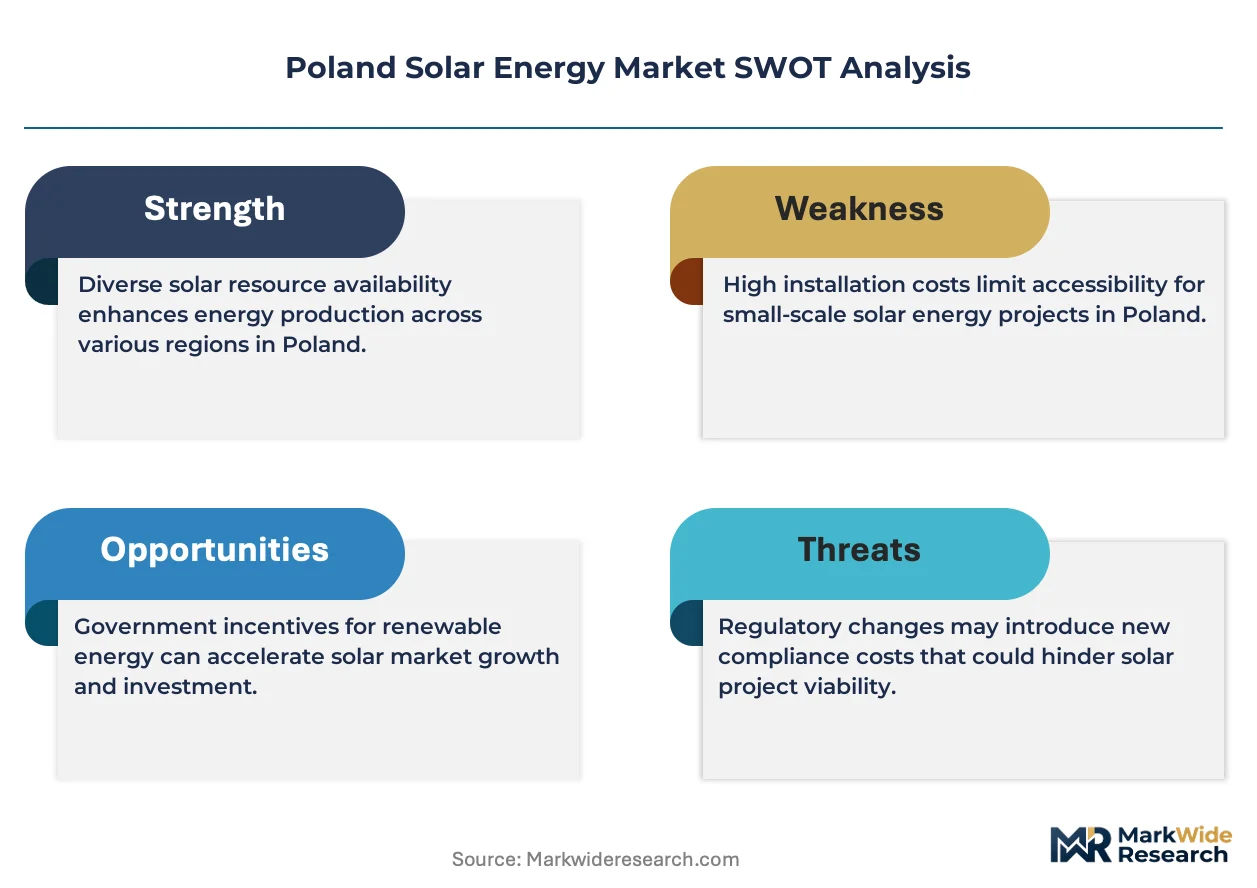
Poland's solar market functions as a defensive-moat arena where URE auction qualification history creates regulatory entrenchment that new entrants cannot rapidly replicate. Incumbent developers with secured grid connection agreements hold structural switching cost advantages.
For Market Incumbents: Entrench auction eligibility through preemptive grid connection deposits in Greater Poland voivodeship nodes before competitive rounds open. Secure brownfield substation access via long-term lease structures that block rival sponsors. Vertical integration into battery storage engineering teams addresses emerging URE co-location pricing tiers. Carbon border adjustment exposure among metals sector offtakers threatens demand concentration in Silesia.
For New Entrants and Emerging Players: Build out distributed generation capabilities in Masovian Voivodeship government building retrofits, where National Energy and Climate Plan alignment creates enhanced auction pricing eligibility. Target municipal infrastructure segments with lower incumbent saturation than industrial corridors. Direct enterprise sales channels bypass utility-scale queue congestion.
For Investors and Strategic Acquirers: Polish distributed generation specialists with captive enterprise customer relationships and URE auction track records represent the most defensible acquisition archetype. Long-term viability hinges on capacity market reform implementation and storage co-location mandate expansion. Watch for distribution system operator technical requirement tightening as inflection signal for compliance-capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Storage Co-location | Qualifies developers for enhanced URE auction pricing tiers under evolving capacity market reforms. |
| Grid Connection Pre-qualification | Brownfield substation deposits in Greater Poland secure lower-congestion interconnection queue positions. |
| Carbon Accounting Integration | Supply chain emissions documentation satisfies EU Green Deal alignment for preferential DSO treatment. |
| Enterprise PPA Aggregation | Industrial cluster procurement consolidation strengthens auction bidding leverage in metals and chemicals verticals. |
| Bifacial Technology Deployment | Dual-sided modules improve project economics on post-mining brownfields with elevated surface albedo. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility-scale project developers, distribution system operator planning officers, EPC contractors, and industrial offtaker energy managers; and secondary validation through URE auction results databases, Energy Regulatory Office interconnection queue filings, EU Green Deal implementation trackers, and Polish customs photovoltaic import records. Bottom-up project pipeline aggregation triangulated against top-down voivodeship-level capacity forecasts.
Forecast inputs span module efficiency migration curves, auction qualification success rates, grid connection timeline distributions, and carbon border adjustment mechanism exposure across manufacturing verticals. Segmentation modeling covers product type, application scale, cell architecture, and end-user category across the analysis window. CAGRs derive from installed capacity trajectory analysis and capital deployment pattern recognition. Polysilicon price volatility and freight rate indices feed supply chain sensitivity layers.
Sensitivities concentrate around URE auction rule modifications, distribution grid saturation thresholds in rural voivodeships, and EU Green Deal carbon intensity disclosure tightening. Forecasts reflect assumptions regarding auction schedule continuity and DSO technical requirement stability. Cross-checking against IEA renewable energy auction databases and European distribution system operator interconnection statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market