
 Spain Rooftop Solar Market | 2026-2036
Spain Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Rooftop Solar Market Analytics
Market Context
High-efficiency monocrystalline module tiers is reorganizing procurement patterns across Spain's distributed solar sector. Iberdrola leverages its utility-scale supply chain to secure volume pricing for rooftop portfolios. Solaria Energía specializes in vertically integrated panel-to-installation service bundles. Acciona Energía anchors its position through engineering-procurement-construction capabilities that reduce balance-of-system costs.
Technical Definition and Segments
Spain rooftop solar encompasses photovoltaic systems, solar water heating units, solar thermal collectors, and hybrid configurations mounted on building envelopes, typically employing silicon-based cells with conversion efficiencies between 20-22% and inverters rated for 230V single-phase or 400V three-phase grid synchronization to offset on-site electricity consumption. Photovoltaic systems dominate installed capacity while hybrid systems represent the fastest-expanding product category as battery storage economics improve. Residential customer segments command premium pricing for sub-10 kW installations, whereas commercial and industrial portfolios above 50 kW concentrate margin pools through economies of scale in procurement and installation labor.
Regulatory Framework
Spain's Ministry for the Ecological Transition enforces RD 244/2019 self-consumption frameworks, while EU Green Deal building performance standards and CE marking requirements for electrical safety shape product certification and market access pathways. These regulations eliminate grid access fees for installations below 100 kW and mandate net metering compensation mechanisms that shorten investor payback periods. Stakeholders must monitor proposed revisions to Spain's National Integrated Energy and Climate Plan and evolving technical specifications from the Spanish Electrical Grid Code as these will determine interconnection protocols and storage co-location eligibility for distributed assets.
Market Dynamics
Spain's rooftop solar sector faces acute pressure from module supply chain concentration in East Asia and the EU's forced labor due diligence mandates, which are rerouting procurement toward European and Southeast Asian manufacturers at higher unit costs.
Growth Catalysts
- RD 244/2019 net metering:Eliminated grid access fees for sub-100 kW installations, shortening payback periods for residential complexes in high-irradiance provinces.
- EU Green Deal building performance standards:Mandated rooftop solar readiness for new commercial construction, creating anchored demand across Catalonia's industrial zones.
- Monocrystalline PERC technology:Conversion efficiencies above 21% now standard for distributed installations, reducing roof space requirements for apartment blocks.
Market Restraints
- Polysilicon supply concentration:Xinjiang-origin material faces EU forced labor restrictions, forcing Spanish developers toward higher-cost European and Malaysian suppliers.
- Distribution network bottlenecks:Certified installer capacity concentrates in Madrid and Barcelona, leaving Galicia and Castile-La Mancha with 6-12 month project queues.
- Grid connection protocols:Spanish Electrical Grid Code technical specifications for storage co-location remain unresolved, delaying hybrid system deployments.
Strategic Opportunities
- Andalusian agricultural self-consumption:Irrigation cooperatives in Almería and Granada provinces present untapped demand for 50-500 kW ground-mounted rooftop arrays.
- Battery storage convergence:Lithium iron phosphate systems paired with rooftop PV unlock time-of-use arbitrage as Spain's regulated tariff structures evolve.
- Community energy frameworks:Pending revisions to Spain's National Integrated Energy and Climate Plan may legalize collective self-consumption across multi-building estates.
Industry Challenges
- Certified electrician scarcity:Spain's vocational training pipeline produces insufficient low-voltage specialists familiar with 400V three-phase inverter synchronization.
- Permit fragmentation:Municipal urban planning departments in Valencia and Málaga apply inconsistent interpretation of RD 244/2019, extending approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Rooftop Solar Market |
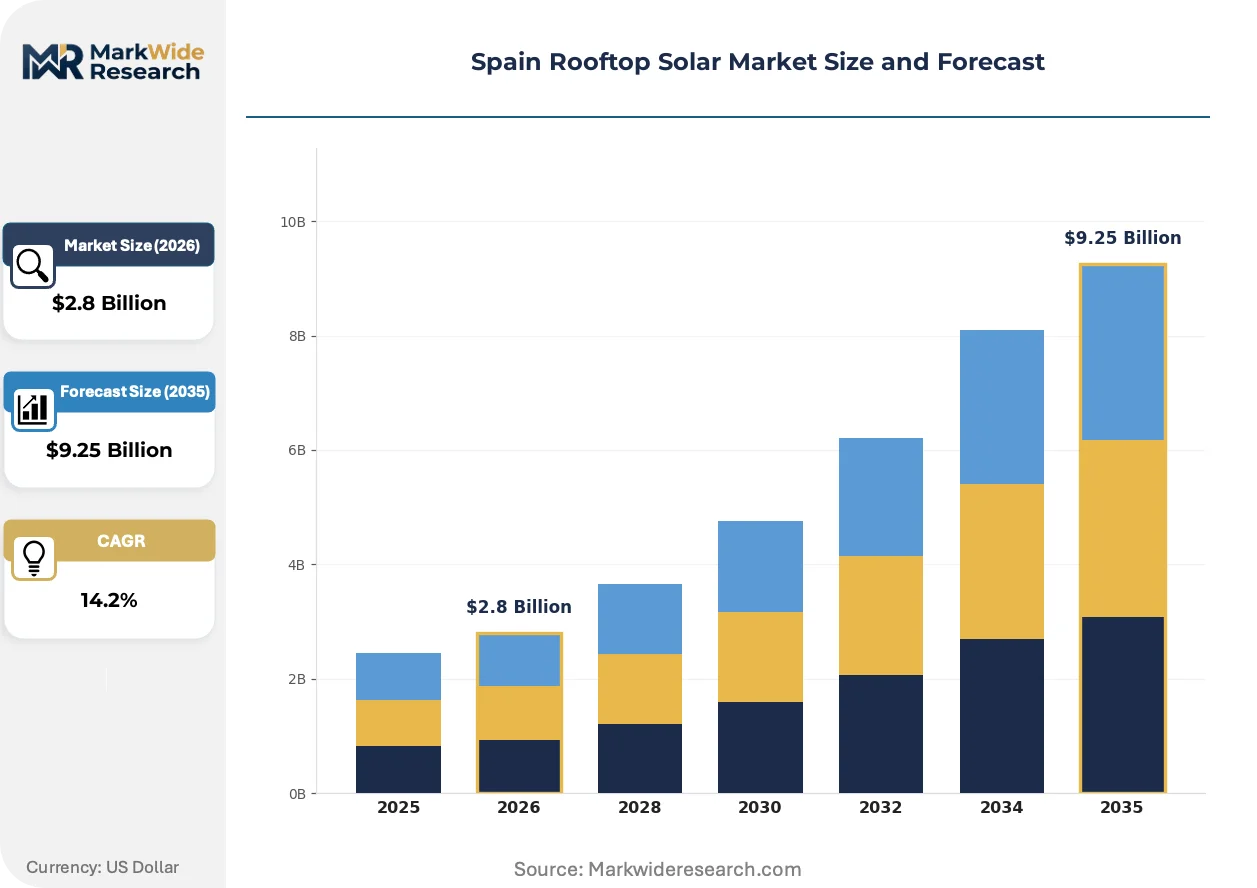
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Solar Water Heating, Solar Thermal, Hybrid Systems Customer Type: Residential, Commercial, Industrial, Governmental Installation Type: On-roof, Building-integrated, Ground-mounted, Off-grid Power Rating: Below 5 kW, 5 kW to 10 kW, 10 kW to 50 kW, Above 50 kW |
| Companies Covered | Zelestra Energy, Prodiel, Prosolia Energy, Endesa, Solaria Energía, Iberdrola, Matrix Renewables, Otovo, Acciona Energía, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Rooftop Solar Market Evolving Landscape
Module efficiency tiers and inverter intelligence are splitting procurement patterns across Spain's distributed solar sector, with premium specifications commanding widening price spreads as buyer sophistication increases.
High-efficiency monocrystalline modules is bifurcating the Spanish rooftop market between premium-tier imports and standard domestic assembly. Residential buyers in Barcelona and Madrid metros specify 21.5%+ efficiency panels despite 15-20% cost premiums. Commercial portfolios above 100 kW increasingly accept standard-tier modules to preserve project IRR thresholds.
Spain's Ministry for the Ecological Transition is tightening technical specifications for grid-connected inverters under evolving interpretations of RD 244/2019. Anti-islanding protection and reactive power capability requirements are forcing retrofit campaigns on pre-2020 installations. Industrial self-consumption projects in Basque Country and Navarre face accelerated compliance deadlines.
Aggregated procurement through energy service companies is displacing direct equipment purchasing among mid-size commercial buyers. Third-party ownership models now dominate 50-200 kW segments in Seville and Zaragoza. Installer networks are consolidating around platform-based customer acquisition rather than traditional referral channels.
Spain Rooftop Solar Market Segmentation
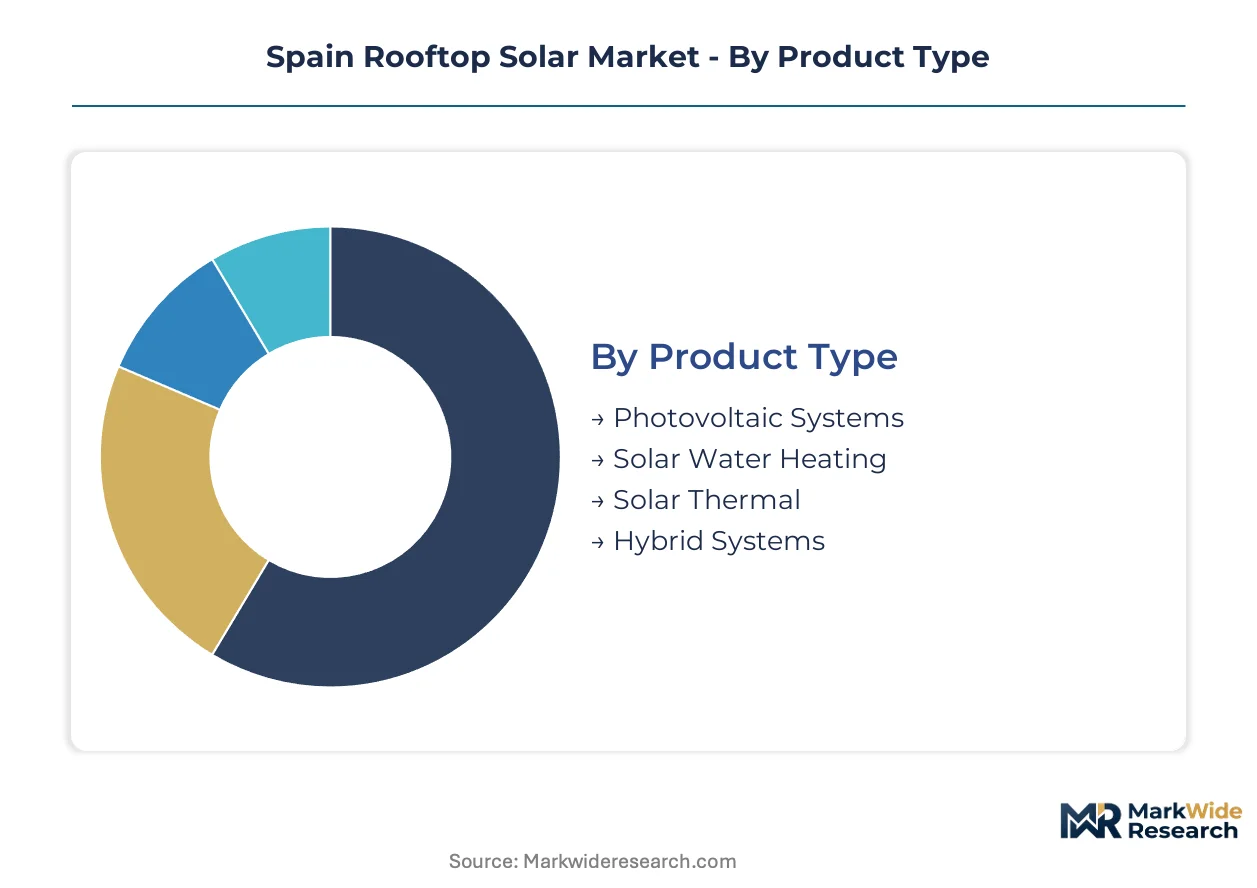
Spain's rooftop solar market fragments across four critical dimensions that determine project economics, regulatory treatment, and installer specialization. Understanding where margin pools concentrate within each category enables stakeholders to prioritize capital deployment and partnership strategies.
Product Type:
Margin concentration favors integrated system bundles over standalone components, with battery-ready configurations commanding premium pricing in Madrid and Barcelona metros.
- Photovoltaic Systems:Silicon-based cell arrays with 20-22% conversion efficiency dominate installed capacity across Spanish rooftops. Demand concentrates in Mediterranean coastal provinces where high irradiance levels and elevated electricity tariffs compress payback periods for residential complexes in Valencia and Málaga.
- Hybrid Systems:PV generation paired with lithium iron phosphate battery storage represents the most dynamic product category as RD 244/2019 net metering evolves. Industrial self-consumption projects in Basque Country anchor early deployments while regulatory clarity on storage co-location protocols remains pending.
- Solar Water Heating:Flat-plate and evacuated tube collectors for domestic hot water applications serve agricultural processing facilities in Andalusia.
- Solar Thermal:Concentrated heat generation systems target industrial process applications in Catalonia's chemical corridor.
The dominant share belongs to Photovoltaic Systems, while Hybrid Systems are climbing the fastest as battery economics improve.
Customer Type:
Commercial portfolios above 50 kW generate the steepest margin expansion through economies of scale in procurement and installation labor.
- Residential:Sub-10 kW installations command premium pricing per watt due to customer acquisition costs and permitting complexity. Apartment blocks in Barcelona and Madrid metros drive specification toward high-efficiency monocrystalline modules despite 15-20% cost premiums.
- Commercial:Mid-size enterprises and retail chains in Seville and Zaragoza increasingly adopt third-party ownership models to preserve balance sheet capacity. Aggregated procurement through energy service companies is displacing direct equipment purchasing in this segment.
- Industrial:Large manufacturing facilities in Navarre and Basque Country pursue self-consumption to hedge against volatile wholesale electricity markets.
- Governmental:Public building mandates under EU Green Deal building performance standards create anchored demand across municipal portfolios.
Commercial installations hold the dominant revenue position, though Residential adoption is expanding most quickly as financing products proliferate.
Installation Type:
Building-integrated configurations capture structural premiums by eliminating separate mounting hardware and satisfying aesthetic constraints in heritage districts.
- On-roof:Conventional rack-mounted systems atop existing roof structures constitute the standard deployment method. Agricultural cooperatives in Almería and Granada provinces favor this approach for 50-500 kW ground-mounted rooftop arrays on warehouse and processing facilities.
- Building-integrated:Solar tiles and facade-embedded modules replace conventional building materials during construction or renovation. New commercial construction in Catalonia's industrial zones faces EU Green Deal mandates for rooftop solar readiness that favor integrated approaches.
- Ground-mounted:Elevated structures on commercial rooftops optimize tilt angles and spacing for maximum yield capture.
- Off-grid:Standalone systems with battery backup serve remote agricultural operations and mountain tourism facilities outside distribution network reach.
On-roof deployments maintain the dominant share, while Building-integrated approaches are gaining share fastest through regulatory tailwinds for new construction.
Power Rating:
Regulatory thresholds at 100 kW under RD 244/2019 create distinct margin zones, with sub-100 kW projects benefiting from eliminated grid access fees.
- Above 50 kW:Commercial and industrial portfolios concentrate margin pools through standardized engineering and bulk procurement. Projects in this bracket face complex interconnection protocols under the Spanish Electrical Grid Code but achieve superior per-watt economics.
- 10 kW to 50 kW:Small commercial installations and large residential estates occupy a competitive middle ground where installer capacity constraints in Galicia and Castile-La Mancha extend project queues to 6-12 months.
- 5 kW to 10 kW:Standard residential systems align with typical household consumption profiles and net metering compensation structures.
- Below 5 kW:Compact installations for apartments and small dwellings face higher relative soft costs but benefit from streamlined municipal approvals in compliant jurisdictions.
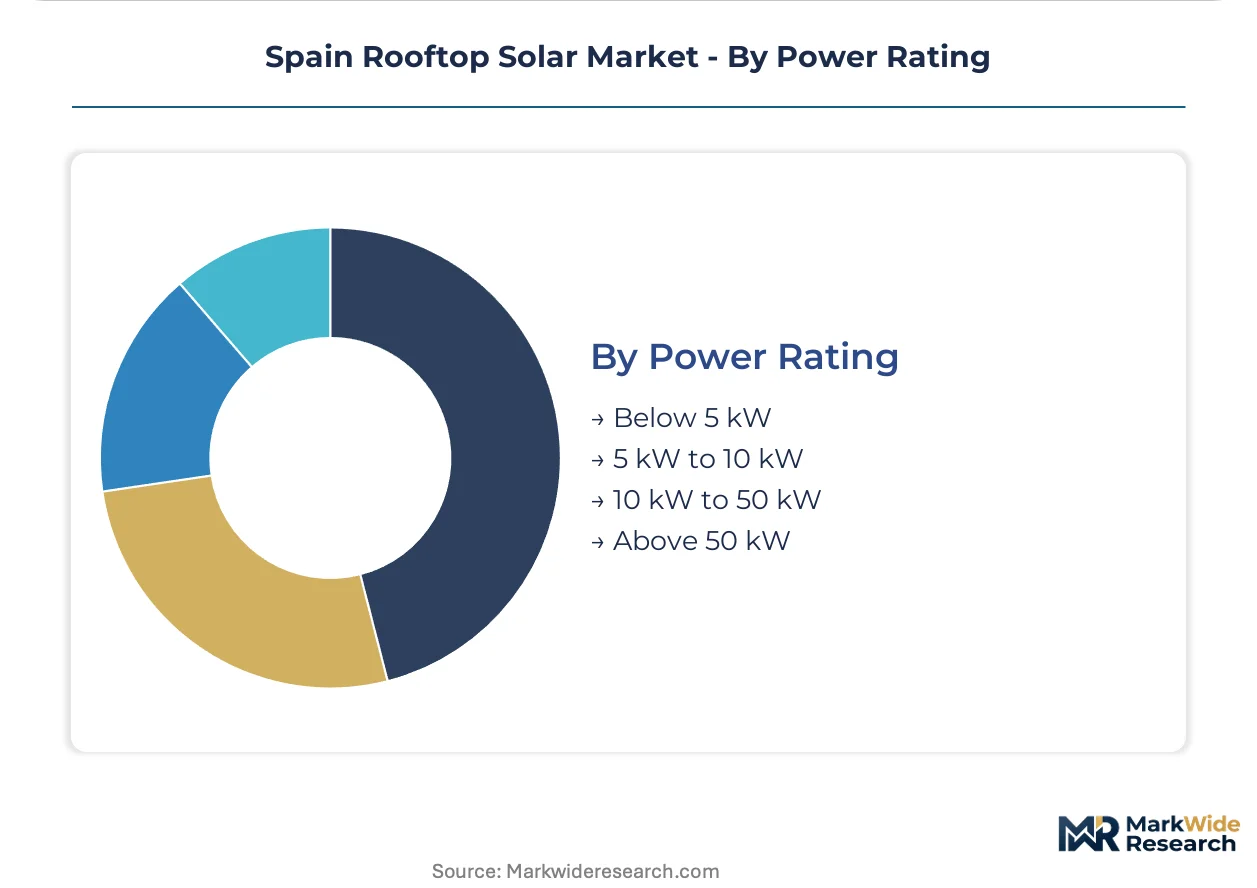
The Above 50 kW bracket commands the dominant revenue position, while the 10 kW to 50 kW range is expanding most quickly as small commercial buyers accelerate adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in Mediterranean coastal provinces show lowest price elasticity, accepting 15-20% premiums for high-efficiency modules, while agricultural cooperatives in interior regions prioritize per-watt economics over specifications.
Andalusia
Irrigation cooperatives in Almería and Granada provinces drive 50-500 kW ground-mounted rooftop arrays on warehouse facilities. RD 244/2019 net metering eliminates grid access fees for these sub-100 kW installations. Seville anchors commercial third-party ownership models where energy service companies aggregate procurement for mid-size enterprises.
Catalonia
Industrial zones around Barcelona face EU Green Deal mandates for rooftop solar readiness in new commercial construction. The regional government enforces building performance standards that favor building-integrated configurations in heritage districts. Tarragona's chemical corridor concentrates solar thermal demand for industrial process heat applications.
Madrid
Apartment blocks in the capital metro specify 21.5%+ efficiency monocrystalline modules despite cost premiums, driven by limited roof space and elevated electricity tariffs. The Ministry for the Ecological Transition operates from Madrid, streamlining permit interpretations for compliant municipalities. Certified installer capacity concentrates here, reducing project queues versus peripheral regions.
Basque Country
Large manufacturing facilities in Navarre pursue self-consumption to hedge volatile wholesale electricity markets. The Spanish Electrical Grid Code imposes accelerated compliance deadlines for anti-islanding protection and reactive power capability. Bilbao anchors early hybrid system deployments pending regulatory clarity on storage co-location protocols.
Valencia
Mediterranean coastal irradiance levels and elevated tariffs compress payback periods for residential complexes in Málaga and Alicante provinces. Municipal urban planning departments apply inconsistent RD 244/2019 interpretations, extending approval timelines. Agricultural processing facilities favor conventional on-roof rack-mounted systems for 50-500 kW deployments.
Spain Rooftop Solar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Spain's rooftop solar sector. Vertically integrated specialists control module supply chains and secure volume pricing for distributed portfolios. Engineering-procurement-construction contractors reduce balance-of-system costs through standardized installation protocols. Platform-based customer acquisition models displace traditional referral channels among mid-size commercial buyers. Dominant competitive moves include aggregated procurement through energy service companies and installer network consolidation around digital acquisition platforms.
Among Spanish energy conglomerates, Iberdrola and Endesa occupy positions that leverage utility-scale supply chain relationships for rooftop portfolio pricing. Solaria Energía exemplifies the vertically integrated archetype, bundling panel manufacturing through installation services. Acciona Energía anchors engineering-procurement-construction capabilities that compress project costs for commercial and industrial segments. These three players represent distinct strategic positions: supply chain scale, vertical integration, and construction execution respectively.
| Leading Market Players |
|---|
| Zelestra Energy |
| Prodiel |
| Prosolia Energy |
| Endesa |
| Solaria Energía |
| Iberdrola |
| Matrix Renewables |
| Otovo |
| Acciona Energía |
| Others |
Value Network & Pricing Analysis
RD 244/2019 net metering eligibility gates both supplier qualification and price differentiation simultaneously, as CE marking compliance and anti-islanding certification requirements filter out uncertified equipment while enabling premium pricing for compliant battery-ready configurations in Madrid and Barcelona metros.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value for Spanish rooftop solar vendors, with third-party ownership models in Seville and Zaragoza embedding maintenance obligations into long-term power purchase agreements. Price differentiation rests on module efficiency grades and installer certification levels, with 21.5%+ efficiency monocrystalline panels commanding 15-20% premiums over standard tiers. Cost compression in the commercial 50-200 kW bracket is intensifying because energy service companies aggregate procurement volumes and squeeze installer margins. Residential sub-10 kW buyers show lowest price sensitivity, accepting specification premiums for limited roof space, while agricultural cooperatives in Almería prioritize per-watt economics over performance tiers.
Supply Chain Analysis
Inventory lead times for lithium iron phosphate battery modules and three-phase inverters have extended as Spanish developers reroute procurement away from Xinjiang-origin polysilicon toward European and Malaysian suppliers. Module assembly concentrates in China, Vietnam, and Malaysia, while inverter manufacturing anchors in Germany, China, and Taiwan. Raw material dependencies span polysilicon feedstock, aluminum framing, and copper cabling. Supply chain risk centers on EU forced labor due diligence enforcement disrupting established procurement channels. Distribution runs through certified installer networks that concentrate capacity in Madrid and Barcelona, leaving peripheral regions with extended project queues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's rooftop solar market is entering a cyclical recovery phase as RD 244/2019 regulatory clarity and EU Green Deal building mandates synchronize to compress payback periods and unlock anchored demand across new commercial construction.
For Market Incumbents: Secure backward integration into battery storage distribution to capture hybrid system premiums before regulatory clarity on co-location protocols resolves. Consolidate installer network partnerships in Galicia and Castile-La Mancha where certified electrician scarcity extends project queues and threatens market share erosion to platform-based customer acquisition models. For New Entrants and Emerging Players: CE marking fast-track for 400V three-phase inverters with reactive power capability unlocks entry into Basque Country industrial self-consumption projects facing accelerated compliance deadlines. Target agricultural irrigation cooperatives in Andalusia's Almería and Granada provinces with ground-mounted rooftop arrays sized for 50-500 kW net metering thresholds, leveraging equipment leasing structures to bypass upfront capital barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across the 10-50 kW small commercial segment as platform-based customer acquisition displaces traditional referral channels and reduces customer acquisition costs. Over a five-to-ten year horizon, vertically integrated specialists with captive module supply and installation networks present superior acquisition targets versus pure-play developers exposed to procurement volatility. Watch for resolution of Spanish Electrical Grid Code storage co-location specifications as the inflection signal triggering hybrid system deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Storage Vertical Integration | Captures hybrid system premiums in Madrid and Barcelona metros as RD 244/2019 evolves. |
| Certified Installer Network Expansion | Reduces project queues in Galicia and Castile-La Mancha where capacity constraints concentrate. |
| CE Marking Fast-Track Investment | Accelerates market access for three-phase inverters targeting Basque Country industrial compliance deadlines. |
| Agricultural Cooperative Leasing Programs | Unlocks 50-500 kW deployments across Almería irrigation facilities through equipment-as-service structures. |
| Platform-Based Customer Acquisition | Displaces traditional referral channels in Seville and Zaragoza commercial segments to compress acquisition economics. |
Research Methodology
A standing panel of utility planning officers, EPC contractors, certified installer network heads, and grid interconnection specialists provided ongoing calibration across primary interview cycles, with secondary validation drawing from RD 244/2019 regulatory filings, Spanish Electrical Grid Code technical specifications, EU Green Deal building performance directives, and customs data on module import origins. Bottom-up project pipeline tracking across Andalusia, Catalonia, Madrid, Basque Country, and Valencia regions triangulated against top-down capacity deployment estimates from the Ministry for the Ecological Transition.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product type, customer category, installation configuration, and power rating bracket. CAGRs were derived from regression analysis of historical deployment trajectories and regulatory elasticity assumptions, incorporating lithium iron phosphate battery cost curves and monocrystalline PERC efficiency improvement rates as technology-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained RD 244/2019 net metering stability, EU forced labor enforcement intensity, and grid connection protocol resolution would require recalibration. Forecasts reflect documented assumptions regarding module supply chain rerouting and installer capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Global Solar PV Balance of System Market