

Bifacial Solar Module Market Size, Share, and Industry Trends Forecast 2026-2036
Bifacial Solar Module Market Insights
Module-plus-tracker bundling is pivoting procurement patterns across the bifacial supply chain. Jinko Solar leverages integrated manufacturing scale to dominate high-volume utility contracts. LONGi Green Energy Technology anchors premium monocrystalline supply through captive wafer capacity. Trina Solar differentiates via vertically controlled cell-to-module production for floating installation projects.
Bifacial solar modules capture irradiance from both front and rear surfaces through transparent backsheet or dual-glass construction, typically achieving bifaciality factors of 70-90% and power outputs exceeding 600W in commercial formats. Their primary purpose is maximizing energy yield per installed watt across high-albedo environments including desert, snow, and reflective rooftop settings. Monocrystalline modules command the dominant value share due to superior conversion efficiency and compatibility with PERC and tunnel oxide passivated contact architectures. Utility-scale projects absorb the majority of volume as developers exploit economies of scale and standardized mounting infrastructure. Floating installations represent the fastest-growing application niche, driven by land scarcity and evaporative cooling benefits that enhance rear-side generation.
China's MIIT enforces GB standards that mandate minimum efficiency thresholds and module durability testing, directly filtering market access for domestic and imported products. The EU Green Deal and F-Gas Regulation shape European demand by linking project finance to lifecycle carbon intensity and restricting fluorinated greenhouse gas use in manufacturing processes. India's BIS certification and PLI scheme create tiered procurement incentives that favor domestic cell and module assembly. Stakeholders must monitor evolving albedo modeling standards and tracker compatibility protocols as these determine bankable yield projections and insurance underwriting terms.
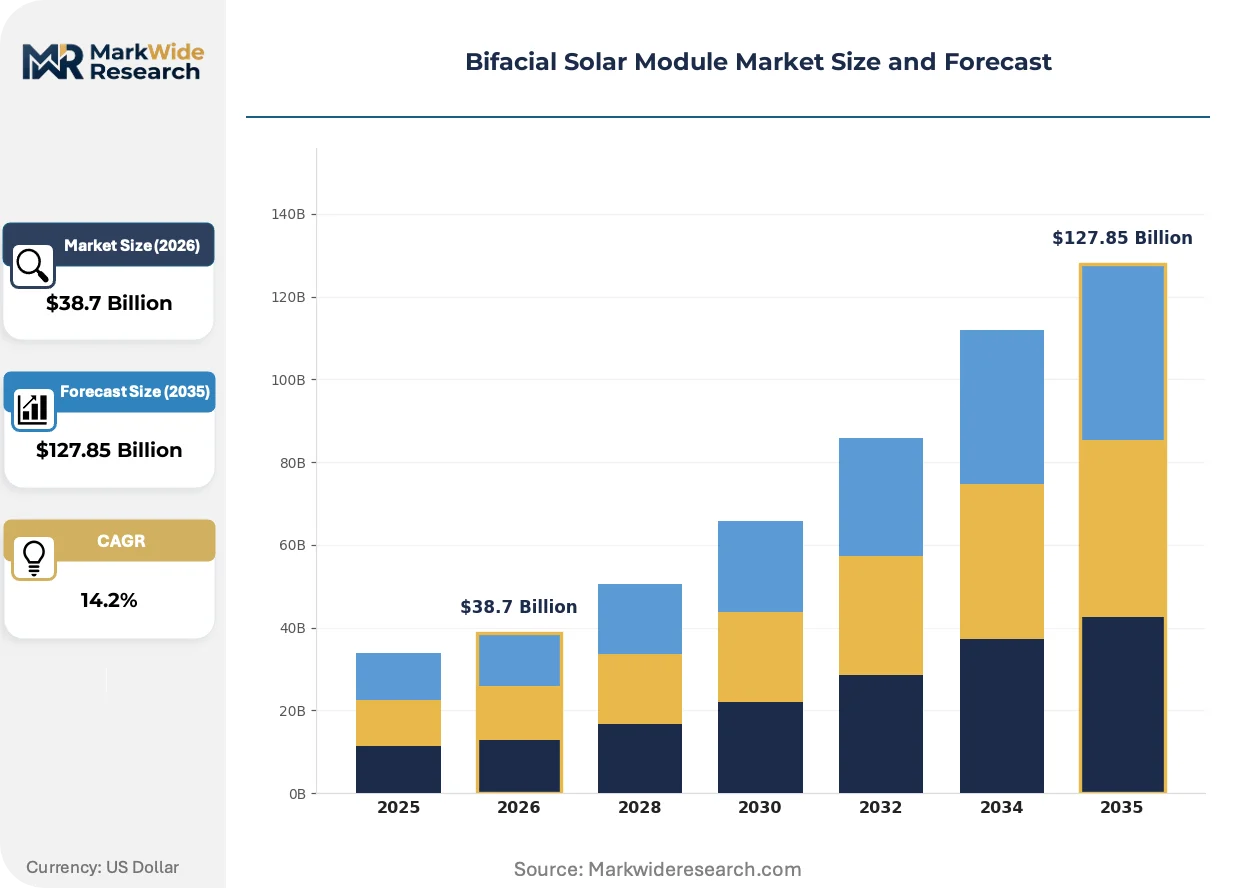
Market Dynamics
Tracker-plus-module bundling is compressing procurement cycles and concentrating contract awards among manufacturers with captive cell capacity and domestic content certifications. This structural shift rewards vertically integrated producers while squeezing pure-play module assemblers out of utility-scale tenders.
Growth Catalysts
- China's dual carbon goals:Binding emissions targets under MIIT mandates accelerate deployment of high-efficiency architectures across Inner Mongolia and Gansu corridor projects.
- Utility-scale developers:American Southwest installations exploit high-albedo desert terrain to maximize rear-side generation and levelized cost advantages.
- EU Green Deal conditionality:Project finance eligibility tied to lifecycle carbon intensity filters procurement toward low-carbon manufacturing supply chains.
Market Restraints
- Polysilicon input volatility:Refining capacity concentration in Xinjiang creates exposure to forced labor audits and trade remedy actions.
- Albedo modeling uncertainty:Absence of standardized rear-side irradiance measurement protocols complicates bankable yield projections and insurance underwriting.
- Silver metallization cost:Cell-level silver paste requirements expose module economics to precious metal price swings and thrifting limitations.
Strategic Opportunities
- Floating photovoltaic installations:Evaporative cooling effects and land scarcity constraints in Japan and South Korea drive demand for moisture-resistant dual-glass construction.
- India's PLI scheme:Domestic cell and module assembly incentives create localized supply hubs for Middle East and African export markets.
- Agrivoltaics convergence:Bifacial modules mounted above crops capture reflected light from vegetation while preserving agricultural output.
Industry Challenges
- Tracker compatibility engineering:Rear-side shading from single-axis tracker torque tubes degrades bifacial gain factors and requires structural redesign.
- Certification timeline compression:IEC 61215 and IEC 61730 testing cycles lag behind cell efficiency roadmaps, delaying product commercialization.
- Skill scarcity in yield modeling:Shortage of engineers proficient in bifacial performance simulation tools limits developer confidence in energy projections.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bifacial Solar Module Market Trends and Innovations
Cell architecture evolution and mounting system integration are compressing balance-of-system costs while regulatory carbon accounting reshapes manufacturing location decisions. These forces are reconfiguring competitive advantage around process control and supply chain transparency.
Tunnel oxide passivated contact cells are unifying front and rear surface passivation to eliminate metal-induced recombination losses. Utility-scale developers in the American Southwest specify these architectures for 600W-plus module formats. The technology is unifying premium and standard product tiers by collapsing efficiency premiums into mainstream procurement specifications.
EU F-Gas Regulation restrictions on fluorinated greenhouse gas use in manufacturing processes are redirecting module sourcing toward European and Southeast Asian assembly plants. Project developers seeking Green Deal-compliant finance must document supply chain carbon intensity through mass-balance certification. Floating installations in the Netherlands and France face heightened scrutiny of backsheet material provenance.
Engineering-procurement-construction firms are consolidating module and tracker specifications into single-source tender packages. This bundling displaces component-level bidding and concentrates contract awards among integrated manufacturers with in-house tracker partnerships. Procurement concentration is most visible in Saudi Arabia's utility-scale pipeline and India's Rajasthan solar parks.
Bifacial Solar Module Market Segmentation
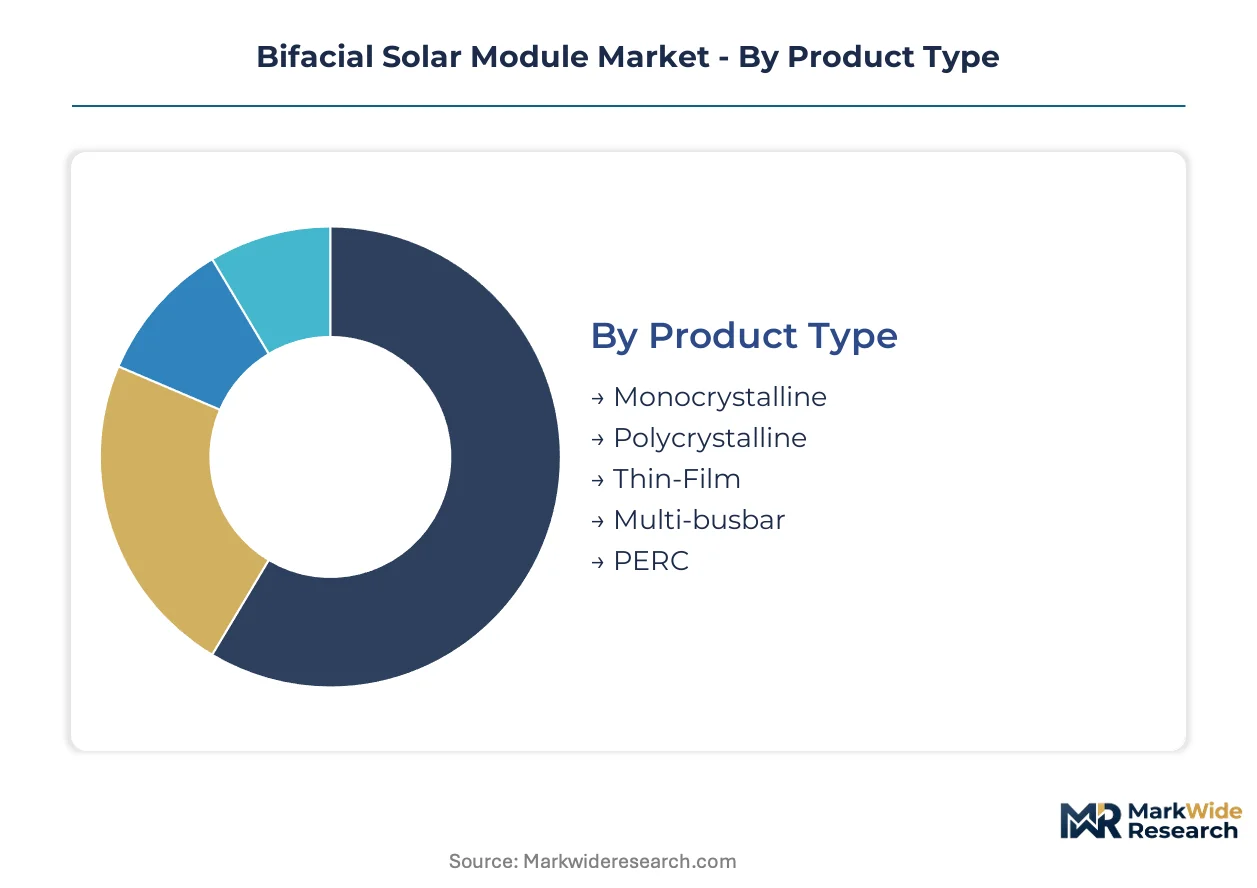
Bifacial module procurement splits along efficiency requirements, mounting constraints, and project finance structures. Buyers prioritize conversion performance, albedo compatibility, and tracker integration when selecting across these dimensions.
Product Type:
Cost tier separates buyers seeking premium efficiency from those optimizing capex per watt.
- Monocrystalline:Uniform silicon crystal structure delivers conversion efficiencies exceeding 22% in commercial formats. Utility-scale developers in the American Southwest and China's Inner Mongolia corridor specify these architectures to maximize rear-side generation in high-albedo desert terrain. Monocrystalline leads volumes today; multi-busbar is gaining share fastest.
- Multi-busbar:Reduced ribbon width cuts shading losses and improves current collection across cell surfaces. Floating installation projects in Japan and South Korea specify these modules for moisture-resistant dual-glass construction where evaporative cooling enhances rear-side output.
- PERC:Passivated emitter and rear contact architecture boosts efficiency through reduced recombination losses.
- Polycrystalline:Multi-crystal silicon ingots offer lower manufacturing cost with moderate efficiency tradeoffs.
- Thin-Film:Cadmium telluride or CIGS layers enable flexible substrate applications where weight constraints dominate.
Monocrystalline commands procurement priority where levelized cost drives tender awards; multi-busbar formats are climbing fastest in specialized applications.
Application:
Volume scale determines project finance structures and module specification stringency.
- Utility-Scale Projects:Installations exceeding 50MW exploit economies of scale and standardized mounting infrastructure. Developers across northwestern India and Saudi Arabia's pipeline bundle modules with tracker systems to compress procurement cycles and maximize rear-side irradiance capture.
- Agricultural Farms:Agrivoltaic configurations mount bifacial modules above crops to capture reflected light from vegetation while preserving agricultural output. France and the Netherlands deploy these systems where land scarcity and EU Green Deal conditionality intersect.
- Commercial Installations:Rooftop and carport deployments serve corporate offtakers seeking renewable energy certificates.
- Parking Structures:Canopy-mounted systems combine shade provision with distributed generation.
- Telecommunication Stations:Remote power requirements drive demand for compact, high-reliability formats.
Utility-scale absorbs dominant procurement volumes; agricultural farms represent the steepest expansion trajectory.
Installation Type:
Geography and site constraints dictate mounting system selection and rear-side exposure optimization.
- Tracker Systems:Single-axis tracking follows solar azimuth to boost front-side yield while torque tube spacing engineering manages rear-side shading degradation. Procurement concentration is most visible in India's Rajasthan solar parks and Saudi Arabia's utility-scale pipeline where EPC firms consolidate module-tracker specifications.
- Floating:Pontoon-mounted arrays exploit evaporative cooling effects and eliminate land use conflicts. Japan and South Korea lead deployment where reservoir availability and cooling-enhanced rear-side generation align.
- Ground-Mounted:Fixed-tilt structures dominate cost-sensitive deployments with standardized foundation requirements.
- Roof-Mounted:Ballasted or attached systems serve commercial and industrial building stock with load-bearing constraints.
- Building-Integrated:Façade and skylight applications prioritize architectural integration over maximum yield.
Ground-mounted configurations retain volume leadership; floating installations are expanding most quickly in East Asian markets.
End User:
Customer type shapes procurement sophistication and domestic content certification requirements.
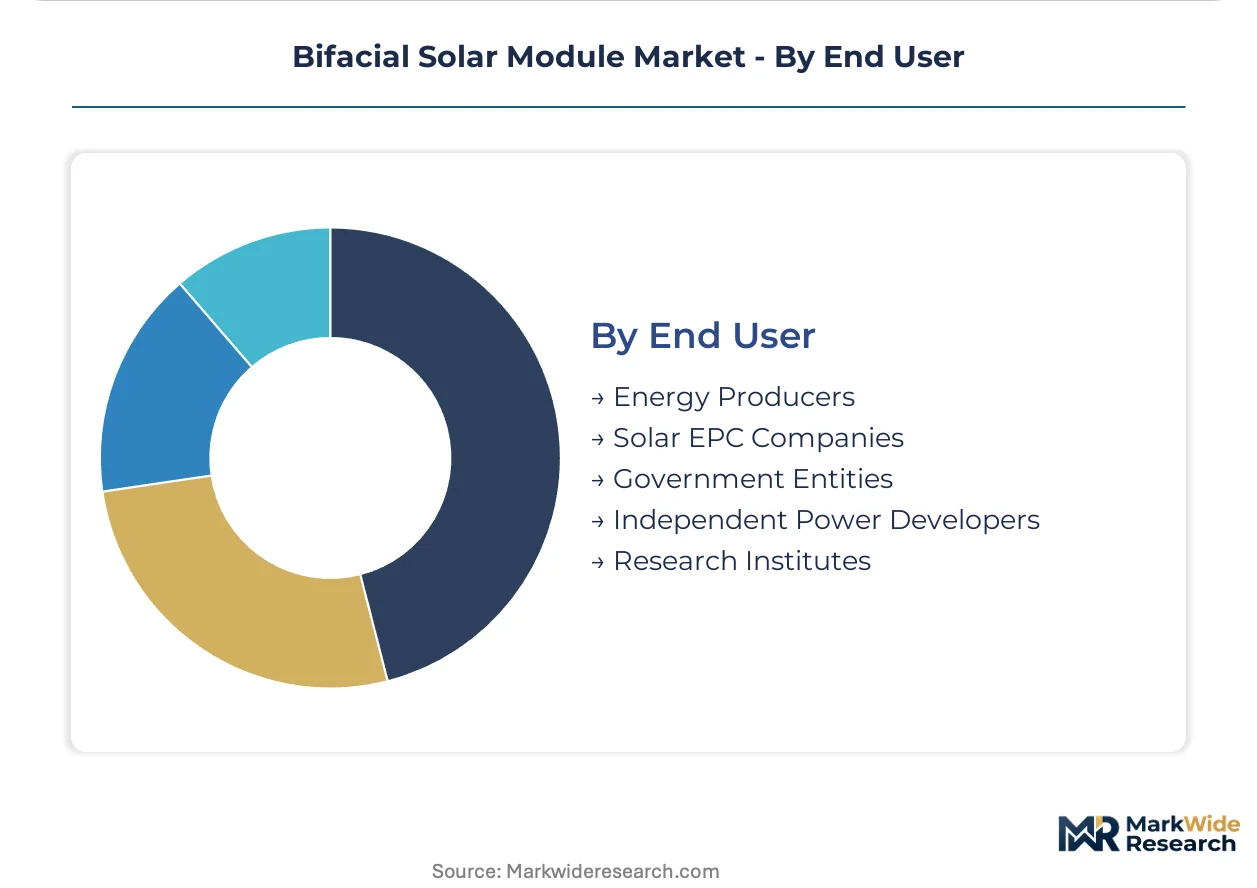
- Energy Producers:Independent power producers and utilities operate under long-term power purchase agreements that demand bankable yield projections. These buyers specify IEC-certified modules and enforce supply chain carbon documentation to secure EU Green Deal-compliant project finance.
- Solar EPC Companies:Engineering-procurement-construction firms consolidate component sourcing to reduce interface risk and accelerate construction timelines. India's PLI scheme incentives drive these contractors toward domestic cell and module assembly hubs.
- Government Entities:Public procurement mandates domestic content thresholds and lifecycle carbon intensity screening.
- Independent Power Developers:Project sponsors seek technology differentiation to secure offtake contracts.
- Research Institutes:Testing and demonstration programs validate emerging cell architectures.
Energy producers dominate contract values today; solar EPC companies are capturing procurement share fastest through bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bifacial solar module manufacturing scaled first through Chinese industrial policy support in the early 2010s, establishing the technological and cost foundations that now shape procurement patterns across utility-scale markets worldwide.
United States
Utility-scale developers in the American Southwest exploit high-albedo desert terrain across Arizona and Nevada to maximize rear-side generation. The Inflation Reduction Act's domestic content bonuses steer procurement toward cell and module assembly facilities in Georgia and Ohio. Tracker bundling concentrates contract awards among producers with captive wafer capacity and compliant supply chains.
China
MIIT-enforced GB standards mandate minimum efficiency thresholds that filter market access for domestic and imported products. The dual carbon goals accelerate deployment of high-efficiency architectures across Inner Mongolia and Gansu corridor projects. Manufacturing clusters in Hefei and Xian anchor vertically integrated production from polysilicon refining through module assembly.
India
Northwestern states Rajasthan and Gujarat host utility-scale installations where developers bundle modules with tracker systems to compress procurement cycles. BIS certification and PLI scheme incentives create tiered procurement that favors domestic cell and module assembly in Andhra Pradesh and Tamil Nadu. Solar park infrastructure concentrates demand around Bhadla and Pavagada complexes.
Germany
Agrivoltaic configurations in Bavaria and Baden-Württemberg mount bifacial modules above crops to capture reflected light while preserving agricultural output. EU Green Deal conditionality ties project finance eligibility to lifecycle carbon intensity documentation. Floating installations in Brandenburg lakes face heightened scrutiny of backsheet material provenance under F-Gas Regulation restrictions.
Japan
Reservoir-based floating photovoltaic arrays in Hyogo and Chiba prefectures exploit evaporative cooling effects that enhance rear-side generation. METI procurement guidelines prioritize moisture-resistant dual-glass construction for humid coastal environments. Land scarcity constraints accelerate deployment in densely populated Kanto and Kansai corridors.
Bifacial Solar Module Market Competitive Landscape
The competitive structure tilts toward vertically integrated producers with captive cell capacity and domestic content certifications. Pure-play module assemblers face exclusion from utility-scale tenders as engineering-procurement-construction firms consolidate component sourcing into single-source packages. Three archetypes dominate: integrated manufacturers controlling wafer-to-module production, regional specialists leveraging PLI scheme incentives, and technology licensors monetizing cell architecture patents. Capacity expansion and strategic tracker partnerships constitute the dominant competitive moves.
Among China-based integrated producers, Jinko Solar, LONGi Green Energy Technology, and Trina Solar occupy positions that exemplify the scale-driven archetype. These entities anchor procurement concentration through in-house wafer capacity and domestic content certifications across multiple geographies. Their representation within utility-scale tender awards reflects structural advantages in bundling negotiations rather than discrete product differentiation.
| Leading Market Players |
|---|
| Jinko Solar |
| LONGi Green Energy Technology |
| JA Solar Technology |
| Trina Solar |
| Canadian Solar |
| First Solar |
| Hanwha Q CELLS |
| Risen Energy |
| Astronergy |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers anchored in China's Xinjiang and Hefei manufacturing clusters exert asymmetric pricing power through captive polysilicon refining and wafer capacity, compressing margins for pure-play module assemblers while insulating integrated incumbents from silver paste and aluminum frame cost volatility.
Pricing Analysis
Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation resting on IEC certification tier and volume scale commitments. Premium pricing accrues to dual-glass modules with tunnel oxide passivated contact architectures, while standard PERC formats face intensifying cost compression from polysilicon spot price fluctuations. Independent power producers exhibit highest price sensitivity; energy producers with Green Deal-compliant project finance demonstrate lowest.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale buyer demand across India's Rajasthan solar parks and Saudi Arabia's utility-scale pipeline, bypassing traditional distributor networks. Manufacturing concentrates in China, Vietnam, and Malaysia, with polysilicon ingots, silver metallization paste, and tempered glass as critical inputs. Single-source vulnerability in Xinjiang polysilicon refining exposes the chain to forced labor audit disruptions and trade remedy actions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bifacial solar module market functions as a geographic-arbitrage play between China's MIIT-enforced efficiency mandates and India's PLI scheme incentives, with domestic content bonuses in the United States widening cost differentials for cell and module assembly.
For Market Incumbents: To counter procurement concentration from tracker-plus-module bundling, secure captive wafer capacity through backward integration into polysilicon refining or joint ventures in Southeast Asian manufacturing hubs, while accelerating IEC 61215 certification timelines to match cell efficiency roadmaps. For New Entrants and Emerging Players: India's PLI scheme in Andhra Pradesh and Tamil Nadu opens a window for regional specialists to capture Middle East and African export demand, targeting floating installation projects in Japan and South Korea with moisture-resistant dual-glass construction as the most penetrable niche. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play module assemblers lacking captive cell capacity, though long-term viability across the projection horizon favors integrated manufacturers with domestic content certifications; watch albedo modeling standardization as the inflection signal for bankable yield projection confidence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Xinjiang refining capacity secures supply chain transparency for EU Green Deal-compliant project finance eligibility. |
| Tracker System Partnership | Single-axis compatibility engineering with torque tube spacing optimization preserves bifacial gain factors in utility-scale tenders. |
| Floating Installation Certification | Moisture-resistant dual-glass validation unlocks reservoir-based deployment in Japan's Kanto corridor. |
| Domestic Content Assembly Expansion | Georgia and Ohio facilities capture Inflation Reduction Act bonuses for American Southwest utility developers. |
| Tunnel Oxide Passivated Contact Licensing | Cell architecture patents monetize efficiency premiums as mainstream procurement specifications shift. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with utility planning officers, EPC contractors, IPP project developers, and polysilicon procurement leads with secondary validation against EIA data, IEA renewable energy reports, FERC interconnection filings, and project development databases. Bottom-up module shipment tracking and top-down capacity installation estimates were triangulated to anchor volume figures.
Comparable-period anchoring linked historical deployment data to forward projections across the analysis window, with segmentation modeling across cell architecture type, installation format, project scale tier, and regional regulatory framework. CAGRs were derived from slope-intercept fitting of annualized capacity additions, incorporating silver price volatility, albedo assumption sensitivity, and tracker penetration rates as industry-specific inputs.
Revisions become necessary when forced labor audit findings disrupt polysilicon supply, MIIT efficiency thresholds escalate, or F-Gas Regulation restrictions tighten manufacturing location requirements; forecasts reflect documented assumptions around domestic content bonus continuity and IEC certification timeline compression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.