
 US Residential Solar PV Market | 2026-2036
US Residential Solar PV Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential Solar PV Market Intelligence
Suburban homeowners with high utility bills is redrawing the US residential solar PV customer map as urban renters and commercial buyers lose relative share. Sunrun leverages its vertically integrated installation and financing platform to dominate the direct-to-consumer channel. Tesla sustains brand pull through its Solar Roof product architecture and integrated Powerwall storage bundling. Qcells anchors domestic manufacturing capacity with its Georgia cell and module factory, competing on supply chain proximity rather than pure cost.
US residential solar PV comprises photovoltaic systems installed on single-family homes, townhouses, and small multifamily buildings, typically using silicon-based cells with power ratings from 5 kW to 20 kW and DC-to-AC conversion efficiencies between 19% and 22%. These systems generate on-site electricity to offset retail utility rates, reduce grid dependence, and in hybrid configurations provide backup power during outages. Monocrystalline technology leads installed capacity due to superior efficiency and declining wafer costs, while bifacial modules represent the fastest-growing technology segment as homeowners seek higher energy yield per rooftop square foot. Grid-tied systems dominate the system type landscape, though hybrid configurations with battery storage capture expanding margin pools as net metering reforms in California and other states reduce the value of pure export models.
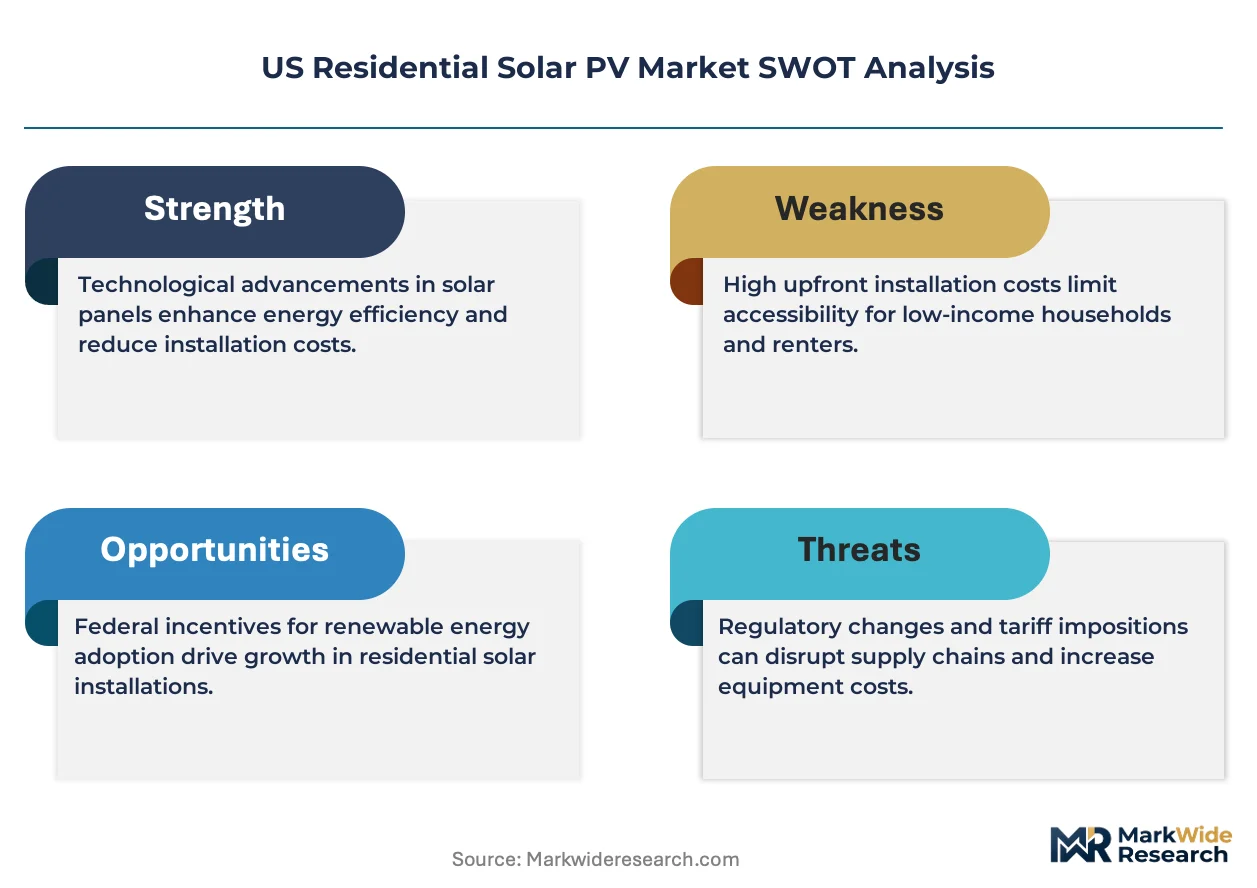
The Inflation Reduction Act, NREL certification protocols, and state-level public utility commission rulings collectively shape equipment eligibility, installer qualification, and interconnection timelines across US jurisdictions. The IRA's domestic content bonus credit rewards projects using American-made cells and modules, redirecting procurement toward Qcells and REC supply. Stakeholders must monitor evolving state net metering policies and utility rate structure reforms, as these regulatory shifts determine whether battery-backed hybrid systems or simpler grid-tied configurations deliver superior customer economics in each service territory.
Market Dynamics
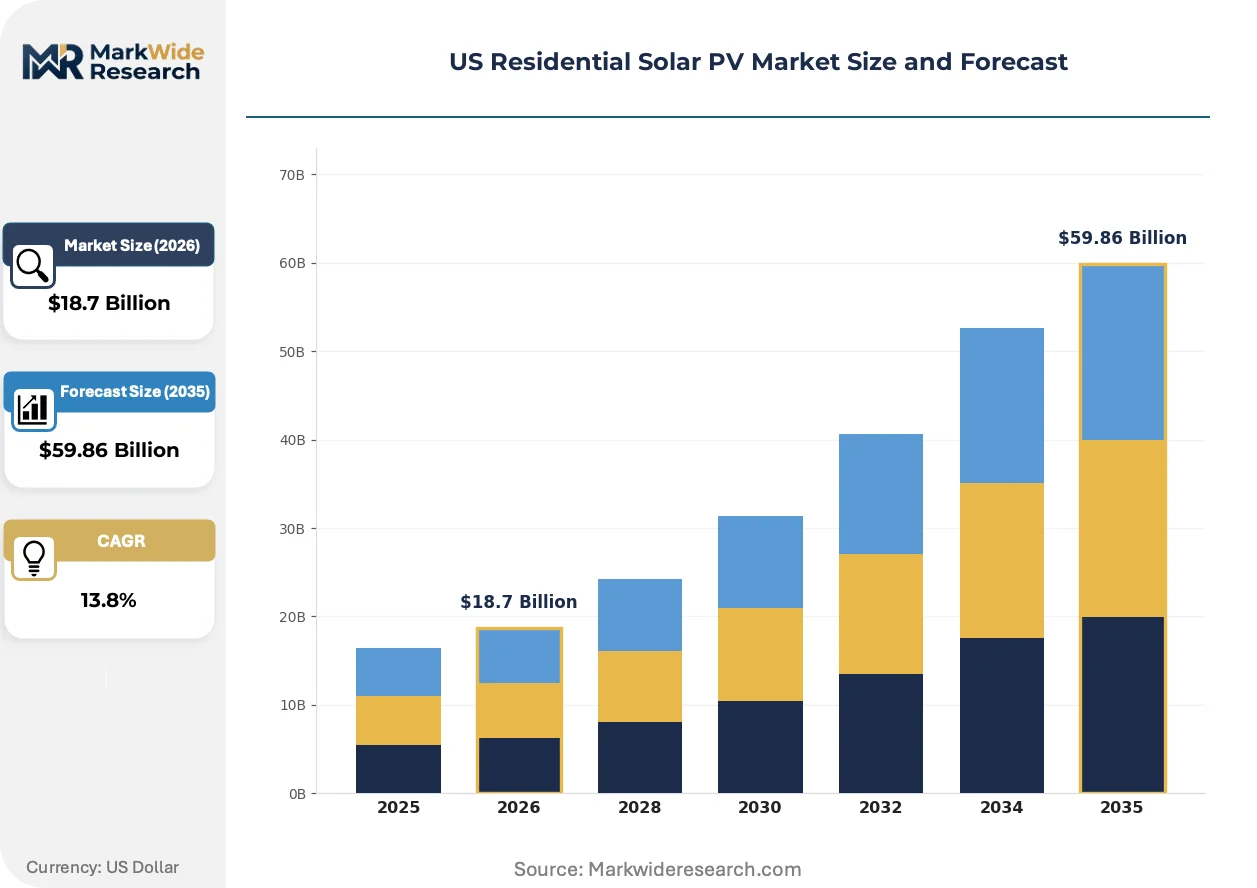
The US residential solar PV market is experiencing a fundamental restructuring as net metering reforms in California and other sunbelt states compress the economic value of pure export configurations, forcing installers toward hybrid battery-backed system architectures and reshaping customer acquisition economics.
Growth Catalysts
- IRA Investment Tax Credit Extension:The Inflation Reduction Act's 30% federal tax credit through 2032 stabilizes project finance assumptions and reduces customer acquisition costs for direct-to-consumer installers.
- Monocrystalline Cell Efficiency Gains:Passivated emitter and rear contact (PERC) and tunnel oxide passivated contact (TOPCon) architectures now deliver 22%+ module efficiency, shrinking rooftop footprint requirements for high-consumption suburban households.
- Texas and Florida Utility Rate Volatility:Deregulated retail markets and hurricane-exposed grid infrastructure in these states create persistent demand for rate hedging and backup power functionality.
Market Restraints
- Polysilicon and Silver Input Cost Volatility:Metallurgical-grade silicon refining capacity concentration in Xinjiang and silver paste dependency for cell metallization expose module assemblers to commodity price swings that compress installer margins.
- California NEM 3.0 Export Value Compression:The California Public Utilities Commission's revised net energy metering tariff slashes compensation rates for excess generation sent to the grid, degrading simple payback periods for grid-tied-only configurations.
- Permitting and Interconnection Friction:Municipal AHJ inspection backlogs and utility interconnection queue delays in high-growth markets extend project completion timelines and increase customer cancellation rates.
Strategic Opportunities
- Texas ERCOT Market Expansion:The absence of statewide net metering mandates and volatile real-time pricing in the Electric Reliability Council of Texas territory creates white space for battery-optimized self-consumption models.
- Virtual Power Plant Aggregation:Utility demand response programs and wholesale market participation frameworks enable residential battery fleets to generate ancillary revenue streams beyond customer bill savings.
- Heat Pump and EV Charger Load Growth:Electrification of space conditioning and transportation in single-family homes expands addressable rooftop capacity requirements and extends system sizing upward.
Industry Challenges
- Licensed Electrician and NABCEP-Certified Installer Scarcity:Rapid market expansion in sunbelt states has outpaced vocational training pipeline output, extending project timelines and inflating labor cost components.
- Supply Chain Reconfiguration from Southeast Asia:Antidumping and countervailing duty investigations on Cambodian, Malaysian, Thai, and Vietnamese cell and module imports force procurement teams to qualify new domestic and alternative sourcing channels under compressed timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential Solar PV Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $59.86 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial System Type: Grid-Tied, Off-Grid, Hybrid, Net Metering Installation Size: Small Scale, Medium Scale, Large Scale, Custom End User: Homeowners, Developers, Installers, Investors |
| Companies Covered | Sunrun, Freedom Forever, Titan Solar Power, Tesla, Enphase Energy, SolarEdge, REC, Qcells, Stellar Solar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential Solar PV Market Strategic Shifts & Innovations
Technology convergence and regulatory recalibration are compressing traditional system boundaries, as rooftop solar integrates with behind-the-meter storage and home energy management platforms to form unified residential energy assets.
Bifacial glass-glass module architectures are supplanting conventional monofacial framed designs in premium residential segments by capturing reflected irradiance from light-colored roofing membranes and snow-covered surfaces. High-efficiency PERC and heterojunction cell adopters in the Mountain West and Northeast are specifying these modules to maximize yield per limited rooftop area. This technology transition is compressing the economic viability gap between constrained urban-suburban installations and sprawling rural arrays.
The Inflation Reduction Act's domestic content bonus credit is redirecting procurement volumes toward American-manufactured cells and modules, with Georgia and Ohio emerging as anchor production locations. Projects qualifying for the additional 10 percentage point credit must demonstrate 40% domestic content value, forcing engineering-procurement-construction firms to requalify supply chains and document bill-of-materials provenance. California and Texas installers with scale advantages are securing offtake agreements with domestic producers earlier than regional competitors.
Customer acquisition through third-party lead generation marketplaces is eroding direct-to-consumer installer margins and compressing sales cycle economics. Sunbelt installers dependent on door-to-door and telemarketing channels are experiencing customer acquisition cost inflation as digital-native buyers self-educate through comparison platforms and demand transparent pricing. Arizona and Colorado markets exhibit the most pronounced channel fragmentation, with national platforms capturing intermediate funnel stages before routing to lowest-bid installers.
US Residential Solar PV Market Segmentation
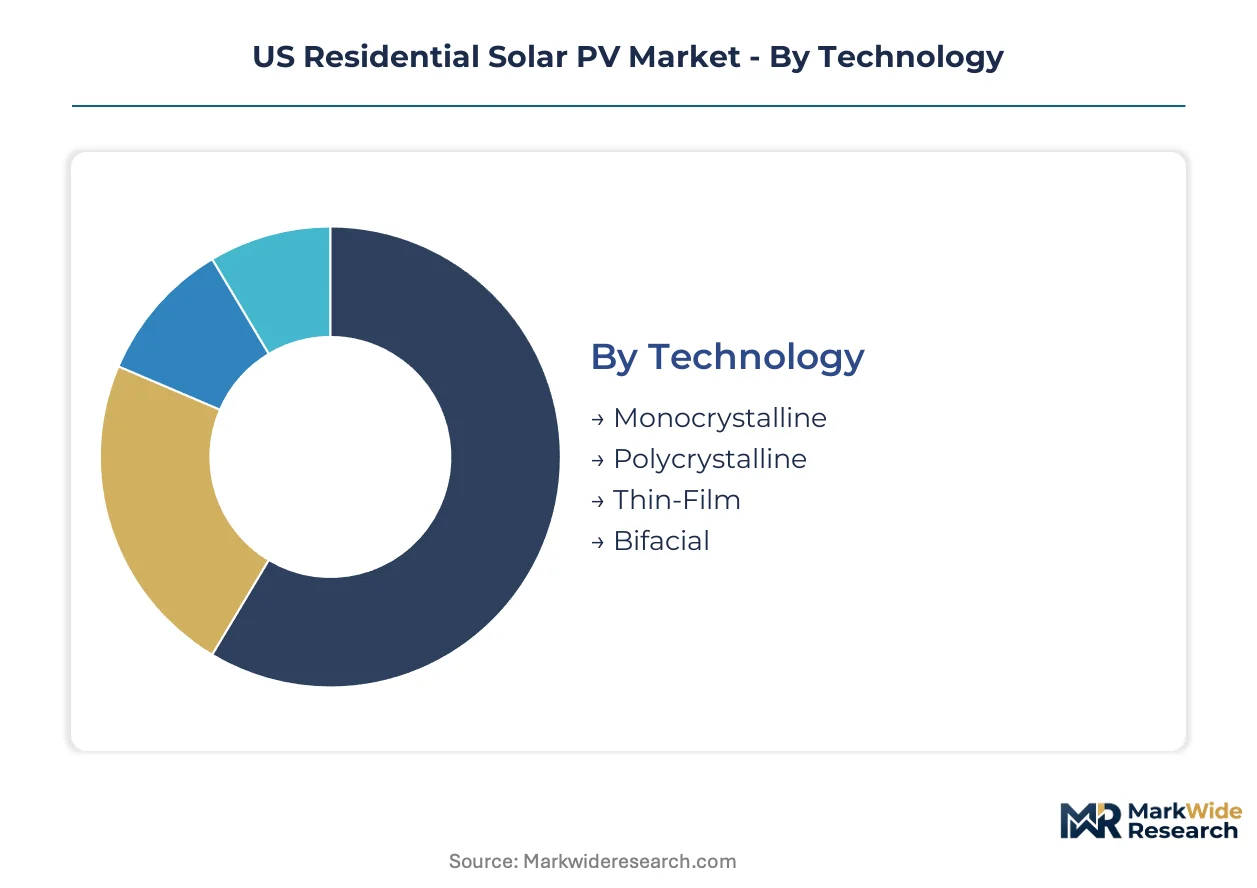
Segmentation reveals how IRA incentives and net metering reforms are concentrating demand around specific technology-system combinations. Installers configure offerings differently across Texas sunbelt suburbs versus California coastal markets where NEM 3.0 has degraded export economics.
Technology:
Domestic manufacturing capacity expansion in Georgia and Ohio is reshaping procurement patterns for American-made cells and modules qualifying for IRA bonus credits.
- Monocrystalline:Passivated emitter and rear contact (PERC) architectures deliver 22%+ conversion efficiency in silicon wafers with uniform crystal structure. Suburban homeowners in Arizona and Florida prioritize these modules to maximize kilowatt-hour yield per limited rooftop square footage where HOA restrictions apply.
- Bifacial:Glass-glass sandwich construction captures reflected irradiance from light-colored roofing membranes and snow-covered surfaces. Mountain West installations in Colorado and Utah specify these for elevated terrain with high albedo conditions, though framing and mounting hardware add incremental balance-of-system costs.
- Polycrystalline:Multi-crystal silicon ingots offer lower manufacturing energy intensity and modest cost advantages for price-sensitive rural installations where rooftop area is unconstrained.
- Thin-Film:Cadmium telluride and copper indium gallium selenide technologies occupy niche applications including building-integrated photovoltaics and portable systems where weight and flexibility outweigh efficiency metrics.
Monocrystalline holds the largest share; momentum sits with bifacial as homeowners seek maximum energy density per square foot.
System Type:
Cost tier differentiation separates premium battery-backed configurations from economy grid-tied-only designs as state-level net metering reforms reshape customer economics.
- Hybrid:DC-coupled or AC-coupled battery storage integration enables self-consumption optimization and backup power functionality. California homeowners under NEM 3.0 export tariffs increasingly specify these systems to arbitrage time-of-use rate differentials rather than maximizing grid export volumes.
- Grid-Tied:Inverter-only configurations without storage deliver lowest upfront capital requirements and simplest permitting pathways. Texas ERCOT market participants favor these where real-time pricing volatility and absence of net metering mandates reduce the economic case for battery investment.
- Net Metering:System architectures specifically engineered to maximize export compensation under legacy one-to-one credit tariffs in states that have not yet adopted NEM 3.0-style reforms.
- Off-Grid:Standalone systems with oversized battery banks and backup generators serve remote rural properties beyond utility distribution infrastructure in western Texas and mountain regions.
Grid-tied configurations retain volume leadership; hybrid systems are climbing the fastest as export compensation rates compress across sunbelt jurisdictions.
Installation Size:
Customer type determines sizing thresholds, with electrification of heating and transportation expanding addressable capacity requirements for single-family households.
- Medium Scale:8 kW to 15 kW DC nameplate capacity matches typical suburban single-family consumption profiles including air conditioning and pool equipment loads. Florida installers concentrate here for post-hurricane rebuilding markets where resilient power commands premium positioning.
- Large Scale:Systems exceeding 15 kW serve high-consumption estates with electric vehicle charging, swimming pool pumps, and whole-home air conditioning. Arizona sunbelt developments with minimal shading and south-facing roof orientation specify these to offset aggressive utility rate schedules.
- Small Scale:Sub-8 kW configurations address townhouses, duplexes, and partial-roof installations where structural or aesthetic constraints limit array footprint.
- Custom:Non-standard configurations including ground-mount arrays, solar pergolas, and building-integrated designs for architecturally sensitive properties.
Medium scale dominates current installations; large scale is gaining share fastest as heat pump and EV charger electrification expands household load profiles.
End User:
Margin concentration varies sharply across the value chain, with financing platforms capturing recurring revenue streams unavailable to pure installation contractors.
- Homeowners:Single-family and townhouse residents with rooftop access and sufficient tax liability to monetize federal investment tax credits. Sunbelt states with high air conditioning loads and volatile utility rates concentrate demand among this segment.
- Installers:Licensed electrical contractors and NABCEP-certified technicians performing system design, permitting, and interconnection. Labor scarcity in Texas and Florida markets is extending project timelines and inflating installation cost components.
- Developers:Residential construction firms integrating solar pre-installation into new home builds, particularly in California where Title 24 energy code mandates solar-ready construction.
- Investors:Tax equity providers and yieldcos monetizing depreciation and credit streams through third-party ownership structures including leases and power purchase agreements.
Homeowners represent the largest addressable base; installers face the steepest margin pressure from customer acquisition cost inflation and labor scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian module assembly capacity feeds directly into California and Texas distribution hubs, with Georgia and Ohio emerging as domestic manufacturing anchors under IRA domestic content requirements.
California
Coastal metropolitan zones from San Diego through Los Angeles to the Bay Area concentrate installation volume despite NEM 3.0 export tariff compression. The California Public Utilities Commission's revised net energy metering framework now values self-consumption over grid export, redirecting system specifications toward battery-backed hybrid architectures. Sacramento and Central Valley installers report extended interconnection timelines as utility backlogs accumulate.
Texas
Houston and Dallas-Fort Worth metroplexes drive demand through deregulated retail electricity markets and ERCOT real-time pricing volatility. The absence of statewide net metering mandates creates white space for battery-optimized self-consumption models rather than pure export configurations. Austin and San Antonio municipal utility territories exhibit distinct rate structures that favor different system sizing economics.
Florida
Post-hurricane rebuilding markets in Tampa Bay and Southwest Florida prioritize resilient power functionality alongside rate hedging. The Florida Public Service Commission maintains retail rate structures that preserve grid-tied economics, though installer labor scarcity extends project completion timelines. Orlando and Jacksonville growth corridors concentrate new construction solar-ready mandates.
Arizona
Phoenix and Tucson sunbelt developments with minimal shading specify large-scale systems to offset aggressive utility rate schedules from Arizona Public Service and Tucson Electric Power. The state's high irradiance levels compress payback periods even without generous export compensation. Flagstaff and northern Arizona markets exhibit distinct seasonal production patterns that influence battery sizing decisions.
Northeast Corridor
Massachusetts and New Jersey markets compensate for lower irradiance through aggressive state-level incentives and SREC markets. The Massachusetts Department of Energy Resources SMART program and New Jersey's Successor Solar Incentive maintain viable project economics despite winter production constraints. Connecticut and Rhode Island follow similar incentive architectures with smaller absolute market volumes.
US Residential Solar PV Market Key Industry Players
Player mix skews toward vertically integrated installation-financing platforms alongside pure-play equipment manufacturers and regional installation contractors. The competitive terrain separates into three strategic archetypes: national direct-to-consumer platforms with captive financing, module-level power electronics specialists, and regional installation contractors with local permitting expertise. Capacity expansion into domestic cell and module manufacturing accelerates as IRA domestic content bonuses reshape procurement patterns. Installer consolidation intensifies as customer acquisition cost inflation squeezes standalone regional operators.
Among national platform operators, Sunrun anchors the direct-to-consumer financing tier through its vertically integrated installation and loan servicing infrastructure. Tesla occupies a distinct position through integrated Solar Roof product architecture and Powerwall storage bundling. Qcells exemplifies the domestic manufacturing pivot with its Georgia cell and module factory competing on supply chain proximity rather than pure cost positioning.
| Leading Market Players |
|---|
| Sunrun |
| Freedom Forever |
| Titan Solar Power |
| Tesla |
| Enphase Energy |
| SolarEdge |
| REC |
| Qcells |
| Stellar Solar |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day module lead times from Southeast Asian assembly plants to Texas distribution hubs concentrate pricing power with domestic manufacturers qualifying for IRA bonus credits, compressing margins for installers locked into foreign supply contracts.
Pricing Analysis
The PERC-to-TOPCon efficiency upgrade commands a 15-20% module price premium over legacy monocrystalline architectures, while polycrystalline alternatives anchor the economy tier for rural unconstrained-rooftop installations. Three-tier pricing structure across premium bifacial glass-glass, standard monofacial PERC, and economy polycrystalline levels reflects efficiency grade and domestic content certification. Cost compression in standard-tier modules is intensifying because Qcells and REC are expanding Georgia and Ohio wafer capacity. Price-sensitive buyers cluster in Texas ERCOT territories where real-time pricing volatility makes payback period math unforgiving, while California NEM 3.0 adopters show reduced sensitivity as battery-backed hybrid systems shift value toward resilience rather than pure economics.
Supply Chain Analysis
Container availability constraints on the Shanghai-Long Beach trade lane and Savannah port congestion are extending inbound logistics cycles for module imports, pushing procurement teams toward rail-linked Midwest distribution centers. Polysilicon refining concentrates in Xinjiang and metallurgical-grade silicon processing in China, South Korea, and Germany, with cell assembly spreading across Cambodia, Malaysia, Thailand, and Vietnam. Silver paste for cell metallization and aluminum frames for module construction represent critical input dependencies. Tariff exposure from ongoing antidumping investigations on Southeast Asian imports threatens supply continuity. Distribution runs through national platform distributors like CED Greentech and regional electrical wholesalers serving NABCEP-certified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US residential solar PV market sits in early-cycle expansion as single-family electrification—heat pumps, EV chargers, pool equipment—expands addressable rooftop capacity requirements beyond traditional air-conditioning loads.
For Market Incumbents: Fortify installer labor pipelines through NABCEP certification partnerships and vocational training apprenticeships in Texas and Florida, where electrician scarcity extends project timelines. Deepen backward integration into battery storage assembly or secure exclusive offtake with Georgia-based cell producers to defend margin position against customer acquisition cost inflation from lead-generation marketplace intermediation. For New Entrants and Emerging Players: Differentiate on ERCOT battery-optimized self-consumption software, where absence of net metering mandates creates white space for algorithmic load-shifting and wholesale market participation. Target Texas sunbelt suburbs with volatile real-time pricing and post-hurricane Florida markets prioritizing resilient backup power. Pursue virtual power plant aggregation partnerships with municipal utilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulated-utility-disintermediation play because state-level rate structure reforms and IRA incentive durability create structural tailwinds for behind-the-meter asset ownership. Acquisition targets should display regional installation density with in-house permitting expertise and established utility interconnection relationships. Watch California CPUC proceedings on successor NEM tariffs and Texas PUCT demand response rulemakings as inflection signals for battery-backed system economics.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | Qcells' Georgia cell factory secures IRA bonus credit eligibility for downstream installers. |
| Battery Storage Integration | DC-coupled architectures capture margin pools as NEM 3.0 compresses pure export value. |
| Virtual Power Plant Aggregation | Utility demand response programs enable residential battery fleets to generate ancillary revenue. |
| Installer Labor Pipeline Development | NABCEP certification partnerships address electrician scarcity extending Texas project timelines. |
| Software-Defined Energy Management | Home energy platforms optimize self-consumption under time-of-use rate differentials. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with residential solar installers, utility interconnection planners, EPC contractors, and module procurement directors. Secondary validation drew from EIA solar installation databases, FERC interconnection queue filings, NREL cost benchmark reports, and state public utility commission rate case dockets. Bottom-up sizing of installer volumes and top-down reconciliation with module shipment data provided cross-verification.
Across the analysis window, projections integrate technology cost curves, IRA incentive phase structures, and state-level net metering policy trajectories. Segmentation dimensions include cell technology architecture, system type configuration, installation size tier, and end-user financing structure. CAGRs derive from regression against historical adoption patterns, utility rate escalation assumptions, and electrification load growth projections. Key inputs encompass NREL module efficiency roadmaps and Lawrence Berkeley National Laboratory interconnection timeline trends.
Material uncertainties—tariff rulings on Southeast Asian imports, polysilicon price volatility, and state PUC net metering reforms—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding IRA continuity and utility rate structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Off-Grid Solar Generator Market