
 United States Fixed-Tilt Solar PV Market | 2026-2036
United States Fixed-Tilt Solar PV Market Size, Share, and Industry Trends Forecast 2026-2036
United States Fixed-Tilt Solar PV Market Analytics
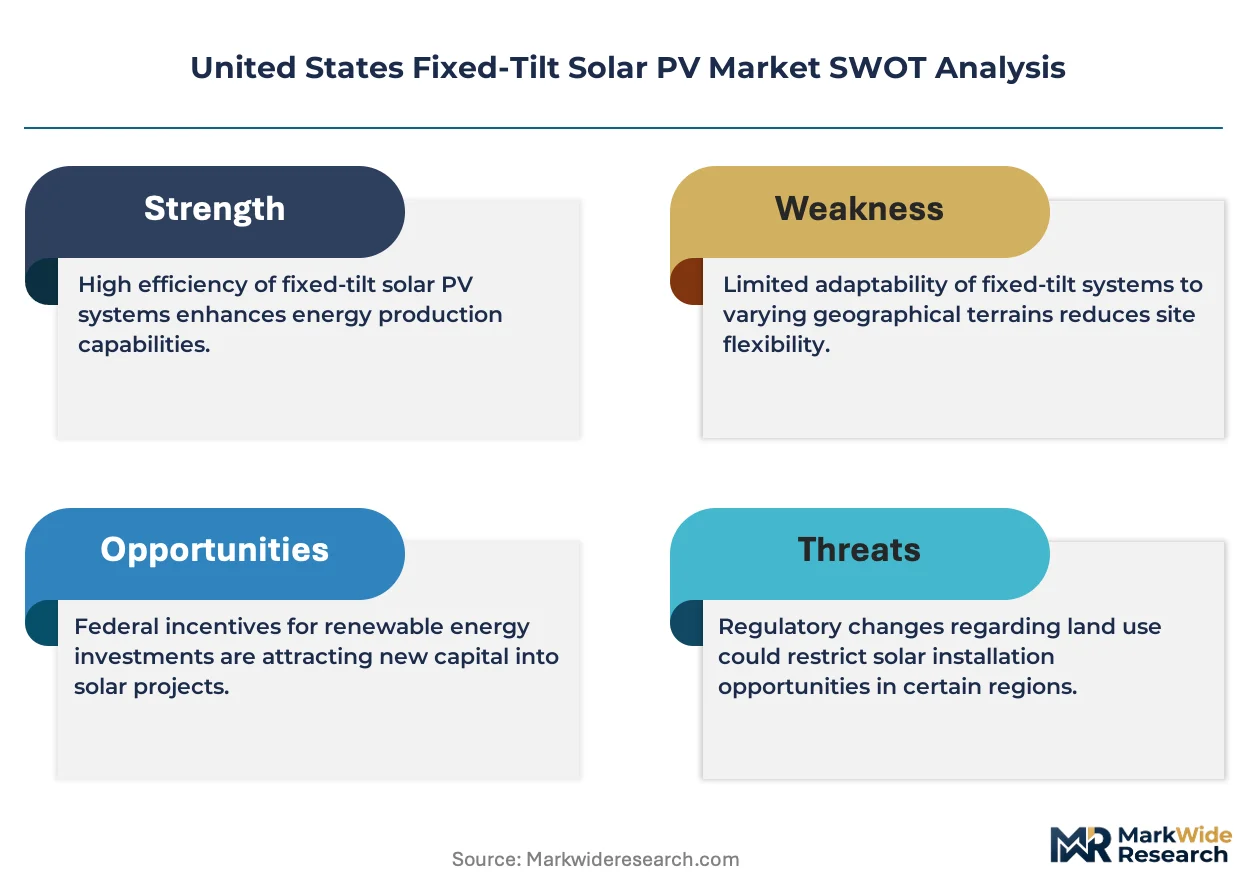
The divergence between premium-grade domestic steel racking and imported aluminum commodity systems is realigning procurement criteria for utility-scale developers. First Solar Inc. leverages captive thin-film module production to anchor large-project bids in the Southwest. Canadian Solar Inc. competes through integrated module-plus-racking packages that reduce balance-of-system complexity. GameChange Solar differentiates with pre-assembled structural components that cut field labor hours.
Fixed-tilt solar PV denotes stationary mounting structures that hold photovoltaic panels at a constant angle to the horizon, typically engineered from galvanized steel or aluminum with specific load ratings for wind and snow, designed to maximize annual energy yield without motorized tracking. Crystalline Silicon dominates installed capacity due to decades of manufacturing scale and supply chain maturity. Thin-Film occupies niche applications where weight constraints or high-temperature performance offset lower conversion efficiency. Ground-Mounted installations command the majority of structural demand as utility-scale projects expand across flat terrain in the Great Plains and Desert Southwest.
The Federal Energy Regulatory Commission governs interstate transmission access, directly shaping interconnection timelines that determine project revenue commencement. The Internal Revenue Service administers Investment Tax Credit domestic content bonuses that now require specified percentages of U.S.-manufactured steel and iron in racking structures. State public utility commissions in Texas and California enforce grid reliability standards that influence fixed-tilt system electrical configuration. Stakeholders must monitor evolving domestic content thresholds and interconnection queue reform to preserve project returns.
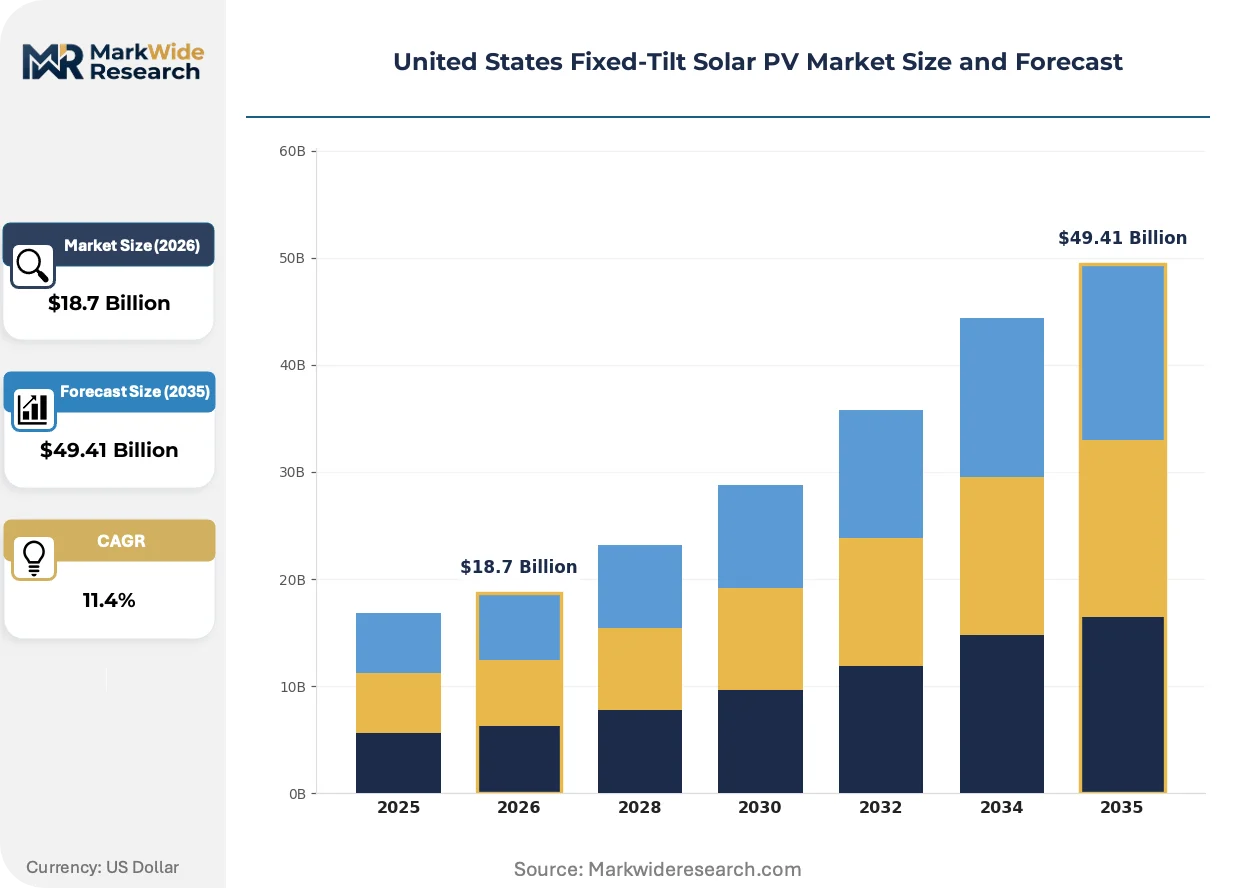
Market Dynamics
The Inflation Reduction Act's domestic content bonus thresholds are compressing procurement timelines as developers race to qualify steel and iron sourcing before percentage escalators tighten. This single regulatory mechanism now governs supplier selection, racking material substitution, and project finance structuring across the Southwest interconnection queues.
Growth Catalysts
- Investment Tax Credit domestic content bonuses:The IRS-administered escalating thresholds for U.S.-manufactured steel in racking structures are pulling forward procurement commitments from utility-scale developers in Texas and California.
- Utility-scale procurement acceleration:Southwest interconnection queue activity is concentrating demand for fixed-tilt ground-mount systems across flat terrain in the Great Plains and Desert Southwest.
- Thin-film module performance:High-temperature coefficient advantages in desert climates are anchoring technology selection for specific project sites where heat degradation erodes crystalline silicon yields.
Market Restraints
- Galvanized steel price volatility:Domestic steel mill capacity constraints and tariff exposure on imported coil are compressing racking margin structures for fixed-tilt system suppliers.
- Interconnection queue congestion:FERC-jurisdictional transmission access timelines in Texas and California are extending revenue commencement delays and inflating carrying costs for project sponsors.
- Aluminum racking substitution limits:Structural load rating deficiencies in high-wind zones restrict commodity aluminum systems to secondary markets, segmenting supplier addressable markets.
Strategic Opportunities
- Pre-assembled structural components:Field labor hour reduction through factory-integrated racking subassemblies creates differentiation for installers competing in tight labor markets.
- Texas ERCOT ancillary service markets:Grid reliability product participation is opening revenue stacking opportunities for solar-plus-storage configurations using fixed-tilt foundations.
- California SGIP incentive alignment:Behind-the-meter storage pairing with commercial fixed-tilt installations is capturing state-level incentive streams for resilient distributed generation.
Industry Challenges
- Electrical trades labor scarcity:Journeyman electrician availability is constraining DC-to-AC conversion commissioning timelines across utility-scale project clusters in the Desert Southwest.
- Domestic content documentation burden:IRS substantiation requirements for steel and iron provenance are extending procurement cycles and inflating compliance overhead for project finance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Fixed-Tilt Solar PV Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Crystalline Silicon, Thin-Film, Bifacial, Concentrated PV End User: Residential, Commercial, Utility, Government Installation Type: Rooftop, Ground-Mounted, Carports, Farms Distribution Channel: Direct Sales, Distributors, Online Retail, EPC Contractors |
| Companies Covered | First Solar Inc., Canadian Solar Inc., ENGIE SA, Solar FlexRack, UNIRAC Inc., GameChange Solar, RBI Solar, Array Technologies Inc., Mounting Systems GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Fixed-Tilt Solar PV Market Evolving Landscape
Fixed-tilt racking architecture is converging with module form factor standardization and domestic manufacturing localization to reshape competitive positioning. Three distinct movements are compressing field installation timelines and reconfiguring supplier value capture.
Galvanized steel torque tube assemblies with integrated grounding hardware are consolidating as the dominant structural standard for utility-scale fixed-tilt installations. EPC contractors in Texas and Arizona are specifying these pre-drilled systems to eliminate field cutting and reduce foundation tolerance sensitivity. The technology is consolidating supplier tiers by rewarding captive steel sourcing and automated roll-forming capacity.
The IRS domestic content bonus regulations are mandating specified percentages of U.S.-manufactured steel and iron in structural racking components. This industrial policy mechanism is forcing racking suppliers to reshore coil processing and extrusion operations to preserve project eligibility. Utility-scale developers in California and Texas interconnection queues are now screening suppliers based on mill certification documentation rather than purely on installed cost.
Integrated module-plus-racking procurement bundles are displacing discrete component sourcing for utility-scale projects. Developer engineering teams are consolidating vendor relationships to reduce interface risk and accelerate project delivery schedules. This pattern is most visible in the ERCOT and CAISO service territories where interconnection timeline pressure rewards simplified supply chain structures.
United States Fixed-Tilt Solar PV Market Segmentation
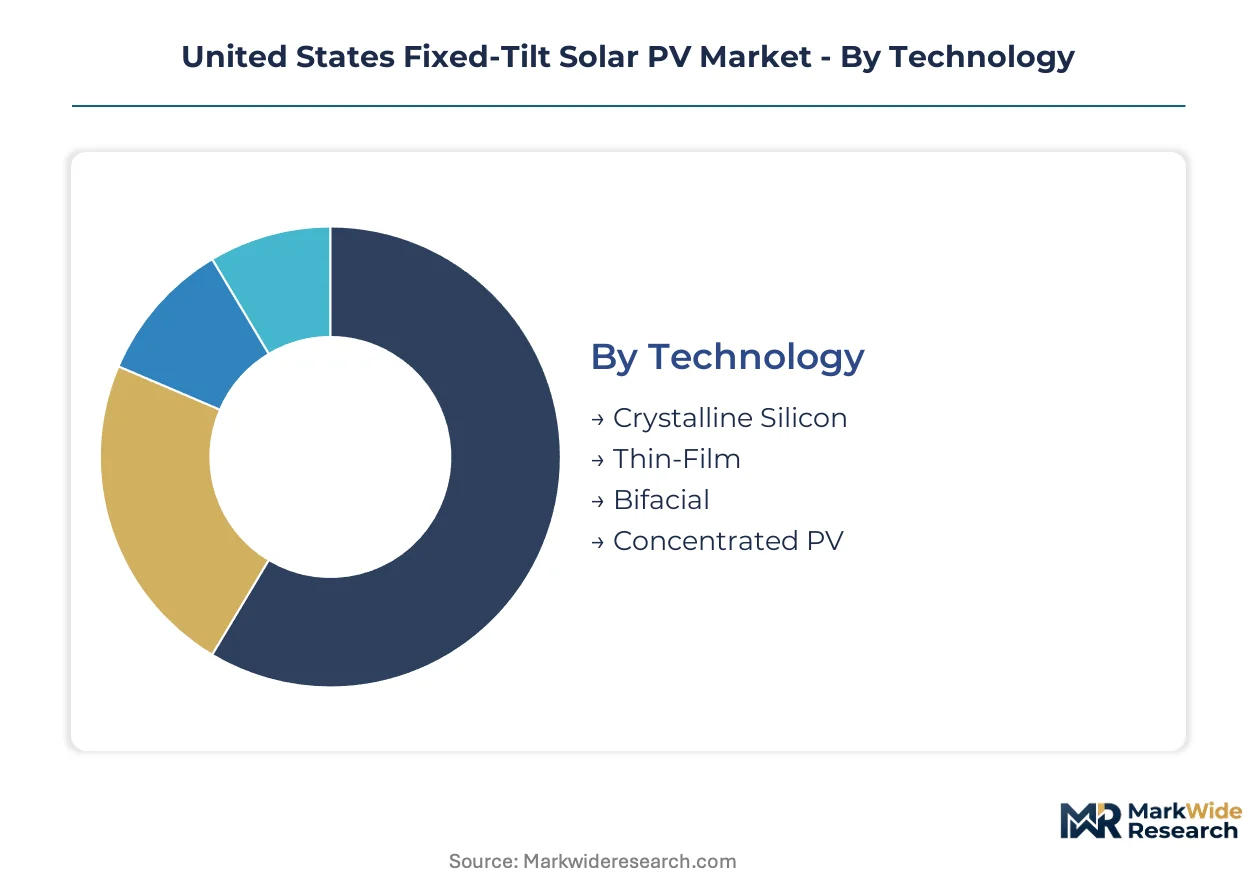
Technology selection dictates racking specification, steel gauge requirements, and foundation engineering across the United States fixed-tilt solar PV market. End-user scale determines procurement channel preference and domestic content bonus eligibility under IRA provisions.
Technology:
Module technology replacement cycles are accelerating as developers optimize for heat performance and bifacial gain capture in Southwestern installations.
- Crystalline Silicon:Standard monocrystalline and polycrystalline cells mounted in aluminum-framed glass-glass assemblies dominate procurement volumes. Texas and California utility-scale queues specify these modules for their proven bankability and established recycling pathways.
- Thin-Film:Cadmium telluride and copper indium gallium selenide cells deliver superior temperature coefficients in Desert Southwest conditions. First Solar's captive manufacturing anchors demand for cadmium telluride in Arizona and Nevada utility projects where heat degradation erodes crystalline yields.
- Bifacial:Dual-sided energy capture requires elevated racking heights and reflective ground surfaces to realize gain premiums.
- Concentrated PV:Multi-junction cells with optical concentrators occupy niche applications where direct normal irradiance exceeds threshold levels.
Volume placements concentrate in Crystalline Silicon; the faster expansion belongs to Bifacial.
End User:
Customer scale determines balance-of-system complexity and whether procurement flows through EPC integrators or direct manufacturer relationships.
- Utility:Single-axis and fixed-tilt ground-mount systems exceeding 100 MWac capacity dominate steel racking demand. ERCOT and CAISO interconnection queues in Texas and California drive procurement concentration for pre-assembled torque tube assemblies with integrated grounding.
- Commercial:Behind-the-meter installations from 100 kW to 5 MW leverage roof-mount and carport configurations. California SGIP incentive alignment is pulling forward storage-paired fixed-tilt demand for resilience-focused commercial offtakers.
- Residential:Distributed rooftop systems under 20 kW require lightweight aluminum racking with simplified permitting packages.
- Government:Federal and state procurement mandates domestic content compliance for military and civilian agency installations.
Utility-scale deployments absorb the majority of structural steel tonnage; commercial applications are climbing the fastest.
Installation Type:
Foundation engineering and racking material selection diverge sharply between elevated structures and ground-penetrating systems.
- Ground-Mounted:Driven pile and ballasted foundations support utility-scale arrays across flat terrain in the Great Plains and Desert Southwest. Galvanized steel torque tube assemblies with pre-drilled connections are consolidating as the structural standard for Texas and Arizona EPC specifications.
- Rooftop:Low-slope commercial membranes and residential asphalt shingle attachments require lightweight aluminum rail systems with distributed load management.
- Carports:Elevated canopy structures combine parking coverage with generation capacity for commercial and municipal offtakers.
- Farms:Agrivoltaic configurations integrate elevated racking with continued agricultural access for crop and grazing operations.
Ground-Mounted systems command the structural steel volume; carport configurations are gaining share fastest.
Distribution Channel:
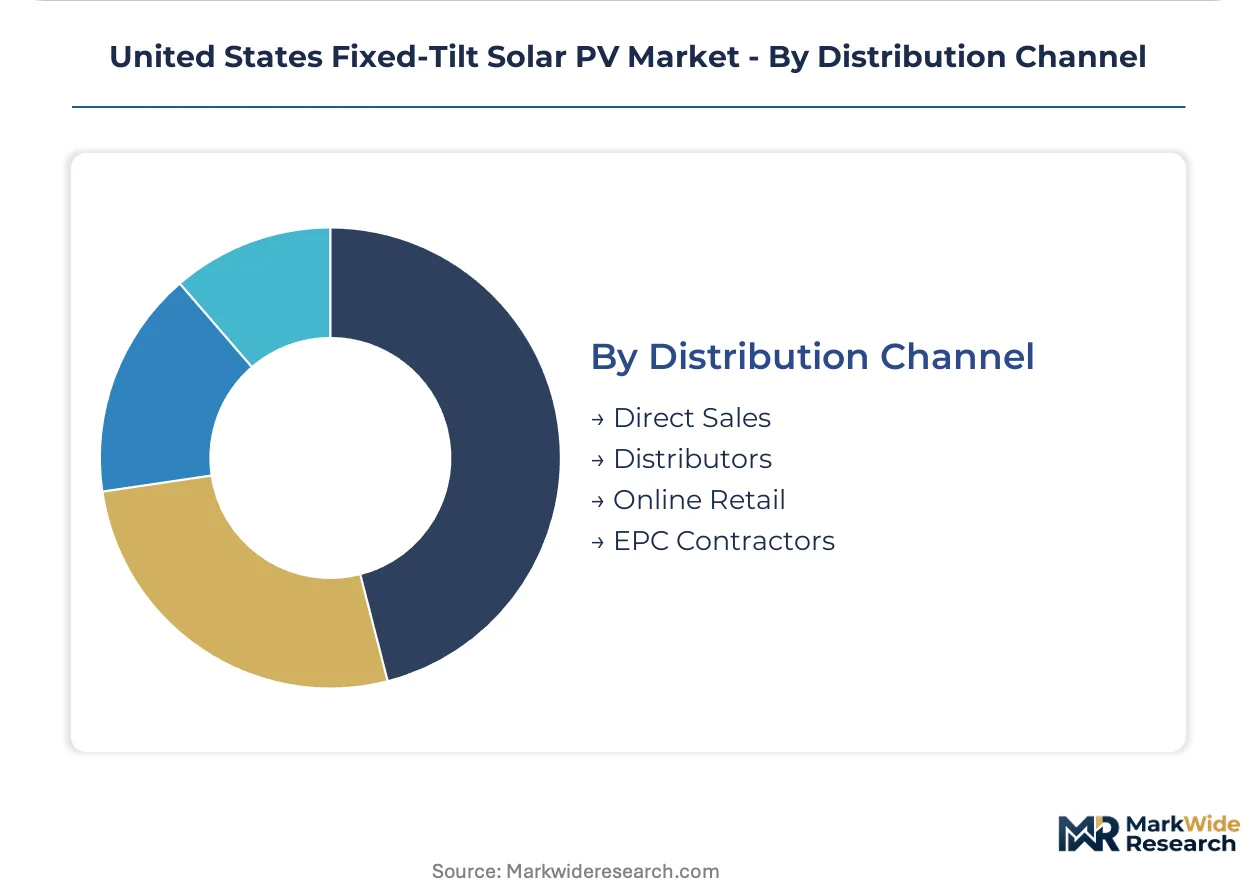
Channel selection determines documentation burden for domestic content substantiation and project delivery timeline compression.
- EPC Contractors:Turnkey engineering-procurement-construction providers consolidate module, racking, and electrical sourcing for utility-scale developers. Texas and California queue pressure is pushing developers toward EPC relationships that absorb interface risk and accelerate interconnection readiness.
- Distributors:Regional and national wholesalers stock standard racking components for commercial and residential installers with shorter procurement cycles.
- Direct Sales:Module and racking manufacturers bypass intermediaries for large utility-scale transactions with dedicated account management.
- Online Retail:E-commerce platforms serve residential and small commercial segments with standardized permitting packages and rapid fulfillment.
EPC Contractors capture the majority of utility-scale volume; direct manufacturer relationships are expanding most quickly for domestic content compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ERCOT interconnection zone spanning West Texas anchors utility-scale procurement velocity, with project pipelines clustering around Midland-Odessa and Abilene transmission nodes. California's CAISO queue concentrates developer activity in Kern County and the Imperial Valley. Federal domestic content thresholds under IRA provisions are compressing procurement timelines across both markets.
Southwest
Desert Southwest installations in Arizona and Nevada exploit high solar irradiance and flat terrain for ground-mounted arrays. The Bureau of Land Management's streamlined permitting for utility-scale solar on federal lands accelerates project development in Clark County and Yuma County. First Solar's thin-film manufacturing presence in Arizona anchors regional supply chain localization.
Texas
ERCOT's ancillary service markets and transmission expansion into the Permian Basin drive fixed-tilt demand for merchant solar projects. The Public Utility Commission of Texas oversees interconnection standards that shape electrical configuration requirements. Developer engineering teams concentrate procurement decisions in Houston and Austin corporate offices.
California
The California Energy Commission enforces building codes and grid reliability standards that influence fixed-tilt system design for utility and commercial segments. Behind-the-meter installations pairing with SGIP incentives cluster in San Diego County and the Central Valley. Interconnection queue congestion extends revenue commencement timelines for projects in the CAISO north and south zones.
Great Plains
Flat terrain and high-capacity factor wind-solar hybrid zones in Oklahoma and Kansas attract utility-scale fixed-tilt development. The Southwest Power Pool coordinates regional transmission planning that shapes interconnection feasibility. Rural electric cooperatives in the Oklahoma Panhandle and western Kansas specify pre-assembled steel racking to reduce field labor requirements.
Southeast
Utility procurement mandates in Florida and Georgia pull fixed-tilt demand for regulated solar programs. The North American Electric Reliability Corporation standards govern grid integration requirements across the Southern Company and Duke Energy service territories. EPC contractors source racking through regional distribution hubs in Atlanta and Jacksonville.
United States Fixed-Tilt Solar PV Market Competitive Landscape
Premium-margin players sit above commodity-margin players across domestic content compliance capability and steel sourcing transparency. The vendor base stratifies into three tiers: captive thin-film module producers with integrated racking supply, specialized structural fabricators with automated roll-forming capacity, and commodity aluminum system distributors serving secondary markets. Strategic moves center on reshoring coil processing operations and consolidating EPC relationships to absorb interface risk.
Among module-integrated suppliers, First Solar Inc. and Canadian Solar Inc. represent the captive manufacturing archetype that leverages in-house production to anchor large-project bids. Specialized structural fabricators include GameChange Solar, which exemplifies the pre-assembly differentiation model targeting field labor reduction. Mounting Systems GmbH occupies a position within the European-origin engineering tier serving U.S. utility-scale developers through localized production partnerships.
| Leading Market Players |
|---|
| First Solar Inc. |
| Canadian Solar Inc. |
| ENGIE SA |
| Solar FlexRack |
| UNIRAC Inc. |
| GameChange Solar |
| RBI Solar |
| Array Technologies Inc. |
| Mounting Systems GmbH |
| Others |
Value Network & Pricing Analysis
Domestic content compliance tiering bifurcates the fixed-tilt racking market into IRS-certifiable steel assemblies and excluded aluminum commodity systems, compressing margins on the latter while anchoring premium pricing on mill-traceable domestic coil. This divergence feeds directly into procurement patterns across Texas and California interconnection queues, where developers now weight supplier qualification documentation above pure installed cost metrics.
Pricing Analysis
Yield-per-watt performance anchors value-based pricing for fixed-tilt racking selections in utility-scale procurement. Three-tier pricing structure across premium domestic steel, standard imported steel, and economy aluminum tiers reflects certification burden and labor efficiency differentials. Cost compression in commodity aluminum racking is intensifying because tariff exposure on imported coil erodes margin structures. Commercial installers exhibit highest price sensitivity due to fragmented procurement authority, while utility-scale developers prioritize total project returns over component-level cost.
Supply Chain Analysis
Inland freight costs from domestic steel mills to Southwest project sites represent a material cost layer that advantages regional roll-forming capacity over coastal import gateways. Coil processing concentrates in Ohio, Indiana, and Texas, with finished racking assemblies drawing from automated extrusion operations in Arizona and California. Supply chain risk centers on single-source vulnerability for domestic steel mill certifications required under IRA domestic content thresholds. Distribution runs through EPC contractor consolidation for utility-scale volume, with direct manufacturer relationships expanding for compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fixed-tilt solar PV market has become a vertical-integration race where captive steel sourcing and automated roll-forming capacity determine supplier viability. Players are pursuing upstream control over mill-certified coil to preserve project eligibility under escalating domestic content thresholds.
For Market Incumbents: Cement market position through backward integration into domestic steel coil processing and automated torque tube roll-forming capacity. First-mover certification under IRS domestic content documentation requirements creates switching costs for utility-scale developers. Capacity addition in Texas and Arizona reduces freight exposure to ERCOT and CAISO project clusters. For New Entrants and Emerging Players: Capture share in commercial behind-the-meter segments where domestic content compliance burden remains lighter and procurement cycles favor agile suppliers. Agrivoltaic configurations in the Great Plains represent the most penetrable application white-space. Go-to-market leverage rests on pre-assembled structural subassemblies that reduce field labor hours for installer partners. For Investors and Strategic Acquirers: Re-rating potential sits with specialized structural fabricators possessing automated roll-forming capacity and captive steel sourcing given IRA domestic content threshold escalations. Long-term viability hinges on supplier tier consolidation around IRS-certifiable documentation capabilities. The signal to watch is interconnection queue reform progress in Texas and California as inflection indicator for procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Steel Sourcing Integration | Captive mill relationships secure IRA bonus eligibility for utility-scale developers in ERCOT and CAISO territories. |
| Automated Roll-Forming Capacity Expansion | Regional torque tube production reduces freight costs and foundation tolerance sensitivity for Southwest EPCs. |
| Pre-Assembled Structural Subassemblies | Factory-integrated racking cuts field labor hours in tight electrical trades markets across the Desert Southwest. |
| Utility-Scale EPC Partnership Consolidation | Direct manufacturer relationships absorb interface risk and accelerate interconnection readiness timelines. |
| Agrivoltaic Configuration Development | Elevated racking designs capture agricultural land-use premiums in Great Plains wind-solar hybrid zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across EPC contractors, utility planning officers, racking procurement leads, and steel mill certification specialists. FERC interconnection queue databases, EIA generation capacity reports, IRS domestic content guidance documents, and state public utility commission dockets supplied quantitative scaffolding. Bottom-up project pipeline tracking and top-down steel consumption estimates were triangulated to validate market sizing.
Data-stream reconciliation across utility-scale procurement databases, steel mill shipment records, and EPC contract announcements informed the analytical framework. Segmentation dimensions modeled include module technology type, end-user scale tier, installation foundation type, and distribution channel structure across the projection horizon. CAGRs were derived from installed capacity forecasts cross-referenced with structural steel intensity coefficients and domestic content compliance adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interconnection queue reform timing and domestic content threshold escalations under IRA provisions. Forecasts reflect documented assumptions about steel mill capacity expansion and tariff policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Solar Carport Market