
 Solar Grid-Tied Systems Market | 2026-2036
Solar Grid-Tied Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Grid-Tied Systems Market Insights
The EU Green Deal's carbon border adjustment mechanism is decoupling solar procurement from fossil-intensive supply chains across European markets. JinkoSolar leverages vertically integrated wafer-to-module capacity to sustain cost leadership in utility-scale tenders. Canadian Solar anchors North American project development through its Guelph manufacturing footprint and downstream EPC capabilities.
Solar grid-tied systems connect photovoltaic arrays directly to the utility network through synchronous inverters that match grid frequency and voltage parameters, typically operating at 480V AC three-phase for commercial installations and 240V AC split-phase for residential feeds. The primary purpose is to offset on-site consumption while exporting surplus generation under net metering or feed-in tariff structures. Monocrystalline panels dominate capacity additions due to superior wattage density and declining per-watt premiums over polycrystalline alternatives. Utility-scale applications concentrate the fastest growth trajectory, driven by power purchase agreement tenors and institutional investor appetite for contracted cash flows.
US developers navigate IRA domestic content bonus thresholds set by the Treasury Department, while European installers face REACH compliance for module encapsulant chemistries and the EU's F-Gas Regulation on inverter refrigerants. India's BIS certification mandates and the PLI scheme for solar module manufacturing are reshaping supplier qualification requirements across South Asian procurement. Stakeholders must track how inverter interoperability standards evolve under IEEE 1547 and IEC 61727 revisions to avoid stranded asset risk in multi-vendor installations.
Market Dynamics
Utility-scale procurement consolidation is compressing margin structures across the solar grid-tied value chain as power purchasers bundle storage co-location requirements into single-source tenders.
Growth Catalysts
- IRA Production Tax Credits:Treasury Department domestic content bonus thresholds are accelerating capital deployment into US module assembly and polysilicon purification capacity.
- EU Carbon Border Adjustment:The EU Green Deal mechanism is decoupling European procurement from fossil-intensive wafer supply chains, redirecting sourcing toward low-carbon manufacturing clusters.
- Topcon Cell Architecture:Tunnel oxide passivated contact technology is displacing PERC dominance in utility-scale tenders through superior temperature coefficients and bifacial gain.
Market Restraints
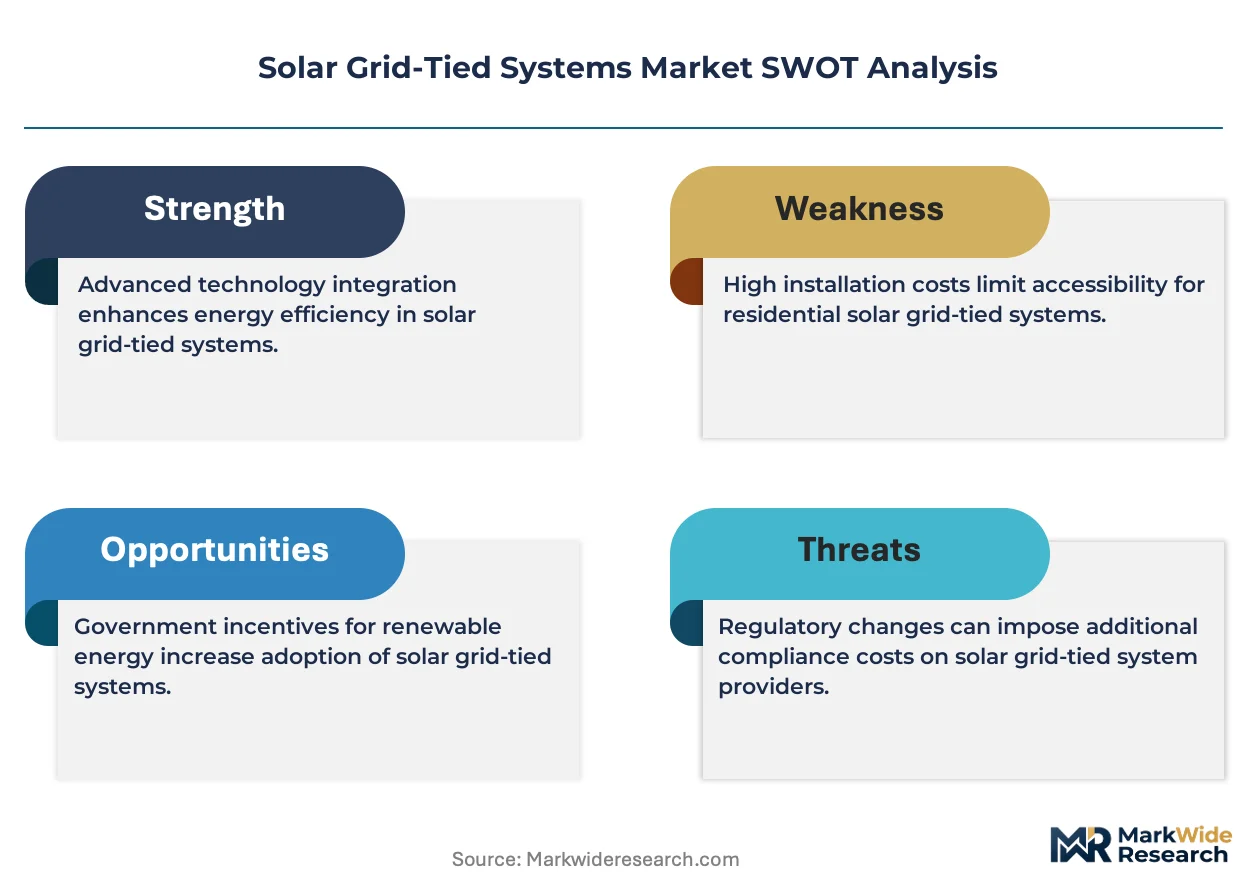
- Polysilicon Supply Concentration:Xinjiang-origin material faces exclusion risk under forced labor due diligence laws, constraining wafer availability for non-vertically integrated module suppliers.
- Silver Paste Cost Volatility:Metallization paste accounts for rising share of cell manufacturing cost, with silver price spikes transmitted directly to module pricing.
- Interconnection Queue Friction:Regional transmission organization study backlogs in ERCOT and CAISO territories are extending project energization timelines by 24-36 months.
Strategic Opportunities
- Agrivoltaics Deployment:Dual-use solar-plus-agriculture installations are unlocking previously restricted rural land access in France and Japan through revised zoning frameworks.
- Virtual Power Plant Aggregation:Residential inverter fleet orchestration is expanding into frequency regulation markets as IEEE 1547-2018 smart inverter requirements mature.
- India PLI Scheme:Production-linked incentive disbursements for solar module manufacturing are attracting cell and wafer capacity migration to Gujarat and Tamil Nadu special economic zones.
Industry Challenges
- Skilled EPC Labor Scarcity:Journeyman electricians certified for medium-voltage DC-to-AC interconnection work command wage premiums exceeding 40% in Texas and Arizona construction markets.
- Multi-Vendor Interoperability:Stranded asset risk accumulates where inverter firmware revisions diverge from utility SCADA integration protocols during system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Grid-Tied Systems Market |
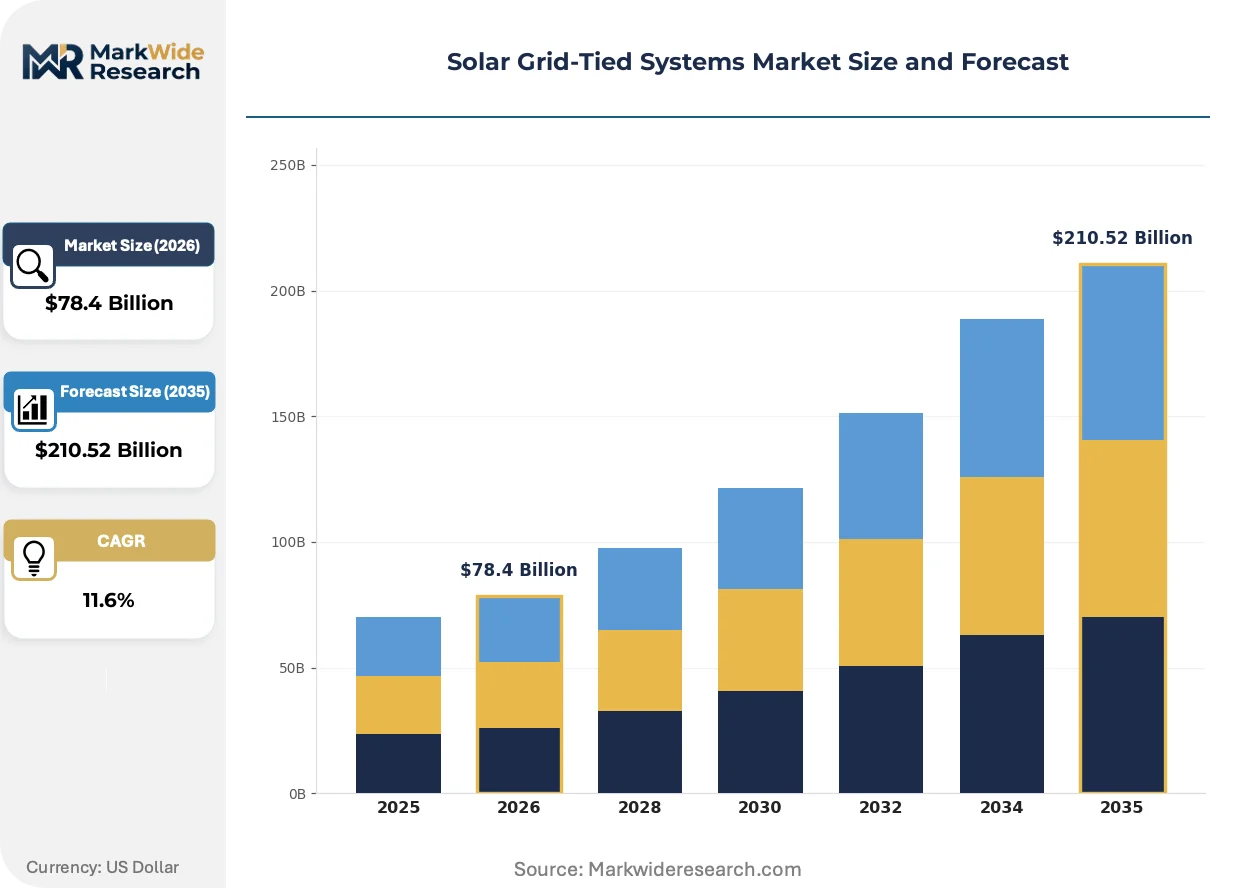
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $210.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverters, Solar Panels, Monitoring Systems, Wiring Application: Residential, Commercial, Industrial, Utility Scale Technology: Monocrystalline, Polycrystalline, Thin Film, Bifacial End User: Homeowners, Businesses, Utilities, Contractors |
| Companies Covered | SunPower Corporation, Canadian Solar Inc, JinkoSolar Holding Co. Ltd, Trina Solar, LONGi Solar, JA Solar, Huawei Technologies, KYOCERA Corporation, Hanwha Q CELLS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Grid-Tied Systems Market Trends and Innovations
Module efficiency trajectories and inverter intelligence are converging to reshape competitive positioning across residential, commercial, and utility-scale deployment tiers.
TOPCon cell architecture is expanding into utility-scale procurement specifications as developers prioritize levelized cost of energy over upfront capital minimization. EPC contractors in the US Southwest and Australian Queensland markets are specifying n-type bifacial modules for 1500V DC string configurations. This technology shift is compressing PERC capacity utilization rates among legacy cell manufacturers without backward integration into tunnel oxide deposition equipment.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in transformer-cooled inverters above 100kW rated capacity. Inverter OEMs are accelerating dry-type transformer and dielectric fluid substitution programs to maintain CE marking compliance. Utility-scale project developers in Germany and Spain are absorbing 8-12% BOM cost premiums for F-Gas-compliant hardware to avoid construction timeline risk.
Corporate offtakers are unbundling engineering-procurement-construction contracts into separate engineering and construction management agreements. Large technology and data center operators in Northern Virginia and Singapore are retaining direct module and inverter procurement authority while outsourcing installation labor. This disintermediation is compressing EPC margin pools and transferring supply chain risk to balance-sheet-backed end-users with superior counterparty ratings.
Solar Grid-Tied Systems Market Segmentation
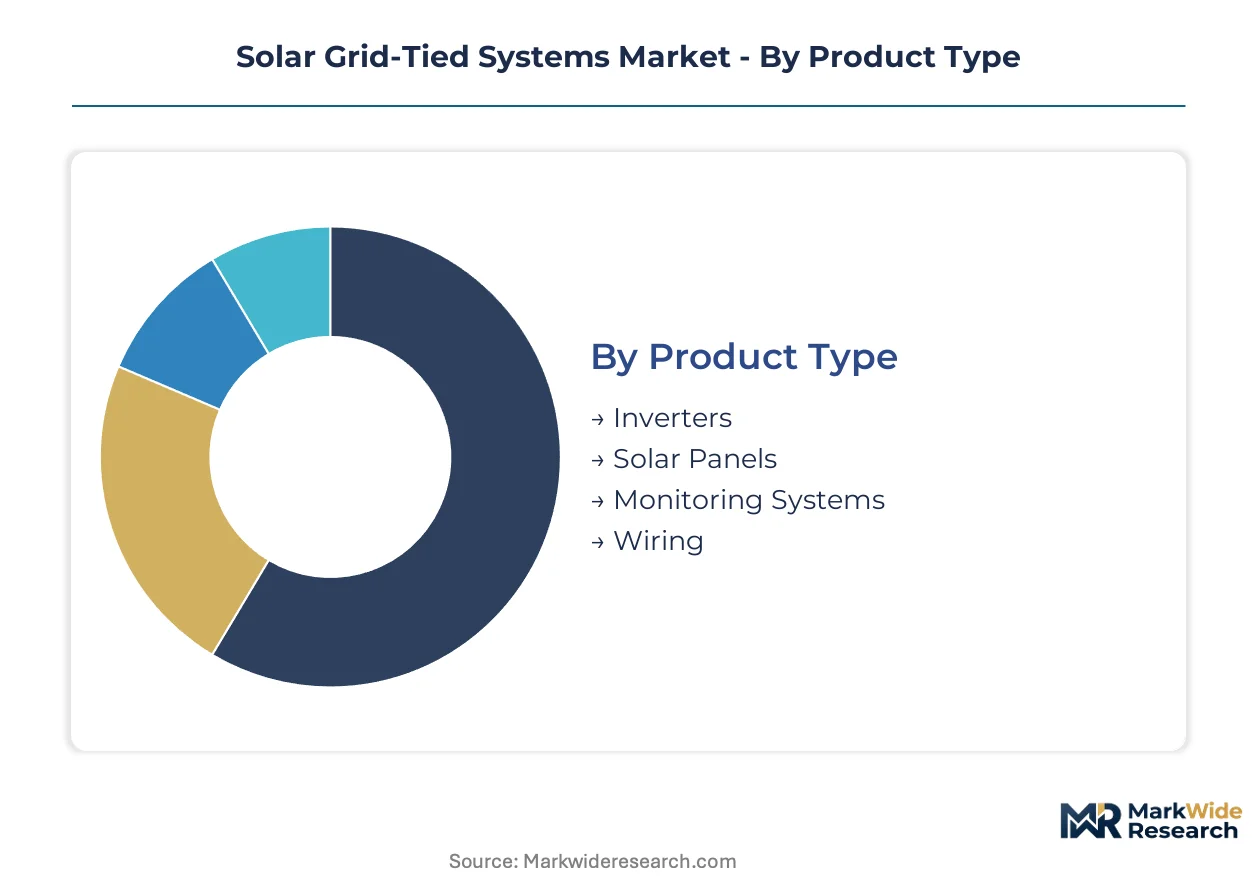
Segmentation in solar grid-tied systems reveals how hardware specifications, deployment scale, and customer procurement authority reshape vendor go-to-market strategies. Each dimension carries distinct margin structures, certification requirements, and channel access rules that determine competitive positioning.
Product Type:
Standalone power conversion equipment commands the highest engineering intensity, while embedded electrical infrastructure operates on commodity cost curves.
- Inverters:Synchronous power electronics match DC array output to grid frequency and voltage parameters, with string inverters dominating residential deployments and central inverters anchoring utility-scale substations. US developers prioritize IEEE 1547-2018 compliant hardware to access IRA domestic content bonuses, while European procurement screens for F-Gas Regulation compliance on transformer-cooled units above 100kW.
- Solar Panels:Monocrystalline silicon wafers laminated between tempered glass and encapsulant layers convert photon flux to direct current, with n-type TOPCon architecture displacing PERC in utility tenders. Module suppliers face forced labor due diligence audits on polysilicon sourcing, constraining qualification lists for federally subsidized US projects.
- Monitoring Systems:SCADA-integrated data loggers track string-level performance and fault detection, enabling predictive maintenance contracts.
- Wiring:PV-rated copper conductors and MC4 connector assemblies complete circuit paths between array and interconnection point.
Solar panels lead volumes today; inverters are gaining share fastest through smart grid functionality premiums.
Application:
Deployment scale determines interconnection voltage, permitting complexity, and offtaker counterparty risk in procurement economics.
- Residential:Rooftop arrays under 20kW AC capacity connect through 240V split-phase service panels, with net metering tariffs driving payback calculations. California NEM 3.0 reforms and similar rate structure revisions in Arizona and Hawaii are compressing export compensation rates and accelerating battery attachment rates.
- Utility Scale:Ground-mounted installations above 5MW AC feed 34.5kV or higher collector systems through power purchase agreements with investment-grade offtakers. ERCOT and CAISO interconnection queues now extend 24-36 months, forcing developers to secure site control years ahead of anticipated energization.
- Commercial:Behind-the-meter systems from 20kW to 2MW serve retail, logistics, and manufacturing load centers with demand charge mitigation as primary value proposition.
- Industrial:Large onsite generation for heavy manufacturing and data center campuses, often paired with direct procurement of renewable energy certificates.
Utility scale leads volumes today; residential is gaining share fastest through virtual power plant aggregation revenue streams.
Technology:
Cell architecture and module form factor trade off efficiency premiums against balance-of-system cost minimization.
- Monocrystalline:Single-crystal silicon ingots sliced into wafers yield 20-22% cell efficiency, with passivated emitter rear contact (PERC) and tunnel oxide passivated contact (TOPCon) variants dominating capacity additions. Bifacial gain coefficients of 8-12% in high-albedo desert installations are reshaping tender specifications in Nevada and Rajasthan.
- Bifacial:Dual-glass construction with transparent backsheet enables rear-side photon collection, delivering superior energy yield in utility-scale tracking configurations. EPC contractors in Queensland and the US Southwest specify 1500V DC string architectures with n-type bifacial modules to minimize land use and cabling costs.
- Polycrystalline:Multi-crystal silicon formed through directional solidification, now relegated to price-sensitive distributed markets.
- Thin Film:Cadmium telluride and copper indium gallium selenide absorber layers on glass substrates, retaining niche position in building-integrated applications.
Monocrystalline leads volumes today; bifacial is gaining share fastest through utility-scale tender penetration.
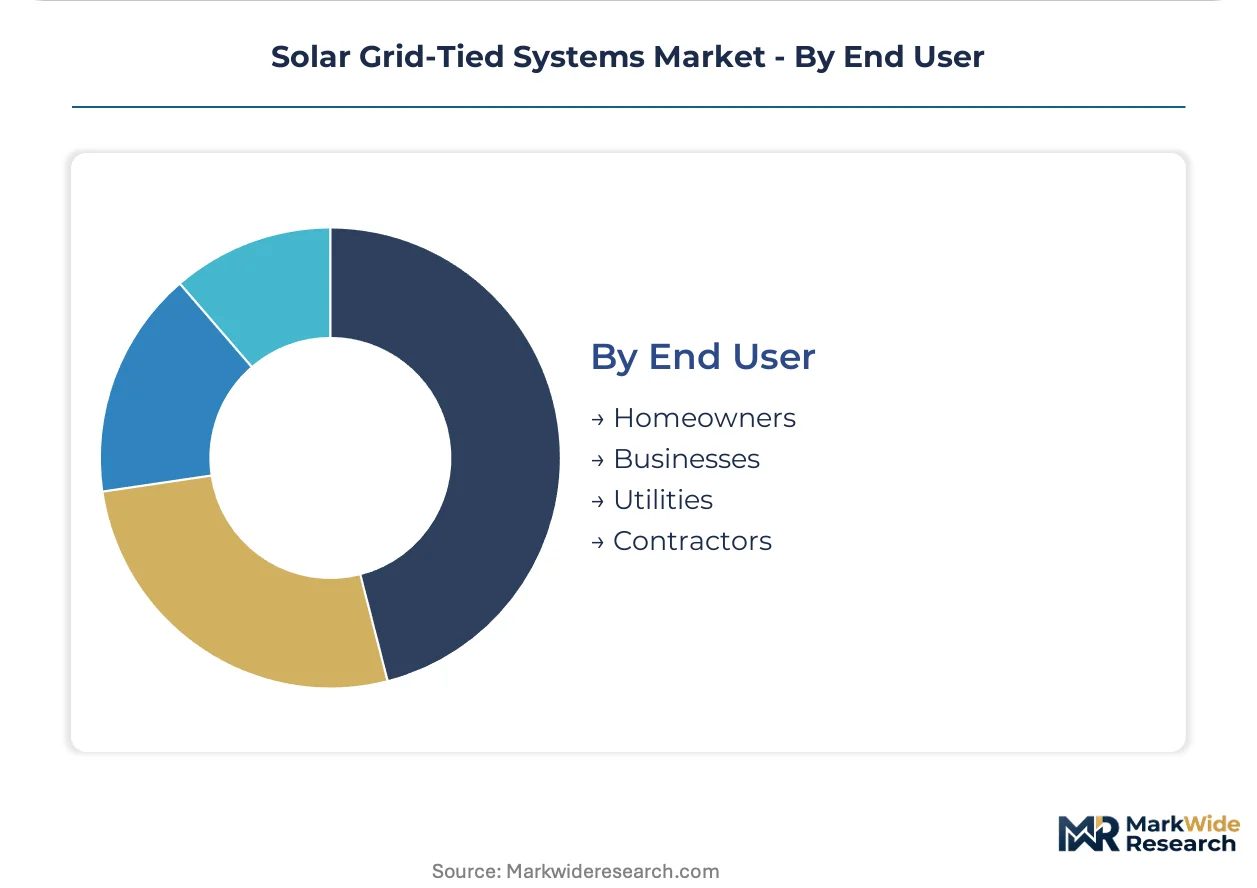
End User:
Procurement authority and technical sophistication determine channel structure and service attachment rates.
- Utilities:Vertically integrated power providers and independent power producers issue engineering-procurement-construction tenders with 20-25 year contracted revenue streams, driving module and inverter OEM direct sales relationships. Dominion Energy, NextEra, and Engie retain in-house development teams while outsourcing construction management.
- Businesses:Corporate offtakers with investment-grade credit ratings negotiate virtual power purchase agreements and green tariff structures, unbundling EPC contracts to retain direct equipment procurement authority. Northern Virginia data center operators and Singapore semiconductor fabricators now source modules and inverters independently.
- Homeowners:Retail customers purchasing through installer-dealer networks with third-party financing or cash transactions.
- Contractors:Electrical and roofing trades executing installation labor under construction management agreements.
Utilities lead volumes today; businesses are gaining share fastest through corporate renewable procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered grid-tied solar deployment through its 2000 Renewable Energy Act feed-in tariffs, establishing the regulatory template that China, the United States, and India later adapted for mass-scale adoption.
United States
Utility-scale developers in Texas and California face ERCOT and CAISO interconnection queues extending 24-36 months. The Treasury Department's domestic content bonus thresholds under IRA production tax credits are accelerating polysilicon purification investments in Washington and Georgia. Arizona and Nevada host the fastest-growing utility-scale clusters, with EPC contractors specifying 1500V DC bifacial configurations for desert albedo conditions.
China
Wafer and cell manufacturing concentrates in Jiangsu and Anhui provinces, with tunnel oxide passivated contact capacity expanding rapidly. The country's dual carbon goals mandate renewable capacity additions that absorb domestic module production. Xinjiang-origin polysilicon faces exclusion risk under forced labor due diligence laws, constraining export qualification for non-vertically integrated suppliers.
India
Gujarat and Tamil Nadu special economic zones are attracting cell and wafer capacity migration under PLI scheme disbursements. BIS certification mandates reshape supplier qualification requirements for federally subsidized projects. Rajasthan hosts the largest utility-scale installations, with developers leveraging high irradiance and revised land acquisition frameworks.
Germany
Agrivoltaics deployment unlocks previously restricted rural land access through revised zoning frameworks in Bavaria and Baden-Württemberg. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in transformer-cooled inverters above 100kW. The country's carbon border adjustment mechanism redirects procurement toward low-carbon manufacturing clusters.
Australia
Queensland and New South Wales EPC contractors specify n-type bifacial modules for 1500V DC string configurations to minimize land use. Virtual power plant aggregation of residential inverter fleets expands into frequency regulation markets. The country's distributed solar penetration rate drives smart inverter requirements under evolving grid stability protocols.
Solar Grid-Tied Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the solar grid-tied value chain. Vertically integrated cell-to-module manufacturers command cost advantages in utility-scale tenders, while specialized inverter OEMs capture margin through power electronics intelligence. Three archetypes dominate: wafer-to-module integrated suppliers, project development arms of module manufacturers, and pure-play power electronics firms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure polysilicon offtake and interconnection queue positions.
Among Asia-Pacific module fabricators, JinkoSolar Holding Co. Ltd, LONGi Solar, and Trina Solar occupy positions within the integrated-supplier tier, representing the scale-driven end of competitive positioning. Canadian Solar Inc exemplifies the project-development-integrated archetype through its North American EPC capabilities. These entities anchor the vendor landscape without exhausting its diversity.
| Leading Market Players |
|---|
| SunPower Corporation |
| Canadian Solar Inc |
| JinkoSolar Holding Co. Ltd |
| Trina Solar |
| LONGi Solar |
| JA Solar |
| Huawei Technologies |
| KYOCERA Corporation |
| Hanwha Q CELLS |
| Others |
Pricing and Supply Chain Analysis
Silver paste spot indices cascade through cell metallization costs, compressing module pricing tiers as polysilicon contract benchmarks reset quarterly. Procurement officers in utility-scale tenders track these input oscillations to time inventory builds and negotiate pass-through clauses with EPC partners.
Pricing Analysis
Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation resting on module efficiency tier and domestic content certification grade. Premium n-type TOPCon modules with IRA-compliant supply chains command margin premiums over standard PERC alternatives. Cost compression in the standard tier intensifies as Chinese wafer capacity floods tender markets. Corporate offtakers with direct procurement authority exhibit lowest price sensitivity; residential installer networks face acute margin pressure from financing spread compression.
Supply Chain Analysis
Container freight rates from Shanghai to Rotterdam and Los Angeles anchor landed cost calculations for module imports into European and North American markets. Manufacturing concentrates in China, Vietnam, and Thailand as Southeast Asian assembly capacity expands to circumvent tariff exposure. Polysilicon feedstock draws from Xinjiang, Inner Mongolia, and Malaysian purification facilities. Single-source vulnerability concentrates in silver paste supply from Japanese and South Korean metallization specialists. Distribution runs through EPC contractors for utility-scale deployment and installer-dealer networks for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module efficiency upgrades and smart inverter premiums are expanding margin capture opportunities for suppliers with captive polysilicon and certified domestic content. TOPCon migration and IRA bonus qualification reshape competitive economics across deployment tiers.
For Market Incumbents: Deepen backward integration into polysilicon purification to secure IRA domestic content bonus thresholds and insulate against Xinjiang-origin exclusion risk. Expand tunnel oxide deposition capacity to maintain cost leadership as PERC utilization rates compress. Prioritize EPC contractor relationships in ERCOT and CAISO queue positions to lock in project development pipelines before interconnection study backlogs extend further. For New Entrants and Emerging Players: EPC contractors in agrivoltaics deployment represent the most penetrable channel partner type for specialized mounting and tracking hardware. Target France and Japan where revised zoning frameworks unlock restricted rural land access. Pursue white-label inverter assembly for virtual power plant aggregation platforms as IEEE 1547-2018 compliance mandates mature in residential markets. For Investors and Strategic Acquirers: Asymmetric upside sits with project development arms of integrated module manufacturers holding interconnection queue positions in Arizona and Nevada. Long-term viability hinges on technology licensing revenue streams and storage co-location capabilities rather than pure hardware manufacturing scale. Monitor FERC interconnection rulemaking and Treasury Department domestic content guidance releases as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| TOPCon Cell Capacity Buildout | N-type architecture displaces PERC dominance in utility tenders through superior temperature coefficients. |
| IRA Domestic Content Certification | Treasury Department bonus thresholds accelerate polysilicon purification investments in Washington and Georgia. |
| Agrivoltaics Zoning Partnership | Dual-use installations unlock restricted rural land access in Bavaria and Baden-Württemberg regulatory frameworks. |
| Virtual Power Plant Platform Integration | Residential inverter fleet orchestration expands into ERCOT frequency regulation markets. |
| F-Gas Compliant Inverter Transition | Dry-type transformer substitution maintains CE marking access for German and Spanish utility-scale projects. |
Research Methodology
Multiple input streams — utility interconnection queue databases, module shipment manifests, and EPC contract registries — were reconciled with primary interviews across the solar grid-tied value chain. Stakeholder consultations included IPP project developers, utility planning officers, EPC contractors, grid operators, and polysilicon procurement specialists. Secondary validation drew from EIA generation data, IEA renewable market reports, FERC interconnection filings, and customs trade records. Bottom-up project pipelines and top-down manufacturing capacity estimates were triangulated to anchor volume forecasts.
Data-stream reconciliation across these sources informed analytical frameworks spanning module technology tier, project scale segmentation, regulatory framework cluster, and regional grid type. CAGRs were derived from capacity addition trajectories and capital deployment patterns throughout the projection horizon. Forecast inputs incorporated IRA domestic content bonus qualification rates, EU carbon border adjustment implementation phases, and silver paste price volatility assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interconnection queue reform, forced labor due diligence enforcement, and cell architecture substitution rates. Forecasts reflect documented assumptions on policy continuity and commodity price bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
US Solar Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market