
 Amorphous Silicon PV Market | 2026-2036
Amorphous Silicon PV Market Size, Share, and Industry Trends Forecast 2026-2036
Amorphous Silicon PV Market Analysis
Thin-film tandem junction architectures is rewriting module efficiency trajectories for amorphous silicon photovoltaics. First Solar leverages cadmium telluride expertise to anchor its thin-film R&D pipeline adjacent to amorphous silicon advances. Mitsubishi Electric Corporation sustains proprietary plasma-enhanced chemical vapor deposition capabilities in Japanese manufacturing facilities. Sharp Corporation dominates residential rooftop segments through integrated building material distribution channels in Osaka and Tokyo metropolitan areas.
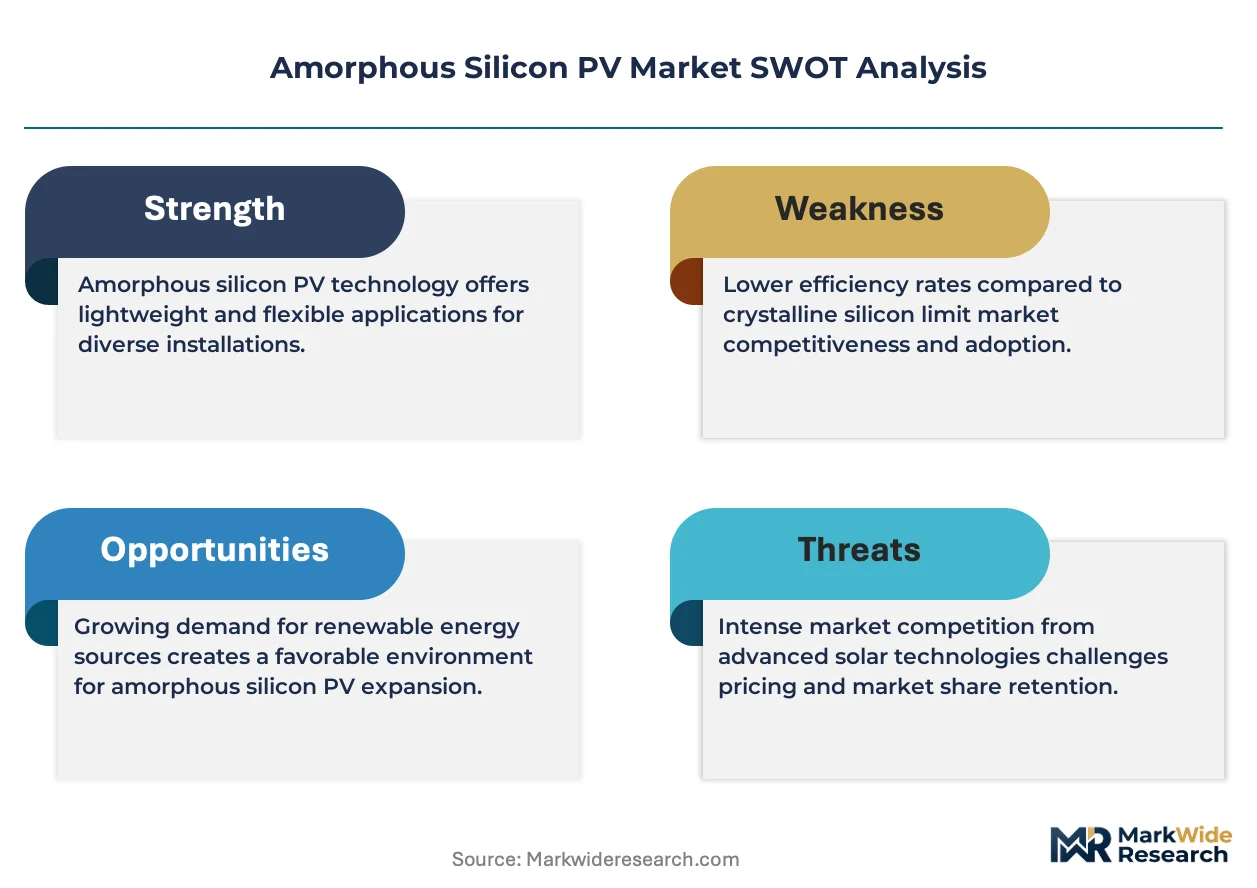
Amorphous silicon photovoltaics employ non-crystalline silicon deposited in thin layers typically one to two micrometers thick onto glass, metal, or flexible polymer substrates through plasma-enhanced chemical vapor deposition at temperatures below 300 degrees Celsius, delivering lightweight power generation for building-integrated and portable applications where crystalline silicon weight and rigidity prove prohibitive. Thin-film modules capture the majority of installed capacity owing to mature roll-to-roll manufacturing economics and established warranty frameworks. Flexible panels represent the fastest-expanding product category as aerospace and portable electronics manufacturers specify bend radii below five millimeters. Building-integrated modules concentrate margin pools in premium architectural glazing contracts where aesthetic and structural performance requirements exclude conventional framed alternatives.
Japan's METI enforces JIS C 8990 testing protocols that shape module durability certification requirements for domestic installations. China's SAMR administers GB/T 9535 standards governing terrestrial photovoltaic performance characterization while MEE implements dual carbon compliance timelines affecting silicon feedstock energy intensity benchmarks. India's BIS adoption of IEC 61215 for thin-film qualification creates parallel certification pathways for export-oriented manufacturers. Stakeholders must monitor evolving efficiency thresholds in building codes and grid interconnection standards as jurisdictions recalibrate renewable portfolio obligations without explicit technology mandates.
Market Dynamics
Thin-film tandem junction architectures are compressing efficiency gaps with crystalline silicon, redirecting capital toward low-temperature deposition equipment and specialized glass substrate supply chains.
Growth Catalysts
- Japan's METI feed-in tariff revisions:Premium rates for building-integrated installations accelerate thin-film adoption in residential retrofits across Osaka and Tokyo metropolitan corridors.
- Plasma-enhanced chemical vapor deposition advances:Process temperature reductions below 250 degrees Celsius unlock polymer substrate compatibility for aerospace and portable electronics specifications.
- China's dual carbon compliance timelines:Manufacturing energy intensity benchmarks favor amorphous silicon's lower thermal budget versus crystalline alternatives in Jiangsu province production clusters.
Market Restraints
- Silane gas supply concentration:Six specialty chemical producers control global high-purity feedstock, exposing module manufacturers to input cost volatility and allocation constraints.
- Efficiency ceiling limitations:Single-junction amorphous silicon stabilizes below tandem architectures, restricting addressable market share in utility-scale ground-mounted installations.
- GB/T 9535 certification friction:China's SAMR terrestrial performance standards create parallel testing requirements that extend product qualification timelines versus IEC pathways.
Strategic Opportunities
- India's BIS IEC 61215 adoption:Thin-film qualification pathway creates export manufacturing foothold for producers seeking alternative to saturated East Asian markets.
- Automotive integrated photovoltaics:Curved glass and polymer substrate compatibility positions amorphous silicon for vehicle-integrated sunroof and body panel applications.
- Roll-to-roll manufacturing convergence with printed electronics:Shared capital equipment and process expertise with flexible circuit production lowers barrier to capacity expansion.
Industry Challenges
- Plasma process engineering talent scarcity:Specialized PECVD equipment operation and thin-film metrology expertise concentrates in Japan's Kansai region and select German research institutes.
- JIS C 8990 durability certification timelines:Extended thermal cycling and humidity freeze testing protocols delay product release schedules for domestic Japanese market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amorphous Silicon PV Market |
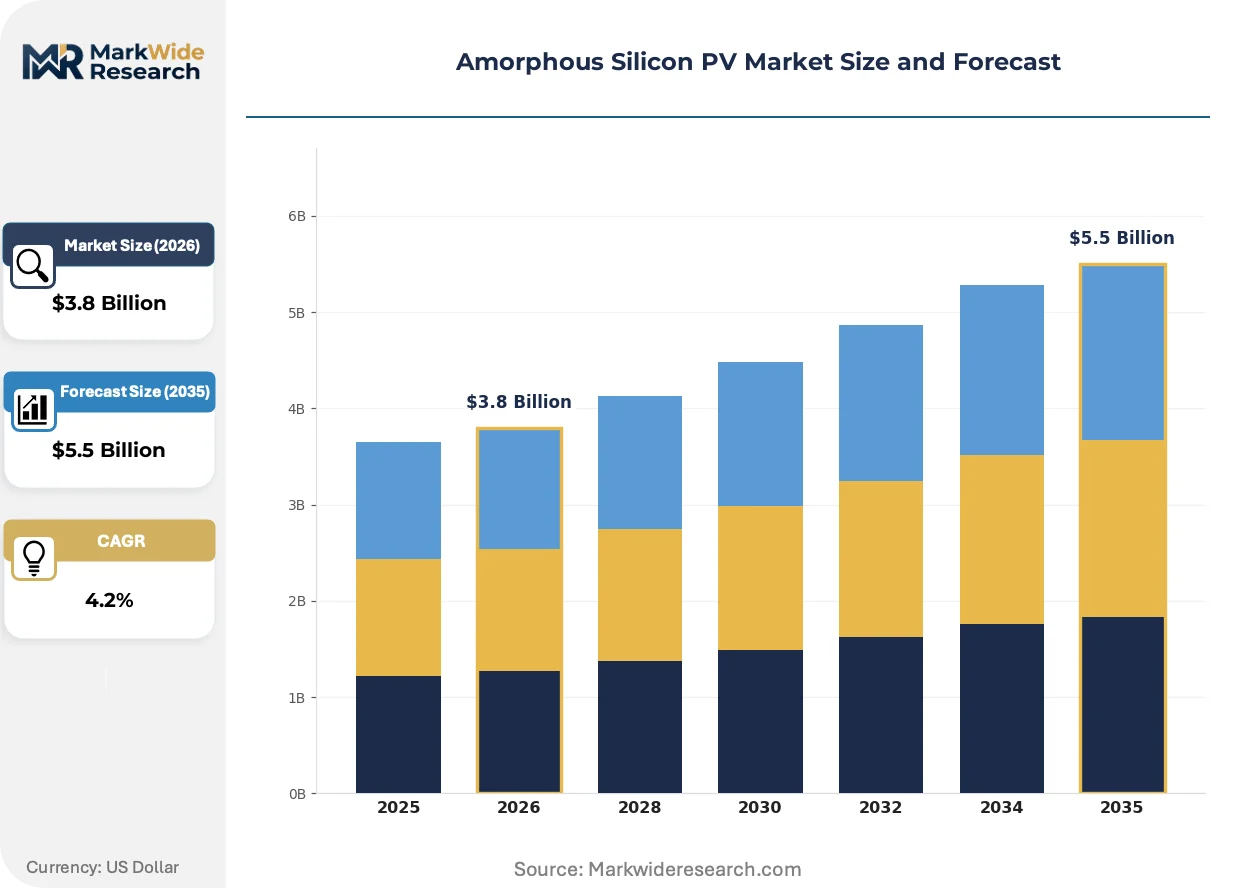
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Modules, Bifacial Panels, Building-Integrated Modules, Flexible Panels Installation Type: Rooftop Systems, Ground-Mounted Systems, Off-Grid Installations, Grid-Connected Installations End User: Residential Users, Commercial Establishments, Industrial Facilities, Utilities Application: Power Generation, Energy Storage, Transportation Solutions, Smart Grids |
| Companies Covered | Hanergy Thin Film Power Group, First Solar, Uni-Solar, Mitsubishi Electric Corporation, Ascent Solar Technologies, Solar Frontier, Sharp Corporation, Panasonic Corporation, Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amorphous Silicon PV Market Emerging Trajectories
Deposition equipment and substrate materials are converging to enable sub-two-micrometer active layers with stabilized efficiencies approaching tandem thresholds, compressing the traditional performance gap with crystalline alternatives.
Silicon-germanium alloy absorber layers are rendering obsolete pure amorphous silicon single-junction designs in premium building-integrated applications. Architectural glazing contractors in Germany and Japan specify these structures for projects where aesthetic uniformity and structural load limits exclude framed crystalline modules. The technology is rendering obsolete previous generation micromorph tandem designs that required thicker silicon deposition.
China's MEE dual carbon enforcement is tightening silicon feedstock energy intensity benchmarks for domestic manufacturing licenses. Module producers in Jiangsu province are retrofitting deposition chambers with regenerative thermal oxidizers to capture silane byproducts and reduce compliance costs. Thin-film qualification under GB/T 9535 now requires documented carbon footprint accounting alongside traditional performance metrics.
Specification processes in commercial building projects are compressing vendor evaluation cycles from eighteen months to six months. Engineering-procurement-construction firms in Japan's Kansai region now pre-qualify module suppliers through integrated building material distribution channels rather than direct manufacturer engagement. This channel consolidation favors producers with established Sharp Corporation-style partnerships over independent thin-film specialists.
Amorphous Silicon PV Market Segmentation
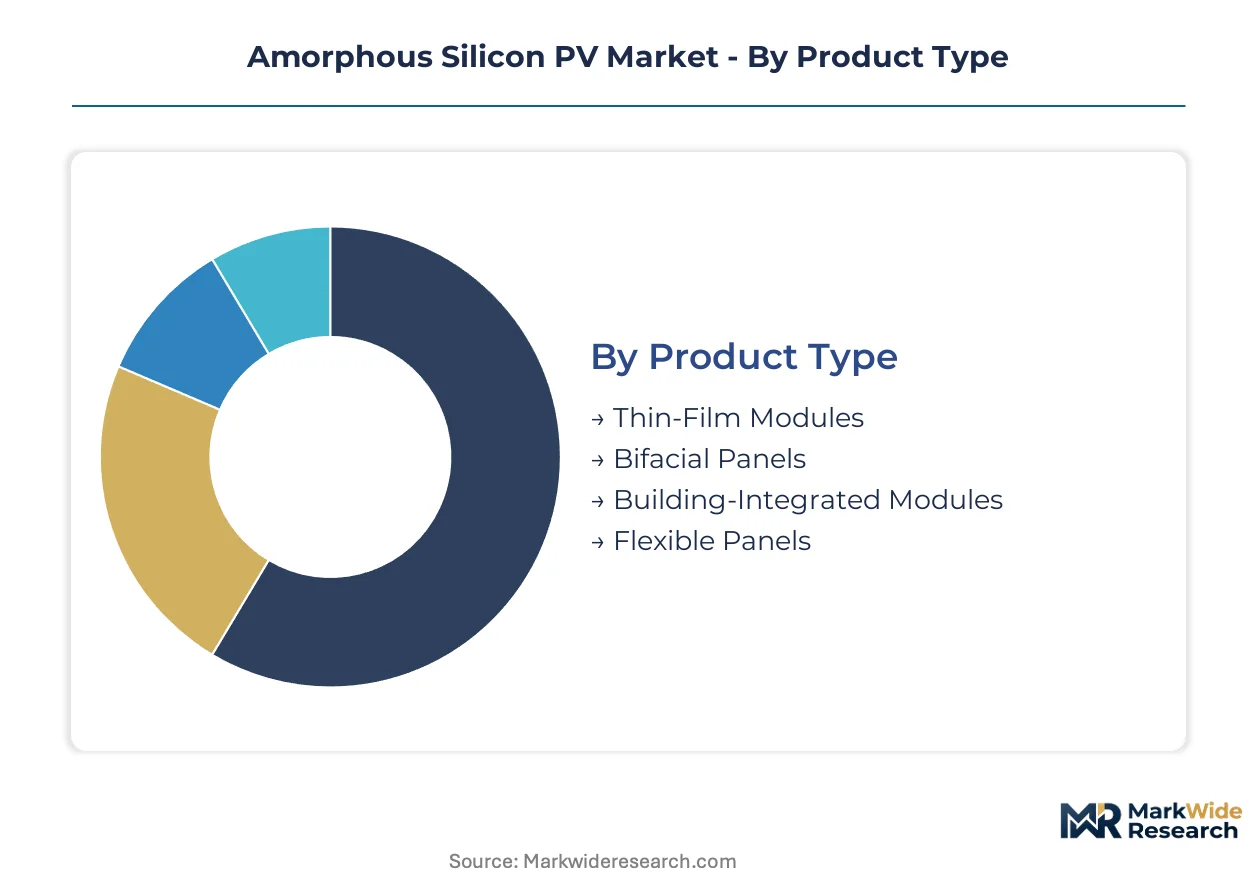
Amorphous silicon photovoltaics fragment across substrate flexibility, mounting configuration, and buyer sophistication tiers. Each segmentation axis reveals distinct margin pools and technical barriers that shape vendor positioning.
Product Type:
Mature roll-to-roll manufacturing anchors established categories while polymer substrate compatibility opens frontier applications.
- Thin-Film Modules:Glass-substrate deposition at sub-300°C thermal budgets delivers standardized wattage for utility and commercial procurement. Demand concentrates in Jiangsu province production clusters where China's MEE dual carbon benchmarks favor low-energy intensity processes over crystalline alternatives.
- Flexible Panels:Polyimide and stainless-steel substrates achieve sub-5mm bend radii for aerospace specifications and portable electronics integration. Japanese aerospace manufacturers in the Kansai region specify these structures for satellite and high-altitude platform applications where mass reduction commands premium pricing.
- Bifacial Panels:Double-sided light capture architectures using transparent conductive oxide rear contacts.
- Building-Integrated Modules:Architectural glazing with embedded photovoltaic layers for structural curtainwall specifications.
Thin-film modules retain volume leadership; flexible panels hold the steepest expansion curve.
Installation Type:
Mounting configuration determines balance-of-system complexity and interconnection standard applicability.
- Rooftop Systems:Distributed generation deployments on residential and commercial structures. Japan's METI feed-in tariff revisions accelerate adoption across Osaka and Tokyo metropolitan corridors where building-integrated aesthetics override efficiency maximization.
- Ground-Mounted Systems:Utility-scale field installations requiring framed module rigidity and tracker compatibility. Efficiency ceiling limitations of single-junction amorphous silicon restrict addressable share in these installations against crystalline alternatives.
- Off-Grid Installations:Remote power systems with battery coupling for rural electrification and telecommunications.
- Grid-Connected Installations:Net-metered distributed generation with inverter synchronization requirements.
Rooftop systems dominate installed base; off-grid installations are expanding most quickly in emerging electrification programs.
End User:
Buyer sophistication tiers separate specification-driven procurement from price-sensitive commodity purchasing.
- Residential Users:Individual homeowners purchasing through building material distribution channels. Sharp Corporation's integrated channel partnerships in Japan's Kansai and Tokyo regions demonstrate how established building supply relationships override direct manufacturer engagement.
- Commercial Establishments:Corporate and institutional buyers with sustainability mandates and long-term power purchase agreements. Engineering-procurement-construction firms now compress vendor qualification cycles from eighteen months to six months, favoring pre-qualified suppliers.
- Industrial Facilities:Manufacturing and processing plants with high load factors and self-consumption optimization.
- Utilities:Centralized generation owners procuring through competitive auctions and renewable portfolio obligations.
Commercial establishments anchor revenue concentration; residential users are gaining share fastest through retrofit acceleration programs.
Application:
Functional use cases span electricity production through integrated system architectures.
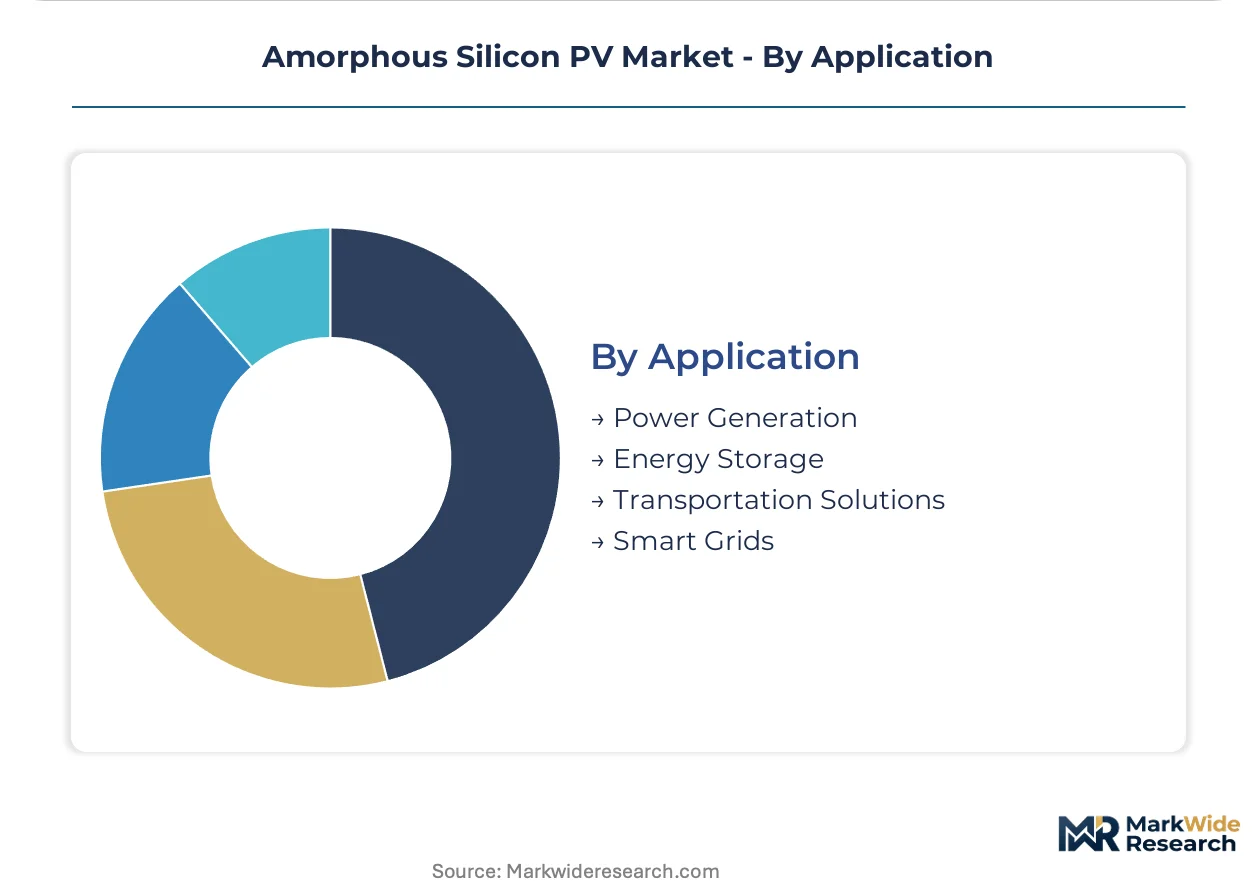
- Power Generation:Direct electricity conversion for immediate consumption or grid injection. Thin-film tandem junction architectures are compressing efficiency gaps with crystalline silicon in premium building-integrated segments where aesthetic requirements exclude conventional framed modules.
- Transportation Solutions:Vehicle-integrated photovoltaics for sunroof and body panel energy harvesting. Curved glass and polymer substrate compatibility positions amorphous silicon for automotive specifications requiring conformal mounting surfaces.
- Energy Storage:Coupled battery systems for dispatchable renewable output and grid stabilization services.
- Smart Grids:Distributed generation with communication-enabled demand response and voltage regulation.
Power generation retains volume leadership; transportation solutions hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Building-integrated photovoltaic procurement concentrates with engineering-procurement-construction firms and architectural glazing contractors. These buyers prioritize aesthetic uniformity and structural load compliance over raw efficiency metrics. Geographic demand clusters reflect feed-in tariff structures, manufacturing energy intensity regulations, and established thin-film deposition expertise.
China
Jiangsu province production clusters dominate thin-film module volume as MEE dual carbon benchmarks favor low-temperature deposition processes. SAMR's GB/T 9535 terrestrial performance standards now require documented carbon footprint accounting alongside traditional metrics. Suzhou and Changzhou host the majority of retrofitting activity for regenerative thermal oxidizer installation.
Japan
Residential rooftop retrofits across Osaka and Tokyo metropolitan corridors accelerate under METI feed-in tariff revisions. JIS C 8990 durability certification protocols enforce extended thermal cycling and humidity freeze testing. Kansai region maintains concentrated plasma-enhanced chemical vapor deposition engineering talent pools.
Germany
Architectural glazing contractors specify silicon-germanium alloy absorber layers for premium building-integrated projects. The country's national building code efficiency thresholds recalibrate without explicit technology mandates. Bavaria and Baden-Württemberg host the primary thin-film qualification testing infrastructure.
India
BIS adoption of IEC 61215 creates parallel thin-film qualification pathways for export-oriented manufacturers. The country's renewable portfolio obligations lack technology-specific mandates. Gujarat and Maharashtra emerge as alternative manufacturing footholds for producers seeking diversification beyond East Asian saturation.
South Korea
Automotive integrated photovoltaics specifications drive polymer substrate compatibility requirements for vehicle sunroof applications. MFDS maintains pharmaceutical-grade silane gas purity standards that indirectly constrain feedstock availability. Seoul Capital Area concentrates procurement decision-making for Hyundai-Kia supplier qualification.
Amorphous Silicon PV Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct margin pools. The vendor base separates into building material distribution incumbents, thin-film deposition equipment operators, and flexible substrate specialists. Three strategic archetypes dominate: integrated electronics conglomerates with captive glass supply, pure-play thin-film module fabricators, and aerospace-focused flexible panel suppliers. Competitive moves concentrate on backward integration into silane gas supply and strategic partnerships with engineering-procurement-construction firms.
Among Japanese integrated electronics conglomerates, Mitsubishi Electric Corporation, Sharp Corporation, and Panasonic Corporation occupy positions that exemplify channel-control archetypes. These Tokyo and Osaka-based entities leverage established building material distribution relationships to compress vendor qualification cycles. Their manufacturing presence in the Kansai region anchors plasma-enhanced chemical vapor deposition capability concentration. First Solar represents the alternative archetype of cadmium telluride expertise adjacent to amorphous silicon advances, demonstrating how thin-film R&D pipelines cross-fertilize across absorber layer chemistries.
| Leading Market Players |
|---|
| Hanergy Thin Film Power Group |
| First Solar |
| Uni-Solar |
| Mitsubishi Electric Corporation |
| Ascent Solar Technologies |
| Solar Frontier |
| Sharp Corporation |
| Panasonic Corporation |
| Kaneka Corporation |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit silane gas cost volatility directly into module pricing tiers, amplifying the margin compression that already separates polymer substrate specialists from glass-substrate commodity producers across Jiangsu province manufacturing clusters.
Pricing Analysis
Cost-plus contracts with silane gas indexation dominate procurement between specialty chemical suppliers and module fabricators. Pricing stratifies across premium silicon-germanium alloy specifications, standard single-junction configurations, and economy-grade flexible panels for portable electronics. Cost compression in standard-tier modules intensifies as Chinese producers retrofit deposition chambers with regenerative thermal oxidizers to meet MEE dual carbon benchmarks. Commercial building-integrated procurement through engineering-procurement-construction firms shows the lowest price sensitivity, while utility-scale ground-mounted buyers drive the hardest volume negotiations.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for module exporters seeking building-integrated qualification under divergent GB/T 9535 and IEC 61215 pathways. Manufacturing concentrates in China's Jiangsu province, Japan's Kansai region, and select German research-to-production facilities. High-purity silane gas, specialized PECVD equipment, and transparent conductive oxide coatings anchor raw material dependencies. Distribution runs through building material wholesalers in Japan and engineering-procurement-construction consortiums in Germany rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service contracts for module performance monitoring and degradation insurance are expanding faster than hardware shipments, reframing vendor economics around recurring revenue attachment rather than capital equipment transactions alone.
For Market Incumbents: Insulate core margin pools by securing captive silane gas supply through backward integration or decade-long offtake agreements with the six global specialty chemical producers. Accelerate JIS C 8990 certification pipelines for next-generation silicon-germanium architectures before METI revises domestic durability thresholds. Channel control through Sharp Corporation-style building material distribution partnerships remains the critical defensive moat against independent thin-film specialists. For New Entrants and Emerging Players: Pursue automotive integrated photovoltaics specifications where polymer substrate compatibility requirements and curved glass conformability create specification gaps that crystalline silicon cannot fill. India's BIS IEC 61215 adoption pathway offers the most penetrable regulatory entry point for export-oriented manufacturing footholds. Engineering-procurement-construction pre-qualification programs in Japan's Kansai region represent the essential go-to-market infrastructure for commercial building-integrated procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated electronics conglomerates divesting non-core photovoltaic divisions to refocus on semiconductor or battery verticals. The five-to-ten-year viability window hinges on tandem junction efficiency trajectories closing remaining gaps with crystalline alternatives. Watch for inflection signals in automotive OEM sunroof specification volumes and aerospace flexible panel procurement acceleration from Japanese satellite manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Gas Supply | Captive feedstock sourcing mitigates allocation constraints from the six global specialty chemical producers controlling high-purity supply. |
| Silicon-Germanium Alloy Absorber Development | Advanced tandem architectures displace obsolete micromorph designs in premium German and Japanese building-integrated glazing contracts. |
| Automotive IPV Specification Pursuit | Curved polymer substrate compatibility opens vehicle sunroof and body panel applications where crystalline rigidity fails. |
| India BIS IEC 61215 Qualification | Parallel certification pathway creates manufacturing foothold alternative to saturated East Asian production clusters. |
| Regenerative Thermal Oxidizer Retrofit | Silane byproduct capture enables MEE dual carbon compliance in Jiangsu province without sacrificing deposition throughput. |
Methodological Framework
A standing panel of plasma-enhanced chemical vapor deposition equipment operators, building-integrated photovoltaic procurement managers at engineering-procurement-construction firms, architectural glazing contractors, and METI regulatory affairs specialists provided ongoing calibration across the study period. Primary interview findings were cross-validated against secondary sources including SAMR GB standards filings, METI feed-in tariff revision documents, JIS C 8990 testing protocol records, and customs trade data tracking silane gas import volumes. Bottom-up module shipment estimates from identified production facilities were reconciled with top-down addressable market sizing across substrate flexibility tiers.
Scenario-bracketing around silane gas price trajectories and METI tariff revision timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include substrate material, installation configuration, end-user sophistication tier, and regional regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle analysis rather than extrapolated from historical growth rates. Forecast inputs incorporated PECVD equipment capacity expansion announcements and building code efficiency threshold revisions in Germany and Japan.
Sensitivities concentrate around silane supply disruption scenarios, METI tariff structure revisions, and automotive IPV specification adoption curves. Forecasts reflect documented assumptions about tandem junction efficiency improvement trajectories and polymer substrate cost reduction curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Smart Solar Power Market