
 Solar Charger Market | 2026-2036
Solar Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Charger Market Outlook
Photovoltaic engineering talent shortages in Asia-Pacific is unwinding manufacturing expansion timelines for several producers. LONGi Green Energy Technology Co. Ltd. leverages its polysilicon-to-module integration to control cost curves across portable charger supply chains. Canadian Solar Inc. anchors its competitive stance through geographic diversification across utility and consumer-scale applications. Hanwha Q CELLS differentiates via PERC cell efficiency gains that translate into smaller form factors for integrated solar charger designs.
A solar charger converts photovoltaic energy into direct-current electricity stored in lithium-ion or solid-state cells for subsequent device charging, typically operating at 5V to 20V output with 15% to 24% panel conversion efficiency depending on cell architecture. Its primary commercial purpose centers on decoupling electronic power access from grid infrastructure across mobile, emergency, and off-grid use cases. Monocrystalline technology leads the technology segment due to superior energy density per surface area, while thin-film formats occupy niche positions in ultra-lightweight outdoor applications where gram reduction commands premium positioning. The application dimension shows outdoor activities and emergency power as the fastest-expanding demand pools, whereas consumer electronics represents the mature volume base with compressed margin structures.
The EU Green Deal and REACH chemical compliance frameworks in Europe, alongside the EPA's e-waste directives in the United States, collectively elevate material traceability and recyclability requirements for solar charger imports and domestic distribution. China's GB standards for photovoltaic consumer products, administered by SAMR, further shape export-ready design specifications for manufacturers serving multiple jurisdictions. Stakeholders must monitor regulatory divergence between efficiency labeling regimes and circular-economy mandates as these frameworks mature at differing speeds across production and consumption geographies.
Market Dynamics
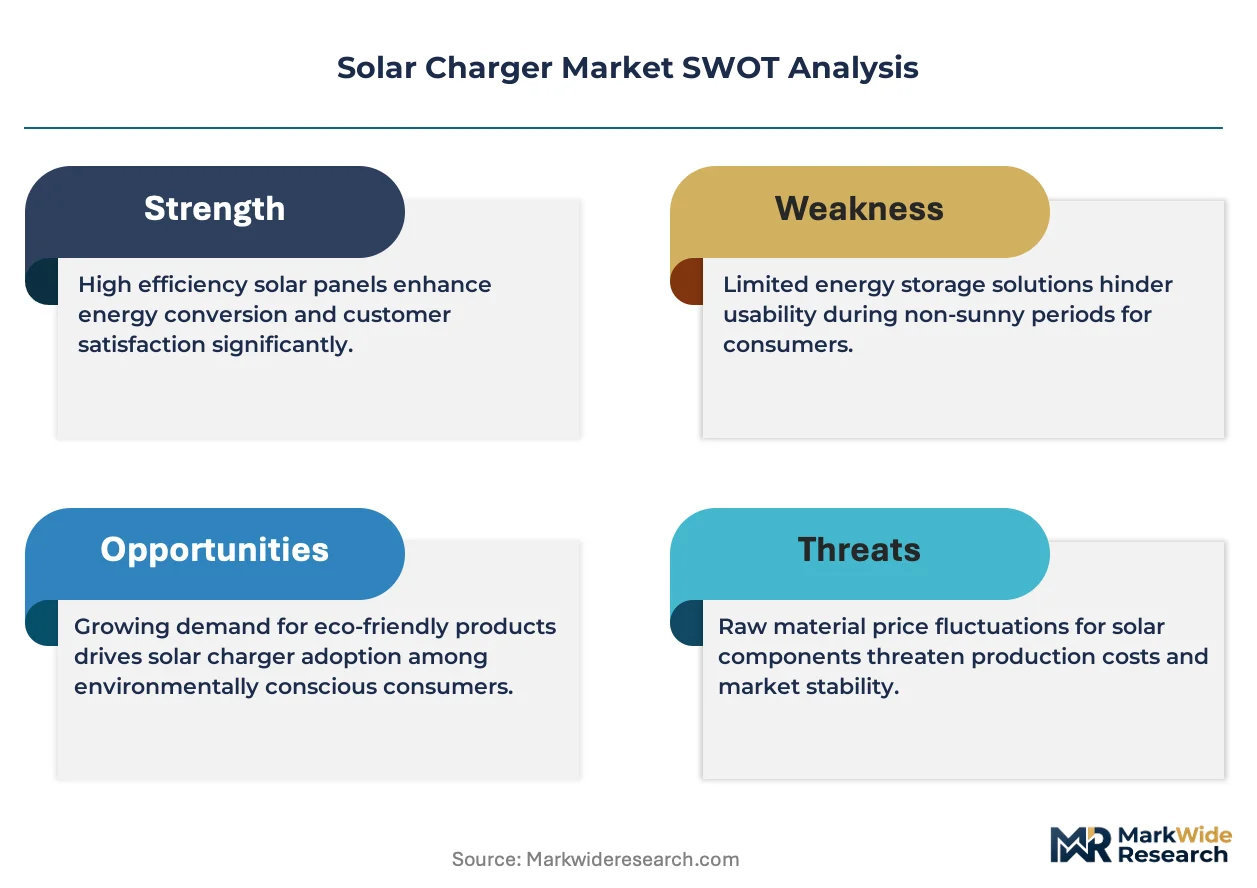
The solar charger market is experiencing structural pressure from polysilicon supply concentration in China and the EU Green Deal's cascading certification requirements, which together force manufacturers to redesign product architectures for multi-jurisdiction compliance.
Growth Catalysts
- EU Green Deal renewable mandates:The framework's binding targets for portable electronics are accelerating retailer procurement of certified solar charging SKUs across Germany, France, and Italy.
- Outdoor recreation equipment buyers:North American camping and overlanding segments are prioritizing off-grid power independence, creating sustained replacement cycles for higher-wattage portable units.
- PERC cell efficiency gains:Passivated emitter and rear contact architectures now deliver conversion rates above 22% in consumer formats, shrinking panel surface area requirements for equivalent output.
Market Restraints
- Polysilicon input cost volatility:Silicon metal price swings tied to energy-intensive smelting operations in Xinjiang and Yunnan provinces compress margin predictability for module assemblers.
- Lithium-ion cell supply concentration:Cathode active material production clusters in China's Hunan and Fujian provinces create single-source vulnerability for energy storage integration.
- REACH chemical compliance friction:ECHA's restricted substance lists for electronics require reformulation of encapsulants and solder materials, extending qualification timelines.
Strategic Opportunities
- India's outdoor tourism infrastructure:Ladakh and Himachal Pradesh trekking corridors lack grid penetration, creating first-mover positioning for ruggedized solar charging rental networks.
- Japan's disaster preparedness mandates:METI guidelines for household emergency kits specify renewable backup power, opening institutional procurement channels.
- Solid-state battery convergence:Sulfide electrolyte cell architectures promise energy density doubling, enabling foldable solar charger form factors currently impossible with liquid electrolyte cells.
Industry Challenges
- Photovoltaic engineering talent scarcity:Asia-Pacific universities produce insufficient cell process engineers, forcing manufacturers to poach from semiconductor fabs or fund internal training academies.
- Multi-jurisdiction certification timelines:Simultaneous GB standard testing for China, CE marking for Europe, and FCC Part 15 for the United States extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Charger Market |
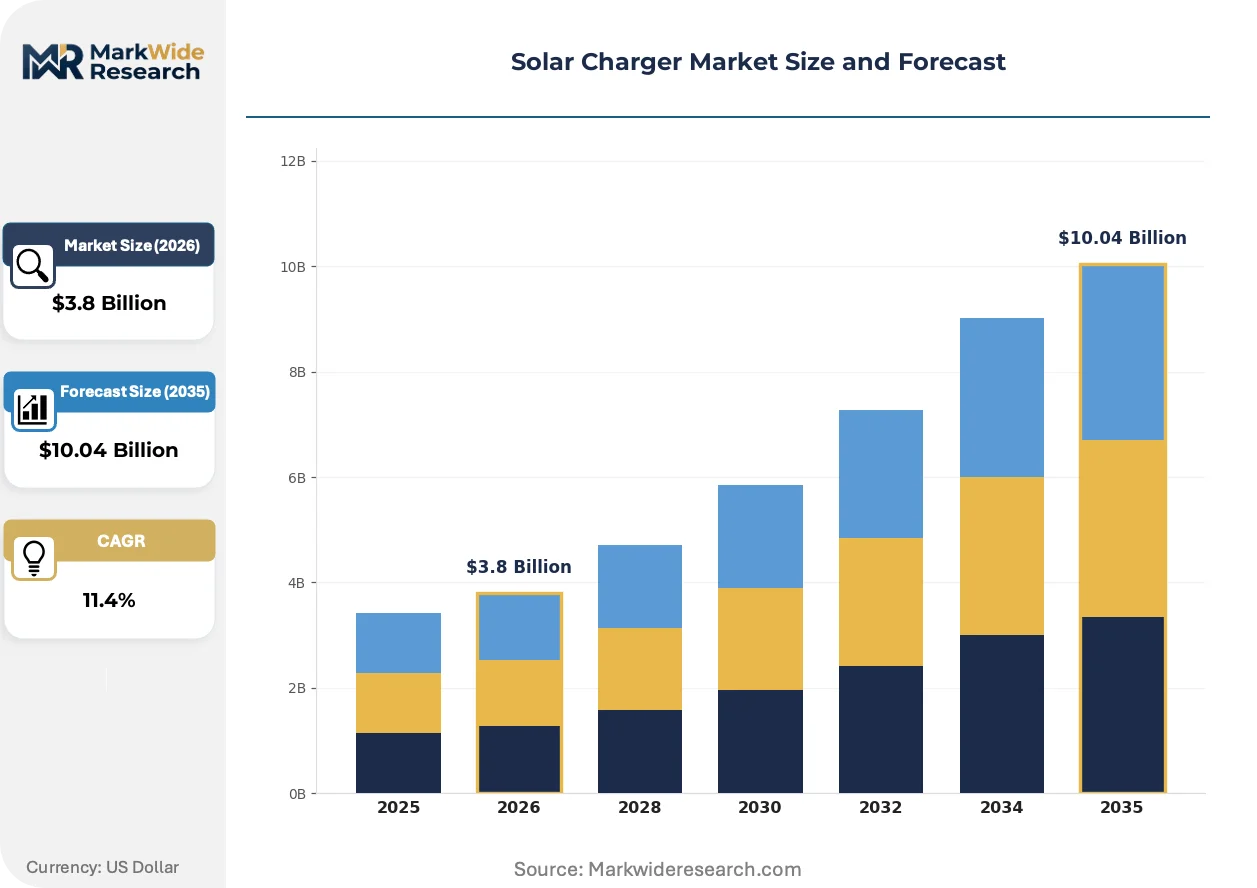
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Integrated, Hybrid Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Consumer Electronics, Outdoor Activities, Emergency Power, Automotive End User: Households, Businesses, Recreational Users, Military |
| Companies Covered | LONGi Green Energy Technology Co. Ltd., Canadian Solar Inc., JinkoSolar Holding Co. Ltd., First Solar, Inc., Chint New Energy Technology Co. Ltd., JA Solar Technology Co. Ltd., Tongwei Solar, Hanwha Q CELLS, Trina Solar Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Charger Market Strategic Shifts
Product architecture is diverging between ultra-lightweight formats for gram-conscious backpackers and integrated power stations for vehicle-based recreation, with cell chemistry and panel lamination choices splitting accordingly.
Monocrystalline silicon wafer technology is fragmenting the premium portable segment from thin-film alternatives. Hikers and alpine climbers now specify 156mm half-cut cell configurations for their superior low-light performance. This specification shift is compressing thin-film's addressable market to emergency-only use cases where absolute weight threshold overrides efficiency concerns.
REACH chemical compliance frameworks in Europe are forcing material declarations through entire supply chains. ECHA's SCIP database requirements for waste traceability now extend to solar charger adhesives and junction box potting compounds. German outdoor retailers are responding by demanding full substance inventories before shelf placement, filtering out suppliers lacking documentation systems.
Direct-to-consumer channel expansion is displacing traditional outdoor equipment distributors. Amazon and specialized renewable energy webstores now capture majority volume for sub-100W portable units. This channel rotation is most pronounced in the United States, where REI and Bass Pro Shops are consolidating shelf space toward integrated power station formats and away from standalone panels.
Solar Charger Market Segmentation
Solar charger segmentation reveals how regulatory frameworks and end-use requirements fragment product architectures across certification regimes. Understanding these divisions clarifies why manufacturers maintain parallel SKUs rather than unified global platforms.
Product Type:
EU Green Deal efficiency labeling and the EPA's e-waste directives create divergent form-factor requirements across jurisdictions, forcing producers to segment by mobility class.
- Portable:Folding panel arrays with integrated lithium-ion storage, typically 10W to 100W output, dominate North American recreational procurement through REI and Bass Pro Shops. Backpackers in Germany's outdoor retail corridor now specify sub-500g configurations with PERC cell architectures.
- Stationary:Fixed-installation units with external battery expansion ports serve off-grid cabins and remote monitoring stations. Demand concentrates in Japan's disaster preparedness procurement under METI guidelines for household emergency renewable backup.
- Integrated:Solar-battery combinations molded into single enclosures, common in consumer electronics accessories. REACH compliance for encapsulant materials restricts supplier pools for European-bound production.
- Hybrid:Dual-input systems accepting grid and photovoltaic charging simultaneously. India's Ladakh trekking infrastructure operators deploy these for rental network reliability.
Portable handles the majority of throughput; Hybrid is the fastest mover on share.
Technology:
Cost tiers separate cell architectures, with polysilicon purification energy intensity driving margin structures at each performance level.
- Monocrystalline:Single-crystal silicon wafers deliver 20-24% conversion efficiency in consumer formats. Hikers and alpine climbers specify 156mm half-cut configurations for superior low-light performance, compressing thin-film's addressable market.
- Polycrystalline:Multi-crystal ingot production yields lower efficiency at reduced wafer cost, occupying standard-tier pricing in emerging market household segments. China's GB standards for photovoltaic consumer products shape export-ready specifications.
- Thin-Film:Cadmium-telluride or CIGS deposition on flexible substrates enables sub-200g panel weights. Emergency-only positioning now dominates as absolute weight threshold overrides efficiency concerns.
- Bifacial:Dual-sided light capture architectures, rarely deployed in portable formats due to rear-surface protection requirements. Niche applications include military ground deployments where albedo reflection is controllable.
Monocrystalline commands volume leadership; Bifacial is expanding most quickly from minimal base.
Application:
Customer maturity splits the market between replacement-cycle compression in established segments and infrastructure buildout in emerging demand pools.
- Consumer Electronics:Smartphone and tablet charging accessories, the original market foundation. Compressed margin structures now force manufacturers toward direct-to-consumer channels to preserve returns.
- Outdoor Activities:Camping, overlanding, and trekking power independence. North American buyers prioritize higher-wattage portable units with vehicle integration capability.
- Emergency Power:Grid-disruption backup for critical communications and medical devices. Japan's institutional procurement channels under METI guidelines specify renewable backup for household emergency kits.
- Automotive:Trickle-charging and auxiliary power for electric and internal-combustion vehicles. Integration challenges with 12V and 48V electrical architectures limit adoption.
Consumer Electronics maintains installed base dominance; Outdoor Activities is climbing the fastest on revenue contribution.
End User:
Procurement authority and volume scale differentiate customer types, with institutional buyers imposing certification burdens that consumer channels avoid.
- Households:Individual purchasers through retail and e-commerce. Amazon and specialized renewable energy webstores capture majority volume for sub-100W portable units.
- Businesses:Corporate fleet and facility managers deploying remote power for field operations. ECHA's SCIP database requirements for waste traceability extend to solar charger adhesives and junction box potting compounds.
- Recreational Users:Dedicated outdoor enthusiasts with equipment replacement cycles. German outdoor retailers demand full substance inventories before shelf placement, filtering undocumented suppliers.
- Military:Defense procurement with ruggedization and electromagnetic compatibility specifications. FCC Part 15 and CE marking timelines extend product launch windows for dual-use suppliers.
Households generate the largest transaction count; Military is gaining share fastest on contract value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers command 15-20% price premiums over equivalent North American channels for certified portable units, while US direct-to-consumer platforms compress margins through volume aggregation. This asymmetry reflects divergent compliance cost absorption and channel structure rather than underlying technology differentiation.
United States
Overlanding and vehicle-based recreation drive procurement of higher-wattage portable systems through Amazon and specialized renewable energy webstores. EPA e-waste directives elevate material traceability requirements for domestic distribution, filtering undocumented suppliers from institutional channels. California's outdoor equipment retail clusters anchor West Coast demand concentration.
Germany
Backpackers in the outdoor retail corridor now specify sub-500g PERC configurations, compressing thin-film positioning to emergency-only segments. EU Green Deal binding targets accelerate retailer procurement of certified SKUs across Germany, France, and Italy. Bavaria's trekking infrastructure operators deploy hybrid rental networks for grid-penetration gaps.
China
Domestic demand concentrates in household segments served by polycrystalline standard-tier pricing, while export-oriented producers redesign architectures for multi-jurisdiction compliance. SAMR-administered GB standards for photovoltaic consumer products shape export-ready specifications. Xinjiang and Yunnan provinces host energy-intensive polysilicon smelting operations with volatile input cost profiles.
Japan
METI guidelines for household emergency kits specify renewable backup power, opening institutional procurement channels for stationary formats with external battery expansion. Disaster preparedness mandates create replacement-cycle visibility distinct from recreational demand patterns. Kanto region distributors integrate solar charging into municipal resilience planning.
India
Ladakh and Himachal Pradesh trekking corridors lack grid penetration, creating first-mover positioning for ruggedized solar charging rental networks. BIS certification requirements for imported electronics extend product qualification timelines for multi-brand distributors. Maharashtra's outdoor tourism infrastructure operators pilot hybrid systems for commercial reliability.
Solar Charger Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with polysilicon-to-module integrators controlling upstream cost curves while cell-efficiency specialists capture premium portable segments. The vendor base spans vertically integrated energy conglomerates, pure-play module assemblers, and thin-film technology specialists. Three archetypes dominate: upstream-integrated cost leaders, efficiency-focused premium-positioned players, and geographic-diversified volume operators. Capacity expansion in PERC architectures and strategic partnerships for solid-state battery convergence represent the dominant competitive moves.
Among Asia-Pacific-based producers, LONGi Green Energy Technology Co. Ltd., JA Solar Technology Co. Ltd., and Hanwha Q CELLS occupy distinct positions within the competitive structure. LONGi exemplifies the upstream-integrated archetype through polysilicon-to-module control. JA Solar represents scale-driven volume positioning across utility and consumer applications. Hanwha Q CELLS anchors the efficiency-specialist tier with PERC architectures translating into portable form-factor advantages.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co. Ltd. |
| Canadian Solar Inc. |
| JinkoSolar Holding Co. Ltd. |
| First Solar, Inc. |
| Chint New Energy Technology Co. Ltd. |
| JA Solar Technology Co. Ltd. |
| Tongwei Solar |
| Hanwha Q CELLS |
| Trina Solar Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day component qualification timelines for REACH-compliant encapsulants concentrate pricing power with certified suppliers in Germany's outdoor retail corridor, while compressing margin buffers for module assemblers sourcing from polysilicon-smelting regions with volatile energy input costs.
Pricing Analysis
Configured-to-order pricing for PERC-cell portable units with full ECHA SCIP documentation commands 15-20% premiums over standard-tier polycrystalline SKUs lacking substance traceability. Three-tier pricing structure across premium, standard, and economy levels separates certified European-bound production from emerging-market household segments and emergency-only thin-film positioning. Cost compression in standard-tier modules intensifies because Xinjiang polysilicon smelters face energy cost volatility. Recreational users in North America exhibit lowest price sensitivity, prioritizing wattage density and vehicle integration over per-watt cost.
Supply Chain Analysis
China and South Korea anchor photovoltaic cell manufacturing, with Xinjiang and Yunnan provinces hosting energy-intensive polysilicon purification and Hunan and Fujian clusters controlling cathode active material production. The solar charger supply chain draws from monocrystalline silicon wafers, lithium-ion electrolyte formulations, and REACH-compliant encapsulant adhesives. Single-source vulnerability concentrates in China's polysilicon-to-cell pipeline, exposing assemblers to input cost swings from regional energy pricing. Distribution runs through Amazon and specialized renewable energy webstores for sub-100W portable units, while German outdoor retailers filter undocumented suppliers from shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated outdoor equipment retail chains in Germany and direct-to-consumer platforms in the United States, fragmenting pricing leverage for module assemblers without certification infrastructure.
For Market Incumbents: Shield margin structures by deepening backward integration into polysilicon purification or securing captive PERC cell capacity against emerging thin-film specialists. Prioritize ECHA SCIP database readiness and full substance inventory systems to defend shelf placement in German outdoor retail corridors against competitors lacking REACH documentation infrastructure. For New Entrants and Emerging Players: Differentiate on solid-state battery convergence for foldable form factors currently impossible with liquid electrolyte architectures. Target India's Ladakh and Himachal Pradesh trekking infrastructure with ruggedized rental network partnerships, deploying hybrid systems for grid-penetration gaps where established players lack localized service presence. For Investors and Strategic Acquirers: Carve-out targets emerge from energy conglomerates with stranded portable solar charger divisions lacking direct-to-consumer channel expertise. Long-term viability hinges on certification infrastructure and solid-state battery partnerships rather than commodity module assembly. Watch for inflection signals in BIS certification timeline compression for Indian market entry.| Strategic Initiative | Industry Significance |
|---|---|
| PERC Cell Efficiency Investment | Higher conversion rates shrink panel surface area for equivalent output, enabling sub-500g portable configurations. |
| REACH Compliance Infrastructure | ECHA SCIP database readiness filters competitors from German outdoor retailer procurement channels. |
| Solid-State Battery Partnership | Sulfide electrolyte architectures promise energy density doubling for foldable form factors. |
| Direct-to-Consumer Channel Buildout | Amazon and specialized webstores displace traditional distributors for sub-100W portable units. |
| India Rental Network Pilot | Ladakh trekking corridors lack grid penetration, creating first-mover positioning for ruggedized deployment. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with photovoltaic process engineers, outdoor equipment procurement managers, and ECHA regulatory compliance officers, combined with secondary validation against SAMR GB standards filings, ECHA restricted substance lists, and METI disaster preparedness guidelines. Bottom-up triangulation across module assembler capacity disclosures and top-down reconciliation against retail channel shipment data anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand by product type, technology architecture, application use case, and end-user procurement authority. CAGRs derived from segment-level growth rate reconciliation against macro renewable energy penetration trajectories. Key inputs included polysilicon spot price volatility bands and lithium-ion cell supply concentration indices.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt polysilicon supply disruption would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and solid-state battery commercialization pacing. Recalibration cycles align with material shifts in ECHA substance restrictions and BIS certification pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Solar Simulator Market