
 Residential Solar Market | 2026-2036
Residential Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Solar Market Insights
Bifacial panel technology paired with module-level power electronics is reshaping residential system architecture toward higher energy density per rooftop. Sunrun leverages its vertically integrated installation and financing platform to sustain recurring revenue streams across lease and loan products. Trinity Solar anchors its competitive position through direct-to-consumer sales channels that bypass third-party lead generation costs. ADT Solar differentiates by bundling solar with home security monitoring, creating stickier customer relationships and lower customer acquisition expenses.
Residential solar encompasses photovoltaic energy systems installed on single-family homes, townhouses, and small multi-unit dwellings, typically rated between three and twenty kilowatts DC and connected to the distribution grid or paired with lithium-ion battery storage. These systems convert sunlight into alternating current electricity through silicon-based cells, inverters, and balance-of-system components to offset household consumption, reduce utility bills, and provide backup power during grid outages. Photovoltaic panels and batteries command the dominant share of product value, though margin pools are shifting toward integrated storage as homeowners seek resilience against escalating utility rates and weather-related disruptions. Roof-mounted installations lead volume across suburban markets, while ground-mounted configurations occupy niche positions on larger rural properties where land constraints are minimal.
The US residential solar sector operates under overlapping federal and state regulatory frameworks, with the Investment Tax Credit administered by the IRS, net metering policies set by state public utility commissions, and interconnection standards governed by IEEE 1547 and local grid codes. California's NEM 3.0 reforms have slashed export compensation rates, forcing installers to emphasize battery pairing and self-consumption optimization rather than pure grid-tied economics. Stakeholders must monitor how evolving state-level rate structures and building code mandates, such as California's Title 24 solar-ready requirements, reshape system sizing and storage attachment rates in their target markets.
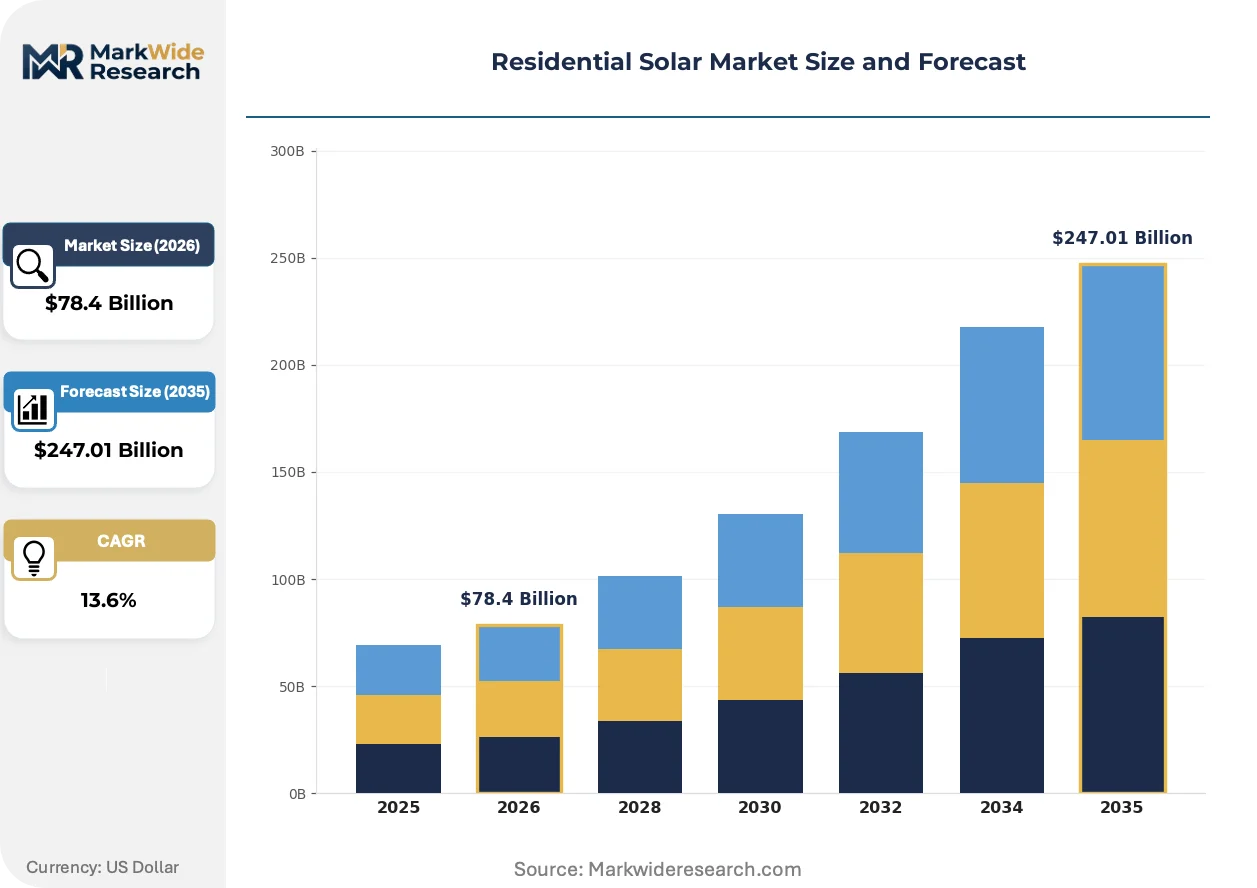
Market Dynamics
Net metering reforms in California and federal tax credit extensions through the IRA are forcing installers to restructure system economics around battery pairing and self-consumption optimization rather than pure export revenue.
Growth Catalysts
- Investment Tax Credit extension:The IRA's multi-year credit continuity gives installers predictable project economics and accelerates loan product uptake among credit-qualified homeowners.
- Silicon carbide inverters:Widespread adoption of SiC-based power electronics cuts conversion losses and enables higher string voltages that reduce balance-of-system copper costs.
- Sun Belt utility rate escalation:Double-digit annual increases in retail electricity rates across Arizona, Nevada, and Texas compress payback periods below six years for standard system configurations.
Market Restraints
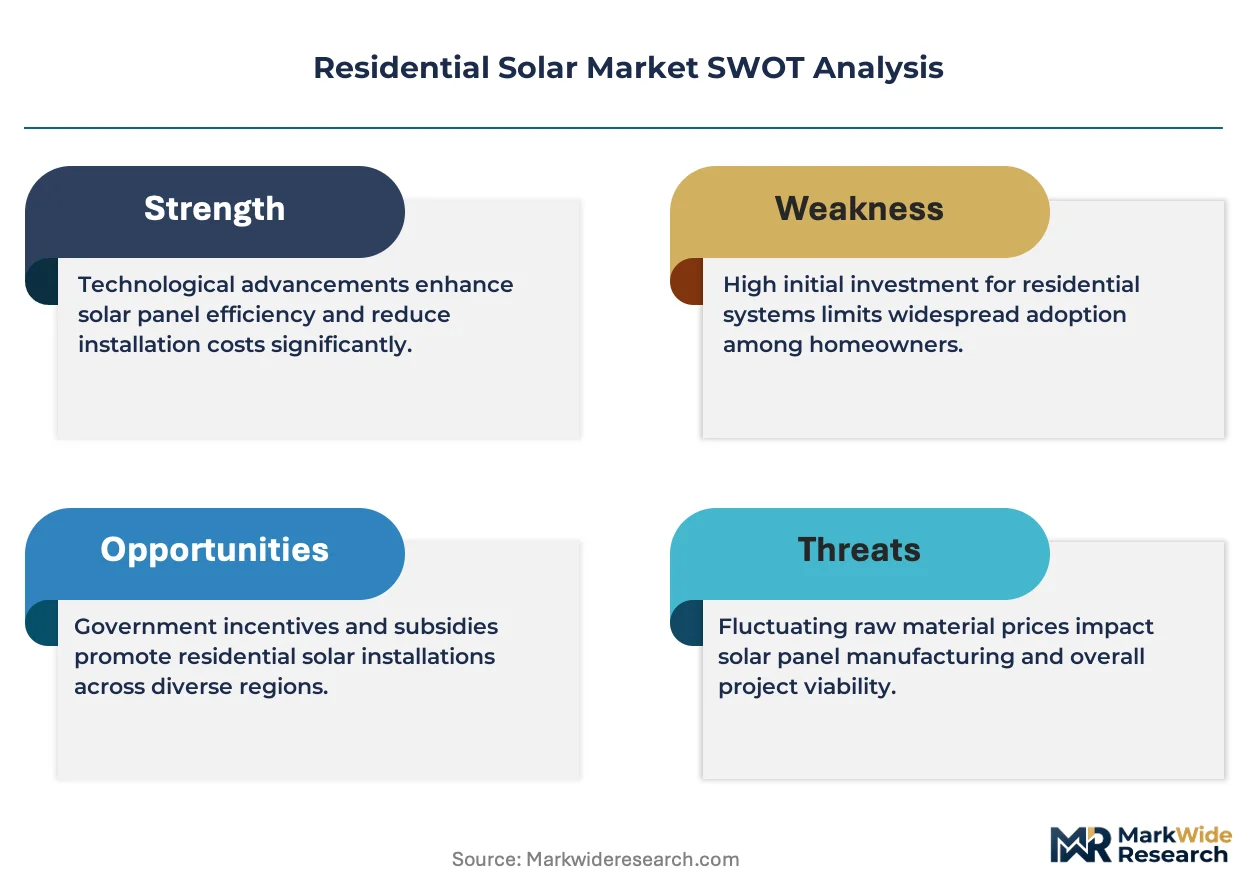
- Polysilicon supply concentration:Four Chinese producers control over seventy percent of metallurgical-grade silicon refining, exposing module costs to geopolitical trade friction and tariff uncertainty.
- Interconnection queue delays:Distribution utilities in high-penetration territories require twelve-to-eighteen-month impact studies before approving residential export capacity, freezing project commencements.
- Roof condition variability:Deferred maintenance on twenty-plus-year-old asphalt shingles forces twenty to thirty percent of site assessments toward reroofing pre-work that erodes project margins.
Strategic Opportunities
- Texas deregulated retail markets:Competitive REP structures and absence of net metering create fertile ground for virtual power plant aggregation and wholesale market participation models.
- California Title 24 mandates:New construction solar-ready requirements in the state's building code guarantee attached market volume through 2030 for production builders.
- DC-optimizer plus storage convergence:Module-level electronics paired with lithium-ion batteries enable granular load flexibility services that command premium pricing from grid operators.
Industry Challenges
- NEM 3.0 compensation complexity:California's time-varying export rates and avoided cost calculations require sophisticated consumption modeling that strains installer sales engineering capacity.
- Permitting standardization gaps:AHJ-specific electrical and fire code interpretations create non-recurring engineering costs that scale poorly across multi-state installation footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Solar Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Mounting Systems, Batteries Installation Type: Roof-mounted, Ground-mounted, Hybrid, Off-grid End User: Homeowners, Builders, Property Managers, Real Estate Developers Financing Model: Cash Purchase, Loan Financing, Power Purchase Agreement, Lease |
| Companies Covered | Trinity Solar, ADT Solar, Sunrun, Project Solar, Freedom Solar Power, Blue Raven Solar, Palmetto, Sunlux, Momentum Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Solar Market Trends and Innovations
Bifacial panel architecture paired with module-level power electronics is compressing levelized cost trajectories and enabling higher energy density per available rooftop square footage. Three convergent developments merit attention.
Passivated contact cell technology is collapsing the efficiency gap between premium and standard module tiers. Manufacturers shipping tunnel oxide passivated contact architectures now extract twenty-three-plus percent conversion efficiency from mass-produced cells. Premium residential buyers in California and Arizona are specifying these modules for constrained roof planes, compressing the pricing power of legacy aluminum-back surface field designs.
California's NEM 3.0 framework is restructuring installer compensation models away from export maximization. The CPUC-mandated avoided cost calculator slashes midday export values and forces battery attachment rates above eighty percent for viable project economics. Installers are responding with consumption-optimization software and time-of-use rate arbitrage controls.
Direct-to-consumer digital origination is displacing third-party lead generation in customer acquisition. Trinity Solar and regional installers are building proprietary traffic engines that bypass the fifteen to twenty percent referral fees charged by national lead aggregators. This channel shift is most visible in Florida and Texas, where door-to-door sales restrictions and high mobility rates favor online qualification and remote site assessment workflows.
Residential Solar Market Segmentation
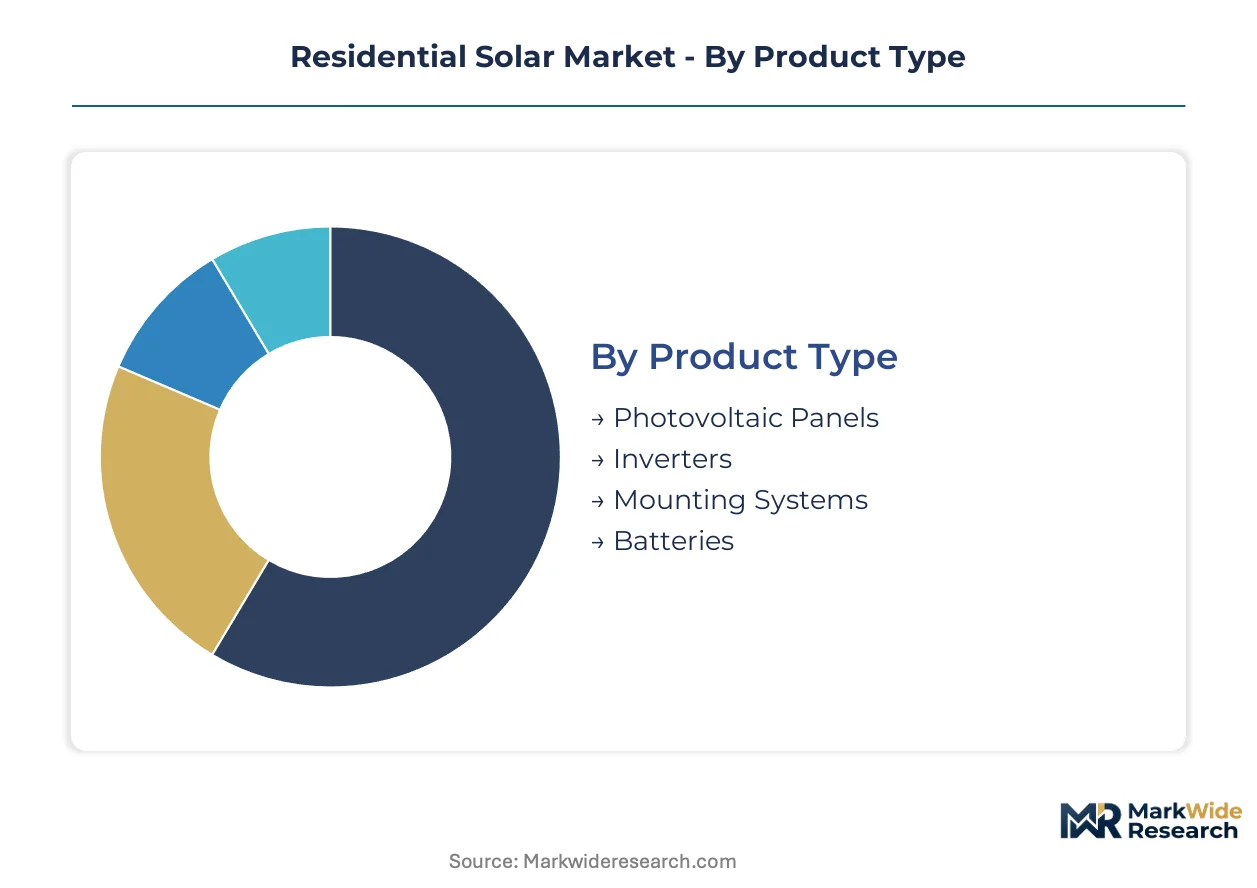
Residential solar purchasing decisions fragment across hardware specifications, site constraints, capital preferences, and regulatory exposure. Installers must align inventory and sales engineering capacity to the segments where attachment rates and margin profiles diverge most sharply.
Product Type:
Photovoltaic panels and inverters turn over on 5-7 year technology cycles as cell efficiency improves, while batteries and racking systems refresh on 10-15 year durability timelines.
- Photovoltaic Panels:Tunnel oxide passivated contact cells now extract conversion efficiency above twenty-three percent from mass-produced silicon wafers. Sun Belt homeowners in Arizona and Nevada specify these premium modules for constrained south-facing roof planes where every square foot counts against utility rate escalation.
- Inverters:Silicon carbide power electronics cut conversion losses while enabling higher string voltages that reduce copper conductor sizing in balance-of-system hardware. String inverters dominate cost-sensitive Texas markets, though California's NEM 3.0 export compensation structure is accelerating microinverter attachment for granular consumption optimization.
- Mounting Systems:Rail-less clamp architectures reduce installation labor hours on asphalt shingle roofs prevalent in suburban Florida developments.
- Batteries:Lithium iron phosphate chemistries paired with DC-coupled inverters capture arbitrage value under California's time-varying export rates.
Photovoltaic panels dominate installed base. Batteries are where expansion concentrates as NEM 3.0 reforms force self-consumption economics.
Installation Type:
Site configuration determines project development velocity, with roof-mounted systems closing in 30-60 days versus ground-mounted timelines stretching 6-12 months for grading and trenching permits.
- Roof-mounted:Asphalt shingle attachments using flashed L-feet remain the volume standard across single-family subdivisions in California, Arizona, and Texas. Deferred roof maintenance forces twenty to thirty percent of site assessments toward reroofing pre-work that erodes installer margins.
- Ground-mounted:Driven pile or concrete pier foundations suit rural properties in Texas Hill Country and Nevada where land constraints are minimal and utility interconnection queues are shorter.
- Hybrid:Grid-tied systems with battery backup capability command premium pricing in hurricane-exposed Florida markets where resilience drives purchasing decisions.
- Off-grid:Standalone configurations with oversized battery banks occupy niche positions in remote Nevada and Arizona territories beyond utility distribution infrastructure.
Roof-mounted systems anchor volume throughput. Hybrid configurations are climbing the fastest as battery attachment rates respond to net metering compensation compression.
End User:
Customer acquisition costs vary 3-5x across buyer types, with production builders converting at 15-20% referral rates versus single homeowners requiring 3-6 month sales cycles.
- Homeowners:Individual purchasers respond to utility bill offset calculations and federal Investment Tax Credit eligibility, with credit-qualified households gravitating toward loan products that preserve the credit benefit.
- Builders:Production home developers in California face Title 24 solar-ready mandates that guarantee attached market volume through 2030, standardizing system specifications across subdivisions.
- Property Managers:Multi-unit dwelling operators in Arizona and Nevada evaluate split-incentive structures where tenant electricity consumption decouples from capital investment recovery.
- Real Estate Developers:Master-planned community builders in Texas deregulated markets negotiate virtual power plant aggregation contracts with competitive retail electricity providers.
Homeowners anchor current revenue concentration. Builders represent the steepest expansion trajectory as California code mandates harden into construction standard practice.
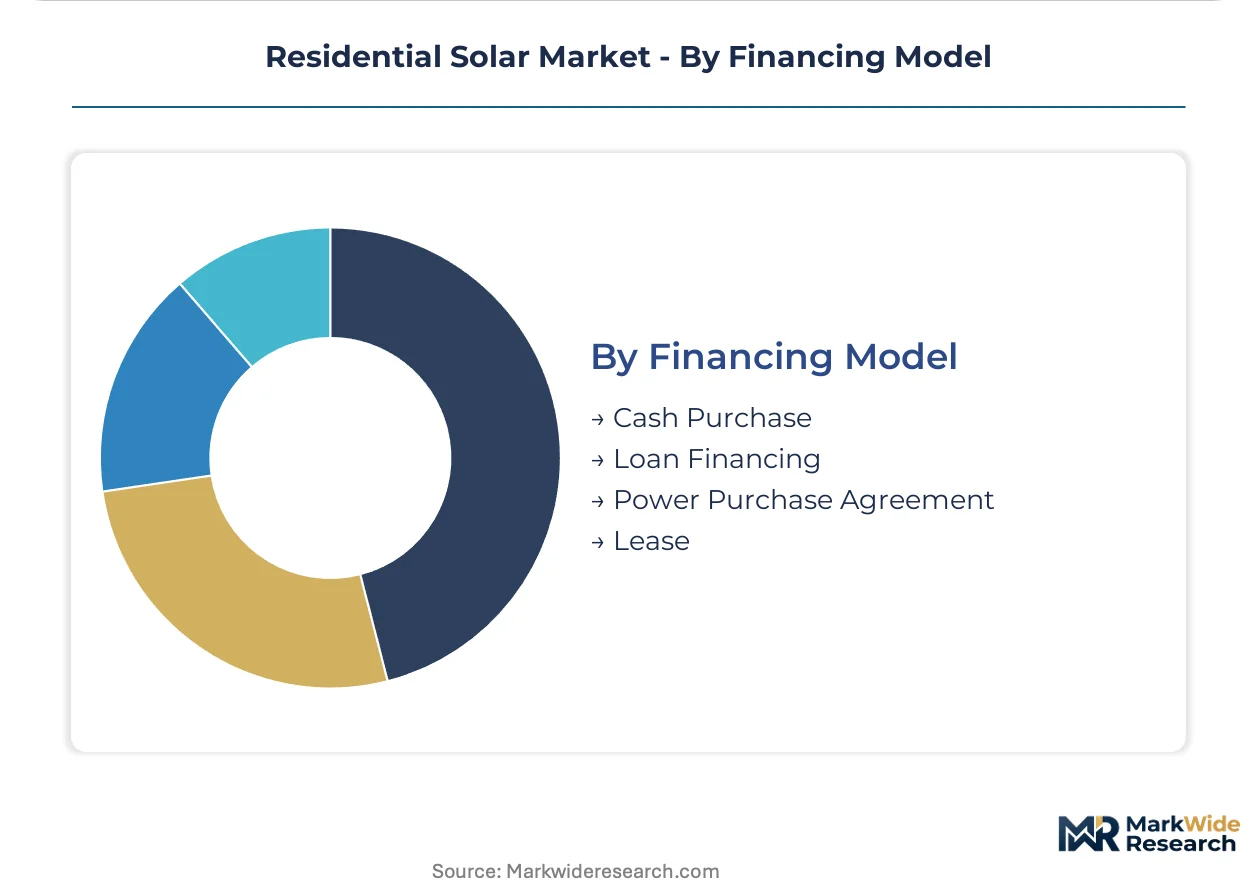
Financing Model:
Capital structure preferences segment by homeowner credit profile and tax appetite, with lease products declining as loan availability expands through credit union and fintech channels.
- Cash Purchase:Full upfront payment captures maximum lifetime savings and Investment Tax Credit value for high-net-worth households in California and Arizona with available liquidity and tax liability to absorb the credit.
- Loan Financing:Secured and unsecured debt products through credit unions and specialty lenders now dominate Texas and Florida markets as interest rate environments compress payback period advantages.
- Power Purchase Agreement:Third-party ownership with per-kilowatt-hour pricing retains appeal for credit-constrained homeowners in Nevada seeking immediate bill reduction without capital outlay.
- Lease:Fixed monthly payment structures with escalator clauses are contracting in volume as NEM 3.0 export compensation reforms erode the underlying utility rate hedge value.
Loan financing dominates new origination flow. Cash purchases are gaining share fastest among affluent California households optimizing around battery pairing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese module manufacturers supply photovoltaic hardware to installer networks across the United States, Germany, and Australia, while domestic project developers in each market compete on customer acquisition and financing origination.
United States
California's NEM 3.0 reforms and Texas deregulated retail markets drive divergent system economics. The IRA's Investment Tax Credit extension through the IRS stabilizes project finance. Installer concentration clusters in Phoenix, Dallas-Fort Worth, and Miami metro areas where utility rate escalation compresses payback periods.
Germany
Rooftop deployment accelerates under the EU Green Deal's building renovation targets and EEG feed-in tariff adjustments. BAFA federal funding programs subsidize battery storage pairing. Industrial activity concentrates in Bavaria and North Rhine-Westphalia where Mittelstand engineering firms integrate solar with building energy management.
Australia
High retail electricity tariffs and abundant solar irradiance drive world-leading per-capita installation rates. State-level feed-in tariffs and battery rebate schemes vary across Queensland, New South Wales, and Victoria. Sydney and Melbourne suburbs exhibit dense rooftop penetration with emerging virtual power plant aggregation by competitive retailers.
Japan
Feed-in tariff reductions shift focus toward self-consumption and post-FIT system replacements. METI promotes building-integrated photovoltaics and residential storage under the GX Green Transformation program. Osaka and Nagoya manufacturing clusters supply power electronics to domestic and Southeast Asian markets.
India
Rooftop solar targets under the National Solar Mission face implementation gaps between policy ambition and DISCOM financial health. MNRE subsidies and state-level net metering regulations create fragmented market conditions. Gujarat and Maharashtra lead deployment through industrial and commercial anchor loads with residential adoption trailing.
Residential Solar Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented installer landscape where regional scale and customer acquisition efficiency determine viability. The vendor base spans vertically integrated national platforms, state-level direct-to-consumer operators, and technology-agnostic local contractors. Two strategic archetypes dominate: financing-integrated installers capturing recurring revenue through lease and loan products, and sales-efficiency specialists minimizing customer acquisition costs through proprietary lead generation. Competitive moves center on battery attachment rate expansion and multi-state permitting standardization to compress project development timelines.
Among financing-integrated platforms, Sunrun and Trinity Solar exemplify divergent channel strategies. Sunrun anchors the lease-and-loan origination model with in-house capital markets access, while Trinity Solar occupies the direct-to-consumer efficiency position bypassing third-party lead aggregators. ADT Solar represents the cross-category bundling archetype, attaching solar to established home security customer relationships to reduce acquisition expenses. These three patterns illustrate how installer economics restructure around California's NEM 3.0 compensation compression and federal tax credit continuity.
| Leading Market Players |
|---|
| Trinity Solar |
| ADT Solar |
| Sunrun |
| Project Solar |
| Freedom Solar Power |
| Blue Raven Solar |
| Palmetto |
| Sunlux |
| Momentum Solar |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit polysilicon cost volatility directly into module landed costs, amplifying price spreads between premium passivated-contact cells and legacy aluminum-back surface field designs while forcing installers to absorb or pass through logistics surcharges across customer segments with divergent willingness-to-pay.
Pricing Analysis
Passivated-contact cell premiums now command fifteen-to-twenty percent spreads over standard PERC architectures, with tunnel oxide passivated contact efficiency gains justifying rooftop-constrained deployments in California and Arizona. Three-tier pricing structure across premium, standard, and economy levels stratifies by cell efficiency grade and module temperature coefficient ratings. Cost compression in economy-tier supply is intensifying because Chinese polysilicon spot markets face tariff exposure and domestic content bonus eligibility requirements. Credit-constrained homeowners in Nevada and Texas exhibit highest price sensitivity, while affluent California households optimizing battery pairing economics show least elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates residential solar supply chain risk calculus, with Section 301 duties and anti-circumvention inquiries disrupting module availability timelines. Polysilicon refining concentrates in China, Malaysia, and Vietnam, while wafer slicing and cell fabrication cluster in Chinese provinces with integrated metallurgical-grade silicon capacity. Raw material dependencies rest on high-purity quartz crucibles, silver paste for front-side metallization, and aluminum frames from extrusion facilities. Single-source vulnerability persists in silicon carbide substrate supply for next-generation inverter power electronics. Distribution runs through national installer procurement consortia and regional distributor networks serving local electrical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer fragmentation across fifty-state regulatory patchworks creates niche entry points as NEM 3.0 compensation complexity forces specialization in consumption-optimization software and battery integration services.
For Market Incumbents: Entrench market position through captive financing origination capabilities and multi-state permitting standardization investments. Sunrun and Trinity Solar demonstrate how in-house capital markets access and proprietary lead generation engines defend against lead-aggregator margin extraction. Battery attachment rate expansion represents the priority capability lever as export compensation reforms erode pure grid-tied economics.
For New Entrants and Emerging Players: Texas Hill Country ground-mount installations and Florida hurricane-resilience hybrid configurations offer underpenetrated white-space with shorter interconnection queues and premium pricing tolerance. Direct-to-consumer digital origination bypassing door-to-door sales restrictions provides the most penetrable go-to-market angle, with remote site assessment workflows reducing customer acquisition costs below third-party lead generation benchmarks.
For Investors and Strategic Acquirers: Regional installers with Title 24 new construction relationships and production builder channel control represent attractive acquisition targets as California code mandates harden into construction standard practice. Long-term viability hinges on battery storage integration capabilities and virtual power plant aggregation software rather than pure photovoltaic installation scale. The signal to watch is attachment rate divergence between NEM 3.0-exposed California operators and Texas deregulated market participants.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Storage Integration | DC-coupled lithium iron phosphate systems capture California time-of-use arbitrage value under NEM 3.0. |
| Direct-to-Consumer Digital Origination | Proprietary traffic engines bypass national lead aggregator fifteen-to-twenty percent referral fees in Florida and Texas. |
| Multi-State Permitting Standardization | AHJ-specific code interpretation harmonization compresses project development timelines across installation footprints. |
| Virtual Power Plant Aggregation | Wholesale market participation contracts with competitive retail electricity providers unlock Texas deregulated revenue streams. |
| Silicon Carbide Inverter Adoption | SiC power electronics reduce conversion losses and enable higher string voltages that cut balance-of-system copper costs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with residential solar installers, project finance officers at tax equity providers, utility interconnection planners, and distributed energy resource software vendors; combined with secondary validation against EIA generation data, FERC interconnection filings, CPUC regulatory dockets, and IRA implementation guidance from the IRS. Bottom-up triangulation across state-level installation permitting databases and top-down reconciliation with national capacity forecasts anchored volume and value estimates.
Forecast inputs span module efficiency tiers, battery attachment rates by net metering regime, financing product mix shifts, and regional utility rate escalation trajectories across the analysis window. Segmentation dimensions modeled include hardware product type, installation configuration, end-user category, and capital structure preference. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for policy discontinuity risks.
Practitioners should monitor interconnection queue length trends, tariff policy announcements, and net metering reform proposals across state public utility commissions for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Saudi Arabia Solar Energy Market