
 Solar Generator Market | 2026-2036
Solar Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Generator Market Intelligence
Subscription-based energy monitoring and remote diagnostics is broadening what solar generator manufacturers sell beyond hardware. EcoFlow US leverages app-integrated power management to differentiate its ecosystem. Jackery Inc. anchors its brand strength in compact lithium-ion portable units for camping and vanlife users. Generac Power Systems, Inc. dominates backup system channels through established dealer networks and whole-home integration expertise.
A solar generator converts photovoltaic energy into stored electrical power through integrated battery banks, charge controllers, and inverter systems, typically outputting pure sine wave AC at 110-240V for sensitive electronics. These units serve primary functions in off-grid power delivery, emergency backup, and mobile energy access where grid connectivity proves unreliable or unavailable. Portable generators occupy the highest volume tier among product types, while off-grid solutions command premium positioning due to larger capacity configurations and specialized installation requirements. Backup systems attract sustained demand from residential users in hurricane-prone and wildfire-exposed regions, whereas power stations gain traction among contractors requiring jobsite electricity without fuel logistics.
US EPA emissions guidelines for portable power equipment and California Air Resources Board standards for off-road engines indirectly channel demand toward zero-emission solar alternatives. IEEE 1547 interconnection standards and UL 2743 safety certifications shape product design requirements for grid-tied and standalone systems respectively. Stakeholders must monitor evolving state-level net metering policies and battery recycling mandates to anticipate margin pressures and compliance costs.
Market Dynamics
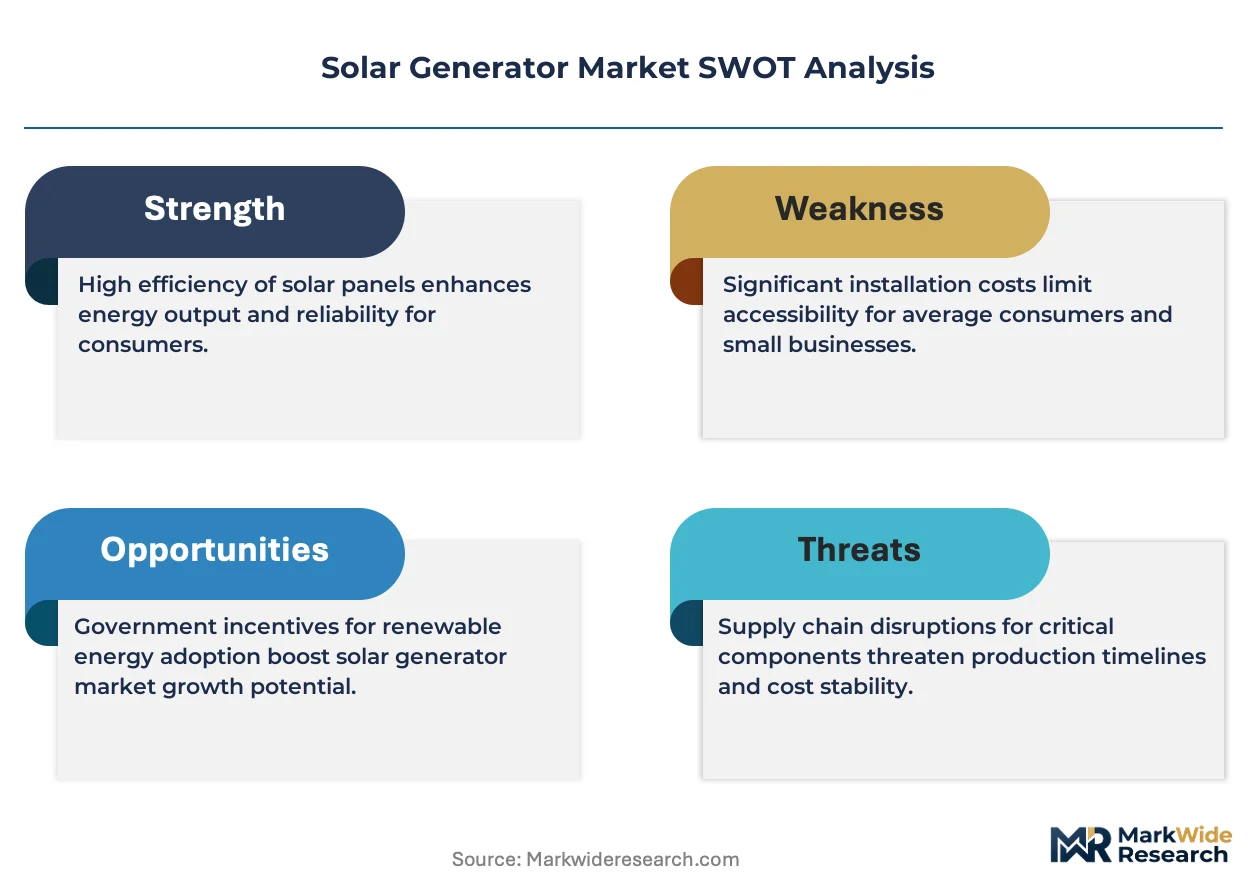
Lithium iron phosphate battery chemistry advances are compressing unit weights while extending cycle life, fundamentally altering portable solar generator economics and opening new mobility-driven use cases previously blocked by mass constraints.
Growth Catalysts
- Clean Energy Tax Credits:The US Inflation Reduction Act's residential energy storage incentives reduce net acquisition costs for homeowners in hurricane-prone states, accelerating backup system deployment.
- Outdoor Recreation Demand:Vanlife and overlanding communities in the western United States are driving portable power station volume through dispersed camping permit expansions on Bureau of Land Management territory.
- LFP Chemistry Maturation:Improved lithium iron phosphate cell manufacturing yields are lowering battery pack costs while eliminating thermal runaway risks that previously constrained indoor storage applications.
Market Restraints
- Raw Material Concentration:Lithium carbonate and refined cobalt supply chains concentrate in Chile and the Democratic Republic of Congo, exposing manufacturers to geopolitical disruption and price volatility.
- Interconnection Standards:IEEE 1547 compliance requirements for grid-tied solar generators create certification bottlenecks that delay product launches by 8-14 months in regulated US utility territories.
- Competing Backup Technologies:Natural gas standby generators retain cost advantages for whole-home applications above 10kW, limiting solar penetration in affluent suburban markets with existing gas infrastructure.
Strategic Opportunities
- Contractor Jobsite Electrification:California's Air Resources Board off-road engine regulations are banning gasoline generators on state-funded construction projects, creating zero-emission mandate pull-through.
- Subscription Diagnostics:Cellular-enabled power management platforms enable recurring revenue attachment to hardware sales, with remote firmware updates extending product relevance across multi-year ownership cycles.
- Modular Capacity Scaling:Stackable battery expansion architectures allow entry-level buyers to incrementally grow storage capacity, reducing upfront capital barriers for price-sensitive residential segments.
Industry Challenges
- UL 2743 Certification Backlogs:Third-party safety testing laboratories face 16-24 week queues for portable power station validation, compressing product launch windows and inventory planning horizons.
- Power Electronics Talent Scarcity:Design engineers with hybrid inverter and battery management system expertise command premium compensation in competing electric vehicle and grid storage sectors, constraining R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Generator Market |
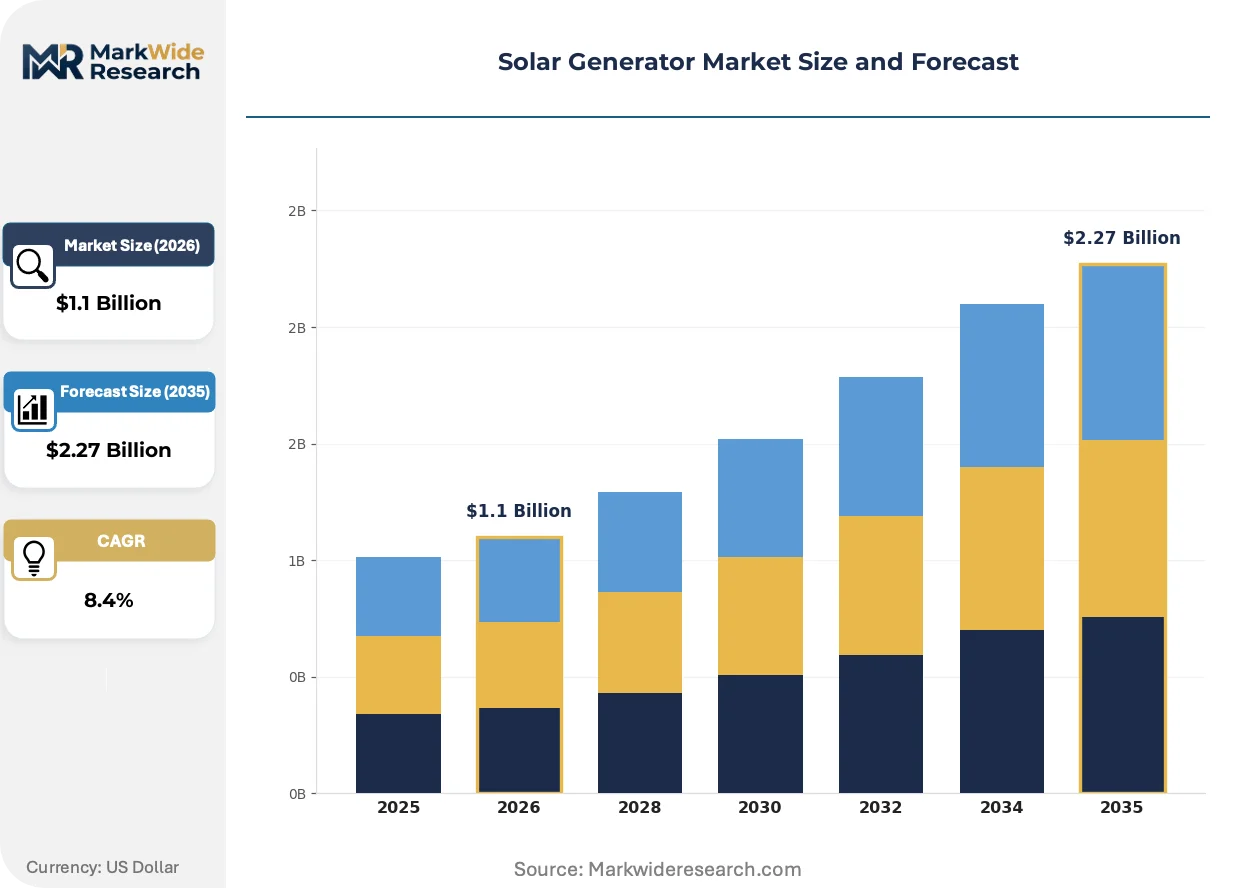
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $2.27 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Backup Systems, Power Stations, Off-Grid Solutions End User: Residential Users, Outdoor Enthusiasts, Contractors, Emergency Services Technology: Photovoltaic, Hybrid Systems, Maintenance-Free, Renewable Sources Capacity: 1-5 kW, 5-10 kW, 10-20 kW, Above 20 kW |
| Companies Covered | EcoFlow US, Westinghouse Electric Corporation, Renogy, Goal Zero, GROWATT, Jackery Inc., oukitel, Bluetti, Generac Power Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Generator Market Strategic Shifts & Innovations
Software-defined power management is displacing hardware-centric product architectures across the solar generator value chain, with connectivity and intelligence becoming primary differentiation vectors rather than raw capacity specifications.
Bidirectional charging circuitry is integrating vehicle-to-load capability as a standard feature in mid-tier portable power stations, enabling electric vehicle owners to extract emergency power from their automotive battery packs. RV and vanlife buyers in the Pacific Northwest are adopting these units fastest, drawn by overnight climate control without engine idling. This convergence is integrating automotive and stationary storage supply chains, compressing development timelines through shared component sourcing.
The US EPA's evolving emissions guidelines for portable power equipment are tightening certification windows for gasoline generator manufacturers, indirectly channeling commercial and residential demand toward zero-emission solar alternatives. Construction contractors facing California Air Resources Board enforcement actions are accelerating fleet replacement timelines. Backup system buyers in Florida and Texas are responding by prioritizing solar units with UL 2743 safety validation for indoor deployment flexibility.
Direct-to-consumer channel expansion is fragmenting traditional dealer-dependent distribution models, with manufacturer-owned digital storefronts capturing growing share of portable power station transactions. Camping specialty retailers are losing attachment rate leverage as buyers research specifications through online comparison tools before purchase. This disintermediation concentrates most visibly in the western United States, where dispersed outdoor recreation demographics align with e-commerce logistics infrastructure.
Solar Generator Market Segmentation
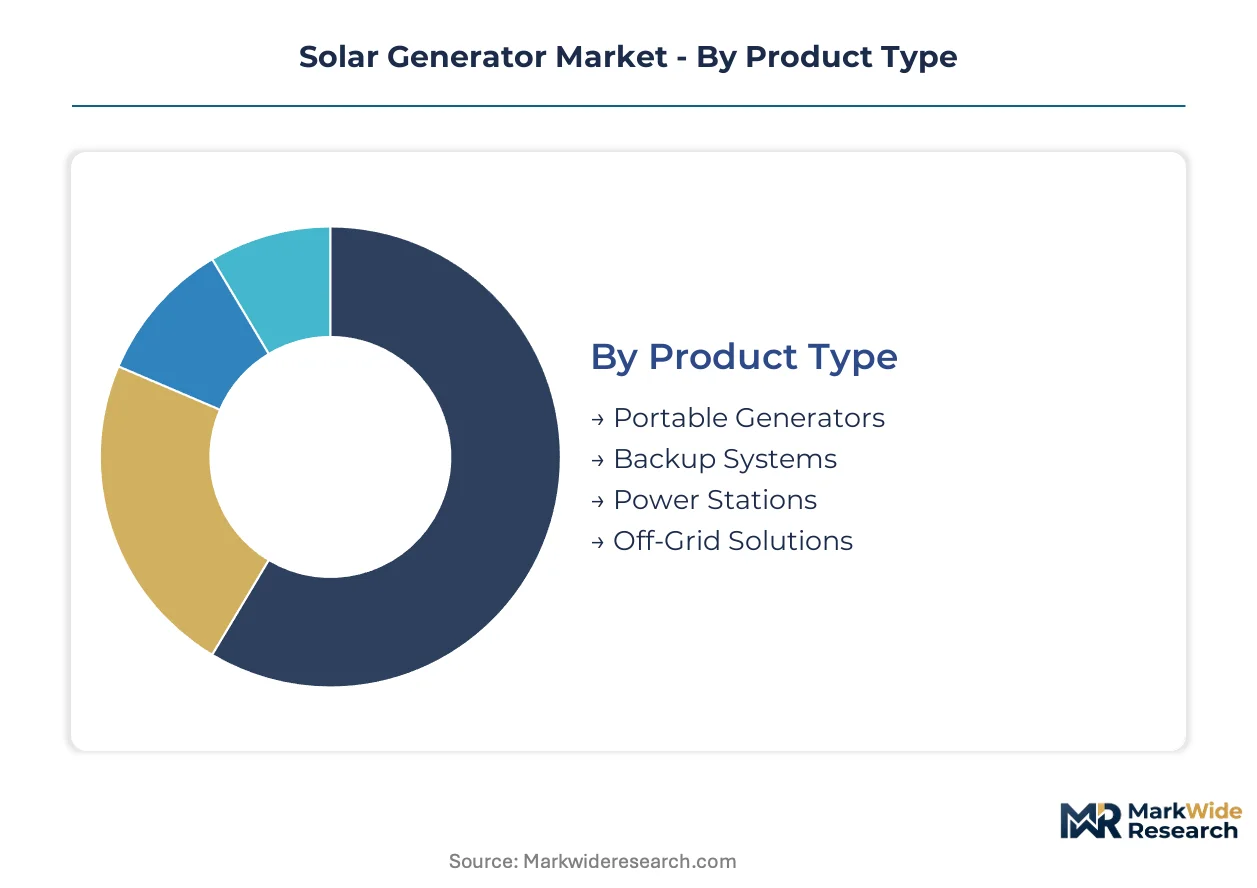
Solar generator manufacturers engineer product portfolios around distinct usage cycles and replacement triggers. Upgrade pathways differ sharply between mobile outdoor units and fixed residential installations, shaping R&D allocation and channel strategy across the value chain.
Product Type:
Replacement cycles stretch from 3-5 years for portable units to 10-15 years for hardwired backup systems, creating divergent revenue recognition patterns.
- Portable Generators:Compact lithium iron phosphate units under 50 pounds dominate dispersed camping and vanlife applications. Western United States Bureau of Land Management permit expansions are accelerating refresh rates among outdoor enthusiasts upgrading from heavier lead-acid predecessors.
- Backup Systems:Whole-home installations with automatic transfer switches serve hurricane-prone Florida and Texas markets where grid reliability concerns trigger replacement of aging gasoline standby units. UL 1741-SA certification requirements extend upgrade timelines but lock in vendor relationships.
- Power Stations:Contractor-grade units with 30A RV outlets and multiple AC ports address jobsite electrification mandates.
- Off-Grid Solutions:Integrated solar-battery-inverter packages for remote cabins and rural homesteads require specialized installation expertise.
Portable Generators sits at the top of the volume ranking, with Power Stations climbing the fastest.
End User:
Customer archetypes segment by mobility requirements and decision-making authority, from individual consumers to institutional procurement officers.
- Residential Users:Homeowners in wildfire-exposed California counties and storm-vulnerable Gulf Coast states prioritize indoor-safe lithium chemistry over legacy gasoline alternatives. Federal IRA storage tax credits reduce effective upgrade costs for systems paired with rooftop solar.
- Outdoor Enthusiasts:Overlanding and dispersed camping participants in the Pacific Northwest demand rapid-charging capability through vehicle alternator integration. Weight constraints below 35 pounds drive frequent product turnover as battery density improves.
- Contractors:Construction firms face California Air Resources Board enforcement timelines for gasoline generator phaseout on state-funded projects.
- Emergency Services:Municipal and federal agencies specify MIL-STD-810G durability standards for disaster response deployments.
Residential Users commands the largest installed base, though Outdoor Enthusiasts is gaining share fastest among first-time buyers.
Technology:
Technical architectures determine maintenance burdens and lifecycle costs, with chemistry and integration choices locking users into upgrade paths.
- Photovoltaic:Monocrystalline silicon panel integration with maximum power point tracking charge controllers delivers 20-23% conversion efficiency. Rooftop and ground-mount configurations in sunbelt states favor this straightforward architecture for predictable degradation curves.
- Hybrid Systems:Combined solar, grid, and generator input capability with intelligent source switching serves markets with intermittent renewable resource availability. Northeastern United States adopters value grid fallback during extended winter cloud cover.
- Maintenance-Free:Sealed lithium iron phosphate architectures eliminate electrolyte monitoring and terminal cleaning requirements.
- Renewable Sources:Wind turbine and micro-hydro input compatibility expands off-grid viability in resource-diverse locations.
Photovoltaic holds the dominant technology share, while Hybrid Systems exhibits the steepest expansion trajectory among new installations.
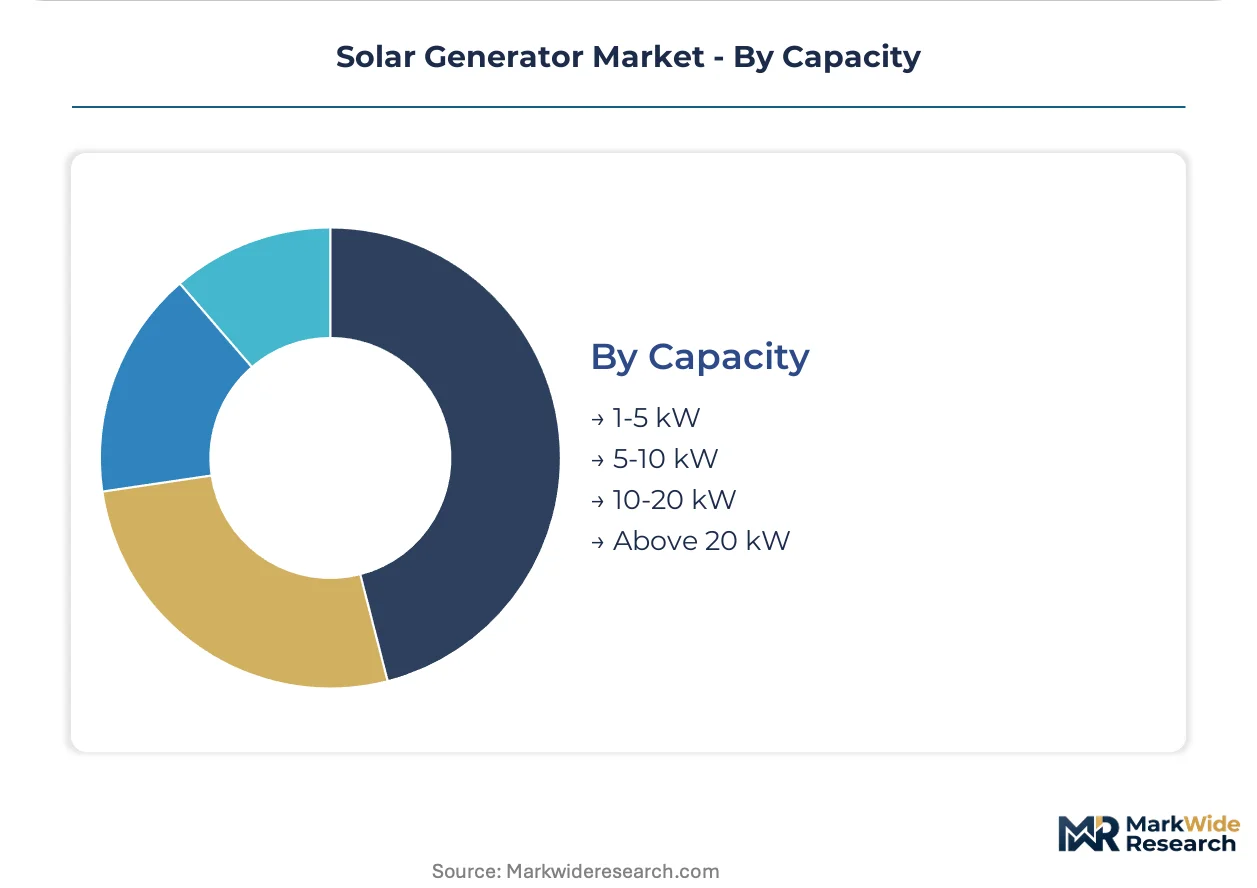
Capacity:
Power output tiers align with load profiles and infrastructure investment levels, from device charging to whole-property electrification.
- 1-5 kW:Entry-level power stations and small portable units serve device charging, lighting, and small appliance loads. Weekend campers and apartment dwellers in urban California markets favor this tier for balcony solar compatibility and storage constraints.
- 5-10 kW:Mid-range systems support essential circuit backup and RV air conditioning. Suburban homeowners in Texas replacing partial-home gasoline generators cluster here, balancing cost against refrigerator and medical equipment continuity needs.
- 10-20 kW:Whole-home coverage with load management capabilities addresses affluent coastal markets.
- Above 20 kW:Commercial-scale installations and luxury estate applications require three-phase output and extended runtime architectures.
1-5 kW leads unit shipments, with 5-10 kW expanding most quickly as residential backup demand broadens beyond early adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's wildfire-driven backup power mandates contrast sharply with Germany's grid-stability focus, revealing how local energy security anxieties shape divergent procurement patterns across developed markets.
United States
Hurricane-prone Gulf Coast states and wildfire-exposed California counties drive residential backup system deployments. The Inflation Reduction Act's residential energy storage tax credits reduce net acquisition costs for homeowners pairing systems with rooftop solar. Austin and Houston metro areas concentrate contractor-grade power station demand as construction electrification mandates tighten.
Germany
Grid instability fears following natural gas supply disruptions accelerate residential solar-plus-storage adoption. The country's national energy regulator prioritizes distributed generation integration under revised grid codes. Bavaria and Baden-Württemberg host the densest installer networks for whole-home backup configurations.
China
Export manufacturing clusters supply global portable power station demand while domestic camping culture expands. The Ministry of Industry and Information Technology enforces lithium battery safety standards under GB/T 36972. Shenzhen and Dongguan concentrate contract manufacturing capacity for lithium iron phosphate pack assembly.
Australia
Remote mining operations and off-grid homesteads sustain demand for high-capacity integrated systems. The country's national renewable energy regulator administers off-grid reliability standards through the Australian Energy Market Operator. Queensland and Western Australia concentrate solar resource development with co-located storage installations.
Japan
Disaster preparedness culture and earthquake risk sustain residential backup system demand. The Ministry of Economy, Trade and Industry subsidizes residential storage deployment under post-Fukushima resilience programs. The Kanto region around Tokyo concentrates distribution infrastructure for premium portable units.
Solar Generator Market Key Industry Players
Top-tier vendors anchor premium backup and whole-home integration segments, while mid-tier specialists dominate portable power stations and outdoor recreation channels. The market exhibits moderate concentration with clear tiering between integrated energy conglomerates and focused lithium storage specialists. Three strategic archetypes prevail: automotive-heritage power electronics firms, pure-play portable storage innovators, and established generator manufacturers pivoting to zero-emission portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure lithium cell supply and certification expertise.
Among US-based energy equipment specialists, Generac Power Systems, Inc. and Westinghouse Electric Corporation exemplify the industrial-heritage archetype migrating toward solar-electrified backup portfolios. EcoFlow US and Jackery Inc. occupy positions within the portable-native tier, representing the app-integrated, direct-to-consumer challenger model that has compressed traditional distribution margins. These four firms collectively illustrate the competitive tension between established channel relationships and digitally native customer acquisition.
| Leading Market Players |
|---|
| EcoFlow US |
| Westinghouse Electric Corporation |
| Renogy |
| Goal Zero |
| GROWATT |
| Jackery Inc. |
| oukitel |
| Bluetti |
| Generac Power Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Power electronics engineering talent concentration in Shenzhen and Dongguan compresses labor-cost differentials between premium UL-certified and economy-tier units, widening pricing spreads as manufacturers pass through certification investment burdens.
Pricing Analysis
Capacity additions in China's lithium iron phosphate cell manufacturing are reshaping price floors for entry-level portable power stations. Pricing stratifies across premium, standard, and economy tiers based on UL 2743 certification status and brand heritage. Cost compression in the standard tier intensifies because domestic Chinese manufacturers are exporting directly through Amazon storefronts. Contractor-grade buyers exhibit lowest price sensitivity due to California Air Resources Board compliance mandates, while weekend campers drive economy-tier volume.
Supply Chain Analysis
UL 2743 and IEEE 1547 certification queues at third-party testing laboratories gate component procurement timelines and extend working capital cycles for manufacturers. Cell production concentrates in China, South Korea, and Japan, while pack assembly and inverter manufacturing cluster in Guangdong province and Taiwan. Supply chains rest on lithium carbonate from Chile, refined cobalt from the Democratic Republic of Congo, and power semiconductors from Taiwan. Single-source vulnerability around IGBT and SiC MOSFET suppliers exposes manufacturers to automotive sector demand surges. Distribution runs through direct-to-consumer digital storefronts for portable units and established electrical contractor networks for backup systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as residential buyers shift from gasoline generator replacement toward premium lithium iron phosphate systems with integrated app control and cellular monitoring.
For Market Incumbents: Lock in lithium cell supply through multi-year offtake agreements with CATL or BYD before automotive sector demand tightens availability. Secure UL 1741-SA certification for whole-home backup systems to defend against emerging hybrid inverter specialists. Prioritize dealer network exclusivity in Florida and Texas hurricane corridors where replacement cycles accelerate. For New Entrants and Emerging Players: Direct-to-consumer TikTok and YouTube creator partnerships offer the lowest customer acquisition cost route for penetrating outdoor enthusiast segments. Target dispersed camping permit expansion zones in Bureau of Land Management territory where vanlife demographics concentrate. Pursue contractor jobsite electrification in California through rental fleet partnerships rather than retail channels. For Investors and Strategic Acquirers: Automotive Tier 1 power electronics suppliers are the most active acquirer in this space, seeking battery management system IP and bidirectional charging expertise. Five-to-ten-year viability hinges on software-defined power management platform adoption rates. Watch for California Air Resources Board enforcement action acceleration against gasoline generator fleets as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium Cell Supply Agreement | CATL and BYD capacity commitments anchor cost competitiveness against gasoline alternatives. |
| UL 2743 Certification Investment | Third-party laboratory relationships compress launch timelines for indoor-safe product lines. |
| Cellular-Enabled Diagnostics Platform | Recurring revenue attachment transforms hardware margins into subscription economics. |
| Dealer Network Expansion | Electrical contractor relationships in Gulf Coast states accelerate whole-home backup penetration. |
| Bidirectional Charging Integration | Vehicle-to-load capability captures electric vehicle owner crossover demand in Pacific Northwest markets. |
Research Approach
Bottom-up residential and contractor demand modeling reconciled against top-down lithium cell supply tracking forms the analytical core. Primary interviews with battery management system engineers, UL certification specialists, electrical contractor purchasing managers, and Bureau of Land Management permit administrators combined with secondary validation from EIA residential storage deployment data, FERC interconnection queue filings, California Air Resources Board enforcement records, and Amazon portable power station sales rankings. Triangulation across these sources calibrates volume estimates against actual procurement patterns.
Historical trendline analysis of lithium iron phosphate cost curves and portable power station shipment patterns established baseline growth assumptions. Segmentation modeling spans product type, end user archetype, capacity tier, and regional regulatory framework dimensions. CAGRs derive from fitted trend extrapolation adjusted for policy incentive phaseout schedules and raw material supply elasticity. Forecast inputs include Inflation Reduction Act residential storage tax credit utilization rates and California construction electrification mandate compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions about IEEE 1547 interconnection standard harmonization and lithium carbonate price stability. A model refresh is warranted upon material change in federal clean energy tax credit policy or UL certification laboratory capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Japan Thermal Power Plant Market
Power Generation
Shore Power Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Canada Power EPC Market
Power Generation
Iraq Power EPC Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Tunisia Power Market
Power Generation
Microturbine Market
Power Generation
Peaking Power Plant Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Micro CHP Market
Power Generation
Hydrogenerators Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Indonesia Power Market
Power Generation
Subsea Power Grid System Market
Power Generation
Retail Electricity Market