
 Hydrogenerators Market | 2026-2036
Hydrogenerators Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogenerators Market Foresight
Buyer concentration among state-owned utilities is pivoting toward fragmented procurement across independent power producers and rural electrification agencies. General Electric leverages its turbine-generator integration capabilities to sustain large-project dominance in North American retrofits. Voith Hydro anchors European supply through specialized Francis turbine expertise, while ANDRITZ competes on pumped-storage configurations across Alpine and Nordic terrain.
A hydrogenerator converts hydraulic energy into electrical power through electromagnetic induction, typically operating at speeds from 50 to 1,000 RPM depending on head and flow conditions, with stator diameters exceeding 20 meters in the largest bulb units. Pelton and Francis installations dominate mature hydroelectric power plants where decades of operational data validate efficiency curves, while pumped storage applications represent the fastest-expanding segment as grid operators seek multi-gigawatt balancing assets. Off-grid systems occupy a narrower margin pool but attract specialized entrants serving remote industrial loads.
The International Electrotechnical Commission sets efficiency and insulation standards that govern cross-border equipment certification, while China's Ministry of Ecology and Environment enforces river basin ecological red lines that constrain greenfield site eligibility. The EU Green Deal and F-Gas Regulation indirectly shape hydrogenerator demand by restricting competing pumped-storage cooling alternatives. Stakeholders must monitor evolving grid codes in major hydropower countries and assess whether modular installation designs can reduce project development timelines without sacrificing unit efficiency.
Market Dynamics
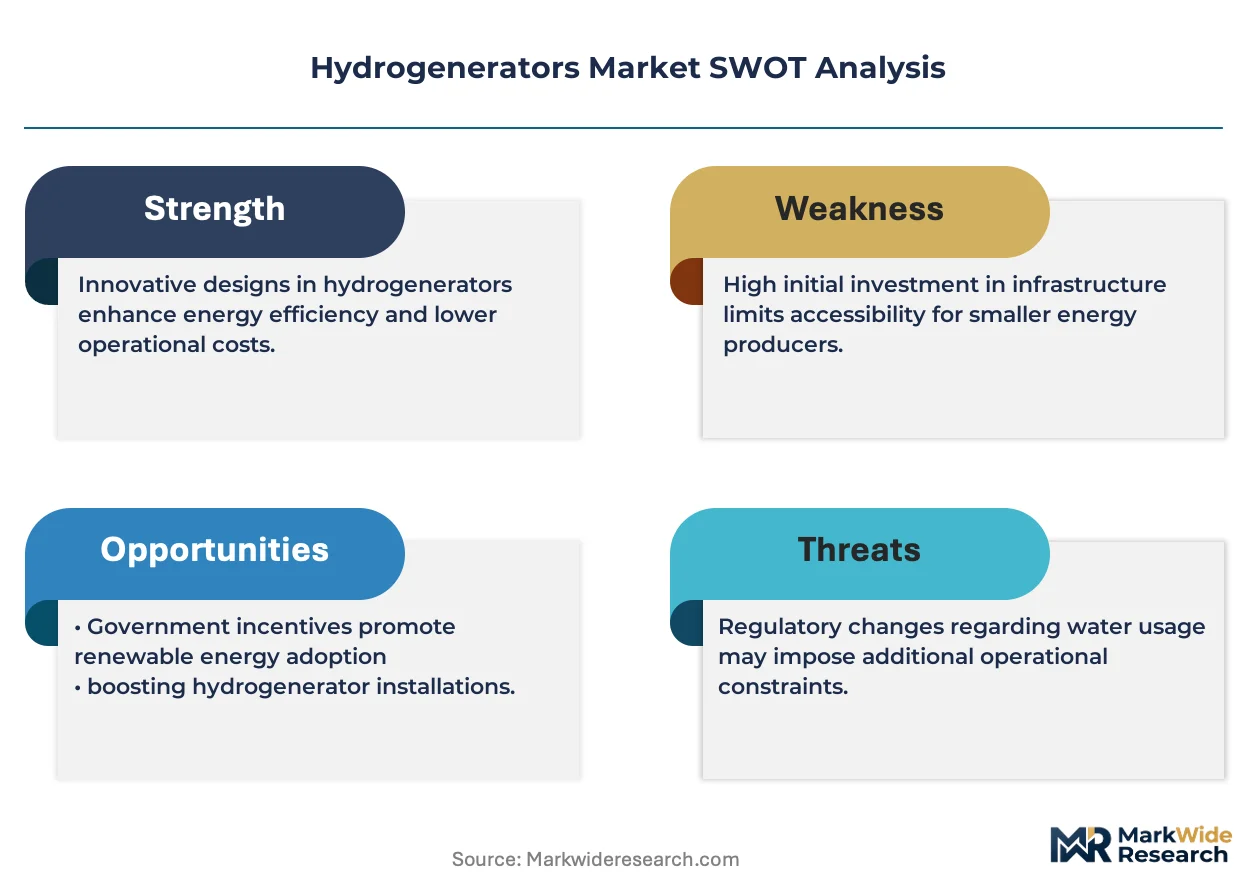
Grid balancing requirements are forcing utilities to prioritize pumped-storage hydrogenerators over conventional baseload units, reshaping procurement specifications toward rapid-response capability and modular installation architectures.
Growth Catalysts
- China's dual carbon goals:The Ministry of Ecology and Environment enforces river basin ecological red lines that redirect investment toward retrofit efficiency upgrades rather than greenfield dams.
- Development bank financing:Multilateral lenders are unlocking previously stalled run-of-river installations across African river basins where sovereign guarantees were previously unavailable.
- Pumped-storage applications:Grid operators seek multi-gigawatt balancing assets to manage intermittent renewable integration, driving demand for reversible turbine-generator configurations.
Market Restraints
- Copper and electrical steel volatility:Stator core laminations and windings depend on commodity inputs subject to supply chain disruptions and tariff exposure.
- Site eligibility constraints:China's river basin ecological red lines and similar watershed protections in Brazil and Canada eliminate previously viable greenfield locations.
- Long-lead manufacturing:Custom-forged turbine runners and stator frames require 18-36 month fabrication timelines that mismatch with accelerated renewable deployment schedules.
Strategic Opportunities
- Southeast Asian river basin developments:Laos, Vietnam, and Myanmar host untapped hydropower potential where transmission infrastructure investments now precede generation procurement.
- Modular bulb turbine packages:Standardized low-head units reduce project development timelines and enable distributed deployment across irrigation canal networks.
- EU Green Deal alignment:The F-Gas Regulation restricts competing pumped-storage cooling alternatives, creating regulatory preference for hydroelectric balancing assets.
Industry Challenges
- Turbine-generator alignment specialists:The field engineering workforce capable of precision shaft alignment and magnetic center verification is aging without sufficient apprenticeship pipeline replacement.
- IEC 60034 certification timelines:Efficiency and insulation standard testing for cross-border equipment creates 6-12 month approval bottlenecks that delay project commissioning.
- Legacy control system integration:Digital excitation and governor retrofits must interface with 1970s-era SCADA architectures without triggering protection system conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogenerators Market |
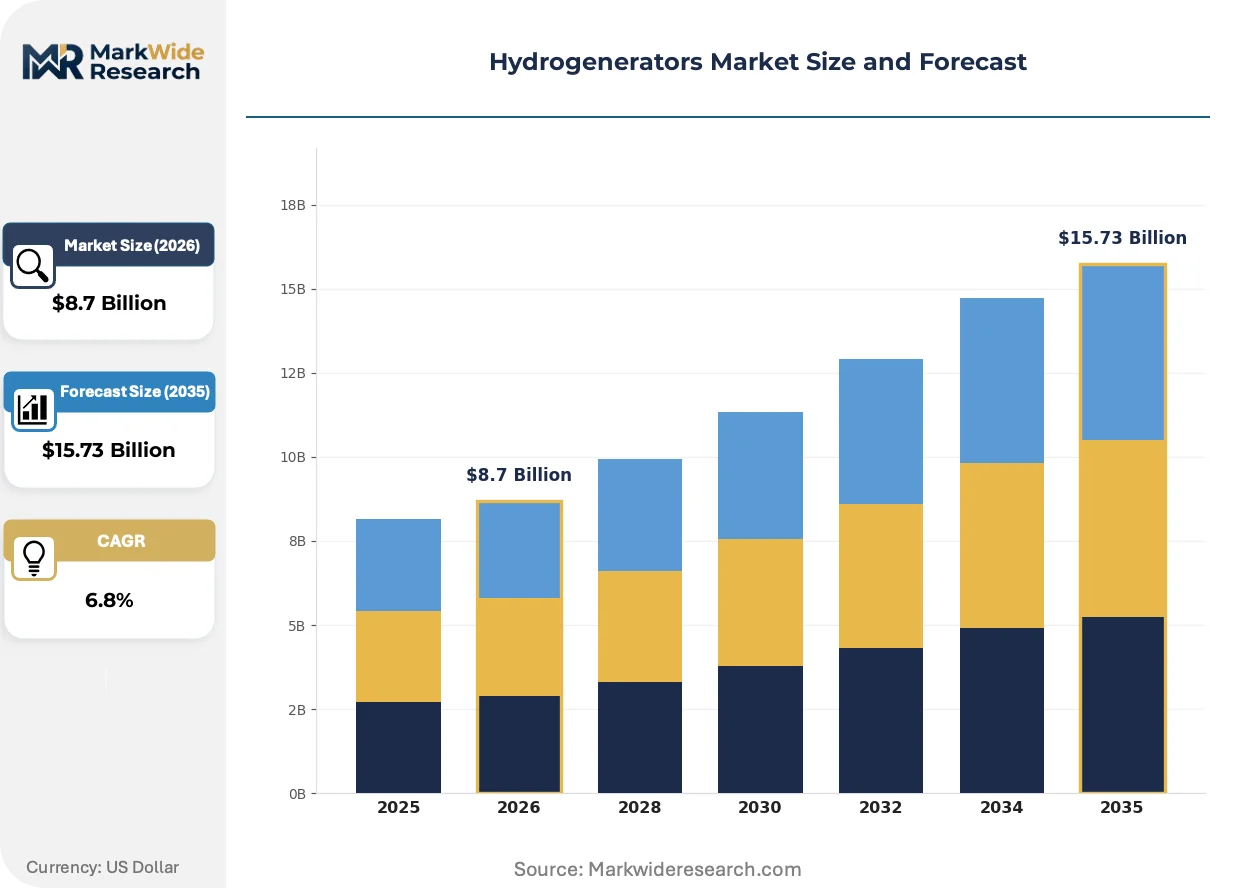
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
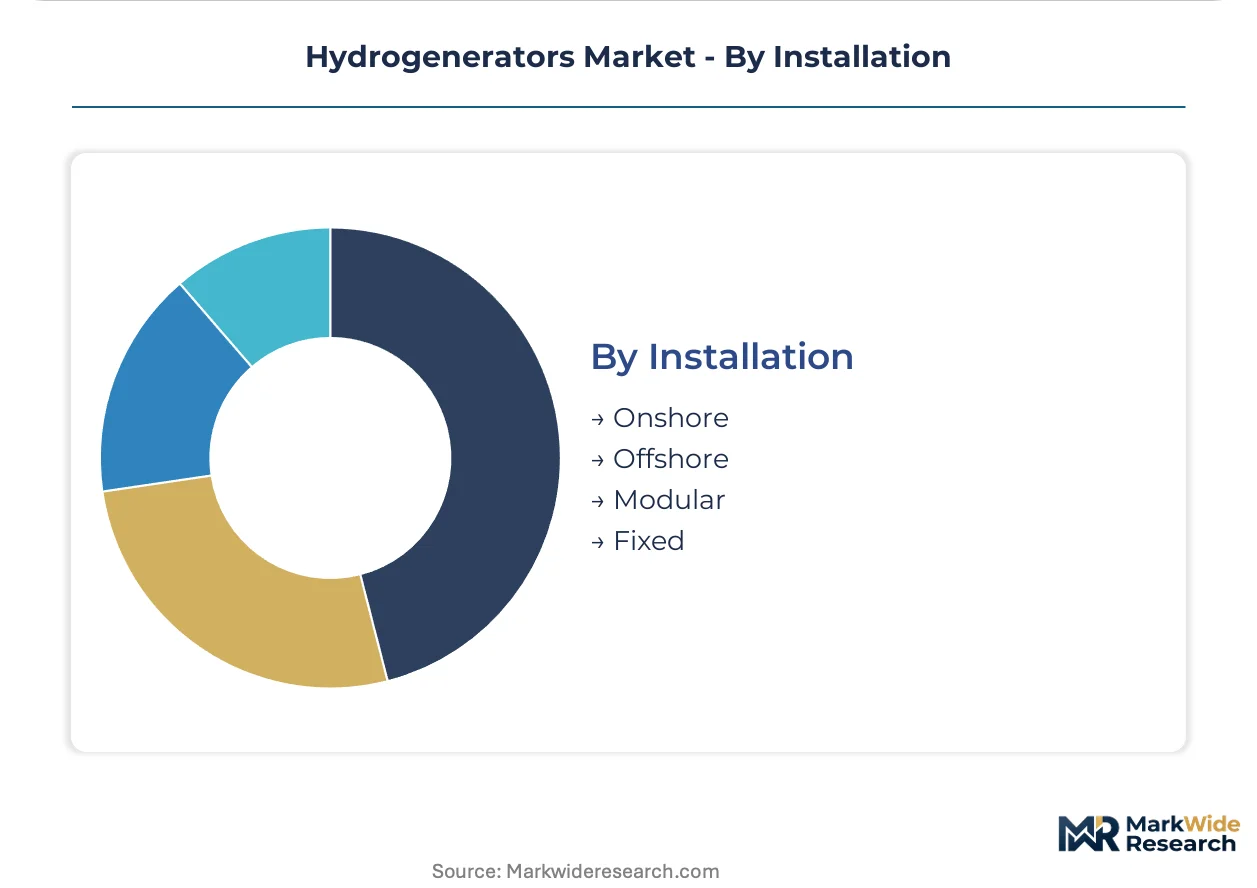
| Segmentation | Type: Pelton, Turbine, Kaplan, Francis Application: Hydroelectric Power Plants, Pumped Storage, Renewable Energy, Off-Grid Systems End User: Utilities, Industrial Plants, Government Agencies, Independent Power Producers Installation: Onshore, Offshore, Modular, Fixed |
| Companies Covered | General Electric, Voith Hydro, ANDRITZ, Toshiba Corporation, Siemens, Mitsubishi Heavy Industries, Cummins Inc., Ingeteam S.A., Nidec Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogenerators Market Shifts & Advancements
Permanent magnet generator technology is expanding into mid-scale hydro applications, while digital twin deployment compresses maintenance intervals and predictive analytics reshape aftermarket service economics.
Permanent magnet synchronous generators are expanding into Francis and Kaplan turbine installations below 50 MW, eliminating excitation systems and reducing auxiliary power consumption. European Alpine utilities and Japanese run-of-river operators are adopting these configurations for efficiency gains in variable-flow river conditions. The technology is expanding into refurbishment markets where stator retrofits can be executed without penstock dewatering, compressing outage durations from months to weeks.
The International Electrotechnical Commission updated efficiency testing protocols under IEC 60034-2-1, mandating stricter measurement uncertainty bounds for hydrogenerator certification. Equipment suppliers must now maintain accredited test facilities or witness testing arrangements, raising barriers for regional manufacturers serving cross-border projects. The regulation most affects Southeast Asian independent power producers sourcing European or Chinese equipment, who face extended documentation requirements and third-party verification costs.
Buyer engineering teams now specify integrated turbine-generator packages rather than split procurement, consolidating vendor accountability and reducing interface risk. State-owned utilities in emerging markets are fragmenting procurement across rural electrification agencies and agricultural cooperatives, displacing centralized tender processes. This pattern is most visible in African run-of-river developments where development bank disbursement conditions require community-benefit procurement structures.
Hydrogenerators Market Segmentation
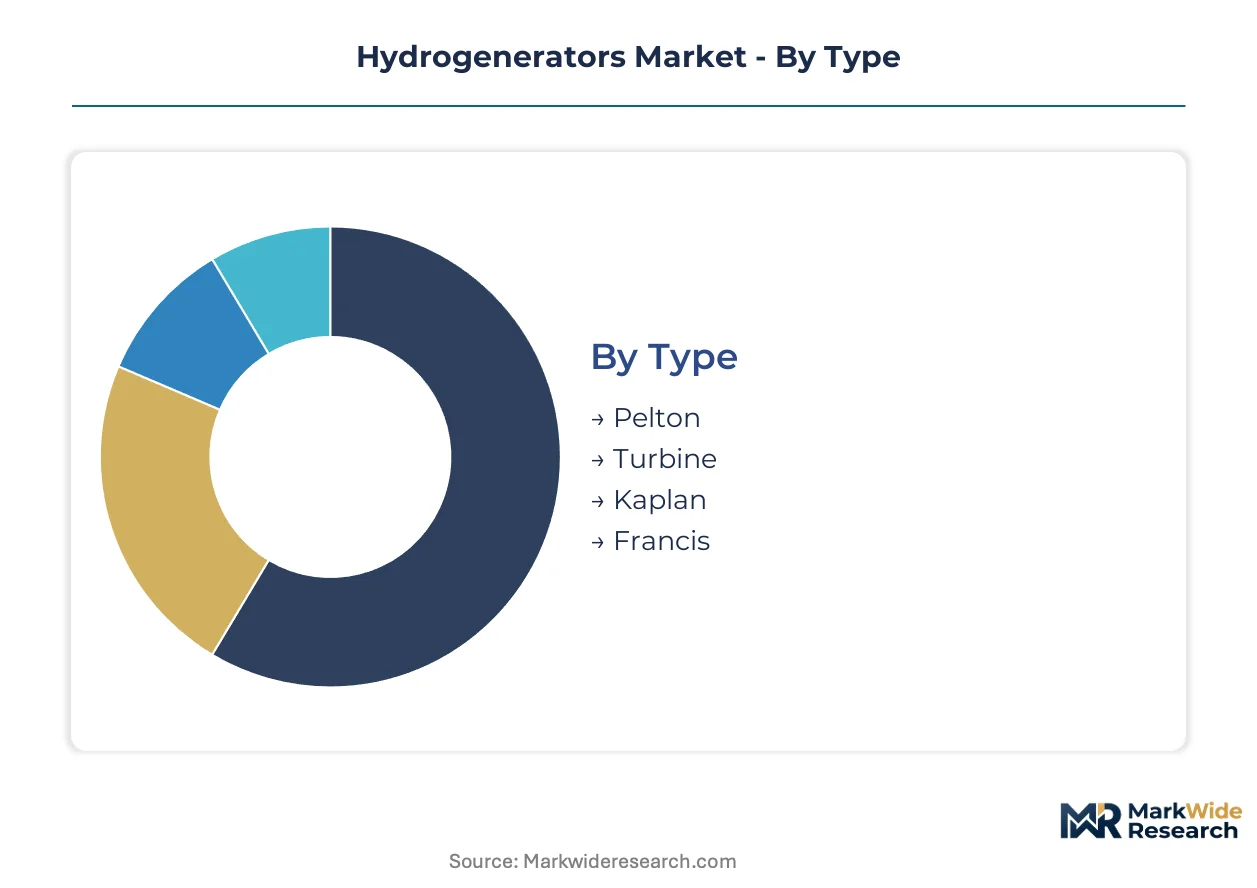
Hydrogenerator procurement diverges sharply across turbine architecture, grid integration mode, and ownership structure. Equipment specifications vary with head pressure, flow variability, and grid code requirements in each deployment context.
Type:
Customization intensity spans from standardized Kaplan units to bespoke Pelton configurations engineered for extreme head conditions.
- Francis:The dominant reaction turbine operates across medium head ranges from 20 to 700 meters, with adjustable wicket gates optimizing efficiency across variable flow regimes. China's retrofits and Southeast Asian greenfield projects concentrate procurement here, driven by the technology's proven performance in run-of-river configurations and pumped-storage reversibility.
- Kaplan:Axial-flow designs with adjustable blade pitch excel in low-head, high-flow river conditions below 30 meters. German and Austrian Alpine utilities specify these for run-of-river modernization, where blade angle automation maximizes annual energy yield across seasonal flow variation.
- Pelton:Impulse turbine architecture for high-head applications exceeding 300 meters.
- Turbine:Generic category encompassing emerging cross-flow and Archimedes screw configurations for micro-hydro applications.
Most installed capacity flows through Francis units. Expansion is steepest in Kaplan configurations for low-head distributed generation.
Application:
Revenue concentration shifts from baseload generation toward grid-balancing assets and remote industrial supply.
- Pumped Storage:Reversible turbine-generator sets enable multi-gigawatt energy arbitrage and frequency regulation, with European grid operators procuring these as renewable penetration climbs. The EU F-Gas Regulation restricts competing cooling technologies, reinforcing hydroelectric preference for balancing capacity.
- Hydroelectric Power Plants:Conventional baseload installations dominate cumulative capacity, with Chinese provincial utilities prioritizing efficiency upgrades over greenfield development under ecological red line constraints.
- Renewable Energy:Hybrid configurations pairing hydro with solar or wind for firming capacity.
- Off-Grid Systems:Micro and pico-hydro units serving remote industrial loads and rural electrification clusters.
Capacity additions concentrate in pumped storage. Deployment velocity is highest in off-grid systems where development bank financing unlocks previously stalled African projects.
End User:
Procurement authority is fragmenting from centralized state utilities toward distributed ownership structures.
- Utilities:State-owned grid operators in China, Brazil, and Canada maintain dominant procurement volumes for large-scale retrofits and transmission-connected assets, with tender specifications increasingly mandating integrated turbine-generator packages.
- Independent Power Producers:Merchant developers and private operators are capturing share in Southeast Asian river basin developments, where power purchase agreement structures and development bank disbursement conditions favor non-utility procurement.
- Industrial Plants:Captive generation for mining, aluminum smelting, and pulp processing in remote locations.
- Government Agencies:Rural electrification authorities and irrigation departments deploying small-scale units.
Largest order volumes originate with utilities. Fastest procurement growth occurs among independent power producers.
Installation:
Project delivery models range from permanent civil works to factory-fabricated modular systems compressing development timelines.
- Modular:Standardized bulb turbine packages with pre-assembled generator components enable deployment across irrigation canal networks and run-of-river sites without extensive civil construction. Vietnamese and Laotian developers are adopting these configurations to accelerate commissioning schedules.
- Onshore:Conventional powerhouse installations with custom-forged runners and stator frames requiring 18-36 month fabrication timelines, dominating large-project procurement in North American retrofits and Chinese efficiency upgrades.
- Offshore:Tidal and marine current turbine-generator systems in early commercial deployment.
- Fixed:Permanent embedded installations with minimal operational flexibility.
Onshore configurations retain the greatest installed base. Modular approaches are gaining share fastest for distributed low-head applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's provincial utilities retrofit aging Francis units while Brazil's state-owned operators expand Amazon basin capacity, revealing divergent paths between efficiency-focused upgrades and greenfield development.
China
The Ministry of Ecology and Environment enforces river basin ecological red lines that eliminate conventional dam sites, redirecting investment toward efficiency retrofits of existing hydroelectric power plants. Provincial grid operators in Sichuan and Yunnan prioritize generator rewinds and digital excitation system upgrades under the dual carbon goals framework. The Yangtze River Delta hosts manufacturing clusters supplying stator core laminations to domestic retrofit programs.
Brazil
State-owned Eletrobras subsidiaries procure Kaplan and bulb turbine configurations for low-head Amazon tributary developments. ANEEL, the national electric energy regulator, mandates grid code compliance that favors integrated turbine-generator packages from European suppliers. The Belo Monte complex and surrounding Pará state installations concentrate demand for large-diameter runners.
Germany
Alpine utilities in Bavaria and Baden-Württemberg modernize pumped-storage facilities to balance renewable intermittency from northern wind zones. The EU F-Gas Regulation restricts competing cooling technologies, reinforcing hydroelectric preference for grid balancing assets. The Black Forest region hosts Voith Hydro's specialized Francis turbine engineering operations serving Alpine modernization contracts.
United States
FERC licensing requirements drive rehabilitation of pre-1980 hydroelectric installations across the Pacific Northwest and Tennessee Valley. Investor-owned utilities prioritize generator efficiency upgrades and digital governor retrofits to extend asset life without new environmental permitting. The Pacific Northwest National Laboratory collaborates with Bonneville Power Administration on modular turbine testing for irrigation canal networks.
Vietnam
Independent power producers deploy modular bulb turbine packages across Mekong Delta irrigation systems, accelerating commissioning schedules for rural electrification. EVN, the national power utility, fragments procurement through provincial rural electrification agencies under development bank disbursement conditions. The Central Highlands concentrate run-of-river installations where transmission infrastructure investments now precede generation procurement.
Hydrogenerators Market Competitive Landscape
European producers anchor the specialized turbine-generator integration tier; North American and Japanese industrial conglomerates hold scale-driven positions in large-project retrofits and emerging market greenfield development. The market structure exhibits moderate consolidation around full-system integrators, with regional specialists competing on low-head and pumped-storage configurations. Two strategic archetypes dominate: turbine-generator integration specialists and diversified industrial conglomerates with power generation divisions. Competitive moves concentrate on integrated package offerings and modular installation architectures compressing project timelines.
Among diversified industrial conglomerates, General Electric and Siemens occupy positions exemplifying scale-driven retrofit dominance, while Voith Hydro represents the specialized European turbine engineering archetype. These three companies anchor distinct competitive vectors: General Electric leverages turbine-generator integration capabilities for North American utility retrofits; Siemens competes on digital control system integration and grid-code compliance packages; Voith Hydro anchors European supply through Francis turbine expertise and Alpine pumped-storage specialization. The competitive dynamic between integration depth and component specialization shapes procurement outcomes across utility and independent power producer segments.
| Leading Market Players |
|---|
| General Electric |
| Voith Hydro |
| ANDRITZ |
| Toshiba Corporation |
| Siemens |
| Mitsubishi Heavy Industries |
| Cummins Inc. |
| Ingeteam S.A. |
| Nidec Industrial Solutions |
| Others |
Supply & Pricing Matrix
Copper and electrical steel price indices cascade through hydrogenerator manufacturing tiers, compressing margins for regional fabricators while integrated turbine-generator suppliers absorb volatility through captive forging capacity and long-term offtake contracts with Chinese and European steel mills.
Pricing Analysis
Capacity additions in Vietnam and Laos are reshaping price floors for standardized bulb turbine packages, forcing European suppliers to differentiate on IEC 60034 certification tiers rather than unit economics. Three-tier pricing structure across premium certified, standard compliant, and economy regional tiers separates vendors by testing facility accreditation and witness testing documentation depth. Cost compression in the economy tier intensifies as Chinese stator core lamination suppliers expand export capacity. State-owned utilities in Brazil and Canada exhibit lowest price sensitivity due to sovereign financing access, while African rural electrification agencies face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Düsseldorf, Shanghai, and São Paulo anchor hub-and-spoke patterns for spare rotor forgings and emergency stator rewind kits. Manufacturing concentration in China, Germany, and Japan feeds from electrical steel mills in South Korea and copper cathode suppliers in Chile. Single-source vulnerability for custom-forged turbine runners creates 18-36 month lead time exposure that mismatches with accelerated renewable deployment schedules. Distribution runs through EPC contractor logistics networks and direct utility procurement channels for large retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through permanent magnet generator retrofits that eliminate excitation system costs and command efficiency premiums from Alpine and Japanese utilities seeking variable-flow optimization.
For Market Incumbents: Cement turbine-generator integration dominance by acquiring specialized Francis turbine engineering capabilities in European Alpine regions and investing in IEC 60034 accredited test facilities to extend certification bottlenecks. Threat from modular bulb turbine entrants in Southeast Asian irrigation networks demands preemptive channel control through development bank partnership structures. Backward integration into electrical steel lamination production secures cost position against commodity volatility. For New Entrants and Emerging Players: Capture African run-of-river procurement fragmentation where development bank disbursement conditions favor community-benefit structures over utility-centralized tenders. The most penetrable white space sits in sub-10 MW Kaplan configurations for low-head distributed generation across Vietnamese and Laotian irrigation canal networks. Go-to-market leverage rests on standardized package offerings compressing commissioning schedules from months to weeks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized turbine-generator integration firms holding IEC 60034 certification and Alpine pumped-storage reference projects. Long-term viability hinges on grid balancing asset expansion across European markets where F-Gas Regulation restricts competing cooling technologies. Watch for inflection signals in development bank procurement condition templates shifting toward integrated package mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Generator Retrofit | Eliminates excitation systems and reduces auxiliary power consumption for Alpine utilities. |
| IEC 60034 Test Facility Accreditation | Creates 6-12 month approval bottlenecks that protect certified suppliers from regional competition. |
| Modular Bulb Turbine Package Standardization | Compresses outage durations from months to weeks for Japanese run-of-river operators. |
| Development Bank Partnership Structuring | Unlocks previously stalled African projects through community-benefit procurement conditions. |
| Digital Twin Predictive Maintenance Deployment | Reshapes aftermarket service economics for North American utility retrofit programs. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down turbine-generator manufacturing capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads combined with secondary validation from FERC filings, IEA hydropower reports, and development bank project databases. Cross-referencing of IEC 60034 certification records against manufacturer shipment data enables supply-side triangulation.
Historical trendline analysis of capacity additions, retrofit cycles, and pumped-storage commissioning rates informs the projection framework across the analysis window. Segmentation dimensions span turbine architecture, grid integration mode, ownership structure, and head pressure classification. CAGRs derive from unit shipment trajectories and average selling price movements informed by commodity input cost modeling and regional procurement pattern shifts.
Commodity price volatility, regulatory timeline extensions for ecological red line compliance, and development bank disbursement delays are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Oman Power Market
Power Generation
Power Plant EPC Market
Power Generation
Global Gensets Market
Power Generation
Microturbine Market
Power Generation
India Gas Generator Market
Power Generation
Global Gas Turbines Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Shore Power Market
Power Generation
Peaking Power Plant Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Distributed Power Generation Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Commercial Gensets Market
Power Generation
Variable Speed Generator Market