
 Gasoline Generator Market | 2026-2036
Gasoline Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline Generator Market Analysis
Southeast Asia's manufacturing corridor is fragmenting as new assembly plants in Vietnam and Thailand compete for regional supply share. Honda Motor Co. leverages its engine R&D heritage to dominate inverter-class reliability benchmarks. Briggs & Stratton anchors the North American replacement parts ecosystem through captive distribution networks. Generac Power Systems competes in the standby segment by integrating automatic transfer switch technology into residential offerings.
A gasoline generator converts chemical energy from gasoline combustion into electrical output through an internal combustion engine coupled to an alternator, typically producing alternating current at 50 or 60 hertz with output ranging from 500 watts to 15 kilowatts for consumer and light commercial units. Its primary purpose is to provide portable or emergency electrical power where grid connections are unavailable, unreliable, or insufficient for load requirements. Portable units lead unit shipments for recreational and job-site mobility, while standby systems command higher margin pools through permanent installation and automatic-start engineering. Inverter technology is displacing conventional alternator designs in the sub-3-kilowatt residential tier where waveform quality powers sensitive electronics.
The US EPA regulates exhaust emissions under Tier 4 and Phase 3 standards for nonroad spark-ignition engines, compelling manufacturers to adopt fuel injection and catalytic aftertreatment. The EU's F-Gas Regulation and Machinery Directive shape product access requirements across member states, while China's MIIT enforces GB standards on noise and fuel consumption for domestic sales. Stakeholders must monitor how California Air Resources Board waivers and pending federal rulemakings redefine engine certification pathways for portable power equipment.
Market Dynamics
Inverter generator technology is collapsing the boundary between portable and standby power categories, forcing manufacturers to recalibrate R&D allocation and channel positioning simultaneously.
Growth Catalysts
- Indonesia's archipelago electrification gaps:Decentralized grid infrastructure across 17,000 islands sustains demand for portable gasoline units where transmission lines remain uneconomical. Construction contractors in Sulawesi and Papua provinces prioritize mobile power for remote job sites.
- US EPA Tier 4 emissions compliance:Phase 3 standards for small spark-ignition engines are accelerating fuel injection adoption, creating upgrade cycles in the replacement market. Carburetor-to-injection retrofits extend product lifecycles.
- Southeast Asian manufacturing corridor fragmentation:New assembly capacity in Vietnam and Thailand is shortening supply chains for regional distribution. Local production reduces freight costs for sub-5-kilowatt consumer units.
Market Restraints
- Copper and steel input volatility:Alternator windings and engine housings face raw material price swings that compress margin visibility. Manufacturers lack forward-contracting depth for specialty electrical steel grades.
- Chinese engine component concentration:Cylinder heads, crankshafts, and ignition systems cluster in Zhejiang and Jiangsu provinces. Geopolitical friction risks disrupt just-in-time assembly schedules.
- Lithium-ion battery substitution:Silent, emission-free battery generators capture recreational and light residential loads below 2 kilowatts. Gasoline units lose share in noise-sensitive camping and tailgating segments.
Strategic Opportunities
- Philippines rural electrification:Barangay-level microgrids in Mindanao and Visayas lack grid interconnection. Gasoline generators fill baseload gaps before solar-battery hybrid deployment matures.
- EU F-Gas Regulation alignment:Phasedown of fluorinated greenhouse gases creates openings for propane conversion kits and alternative fuel compatibility. Dual-fuel engineering commands certification premiums.
- E-commerce direct-to-consumer channels:Amazon and regional platforms (Shopee, Lazada) displace traditional dealer networks for sub-3-kilowatt residential sales. Digital shelf space reduces working capital requirements.
Industry Challenges
- Small-engine calibration expertise scarcity:Fuel injection mapping and catalytic aftertreatment integration require software-capable technicians. Vocational pipelines in Southeast Asia lag OEM hiring needs.
- California Air Resources Board waiver complexity:State-level emissions certifications create parallel compliance tracks beyond federal EPA pathways. Multi-jurisdiction product planning extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline Generator Market |
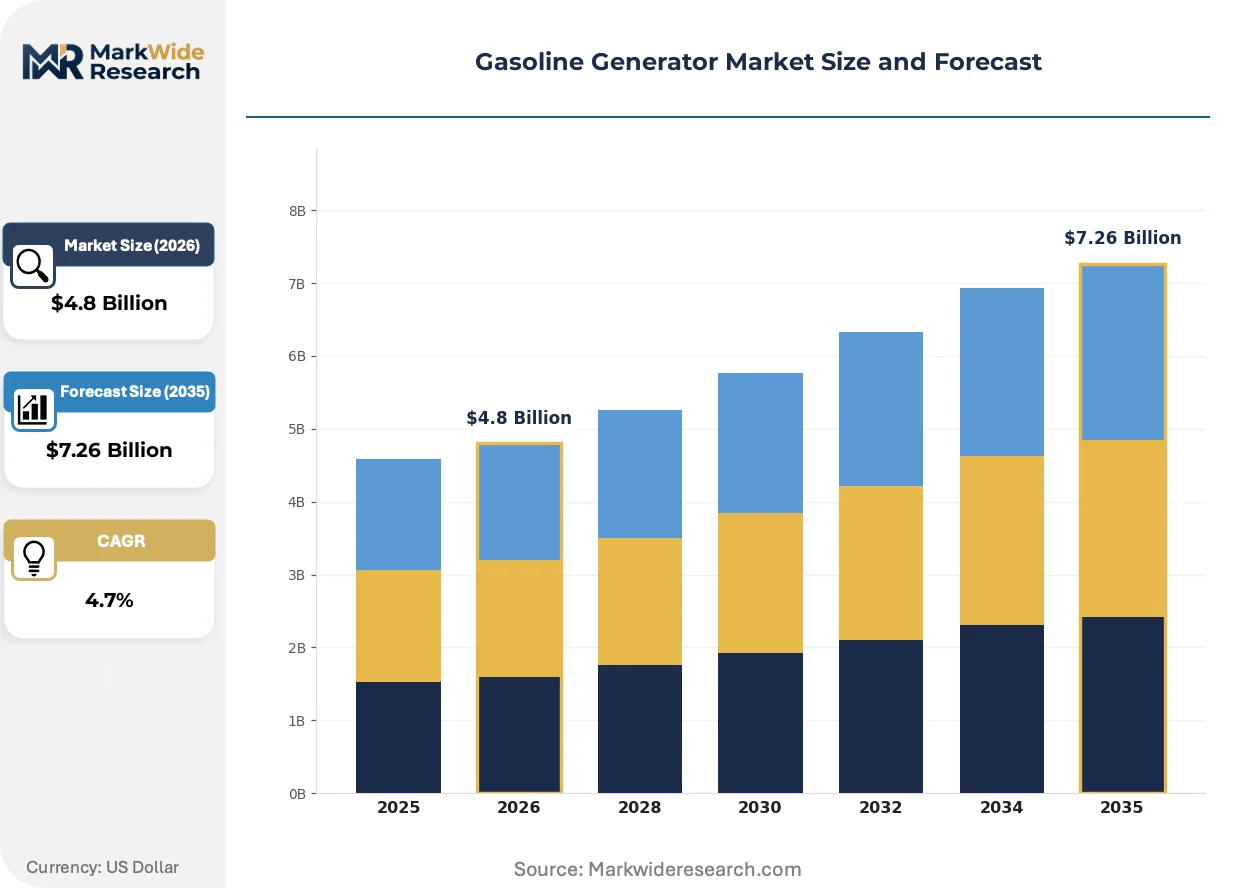
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Inverter, Dual Fuel End User: Residential, Commercial, Industrial, Emergency Services Technology: Conventional, Electronic, Hybrid, Smart Power Rating: Less than 1 kW, 1-3 kW, 3-5 kW, Above 5 kW |
| Companies Covered | Honda Motor Co., Briggs & Stratton, Generac Power Systems, Atlas Copco AB, Kohler Co., Cummins Inc., DuroMax Power Equipment, Kubota Corporation, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline Generator Market Emerging Trajectories
Waveform quality requirements from sensitive electronics are reshaping generator architecture faster than traditional power-tool loads can sustain conventional alternator economics.
Inverter generator circuitry is collapsing the cost premium between sine-wave and modified-wave output. Smartphone, laptop, and medical device loads now dominate residential purchase criteria. Japanese and South Korean OEMs embed microprocessor-controlled voltage regulation in sub-2-kilowatt units. The technology is collapsing aftermarket UPS pairing demand as built-in power conditioning becomes standard.
EPA Phase 3 small spark-ignition engine standards are mandating closed-loop fuel injection and evaporative emissions controls. Carburetor production lines face stranded asset risk as port fuel injection becomes baseline. California's pending waivers for handheld and portable equipment may accelerate catalyst integration timelines. Engine manufacturers are responding with modular aftertreatment architectures that scale across displacement classes.
Recreational buyers now prioritize decibel ratings and parallel connection capability over raw wattage specifications. Camping and RV segments reward quiet operation over peak output. Retail channel training emphasizes runtime-at-quarter-load metrics rather than maximum surge capacity. This behavioral pivot is most visible in US and Australian markets where outdoor lifestyle equipment spending concentrates.
Gasoline Generator Market Segmentation
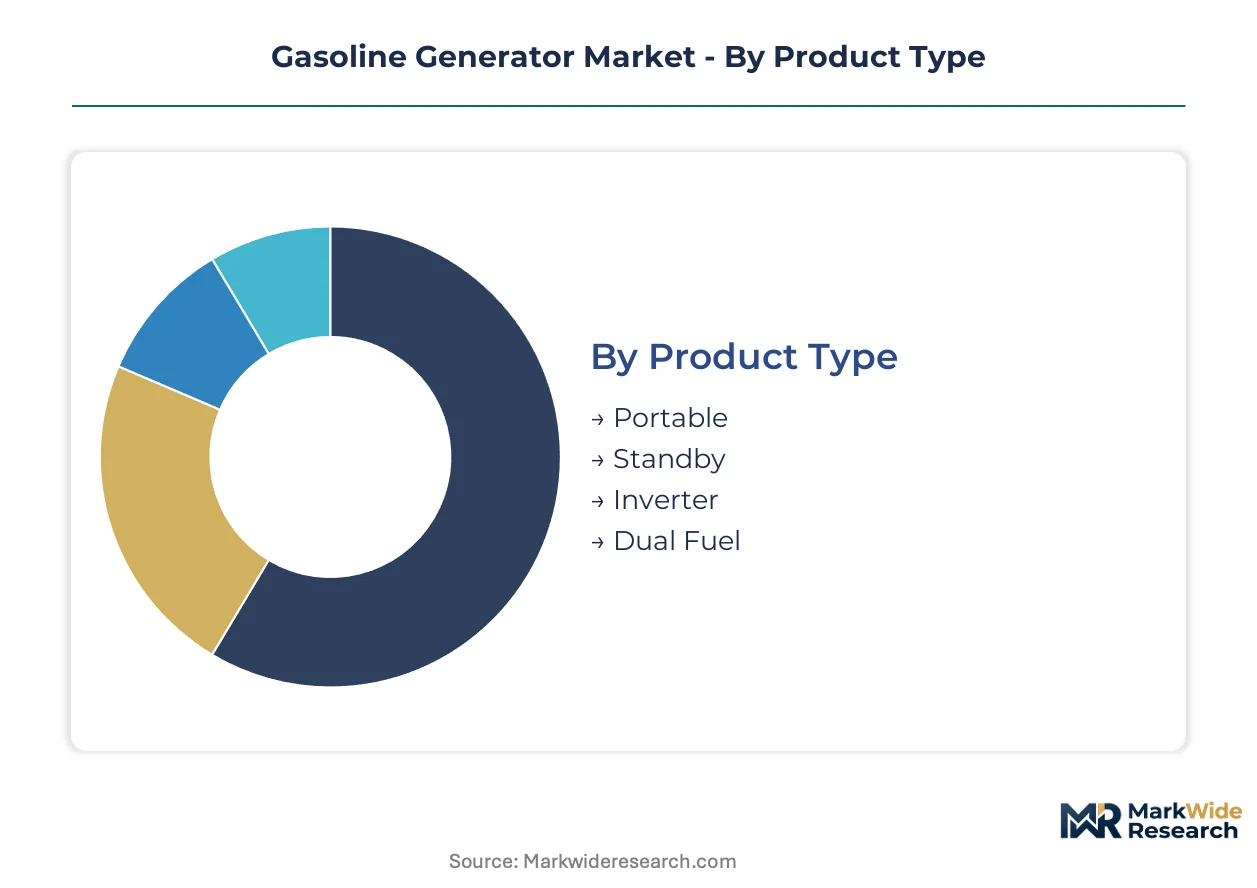
Gasoline generator procurement patterns diverge sharply across use-case scenarios, with waveform quality requirements and runtime economics driving category-specific engineering investments. Manufacturers must calibrate R&D allocation across four distinct segmentation axes to capture margin pools effectively.
Product Type:
Cost tier stratification separates mobile recreational units from permanently installed standby systems, with inverter technology collapsing the boundary between categories.
- Portable:Units below 5 kilowatts dominate unit shipments through recreational and construction mobility applications. Indonesian contractors in Sulawesi and Papua provinces prioritize these for remote job sites where grid access remains uneconomical.
- Standby:Permanent installation systems integrate automatic transfer switches for residential and commercial backup. Higher margin pools accrue through engineering services and maintenance contracts rather than hardware alone.
- Inverter:Microprocessor-controlled voltage regulation produces sine-wave output suitable for sensitive electronics. Waveform quality is displacing raw wattage as the primary purchase criterion in sub-3-kilowatt residential tiers.
- Dual Fuel:Propane compatibility kits address EU F-Gas Regulation phasedown requirements. Certification premiums attach to alternative fuel engineering as gasoline-only designs face regulatory headwinds.
Portable holds installed capacity. Inverter is rotating up the share rankings.
End User:
Application intensity varies from intermittent recreational use to continuous industrial baseload, reshaping durability specifications and service interval engineering.
- Residential:Backup power for outage protection and recreational activities drives sub-5-kilowatt purchases. Decibel ratings and parallel connection capability now outweigh maximum surge capacity in purchase decisions.
- Commercial:Retail, hospitality, and small business operations require runtime reliability for revenue protection. Construction contractors across Southeast Asia expand procurement as grid reliability fluctuates.
- Industrial:Manufacturing facilities and mining operations deploy higher-capacity units for process continuity. Load profiles demand extended runtime-at-rated-load performance rather than peak surge tolerance.
- Emergency Services:Hospitals, fire departments, and disaster response agencies mandate instant-start reliability under stress conditions. EPA emissions compliance adds procurement complexity for fleet operators.
Commercial holds installed capacity. Residential is rotating up the share rankings.
Technology:
Maturity gradients separate legacy electromechanical designs from software-defined power management architectures, with fuel injection mapping becoming the critical competence gap.
- Conventional:Brush-type alternators with mechanical voltage regulation serve price-sensitive bulk power applications. Carburetor-based fuel systems face stranded asset risk under EPA Phase 3 standards.
- Electronic:Digital voltage regulation and closed-loop fuel injection improve efficiency and emissions compliance. Port fuel injection retrofits extend product lifecycles in the replacement market.
- Hybrid:Gasoline-battery combinations capture peak shaving and silent operation modes. Lithium-ion substitution threats concentrate in this sub-2-kilowatt recreational segment.
- Smart:IoT connectivity enables remote monitoring, predictive maintenance, and load optimization. Mobile app integration commands price premiums in residential standby configurations.
Conventional holds installed capacity. Electronic is rotating up the share rankings.
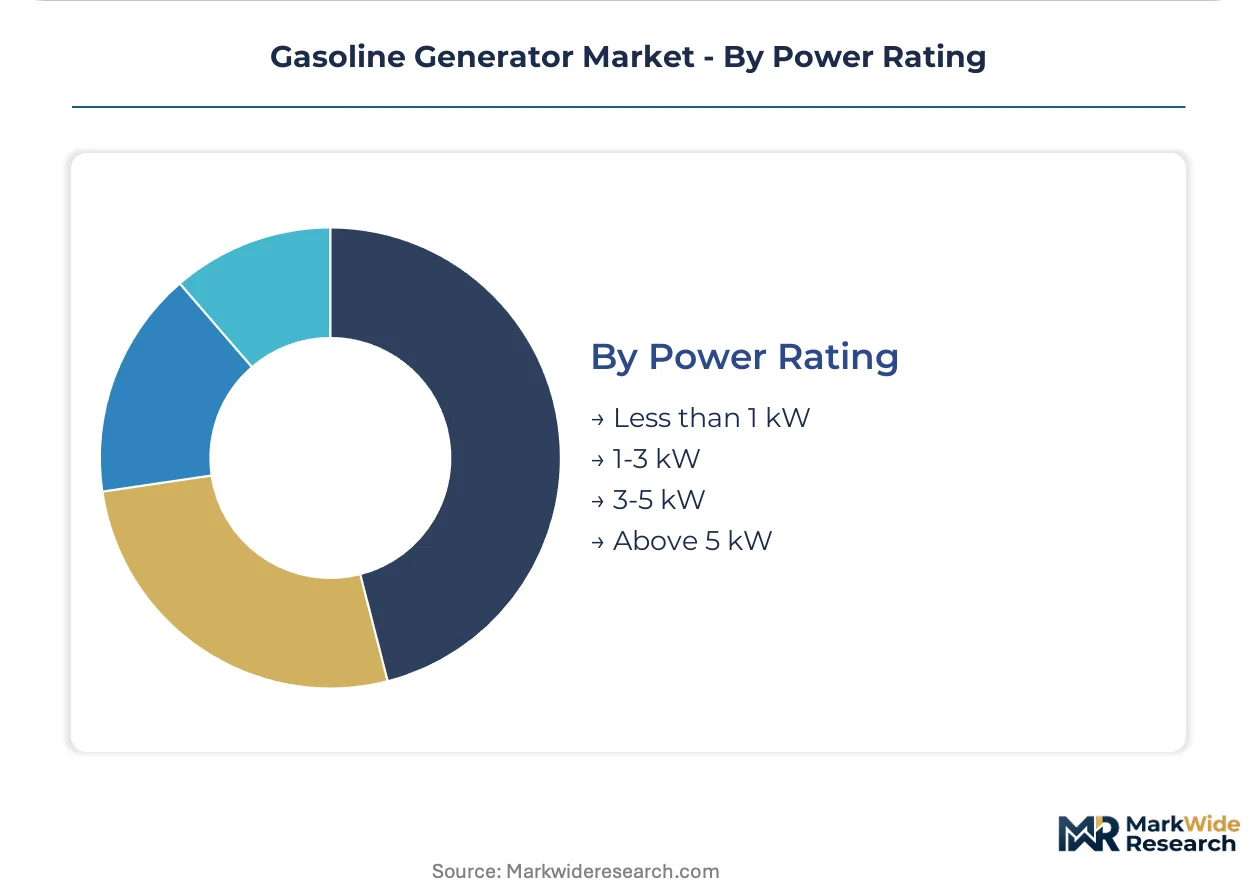
Power Rating:
Volume distribution concentrates in smaller displacement classes where manufacturing scale and e-commerce channel penetration enable working capital efficiency.
- Less than 1 kW:Ultra-portable units serve camping, tailgating, and personal electronics charging. Lithium-ion battery generators capture share in this noise-sensitive recreational tier.
- 1-3 kW:Residential backup and light commercial applications balance portability with substantive power delivery. Inverter technology penetration is deepest in this rating band.
- 3-5 kW:Small business and construction job-site requirements demand sustained runtime performance. Southeast Asian assembly plants in Vietnam and Thailand optimize production for this consumer-commercial boundary.
- Above 5 kW:Industrial and large commercial loads require reinforced frames and enhanced cooling systems. Copper and steel input volatility compresses margin visibility most severely in this housing-intensive segment.
1-3 kW holds installed capacity. 3-5 kW is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine manufacturing clusters in Japan and the United States anchor gasoline generator supply chains, while demand concentrates in archipelago nations with incomplete grid infrastructure. Southeast Asian assembly expansion shortens regional distribution routes. Regulatory divergence between EPA Phase 3 standards and EU F-Gas phasedowns complicates multi-jurisdiction product planning.
United States
Recreational buyers in Texas and Florida prioritize decibel ratings and parallel connection capability for RV and camping applications. EPA Tier 4 and Phase 3 standards for small spark-ignition engines mandate closed-loop fuel injection and catalytic aftertreatment. Wisconsin-based engine manufacturers anchor the North American replacement parts ecosystem through captive distribution networks.
Indonesia
Construction contractors in Sulawesi and Papua provinces expand mobile power procurement as grid reliability fluctuates across 17,000 islands. The national electrification program leaves decentralized baseload gaps that gasoline units fill before solar-battery hybrid deployment matures. Surabaya and Jakarta serve as import hubs for sub-5-kilowatt consumer units.
Japan
Microprocessor-controlled voltage regulation in sub-2-kilowatt inverter units targets residential backup for sensitive electronics. METI efficiency standards shape domestic product specifications. Tokyo-Osaka industrial corridors concentrate R&D heritage for engine reliability benchmarks.
Germany
EU F-Gas Regulation phasedown of fluorinated greenhouse gases creates openings for propane conversion kits and alternative fuel compatibility. The Machinery Directive and CE marking requirements filter product access. Bavarian industrial zones host testing facilities for dual-fuel engineering certification.
Vietnam
New assembly capacity shortens supply chains for regional distribution of consumer-commercial boundary units. Chinese engine component concentration in neighboring Zhejiang and Jiangsu provinces exposes just-in-time schedules to geopolitical friction. Ho Chi Minh City industrial parks optimize production for 3-5 kilowatt ratings.
Gasoline Generator Market Vendor Landscape
Vertically integrated engine specialists and diversified power equipment conglomerates split the market between proprietary technology control and portfolio breadth. Honda Motor Co. and Briggs & Stratton anchor opposing strategic poles. Three archetypes dominate: Japanese precision-engineering houses, North American distribution-captive manufacturers, and European industrial equipment conglomerates. M&A activity concentrates in automatic transfer switch integration and inverter circuitry acquisitions. Geographic expansion through Southeast Asian assembly joint ventures accelerates.
Among Japanese precision-engineering houses, Honda Motor Co. exemplifies the engine R&D heritage archetype. Briggs & Stratton occupies a position within the North American distribution-captive tier. Generac Power Systems represents the standby-system integration specialist. These three companies illustrate how waveform quality requirements and emissions compliance are reshaping competitive positioning across the gasoline generator market.
| Leading Market Players |
|---|
| Honda Motor Co. |
| Briggs & Stratton |
| Generac Power Systems |
| Atlas Copco AB |
| Kohler Co. |
| Cummins Inc. |
| DuroMax Power Equipment |
| Kubota Corporation |
| Caterpillar Inc. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-to-Los Angeles transpacific corridor anchors freight cost dynamics for gasoline generator components, compressing margin visibility for manufacturers dependent on Chinese engine parts while enabling price differentiation between inventory-heavy and lean-configured competitors.
Pricing Analysis
EPA Phase 3 small spark-ignition engine standards dictate the pricing tier structure across the gasoline generator market. Three-tier pricing structure across premium, standard, and economy levels separates inverter-class fuel injection systems from carburetor-based conventional units from basic recreational models. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because stranded carburetor production lines face asset write-down pressure. Residential recreational buyers exhibit highest price sensitivity, while emergency services procurement teams prioritize reliability premiums over unit cost.
Supply Chain Analysis
Extended payment terms from Zhejiang and Jiangsu component suppliers have become the dominant supply-chain finance mechanism for Southeast Asian assembly plants. Manufacturing gravity centers on China for cylinder heads and ignition systems, Vietnam for 3-5 kilowatt final assembly, and Japan for microprocessor-controlled inverter modules. Raw material dependencies rest on copper for alternator windings, specialty electrical steel for laminations, and aluminum for engine housings. Single-source vulnerability in Chinese crankshaft machining creates chokepoint exposure. Distribution runs through captive dealer networks for standby systems and e-commerce platforms for sub-3-kilowatt portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gasoline generator incumbents face a substitution defense imperative as lithium-ion battery generators capture sub-2-kilowatt recreational loads through silent operation and zero-emission positioning.
For Market Incumbents: Harden inverter technology R&D allocation to collapse the cost premium against battery substitutes in the 1-3 kilowatt residential tier. Deepen backward integration into fuel injection system production to capture margin pools eroding from carburetor phase-out. Secure automatic transfer switch engineering talent through targeted acquisition of standby-system specialists before Generac and Kohler consolidate this capability layer. For New Entrants and Emerging Players: Mindanao and Visayas barangay-level microgrids in the Philippines present the most penetrable white-space target for gasoline-battery hybrid configurations before solar-battery deployment matures. Sulawesi construction contractors offer a second entry vector through mobile power procurement for remote job sites. Pursue direct-to-consumer e-commerce positioning on Shopee and Lazada to bypass entrenched dealer networks and reduce working capital requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded small-engine divisions facing EPA compliance cost burdens. Long-term viability frames around 5-10 year regulatory compliance windows where fuel injection and catalytic aftertreatment expertise concentrates value. Watch California Air Resources Board waiver rulings as the inflection signal for accelerated catalyst integration timelines that would strand carburetor-dependent assets faster than federal EPA schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Injection System Integration | EPA Phase 3 compliance mandates closed-loop port injection, collapsing carburetor economics. |
| Inverter Circuitry Acquisition | Microprocessor-controlled voltage regulation commands premium positioning in sub-3-kilowatt tiers. |
| Southeast Asian Assembly Joint Venture | Vietnam and Thailand production shortens supply chains for Indonesian archipelago distribution. |
| Dual-Fuel Engineering Certification | EU F-Gas Regulation phasedown creates propane compatibility premiums in European markets. |
| E-Commerce Channel Direct Launch | Amazon and regional platforms displace traditional dealer networks for residential sales. |
Methodological Framework
A spread of perspectives from plant engineers at Indonesian construction sites, procurement leads at Vietnamese assembly facilities, aftermarket service heads at North American distributors, and regulatory affairs specialists at engine OEMs converged on the working assumptions. Primary interviews combined with secondary validation from EPA certification databases, EU Machinery Directive technical files, and customs trade records for generator imports into Indonesia and the Philippines. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user intensity, technology maturity gradient, and power rating tier. CAGRs derived from historical trajectory analysis adjusted for regulatory compliance cycle timing and raw material input volatility. Industry-specific forecast inputs incorporated EPA Phase 3 implementation schedules and lithium-ion battery cost curves for recreational segment substitution pressure.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese battery generator specialists or accelerated CARB waiver timelines would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Construction Generator Sets Market
Generators
Saudi Arabia Diesel Generator Market
Generators
North America Gasoline Gensets Market
Generators
China Generator Sets Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
China Diesel Generator Market
Generators
South America Diesel Generator Market
Generators
Generator Sales Market
Generators
Tri Fuel Generators Market
Generators
Dual-Fuel Generator Market
Generators
Power Generator Rental Market
Generators
Industrial Generator Market
Generators
North America Diesel Generator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Heat Recovery Steam Generator Sales Market