
 Japan Thermal Power Plant Market | 2026-2036
Japan Thermal Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Thermal Power Plant Market Foresight
Power project finance through utility-sponsored leasing vehicles is reshaping competitive access for independent operators and equipment suppliers. Mitsubishi Heavy Industries leverages its integrated turbine-generator manufacturing scale to anchor long-term service contracts. Toshiba Corp competes through specialized ultra-supercritical steam system retrofits. J-POWER sustains its position by controlling a nationwide portfolio of coal and gas-fired baseload assets.
Japan thermal power plants are electricity generation facilities that combust fossil fuels or biomass to produce steam or hot combustion gases, driving turbines connected to generators at capacities ranging from hundreds of megawatts to gigawatt scale, with thermal efficiencies varying from subcritical cycles below 40% to advanced combined-cycle configurations exceeding 60%. These installations serve as dispatchable baseload and mid-merit resources that balance grid stability against variable renewable output in one of the world's most constrained electricity systems. Natural gas combined-cycle technology leads new-build investment due to lower carbon intensity per kilowatt-hour and faster ramping capability, while coal retrofits dominate the installation segment as aging subcritical units face efficiency mandates. Biomass co-firing represents the fastest-growing type category, driven by feed-in-tariff structures and forestry residue availability from Hokkaido and Tohoku supply chains.
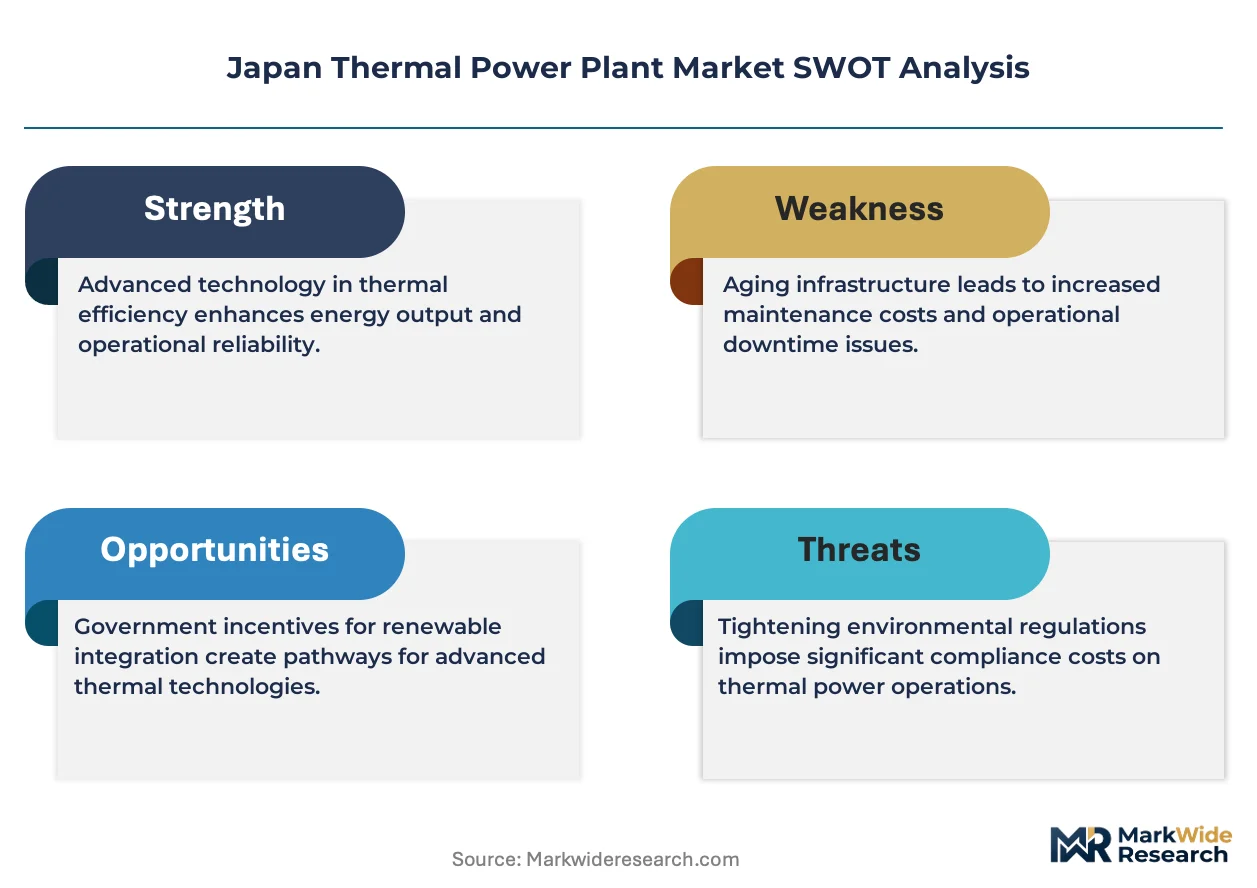
METI's GX League transition framework and the Ministry of the Environment's emissions trading pilot are tightening operational carbon intensity benchmarks, forcing operators to select between deep retrofits, fuel switching, or strategic retirement. JIS B 8223 and associated power plant construction standards govern material specifications, welding protocols, and pressure vessel integrity, creating compliance barriers for non-domestic equipment entrants. Stakeholders must monitor the pace of hydrogen-ammonia co-firing demonstration outcomes and their subsequent codification into feedstock eligibility rules under Japan's green transformation taxonomy.
Market Dynamics
METI's GX League transition framework is forcing Japanese thermal operators to choose between deep efficiency retrofits, fuel switching to hydrogen-ammonia blends, or strategic plant retirement. This regulatory pressure cascades through equipment procurement, service contracting, and financing structures across the archipelago.
Growth Catalysts
- Baseload Necessity:Nuclear intermittency in the Kanto region compels utilities to maintain gas-fired spinning reserves. Grid stability requirements sustain investment cycles in combined-cycle turbine systems.
- GX League Compliance:METI's carbon intensity benchmarks accelerate retrofit demand for ultra-supercritical steam cycles. Operators face 2030 efficiency mandates that subcritical plants cannot meet without overhaul.
- Biomass Feedstock Abundance:Forestry residue supply chains from Hokkaido and Tohoku enable co-firing retrofits. Feed-in-tariff structures protect returns for biomass-gas hybrid configurations.
Market Restraints
- Dominated Equipment Supply:Turbine-generator manufacturing concentrates among three domestic industrial groups. Foreign entrants face JIS B 8223 certification barriers and welding protocol exclusions.
- LNG Price Volatility:Combined-cycle operators absorb fuel cost swings without full pass-through mechanisms. Marginal plants in western Honshu face negative spark spreads during price spikes.
- Ammonia Infrastructure Gap:Hydrogen-ammonia co-firing pilots lack codified feedstock eligibility under green transformation taxonomy. Regulatory uncertainty freezes commercial-scale investment decisions.
Strategic Opportunities
- Chubu Industrial Corridor Expansion:Petrochemical and semiconductor manufacturers in Aichi and Mie prefectures require dispatchable thermal output. Dedicated power purchase agreements anchor greenfield gas plant economics.
- Service Contract Unbundling:Independent operators access long-term maintenance agreements previously captured by integrated manufacturers. Utility-sponsored leasing vehicles reshape competitive access.
- Hydrogen-Ready Turbine Retrofits:METI demonstration programs subsidize 30% ammonia co-firing capability upgrades. Early movers secure preferential grid dispatch under capacity market rules.
Industry Challenges
- Specialized Welding Certification:JIS-qualified pressure vessel technicians face acute shortages. Retrofit timelines extend 18-24 months due to inspection queue congestion.
- Legacy Control System Integration:Digital turbine monitoring platforms must interface with 1980s-era distributed control architectures. Middleware development consumes 15-20% of project engineering budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Thermal Power Plant Market |
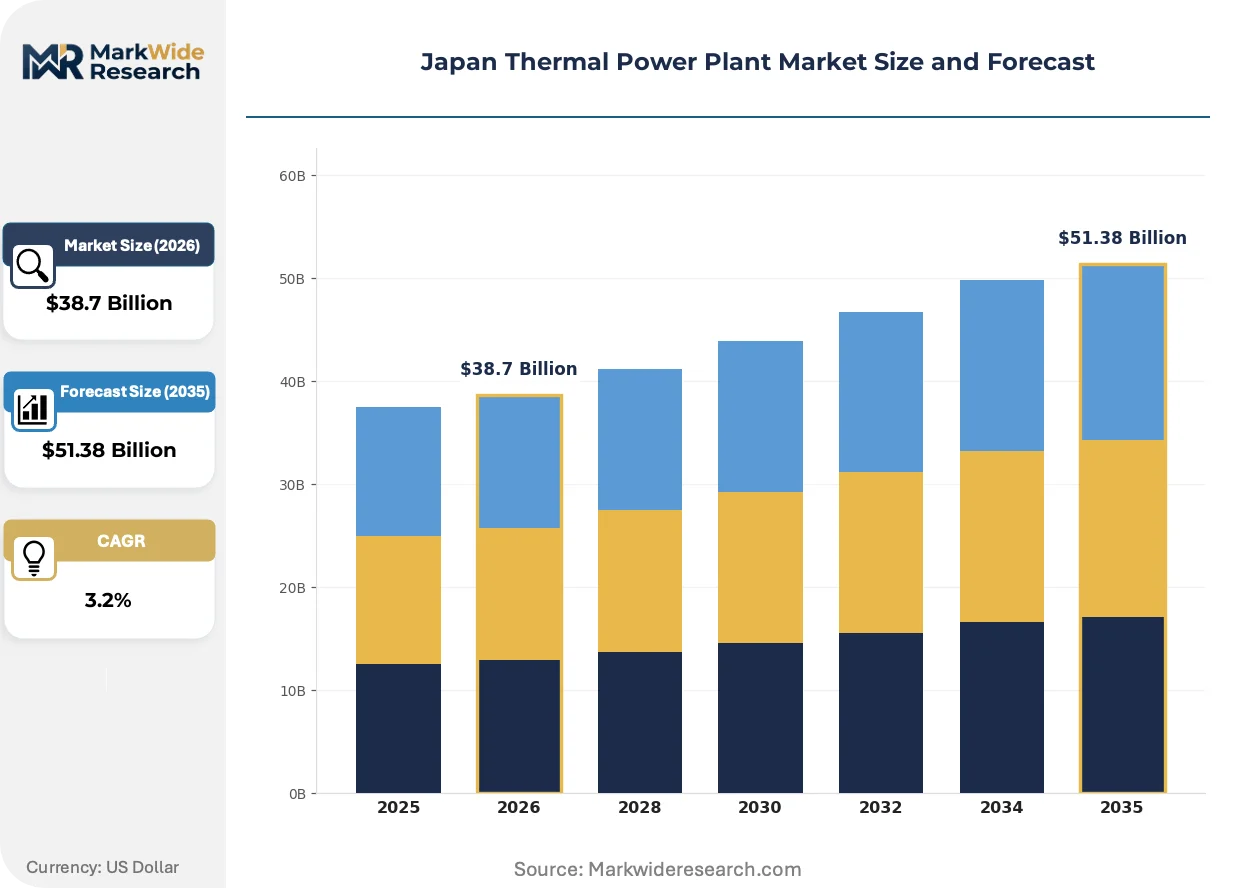
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $51.38 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Coal, Natural Gas, Oil, Biomass Technology: Conventional, Combined Cycle, Gas Turbine, Steam Turbine End User: Utilities, Industrial, Commercial, Residential Installation: Onshore, Offsite, Retrofit, New Build |
| Companies Covered | Tokyo Electric Power Company Holdings, Inc., Mitsubishi Heavy Industries, Ltd., Toshiba Corp, Hitachi, Ltd., Chubu Electric Power Co., Inc., The Kansai Electric Power Co., Inc., J-POWER (Electric Power Development Co., Ltd.), Chugoku Electric Power Co., Inc., Kyushu Electric Power Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Thermal Power Plant Market Shifts & Advancements
Japanese thermal power is compressing toward dual-fuel flexibility and digitalized asset management. Technology trajectories prioritize carbon intensity reduction without sacrificing dispatchability.
Advanced gas turbine blade coatings are collapsing maintenance intervals for combined-cycle units operating on variable renewable balancing duty. Chubu Electric and JERA deploy these materials across 1,600 MW-class blocks. The technology is collapsing the economic trade-off between cycling frequency and component life, enabling deeper renewable penetration without standby reserve penalties.
METI's 2023 feed-in-tariff revision for biomass co-firing tightens sustainability certification requirements. Forestry residue traceability mandates now require blockchain-verified chain-of-custody documentation. Biomass-gas hybrid projects in Tohoku face 6-9 month approval delays as operators implement new verification systems.
Power purchase agreement structures are fragmenting across term length and price indexation clauses. Semiconductor fabs in Kyushu negotiate 15-year baseload contracts with fixed LNG pass-through formulas. Smaller industrial offtakers in Kansai migrate to shorter tenors with spot-indexed pricing, accepting volume flexibility in exchange for lower fixed charges.
Japan Thermal Power Plant Market Segmentation
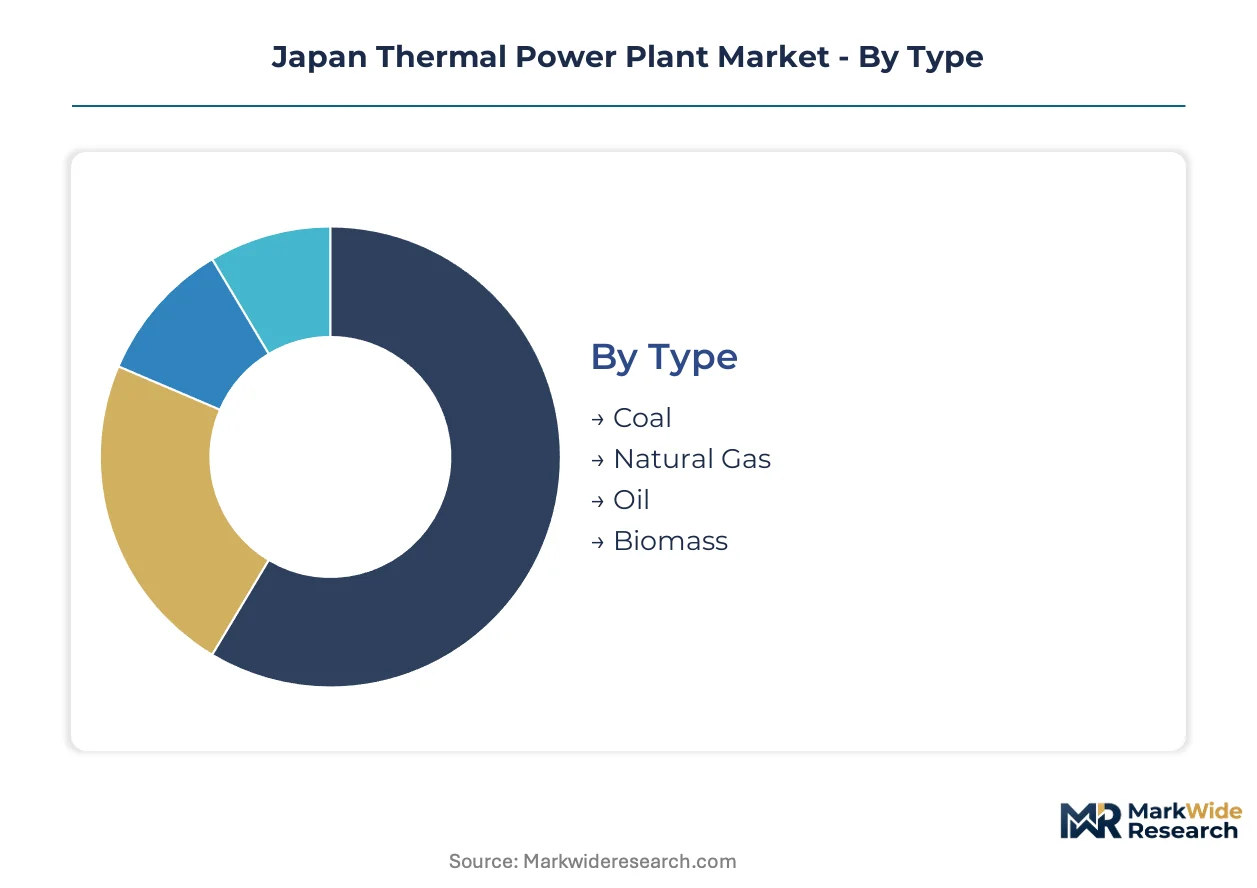
Segmentation reveals how METI efficiency mandates and fuel-switching economics fragment procurement priorities across Japanese thermal operators. Equipment specifications diverge sharply between baseload utilities and cycling-dependent industrial generators.
Type:
After-sales service intensity varies dramatically by fuel chemistry, with coal retrofits demanding specialized pressure vessel inspection protocols that natural gas units rarely require.
- Coal:Aging subcritical units face METI-mandated efficiency overhauls requiring JIS-qualified welding crews. Chubu Electric and J-POWER dominate retrofit procurement for their legacy baseload portfolios. By volume, coal leads. By growth pace, natural gas is ahead.
- Natural Gas:Combined-cycle configurations exceed 60% thermal efficiency and ramp within minutes to balance variable renewable output. Kanto utilities prioritize these systems for nuclear intermittency coverage.
- Oil:Peaking plants in Okinawa and remote islands retain strategic reserve status despite high carbon intensity. METI designates these as grid stability assets exempt from standard retirement timelines.
- Biomass:Forestry residue co-firing from Hokkaido supply chains climbs fastest under feed-in-tariff protection.
Coal dominates installed megawatts. Biomass expands most quickly under green transformation incentives.
Technology:
Cost tiering separates premium combined-cycle blocks from conventional steam systems, with price spreads reflecting turbine inlet temperature capabilities and maintenance contract bundling.
- Conventional:Subcritical steam cycles below 40% efficiency face regulated phase-out unless retrofitted with ultra-supercritical upgrades. Tohoku operators concentrate procurement here for biomass hybridization.
- Combined Cycle:Gas turbines exhaust into heat recovery steam generators, capturing waste heat for secondary power generation. JERA deploys 1,600 MW-class units across Chubu and Kanto for baseload duty.
- Gas Turbine:Simple-cycle aeroderivative units provide sub-15-minute startup for grid balancing. Western Honshu utilities specify these for LNG price volatility exposure.
- Steam Turbine:Legacy units predominate in coal and biomass applications requiring saturated steam conditions.
Combined cycle commands capital deployment. Conventional technology faces steepest replacement pressure.
End User:
Application context dictates equipment sizing, with semiconductor fabs demanding power quality specifications that standard utility procurement rarely includes.
- Utilities:Regional power companies operate gigawatt-scale portfolios under METI capacity market rules. J-POWER, Chubu Electric, and Tohoku Electric anchor procurement volume for baseload and reserve assets.
- Industrial:Petrochemical complexes in Mie and steel mills in Kitakyushu negotiate dedicated power purchase agreements. These offtakers require dispatchable thermal output unavailable from grid-mix contracts.
- Commercial:District heating and cooling operators in Tokyo and Osaka metropolitan areas specify cogeneration configurations.
- Residential:Micro-cogeneration fuel cells and small gas engines serve detached housing in gas-grid regions.
Utilities absorb most megawatts. Industrial self-generation expands most quickly under reliability premiums.
Installation:
Geography constrains site selection, with coastal locations dominating for LNG regasification integration and cooling water access.
- Onshore:Greenfield developments concentrate in Chubu and Kanto industrial corridors with existing transmission infrastructure. Coastal sites enable direct LNG receipt without pipeline construction.
- Offsite:Modular power barges and floating storage serve Okinawa and remote islands lacking land availability. These configurations avoid seismic foundation requirements.
- Retrofit:Efficiency upgrades and fuel-switching modifications extend asset life for aging subcritical coal units. JIS B 8223 pressure vessel recertification governs all structural modifications.
- New Build:Hydrogen-ready turbine specifications dominate recent procurement, with METI demonstration subsidies covering ammonia co-firing capability.
Retrofit work exceeds new build by project count. New build claims capital intensity leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto utilities command premium pricing for baseload capacity against nuclear intermittency, while Chubu industrial generators absorb efficiency retrofit costs under METI mandates. This pricing-power asymmetry fragments procurement priorities across Japan's archipelago.
Kanto
Tokyo Electric and regional utilities maintain gas-fired spinning reserves to offset nuclear reactor outages. METI capacity market rules reward dispatchable assets with preferential grid access. The Keihin industrial corridor hosts semiconductor fabs negotiating 15-year baseload power purchase agreements.
Chubu
Petrochemical complexes in Aichi and steel mills in Mie prefecture require thermal output unavailable from variable renewables. Chubu Electric anchors procurement for ultra-supercritical retrofits under 2030 efficiency deadlines. The Nagoya-Toyota manufacturing cluster drives dedicated cogeneration installations.
Kansai
Kansai Electric balances LNG price volatility against industrial reliability premiums from Osaka-based manufacturers. The Ministry of the Environment's emissions trading pilot tightens operational carbon intensity benchmarks for aging coal units. The Osaka-Kobe industrial zone sustains mid-merit gas turbine deployment.
Kyushu
Kyushu Electric manages grid stability across an island system with limited interconnection to Honshu. Smaller industrial offtakers migrate to shorter-term power purchase agreements with spot-indexed LNG pricing. The Kitakyushu steel corridor maintains blast furnace-dependent thermal demand.
Tohoku
Forestry residue supply chains from Iwate and Aomori prefectures enable biomass co-firing retrofits under feed-in-tariff protection. J-POWER controls coal and gas-fired baseload assets serving northern industrial load. Biomass-gas hybrid projects face approval delays from new blockchain-verified chain-of-custody requirements.
Japan Thermal Power Plant Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in turbine blade coatings and pressure vessel fabrication. The vendor base concentrates among three domestic industrial groups with JIS B 8223 certification advantages. Strategic archetypes include integrated turbine-generator manufacturers, ultra-supercritical retrofit specialists, and utility-sponsored leasing vehicles. Competitive moves center on long-term service contract bundling and hydrogen-ready turbine specification races.
Within the integrated manufacturing tier, Mitsubishi Heavy Industries and Toshiba Corp occupy positions shaped by manufacturing scale and specialized retrofit capabilities respectively. Tokyo Electric Power Company Holdings exemplifies the utility-platform archetype controlling dispatch and financing structures. J-POWER sits within the independent power producer category with nationwide coal and gas asset portfolios. These three entities represent distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Tokyo Electric Power Company Holdings, Inc. |
| Mitsubishi Heavy Industries, Ltd. |
| Toshiba Corp |
| Hitachi, Ltd. |
| Chubu Electric Power Co., Inc. |
| The Kansai Electric Power Co., Inc. |
| J-POWER (Electric Power Development Co., Ltd.) |
| Chugoku Electric Power Co., Inc. |
| Kyushu Electric Power Co., Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in western Honshu gas-fired capacity is compressing spark spreads and forcing turbine suppliers into extended payment terms to secure equipment orders. This utilization squeeze reshapes both procurement negotiations and supplier financing structures across the archipelago.
Pricing Analysis
The customization-premium spread separates hydrogen-ready turbine specifications from standard combined-cycle configurations. Project-based long-term offtake contracts dominate, with price differentiation driven by JIS B 8223 certification tier and after-sales service bundling. Cost compression in standard gas turbine supply is intensifying because LNG price volatility erodes operator capital budgets. Industrial self-generators in Chubu exhibit lowest price sensitivity due to reliability premiums, while smaller commercial offtakers in Kansai drive hardest bargain on unit economics.
Supply Chain Analysis
Supplier-financing facilities from utility-sponsored leasing vehicles now extend payment terms to 36 months for major equipment procurement. Manufacturing concentrates in Japan, with critical components drawn from South Korea and Germany. Raw material dependencies center on nickel-based superalloys, precision-forged turbine blades, and high-grade pressure vessel steel. Single-source vulnerability looms in JIS-qualified welding certification, where technician shortages create inspection queue congestion. Distribution runs through regional utility procurement consortia and EPC contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's thermal power sector operates as a substitution defense against renewable overbuild and nuclear intermittency, with battery storage and grid-scale solar posing the most credible displacement threat to mid-merit gas assets.
For Market Incumbents: Harden service contract bundling to capture aftermarket revenue streams as new-build orders plateau. Deepen backward integration into hydrogen-ready turbine manufacturing to secure METI demonstration subsidies. Vertical control over JIS-qualified welding crews defends against technician shortage bottlenecks that delay retrofit timelines. For New Entrants and Emerging Players: Biomass-gas hybrid retrofits in Tohoku represent the most penetrable entry point given feed-in-tariff protection and forestry residue supply chain maturity. Independent maintenance providers can unbundle long-term service agreements previously captured by integrated manufacturers. A go-to-market angle anchored to blockchain-verified chain-of-custody certification addresses METI's tightened sustainability requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogen-ammonia co-firing capability upgrades. Long-term viability over the coming decade hinges on regulatory codification of feedstock eligibility under green transformation taxonomy. Acquisition targets should display utility-sponsored leasing vehicle relationships and preferential grid dispatch rights. The signal to watch is ammonia infrastructure investment commitments from major trading houses.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | METI demonstration subsidies cover 30% of ammonia co-firing upgrades for early movers. |
| Long-Term Service Agreement Unbundling | Independent operators access maintenance contracts previously captured by Mitsubishi Heavy Industries. |
| Biomass-Gas Hybrid Development | Forestry residue supply chains from Hokkaido enable feed-in-tariff protected project economics. |
| JIS B 8223 Certification Investment | Pressure vessel recertification capabilities create compliance barriers against foreign equipment entrants. |
| Utility-Sponsored Leasing Vehicle Formation | Tokyo Electric and Chubu Electric reshape competitive access for independent power producers. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with plant engineers and aftermarket service heads alongside secondary validation from METI policy filings, JERA capex disclosures, and IEA power sector databases. Bottom-up project pipelines and top-down capacity forecasts were triangulated to anchor volume estimates.
Scenario-bracketing around nuclear restart trajectories and LNG price bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, and regional grid type. CAGRs were derived from installed capacity growth rates applied to capital cost benchmarks. Forecast inputs incorporated METI efficiency mandate timelines and feed-in-tariff revision schedules.
Practitioners should monitor hydrogen-ammonia co-firing demonstration outcomes and feedstock eligibility codification for early signals of technology inflection. Forecasts reflect assumptions about regulatory continuity and supply chain labor availability that material revisions could invalidate. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Shore Power Market
Power Generation
Oman Power Market
Power Generation
Captive Power Plant Market
Power Generation
Commercial Gensets Market
Power Generation
Tunisia Power Market
Power Generation
Global Power to Gas Market
Power Generation
India Gensets Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Subsea Power Grid System Market
Power Generation
Vietnam Power Generation EPC Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Captive Power Generation Market
Power Generation
India Thermal Power Plant Market
Power Generation
Residential Solar Generator Market
Power Generation
Microturbine Market