
 Brazil Power Plant EPC Market | 2026-2036
Brazil Power Plant EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Power Plant EPC Market Insights
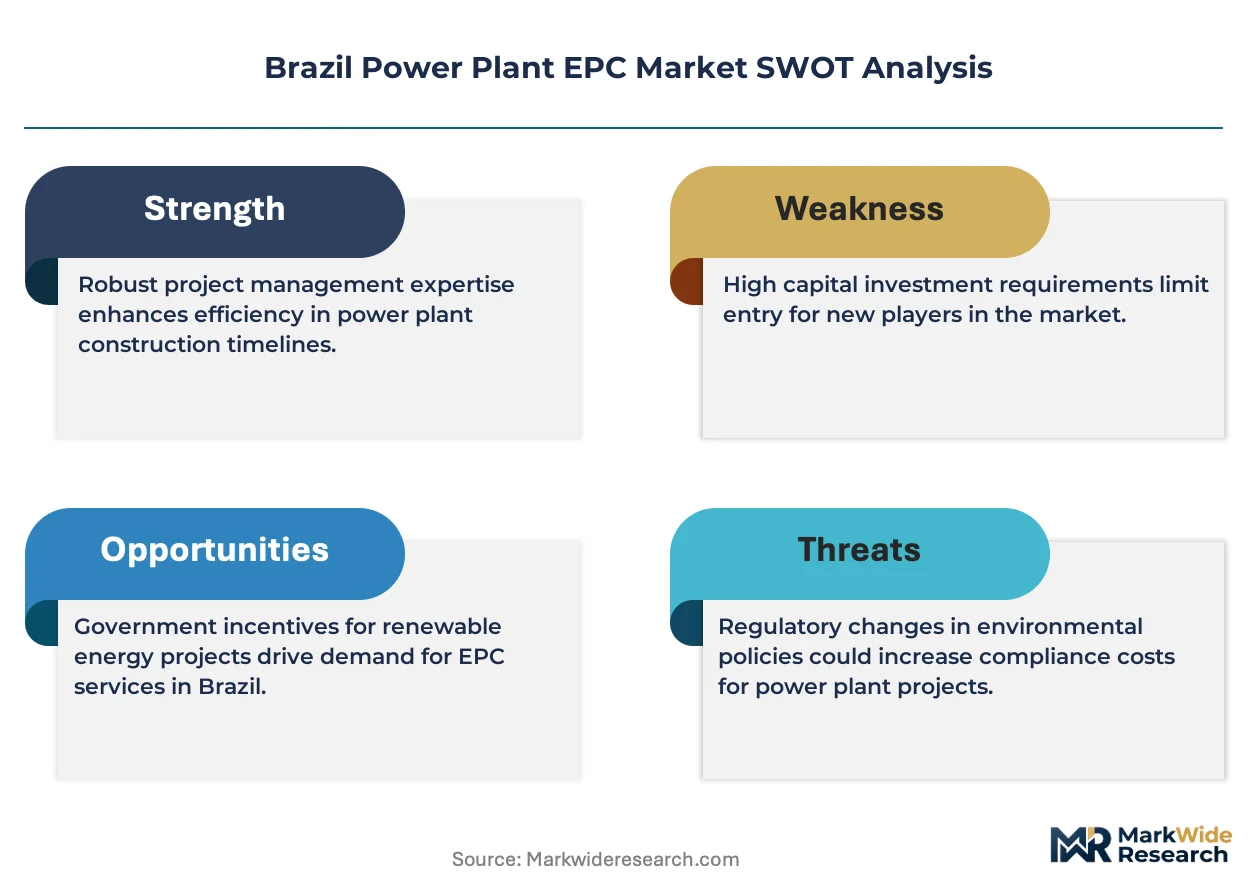
The Brazil power plant EPC sector is consolidating around a widening gap between integrated full-service contracts and fragmented, price-driven bids. Fluor Daniel Brasil leverages its global project management protocols to command premium positioning in complex thermal and combined-cycle builds. Techint Engenharia e Construcao SA anchors heavy civil construction capabilities that sustain its dominance in hydroelectric rehabilitation and greenfield dam projects. Siemens Renewable Energy SA differentiates through digital twin integration and grid-code compliance services that reduce commissioning risk for wind farm developers.
Brazil power plant EPC denotes the complete engineering, procurement, and construction delivery model for electricity generation facilities, spanning feasibility studies, equipment sourcing, civil works, and operational handover with performance guarantees typically tied to output and heat-rate thresholds. The primary purpose is to transfer construction risk from asset owners to contractors while locking in capital expenditure and schedule certainty for projects ranging from 10 MW biomass units to 1,000+ MW combined-cycle gas turbine installations. Construction services capture the largest value pool given Brazil's complex terrain, remote site access, and stringent labor regulations that inflate field execution costs relative to engineering design. Renewable energy sources, particularly wind and solar, represent the fastest-expanding segment as ANEEL auction schedules and corporate power purchase agreements redirect capital from thermal baseload toward variable renewable portfolios. Hydroelectric technology retains structural importance through refurbishment of aging plants commissioned during the 1970s and 1980s, though new large-dam development faces environmental licensing delays that compress contractor margins.
ANEEL, the national electric energy regulator, shapes market access through auction design and grid connection standards that determine which EPC bidders qualify for utility-scale projects. Brazil's environmental licensing framework under IBAMA and state-level environmental agencies adds procedural layers that favor contractors with established permitting track records and in-house environmental compliance teams. Stakeholders must monitor how proposed reforms to Law 14,300 on distributed generation and ongoing transmission expansion auctions under the Ministry of Mines and Energy reroute EPC demand between centralized and decentralized generation architectures.
Market Dynamics
ANEEL's net metering reforms and distributed generation regulations are compressing traditional utility-scale EPC contract structures while accelerating decentralized solar deployment across Brazil's Northeast corridor.
Growth Catalysts
- ANEEL Auction Schedules:Regular capacity auctions under Brazil's national electric energy regulator create predictable procurement pipelines for combined-cycle and renewable EPC contractors.
- Corporate Power Purchase Agreements:Industrial offtakers in Minas Gerais and São Paulo states are bypassing traditional utility intermediaries to contract directly with solar farm developers.
- Biomass Cogeneration:Sugarcane mills in São Paulo's interior are retrofitting bagasse-fired units with higher-efficiency boilers, sustaining EPC demand in thermal rehabilitation.
Market Restraints
- Environmental Licensing Delays:IBAMA and state environmental agencies impose multi-year approval timelines for greenfield hydroelectric dams, eroding contractor margin predictability.
- Specialized Labor Shortages:Brazil's stringent NR-18 labor regulations and confined-space protocols limit the pool of certified welders and high-voltage technicians available for remote site construction.
- Grid Connection Queues:Transmission expansion lags behind generation capacity additions, leaving completed wind farms in Ceará and Rio Grande do Norte stranded without firm dispatch schedules.
Strategic Opportunities
- Distributed Generation Microgrids:Law 14,300 reforms enable commercial and industrial consumers in Pernambuco to aggregate behind-the-meter solar with battery storage, opening sub-10 MW EPC contracts outside traditional auction channels.
- Digital Twin Integration:Convergence of SCADA systems with predictive maintenance platforms allows EPC contractors to offer performance-guaranteed output contracts extending beyond standard commissioning periods.
- Hydroelectric Rehabilitation:Aging plants commissioned during Brazil's 1970s-1980s dam-building era require turbine runner replacements and generator rewinding, creating captive demand for civil-mechanical specialists.
Industry Challenges
- Project Finance Structuring:Local development banks BNDES and Banco do Nordeste impose domestic content requirements that complicate equipment sourcing for international EPC consortiums.
- Supply Chain Reconfiguration:Port congestion at Pecém and Suape delays wind turbine component delivery, forcing contractors to absorb demurrage costs or pre-position inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Power Plant EPC Market |
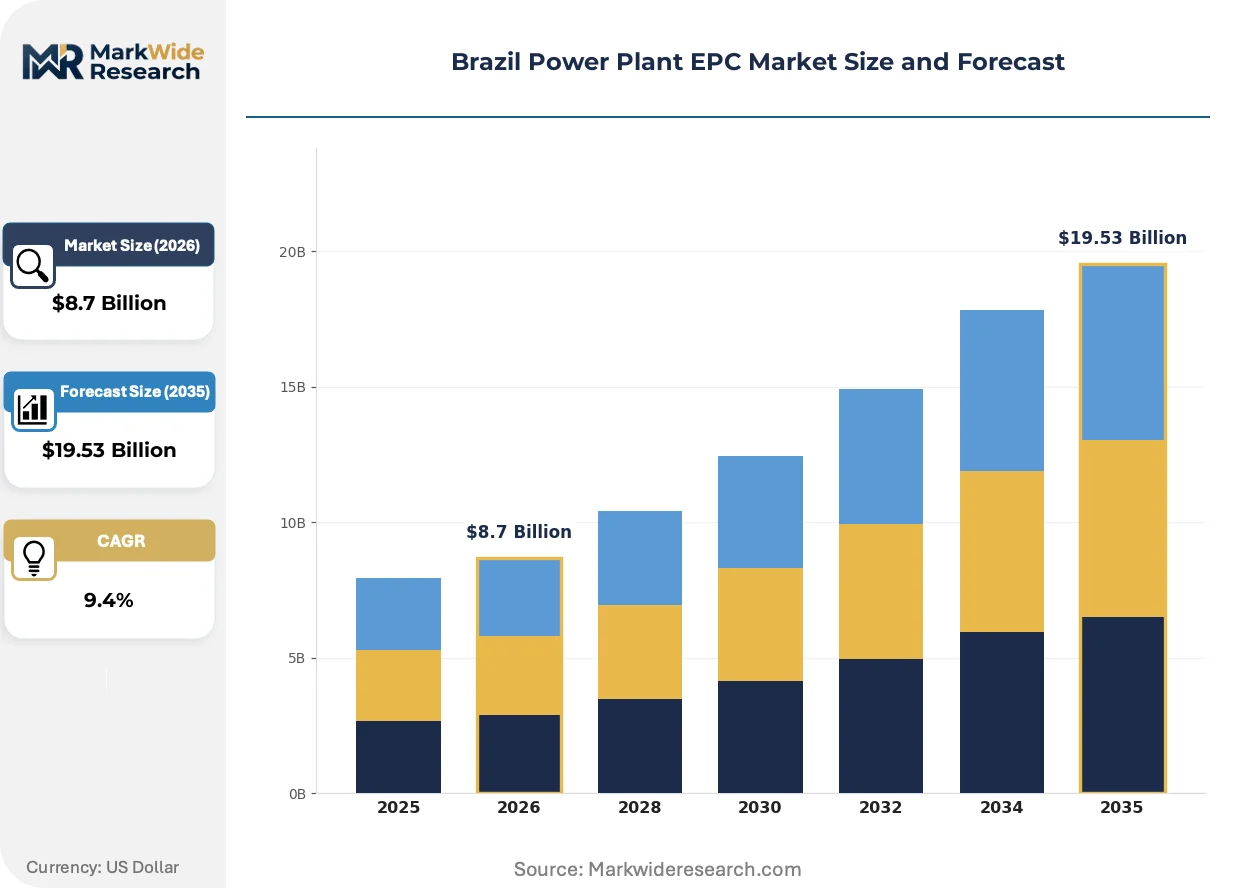
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Commissioning, Maintenance Energy Source: Renewable, Natural Gas, Nuclear, Coal Client Type: Government, Private Sector, Utilities, Independent Power Producers Technology: Thermal, Hydroelectric, Wind, Solar |
| Companies Covered | Fluor Daniel Brasil, General Electric Company, Enel SpA, Canadian Solar Inc., Siemens Renewable Energy SA, Omexom Belo Horizonte, Duro Felguera SA, Techint Engenharia e Construcao SA, Poyry PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Power Plant EPC Market Trends and Innovations
Digitalization of construction workflows and modular assembly methods are compressing field execution timelines for remote renewable sites while reshaping contractor capability requirements.
Modular substation packages with pre-fabricated switchgear and control enclosures are rewriting commissioning protocols for solar farms in Brazil's semi-arid Northeast. IPP developers in Ceará and Piauí are specifying these plug-and-play electrical houses to reduce on-site skilled labor dependence. The technology is compressing grid-connection schedules from eighteen months to under ten months, altering EPC contractor staffing models toward system integration specialists rather than traditional civil construction crews.
ANEEL's revised grid code for distributed generation resources is mandating reactive power capability and voltage ride-through standards that force inverter and transformer specification upgrades. Equipment suppliers must now certify compliance with ONS operational procedures before interconnect approval, adding documentation layers to procurement cycles. Wind farm EPC contracts in Rio Grande do Norte are absorbing these compliance costs through extended commissioning support clauses.
Industrial offtakers are unbundling long-term O&M agreements from initial construction contracts, preferring to tender operational services separately after performance acceptance. Mining and pulp-and-paper companies in Pará and Espírito Santo are driving this bifurcation to retain direct supplier relationships with turbine and panel manufacturers. The pattern concentrates EPC contractor risk into shorter warranty windows while shifting lifecycle revenue to specialized asset managers.
Brazil Power Plant EPC Market Segmentation
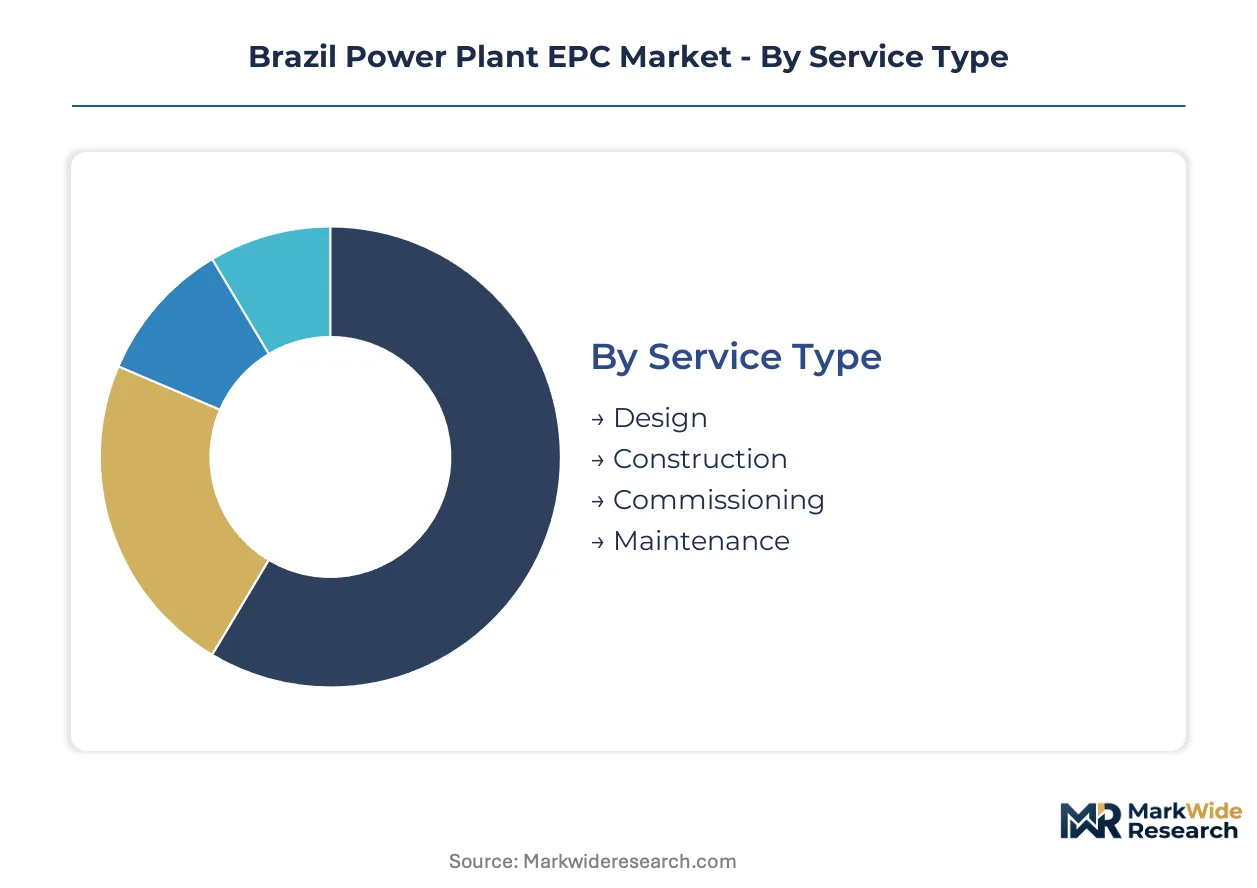
Segmentation in Brazil's power plant EPC market reveals how contract structures and technology choices distribute risk between asset owners and contractors. Each dimension shapes procurement patterns, from ANEEL auction eligibility to financing terms at BNDES.
Service Type:
Standardization dominates basic construction modules, while design and commissioning services demand customization for site-specific grid-code compliance.
- Design:Front-end engineering packages incorporate IBAMA environmental constraints and ONS grid interconnection standards from project inception. ANEEL's evolving distributed generation regulations force iterative revision of electrical single-line diagrams for solar farms in Ceará and Pernambuco.
- Construction:Heavy civil works account for the largest value pool given Brazil's remote site access, complex terrain in Minas Gerais, and stringent NR-18 labor regulations that inflate field execution costs. Northeast wind projects in Rio Grande do Norte concentrate demand for specialized crane operators and high-voltage technicians.
- Commissioning:Performance testing against heat-rate and output guarantees.
- Maintenance:Long-term service agreements extending beyond standard warranty periods.
Most installed capacity flows through Construction. Expansion is steepest in Design as digital twin integration and modular substation specifications gain traction.
Energy Source:
Cost tiers separate mature thermal technologies from capital-intensive nuclear and emerging renewable portfolios competing for auction slots.
- Renewable:Wind and solar EPC contracts dominate new capacity additions, driven by ANEEL auction schedules and corporate power purchase agreements from industrial offtakers in São Paulo. Northeast Brazil's irradiance and wind resources attract IPP developers seeking 20-year fixed-price contracts.
- Natural Gas:Combined-cycle gas turbine installations provide flexible dispatch for grid balancing.
- Nuclear:Limited to Angra 3 completion with specialized containment and reactor vessel sourcing constraints.
- Coal:Restricted to existing plant upgrades given environmental licensing barriers under IBAMA protocols.
Renewable sources capture the majority of new EPC contract value. Natural gas maintains structural importance for reliability services as intermittent generation expands.
Client Type:
Volume concentration varies sharply between auction-driven utilities and decentralized private offtakers pursuing behind-the-meter solutions.
- Government:Federal and state entities procuring through ANEEL auctions with BNDES financing requirements.
- Private Sector:Mining and pulp-and-paper companies in Pará and Espírito Santo tendering direct EPC contracts for captive generation, unbundling construction from long-term O&M to retain supplier relationships.
- Utilities:Incumbent distributors fulfilling regulatory obligations through auction wins.
- Independent Power Producers:Specialized developers aggregating distributed generation portfolios under Law 14,300 reforms.
Private sector clients are diversifying fastest into distributed generation microgrids. Utilities remain the largest contract volume source through centralized auction participation.
Technology:
Maturity curves separate established hydroelectric rehabilitation from rapidly scaling solar and wind deployments.
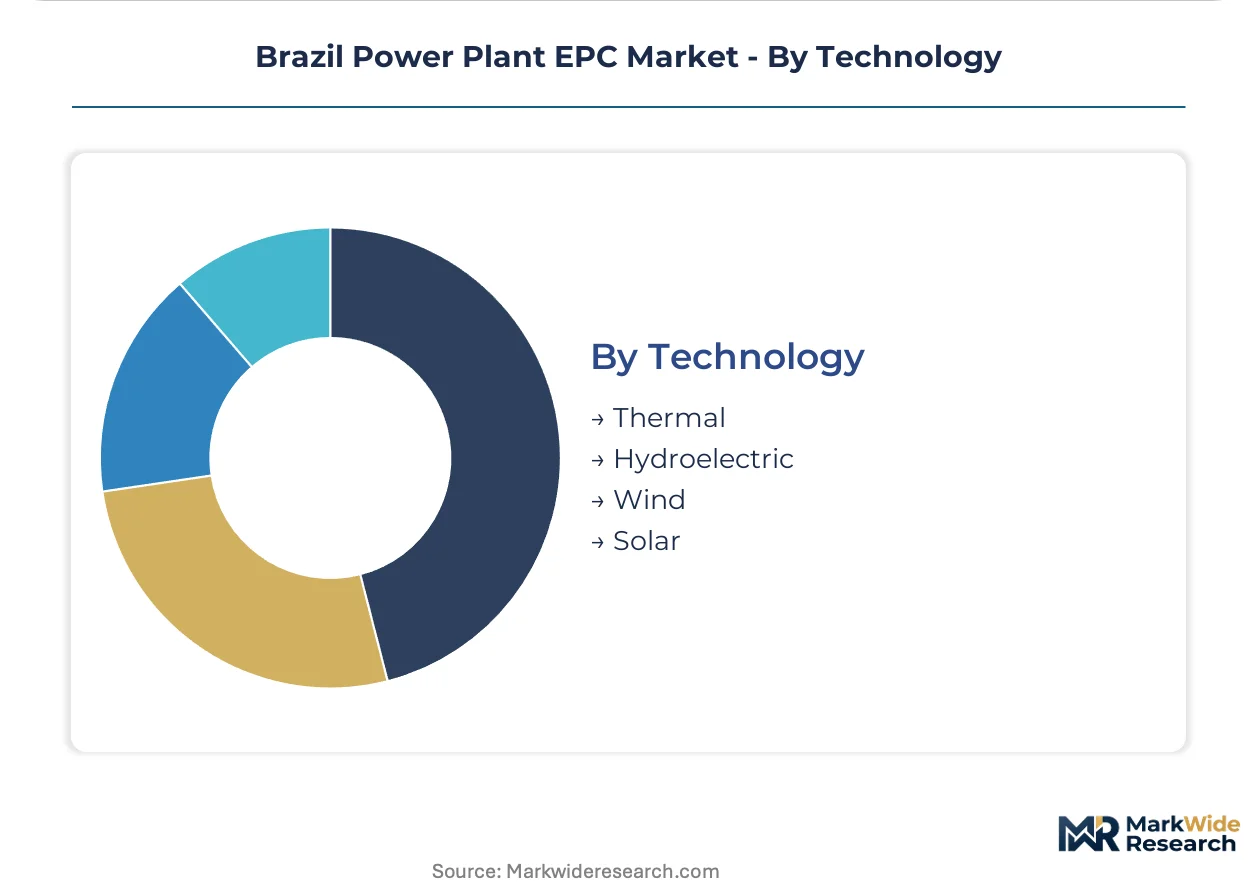
- Thermal:Biomass cogeneration at São Paulo sugarcane mills and combined-cycle upgrades sustain demand for boiler and turbine specialists.
- Hydroelectric:Rehabilitation of 1970s-1980s vintage plants dominates, with turbine runner replacements and generator rewinding creating captive demand for civil-mechanical contractors. Greenfield dam development faces multi-year IBAMA licensing delays.
- Wind:Northeast onshore farms in Ceará and Rio Grande do Norte specify modular substation packages to compress grid-connection timelines.
- Solar:Utility-scale and distributed generation deployments accelerate across the semi-arid Northeast, with pre-fabricated electrical houses reducing on-site labor dependence.
Hydroelectric rehabilitation absorbs the most specialized contractor capacity. Solar represents the steepest expansion trajectory as distributed generation regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding crews and high-voltage technicians concentrate in Brazil's Northeast corridor, drawn by wind farm construction cycles and solar irradiance mapping. This workforce migration patterns EPC contract allocation across state boundaries.
Ceará
Onshore wind clusters in the Ceará interior drive demand for modular substation integration and specialized crane logistics. ANEEL's distributed generation regulations enable commercial aggregators to bypass traditional utility procurement channels. Pecém port congestion forces contractors to pre-position nacelle components, inflating working capital requirements for projects near Trairi and Aracati.
Pernambuco
Behind-the-meter solar deployment accelerates under Law 14,300 reforms targeting industrial consumers in the Suape complex. The state's environmental licensing protocols under CPRH favor contractors with established permitting track records. Grid connection queues at substations near Recife compress EPC completion schedules, shifting contractor risk toward commissioning delays.
Minas Gerais
Combined-cycle gas turbine rehabilitation sustains demand for boiler specialists and heat-recovery steam generator crews. Corporate power purchase agreements from mining and steel operations in the Belo Horizonte corridor redirect capital toward captive generation. BNDES domestic content requirements complicate equipment sourcing for international consortiums bidding on thermal upgrades.
São Paulo
Biomass cogeneration retrofits at sugarcane mills in the interior sustain thermal EPC demand for bagasse-fired boiler replacements. The state's stringent NR-18 labor regulations limit certified welder availability for confined-space construction. Industrial offtakers in the Sorocaba and Piracicaba clusters unbundle long-term O&M agreements from initial construction contracts.
Rio Grande do Norte
Wind farm commissioning faces stranded asset risk where transmission expansion lags behind generation capacity additions. ONS grid-code compliance mandates reactive power capability upgrades for inverter specifications. The Mossoró and Macau sub-regions attract IPP developers seeking 20-year fixed-price auction contracts.
Brazil Power Plant EPC Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Brazil's power plant EPC sector, with integrated full-service contractors commanding premium positioning against fragmented price-driven bidders. The market structure concentrates around three strategic archetypes: global engineering conglomerates leveraging standardized project management protocols, regional civil construction specialists anchoring heavy infrastructure capabilities, and technology-integrated providers bundling digital commissioning services. Competitive moves center on M&A activity consolidating regional permitting expertise and strategic partnerships securing domestic content compliance for BNDES-financed projects.
Within the integrated engineering tier, Fluor Daniel Brasil and Techint Engenharia e Construcao SA exemplify divergent capability positioning—one representing global protocol deployment, the other anchoring localized civil-mechanical execution. Siemens Renewable Energy SA occupies a technology-integrated position, bundling grid-code compliance and digital twin services that reduce commissioning risk for renewable developers. These three entities illustrate how contractor specialization maps to Brazil's bifurcated demand between centralized auction-driven procurement and decentralized distributed generation deployment.
| Leading Market Players |
|---|
| Fluor Daniel Brasil |
| General Electric Company |
| Enel SpA |
| Canadian Solar Inc. |
| Siemens Renewable Energy SA |
| Omexom Belo Horizonte |
| Duro Felguera SA |
| Techint Engenharia e Construcao SA |
| Poyry PLC |
| Others |
Pricing and Supply Chain Analysis
Wind turbine nacelle costs cascade through EPC contract tiers as port congestion at Pecém and Suape inflates inventory carrying charges for contractors serving Ceará and Rio Grande do Norte wind clusters. These logistics premiums compress margins on fixed-price bids while pushing integrated full-service providers toward performance-guaranteed structures that pass through component volatility.
Pricing Analysis
Bundled turnkey contracts command premium positioning against unbundled construction-only bids as IPP developers seek to transfer commissioning risk. Price differentiation hinges on ANEEL auction eligibility track records and in-house environmental compliance capabilities that accelerate IBAMA permitting. Cost compression in standard civil construction runs through aggressive price-driven competition from regional specialists. Mining and pulp-and-paper offtakers in Pará and Espírito Santo exhibit lowest price sensitivity, prioritizing schedule certainty over bid competitiveness.
Supply Chain Analysis
Specialized electrical equipment supply rests on Chinese inverter manufacturers, European transformer producers, and domestic switchgear fabricators facing BNDES domestic content requirements. Critical component dependencies span silicon steel laminations, high-voltage insulators, and SCADA control systems. Single-source vulnerability concentrates in offshore wind turbine generators where pre-positioning at Brazilian ports ties up contractor working capital. Distribution runs through direct procurement by EPC consortia rather than distributor intermediaries, with equipment suppliers maintaining technical service teams at project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through digital twin integration that extends performance guarantees beyond standard commissioning, capturing lifecycle revenue from risk-averse IPP developers.
For Market Incumbents: Lock in permitting track records by acquiring regional environmental consultancies with established IBAMA relationships before licensing timelines compress further. Anchor heavy civil capabilities through captive crane fleets and specialized welding crews certified under NR-18 protocols, defending against price-driven fragmentation from construction-only bidders lacking integrated commissioning expertise. For New Entrants and Emerging Players: Remote monitoring platforms offer a low-capital entry path into distributed generation microgrids under Law 14,300 reforms targeting commercial aggregators in Pernambuco and Ceará. Target behind-the-meter solar deployments for industrial consumers in the Suape complex, where grid connection queues at utility scale create white-space for sub-10 MW EPC contracts outside traditional auction channels. For Investors and Strategic Acquirers: Consolidation pressure builds where environmental licensing delays erode contractor margin predictability and specialized labor shortages under NR-18 constrain execution capacity. Viable acquisition targets include civil-mechanical specialists with hydroelectric rehabilitation expertise and established state-level permitting track records. Watch ANEEL transmission auction schedules as the inflection signal—accelerated grid expansion would unlock stranded wind assets and reroute EPC demand toward centralized generation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Performance-guaranteed output contracts extend revenue capture beyond commissioning into operational phases. |
| Environmental Permitting Acquisition | IBAMA track records compress project timelines and qualify bidders for utility-scale ANEEL auctions. |
| Modular Substation Packaging | Pre-fabricated electrical houses reduce on-site labor dependence and accelerate grid-connection schedules. |
| Specialized Labor Certification | NR-18 compliant welding and high-voltage technician pools defend execution capacity in remote Northeast sites. |
| Distributed Generation Microgrids | Law 14,300 reforms open sub-10 MW contracts outside traditional centralized auction procurement channels. |
Research Methodology
Direct dialogue with EPC project directors, IPP development officers, ANEEL regulatory staff, and BNDES financing specialists grounded qualitative findings in execution-level detail. Secondary validation drew from ANEEL auction databases, ONS grid interconnection records, IBAMA environmental licensing filings, and BNDES domestic content compliance documentation. Bottom-up project pipeline tracking triangulated against top-down capacity addition forecasts across the analysis window.
Top-down macroeconomic drivers and bottom-up project economics converged in a segmented analytical framework spanning energy source, service type, client archetype, and regional grid configuration. CAGRs were derived from installed capacity trajectories, auction schedule densities, and corporate PPA execution rates. Key forecast inputs included ANEEL distributed generation regulatory evolution and transmission expansion auction timelines.
The model assumes a particular technology adoption path; alternative pathways for battery storage integration would alter the outlook for grid-connection risk and EPC contract structures. Forecasts reflect assumptions around environmental licensing timelines, specialized labor availability, and port logistics capacity. A small set of triggers—ANEEL auction design reforms, IBAMA staffing changes, and transmission expansion delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
India Gas Generator Market
Power Generation
Industrial Solar Generator Market
Power Generation
Venezuela Power Market
Power Generation
Power Plant EPC Market
Power Generation
Canada Power EPC Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
LAMEA Microturbine Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Micro CHP Market
Power Generation
India Gensets Market
Power Generation
Power Generation Technologies Market
Power Generation
Retail Electricity Market
Power Generation
Global Power Grid System Market
Power Generation
Peaking Power Plant Market