
 Shore Power Market | 2026-2036
Shore Power Market Size, Share, and Industry Trends Forecast 2026-2036
Shore Power Market Analysis
Cruise liner electrification at berth is shifting the commercial center of shore power demand away from cargo-dominant installations. ABB leverages its vessel-to-grid converter portfolio to anchor Nordic port deployments. Siemens Energy sustains technology leadership through high-voltage direct current shore connection systems. Cavotec SA specializes in automated cable management systems that reduce connection times for frequent-turnaround ferries.
Shore power denotes the supply of electrical energy from land-based grids to vessels at berth, typically delivered at 50 or 60 hertz through high-capacity cable management systems with power ratings spanning low voltage to ultra high voltage. The primary industrial purpose is eliminating auxiliary engine combustion during port stays, thereby cutting particulate matter, nitrogen oxides, and carbon dioxide emissions at dockside. Onshore power supply systems dominate installed base value due to established grid interconnection protocols, while hybrid solutions represent the fastest-expanding category as ports integrate battery buffering to manage peak vessel load without grid reinforcement. Medium voltage installations command the strongest margin pools where specialized switchgear and transformer requirements limit vendor participation.
The EU Green Deal, IMO sulfur regulations, and port-specific emissions controls in Hamburg and Rotterdam collectively mandate shore power availability or penalize conventional berthing. These frameworks shape demand by accelerating retrofit deadlines and conditioning port operating licenses on cold-ironing readiness. Stakeholders must monitor which regulatory tier—EU-wide directive, national transposition, or municipal port authority rule—becomes the binding constraint for their installation timelines.
Market Dynamics
Port electrification mandates are compressing installation timelines as vessel operators face simultaneous pressure from EU Green Deal compliance and municipal cold-ironing ordinances in Hamburg and Rotterdam. This regulatory stacking forces capital deployment decisions before grid reinforcement cycles can complete.
Growth Catalysts
- EU Green Deal port electrification mandates:Binding 2030 deadlines for onshore power availability at major berths in Germany, Norway, and the Netherlands accelerate retrofit procurement cycles for terminal operators.
- Cruise liner cold-ironing expansion:Passenger vessel operators are expanding shore power infrastructure at Mediterranean and Baltic berths to meet corporate sustainability targets and port access conditions.
- IMO 2020 sulfur cap enforcement:The International Maritime Organization's fuel sulfur limits push vessel operators toward shore power as a compliance pathway for emissions reduction at dockside.
Market Restraints
- Grid reinforcement cost volatility:Copper and transformer core material price swings distort project economics for medium voltage shore connection installations in Nordic ports.
- Specialized switchgear supply concentration:European transformer and switchgear fabrication capacity limits create bottlenecks for ultra high voltage shore power system delivery.
- Harbor space constraints:Dense port layouts in Rotterdam and Hamburg restrict cable management system footprint, forcing customized engineering that extends deployment timelines.
Strategic Opportunities
- Hybrid battery-buffered shore power:Ports in Norway are integrating lithium-ion storage to manage peak vessel load without awaiting grid upgrades, creating faster deployment pathways.
- Ferry rapid-turnaround automation:Automated cable management systems for short-haul ferry routes in the Netherlands reduce connection times and expand addressable vessel classes.
- EU Emissions Trading System maritime inclusion:Carbon pricing for shipping creates direct financial incentive for shore power adoption as a measurable emissions reduction mechanism.
Industry Challenges
- Marine electrical engineering talent scarcity:Specialized skills for high-voltage vessel-to-grid integration are concentrated among aging workforces in German and Norwegian port engineering consultancies.
- Multi-stakeholder coordination complexity:Grid operators, port authorities, and vessel classification societies maintain incompatible technical standards that delay commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shore Power Market |
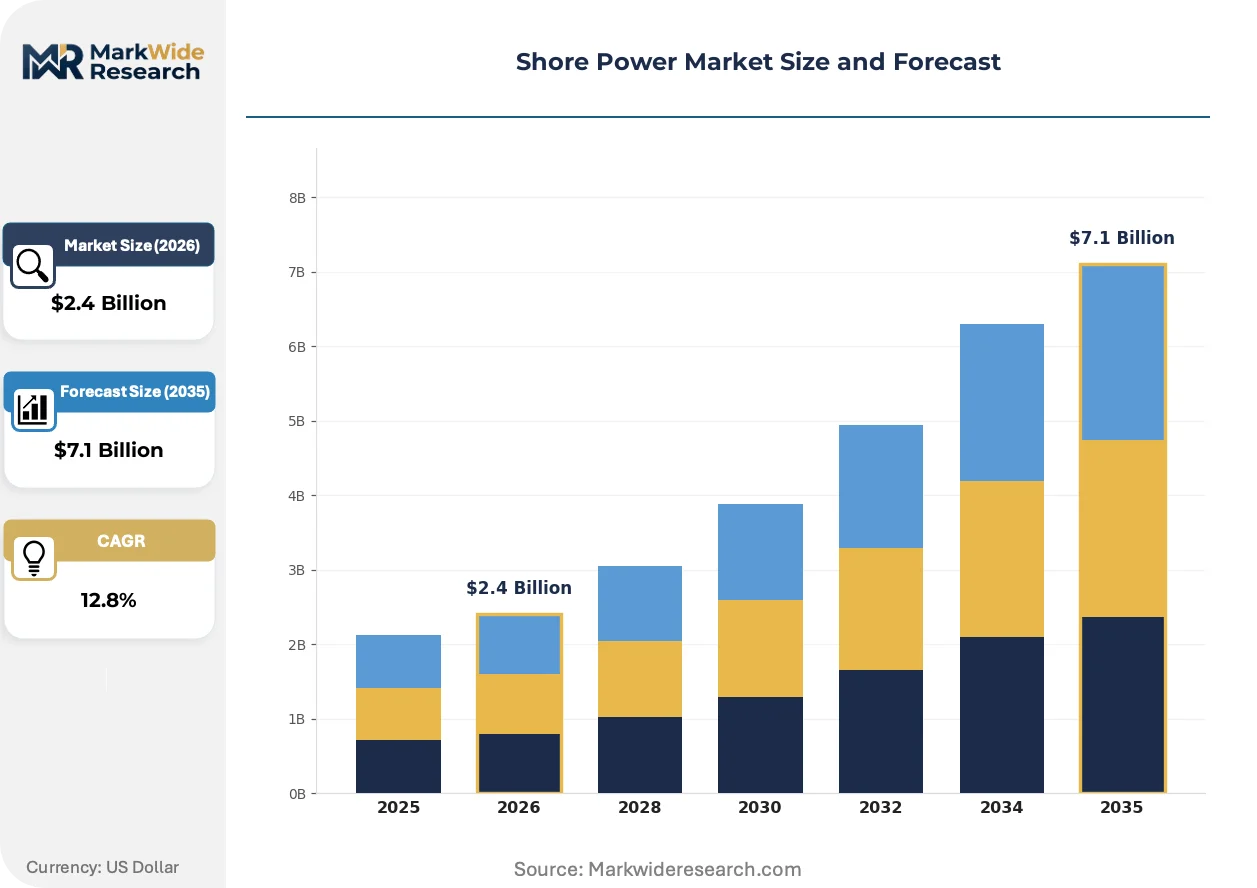
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.1 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Power Supply, Renewable Energy Systems, Hybrid Solutions, Electric Power Generators Application: Marine Vessels, Cargo Ships, Ferries, Cruise Liners Power Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Installation: Fixed Systems, Mobile Solutions, Retrofit Installations, Integrated Platforms |
| Companies Covered | Schneider Electric, Eaton, ABB, Danfoss, Wartsila, Siemens Energy, Cavotec SA, ESL Power Systems, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shore Power Market Emerging Trajectories
Shore power infrastructure is evolving from static grid connections toward intelligent, buffered systems that manage vessel load variability without demanding immediate utility-scale reinforcement. This shift reconfigures vendor competitive positioning around energy storage integration and automation.
Medium voltage direct current shore connection technology is converging with vessel-side battery energy storage systems. Ferry operators in Norway are deploying DC microgrid architectures that eliminate conversion losses and reduce connection times. This convergence is compressing the traditional separation between shore-side power delivery and vessel-side energy management, forcing converter vendors to expand into integrated system offerings.
The EU Green Deal's port electrification timelines are tightening municipal operating license conditions in Hamburg, Rotterdam, and Antwerp. Terminal operators now face penalties for conventional berthing without cold-ironing infrastructure. Cruise and container segments are responding by front-loading capital commitments to secure installation slots ahead of 2030 compliance deadlines.
Charter contract structures are incorporating shore power availability clauses that displace traditional fuel surcharge negotiations. Container lines operating Baltic routes are prioritizing terminal selection based on confirmed high-voltage connection capability. This preference shift is most visible in German port procurement, where Hamburg and Bremerhaven compete for volume through accelerated electrification investment.
Shore Power Market Segmentation
Shore power procurement decisions split across vessel-specific load profiles and port infrastructure constraints. Terminal operators weigh connection frequency, peak demand cycles, and grid reinforcement timelines when selecting system configurations.
Product Type:
Port authorities prioritize total cost of ownership over upfront capital, driving divergence between established grid-tied systems and emerging buffered architectures.
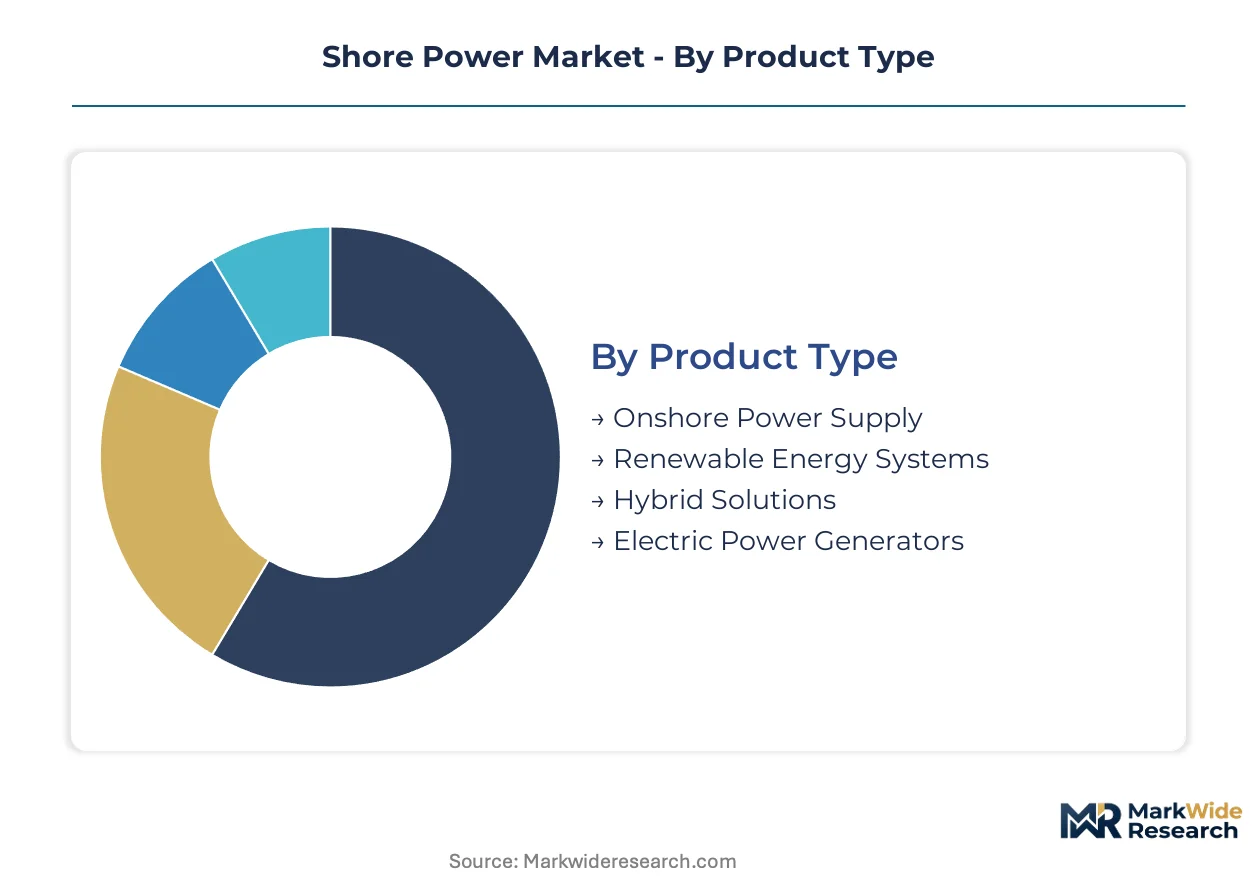
- Onshore Power Supply:Conventional land-to-vessel electrical delivery through high-capacity cable management and transformer infrastructure. Demand concentrates at Hamburg and Rotterdam container terminals where EU Green Deal mandates enforce cold-ironing availability.
- Hybrid Solutions:Battery-buffered shore connections that store grid energy to manage vessel load spikes without utility reinforcement. Norwegian ferry operators are deploying these systems fastest where grid upgrade timelines conflict with 2030 compliance deadlines.
- Renewable Energy Systems:Direct solar or wind-to-vessel architectures with on-site generation. Port of Kiel pilots this technology for cruise terminal operations.
- Electric Power Generators:Mobile or fixed generator sets providing auxiliary power where grid connections remain unavailable. Baltic secondary ports deploy these as interim compliance measures.
Volume sits with Onshore Power Supply; growth tilts toward Hybrid Solutions.
Application:
Vessel operational patterns dictate connection frequency and power rating requirements, creating distinct procurement specifications across maritime segments.
- Cargo Ships:Container and bulk carriers with extended berth durations requiring sustained high-capacity power delivery. German terminal operators at Bremerhaven are retrofitting crane-fed connections for 20,000 TEU vessel classes.
- Cruise Liners:Passenger vessels with hotel-load demands exceeding propulsion requirements during multi-day port stays. Mediterranean berth expansions in Barcelona and Civitavecchia prioritize these installations for corporate sustainability reporting.
- Ferries:Short-haul vessels with rapid turnaround cycles demanding automated connection systems. Dutch operators in the Wadden Islands are standardizing 15-minute connection protocols.
- Marine Vessels:General category encompassing offshore support, tug, and specialized craft with intermittent shore power needs. Norwegian offshore bases are expanding coverage for supply vessel fleets.
Procurement volume clusters around Cargo Ships; installation velocity is climbing fastest for Cruise Liners.
Power Rating:
Grid interconnection capacity and vessel electrical architecture determine voltage tier selection, with higher ratings commanding specialized switchgear and extended lead times.
- Medium Voltage:1-35 kV systems serving large commercial vessels through dedicated substations. Rotterdam Maasvlakte terminals specify these for ultra-large container carriers requiring 10+ MW sustained delivery.
- Ultra High Voltage:Systems exceeding 35 kV for the largest cruise and container vessels with integrated propulsion. Limited European transformer fabrication capacity creates procurement bottlenecks for Hamburg's Elbe River expansion.
- Low Voltage:Standard 400V-690V connections for smaller craft and auxiliary loads. Widespread at Mediterranean yacht marinas and fishing harbors.
- High Voltage:35 kV-class systems bridging medium and ultra-high voltage applications. Baltic cruise terminals are standardizing this tier for next-generation vessel compatibility.
Medium Voltage captures current installation value; Ultra High Voltage is gaining share fastest as vessel sizes escalate.
Installation:
Harbor spatial constraints and existing electrical infrastructure determine deployment architecture, with retrofit timelines compressing against regulatory deadlines.
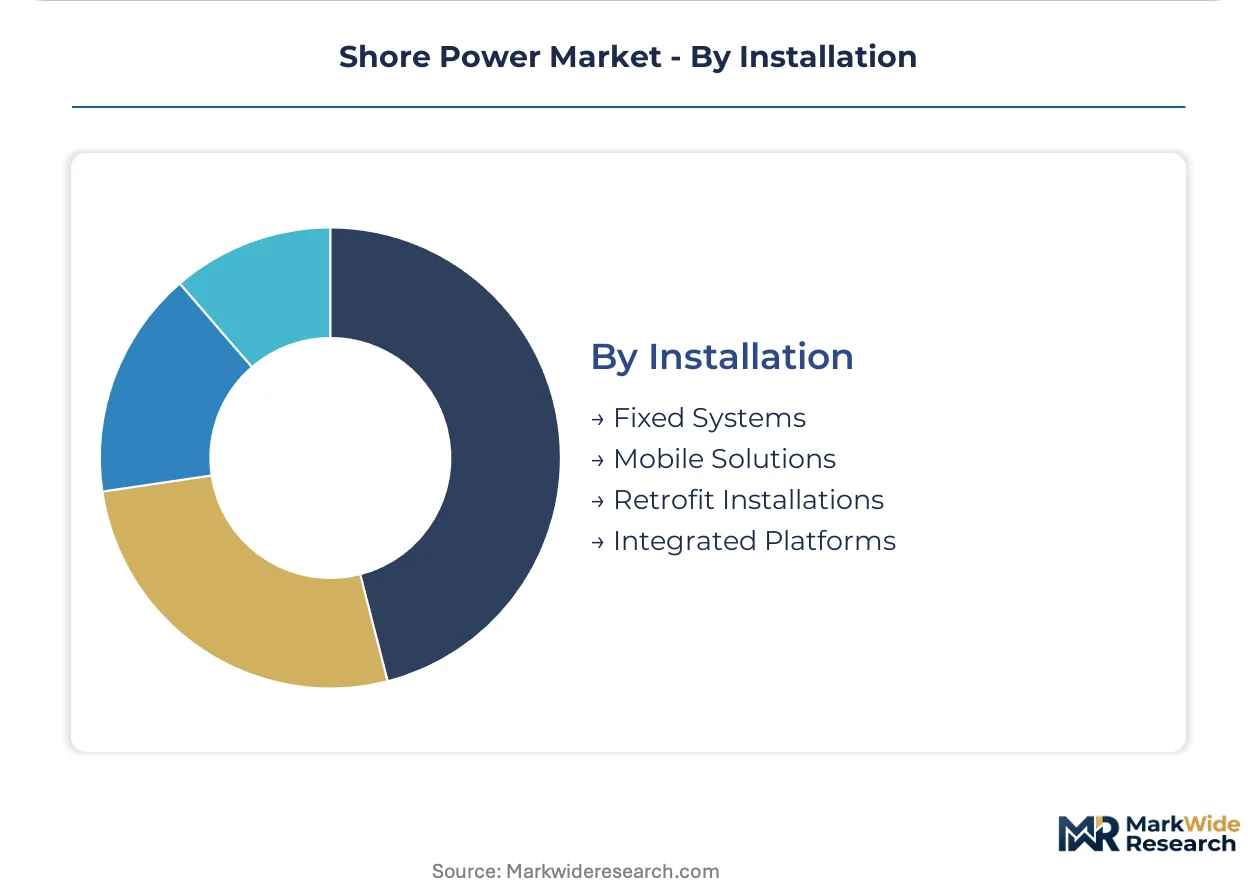
- Fixed Systems:Permanent shore-side infrastructure with dedicated cable management and transformer housing. Antwerp's Deurganck dock exemplifies greenfield deployment of this architecture.
- Retrofit Installations:Adaptation of existing berth electrical infrastructure for vessel-to-grid compatibility. Dense Hamburg harbor layouts force customized engineering that extends these project timelines.
- Mobile Solutions:Containerized or trailer-mounted systems repositionable across multiple berths. Port of Oslo deploys these for seasonal cruise traffic variations.
- Integrated Platforms:Combined shore power and vessel charging systems for hybrid-electric fleets. Norwegian fjord tourism operators are piloting these for zero-emission route segments.
Fixed Systems dominate capital deployment; Retrofit Installations are expanding most quickly as compliance deadlines approach existing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port electrification incentives in the EU Green Deal framework are concentrating shore power deployment capital in Northern European maritime clusters. Tax-advantaged infrastructure zones in Germany, Norway, and the Netherlands are accelerating cold-ironing timelines ahead of 2030 mandates.
Germany
Hamburg and Bremerhaven container terminals drive procurement volume for ultra-large vessel connections. The EU Green Deal's binding port electrification deadlines force terminal operators into retrofit cycles before grid reinforcement completes. Elbe River expansion projects concentrate engineering demand for specialized switchgear and transformer systems.
Norway
Ferry operators in the Oslofjord and Western Fjord regions are deploying battery-buffered shore connections to bypass grid upgrade delays. National emissions reduction targets for maritime transport accelerate hybrid system adoption. Norwegian port authorities in Bergen and Stavanger are standardizing rapid-connection protocols for short-haul fleets.
Netherlands
Rotterdam Maasvlakte terminals specify medium-voltage systems for next-generation container carriers. Municipal cold-ironing ordinances in Rotterdam and Amsterdam condition operating licenses on shore power availability. Wadden Islands ferry routes are piloting automated cable management for sub-15-minute turnaround cycles.
United States
California Air Resources Board regulations at Los Angeles and Long Beach ports mandate shore power for container and cruise vessels. EPA port emissions standards drive retrofit investment in Pacific Northwest terminals. Seattle and Tacoma harbor districts are expanding high-voltage infrastructure for Alaska cruise routes.
China
Yangtze River Delta ports in Shanghai and Ningbo are scaling shore power for domestic container trade under national dual carbon goals. Ministry of Ecology and Environment port emissions guidelines push terminal electrification. Shenzhen's Pearl River Delta cluster is integrating shore power with terminal automation systems.
Shore Power Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding premium positioning in high-voltage installations while component suppliers serve price-sensitive retrofit markets. The competitive structure tilts toward consolidation at the top tier, where converter and switchgear capabilities create entry barriers. Three archetypes dominate: full-system integrators with vessel-to-grid portfolios, specialized cable management automation firms, and electrical infrastructure conglomerates with port-sector divisions. Capacity expansion and technology licensing represent the primary competitive vectors as vendors race to secure 2030 compliance-driven installation slots.
Among European electrical infrastructure conglomerates, ABB, Siemens Energy, and Schneider Electric occupy positions across the voltage spectrum. ABB exemplifies the integrated system archetype through its vessel-to-grid converter focus. Siemens Energy anchors high-voltage direct current shore connection development. Schneider Electric represents the diversified industrial electrification approach, leveraging broad switchgear and distribution expertise. These three firms sit within the premium tier where specialized engineering capabilities limit competitor participation.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton |
| ABB |
| Danfoss |
| Wartsila |
| Siemens Energy |
| Cavotec SA |
| ESL Power Systems |
| General Electric Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal port electrification mandates gate qualified supply and premium-tier pricing access, restricting vendor participation to firms with certified high-voltage converter portfolios while compressing procurement timelines for terminal operators facing 2030 compliance deadlines.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent retrofit projects commanding premium placement fees from standard-cycle installations with extended delivery windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from copper and transformer core material volatility distorting project economics. Cargo terminal operators at Rotterdam Maasvlakte exhibit lowest price sensitivity due to regulatory penalty exposure, while Baltic secondary ports prioritize economy-tier mobile generator solutions.
Supply Chain Analysis
Specialized marine electrical engineering talent scarcity in German and Norwegian fabrication centers constrains transformer and switchgear production capacity. Supply concentrates in Germany, Norway, and the Netherlands for high-voltage converter systems, with China anchoring cable management component manufacturing. Raw material dependencies encompass copper conductors, silicon steel transformer cores, and lithium-ion battery cells for hybrid architectures. Single-source vulnerability around European ultra-high-voltage switchgear fabrication creates procurement bottlenecks. Distribution runs through EPC contractors and port engineering consultancies serving terminal operators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as regulatory compliance deadlines force capital deployment decisions before weaker vendors can secure installation slots.
For Market Incumbents: Anchor market position through backward integration into transformer core material supply and captive marine electrical engineering talent development. ABB, Siemens Energy, and Schneider Electric should expand Norwegian and German fabrication capacity to capture 2030 deadline-driven procurement. Certification investment in EU Green Deal-compliant system portfolios creates switching costs for terminal operators. For New Entrants and Emerging Players: The mid-tier price-point gap between ABB's integrated systems and economy-tier mobile generators offers white-space entry. Target Wadden Islands ferry automation and Baltic secondary port retrofit segments where incumbent footprint remains limited. Partner with Norwegian battery system integrators to accelerate hybrid solution deployment without full converter development. For Investors and Strategic Acquirers: Norwegian port authority announcement of rapid-connection protocol standardization is the leading indicator that battery-buffered hybrid architectures will dominate ferry segment procurement. Five-to-ten-year viability favors acquisition of specialized cable management automation firms with marine certification. Monitor EU Emissions Trading System maritime inclusion timeline as inflection signal for carbon-price-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transformer Manufacturing | German and Norwegian vendors secure silicon steel supply chains against commodity volatility. |
| Battery-Buffered Hybrid System Launch | Norwegian ferry operators bypass grid reinforcement delays while meeting 2030 compliance. |
| Rapid-Connection Protocol Standardization | Dutch Wadden Islands routes reduce vessel turnaround below fifteen minutes. |
| Marine Electrical Engineering Talent Acquisition | Specialized high-voltage integration skills concentrate among aging German and Norwegian workforces. |
| EU Green Deal Certification Investment | Terminal operators face operating license penalties without cold-ironing infrastructure. |
Methodological Framework
Document review covered EU regulatory filings, port authority procurement databases, and vessel classification society technical standards, complemented by interviews with terminal operations directors, marine electrical engineering consultants, grid interconnection planners, and shore power system procurement managers. Secondary validation drew from customs trade data, SEC 10-K infrastructure disclosures, and national maritime emissions reports. Bottom-up installation volume estimates triangulated against top-down regulatory mandate timelines.
Cross-referencing historical deployment patterns with expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass product type, vessel application, power rating tier, installation architecture, and regional regulatory cluster. CAGRs were derived from mandated compliance deadline pacing and vessel fleet turnover schedules. Forecast inputs incorporated grid reinforcement cycle timelines and lithium-ion battery cost trajectories for hybrid system penetration.
Inputs from port authority procurement officers and EPC contractors were available through the study window; gaps in confidential vessel operator capex planning introduce uncertainty bands around cruise liner segment projections. Forecasts reflect assumptions regarding EU Green Deal transposition consistency and municipal ordinance enforcement intensity. Material deviation in Norwegian battery system integration timelines or German transformer fabrication capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Micro CHP Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Global Power Generation Market
Power Generation
North America Distributed Power Generation Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Distributed Power Generation Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Europe Thermal Power Market
Power Generation
South America Thermal Power Market
Power Generation
Commercial Gensets Market
Power Generation
United Kingdom Power Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Venezuela Power Market