
 Micro CHP Market | 2026-2036
Micro CHP Market Size, Share, and Industry Trends Forecast 2026-2036
Micro CHP Market Analysis
Commercial property developers is redrawing procurement priorities for micro CHP systems as energy security concerns reshape building infrastructure planning. Viessmann Group leverages its established boiler distribution channels to bundle micro CHP units with conventional heating hardware. Yanmar Holdings anchors its position through compact gas engine designs purpose-built for Asian commercial building footprints. Ceres Power differentiates via solid oxide fuel cell technology that achieves electrical efficiencies above 50 percent in sub-megawatt installations.
Micro combined heat and power refers to decentralized generation systems typically rated below 50 kW electrical output that simultaneously produce usable heat and electricity from a single fuel source, achieving total system efficiencies of 80 to 90 percent through thermal recovery. Fuel cell variants employ electrochemical conversion rather than mechanical combustion, eliminating nitrogen oxide emissions and enabling sub-ppm pollutant profiles critical for dense urban deployment. Gas engine configurations currently dominate installed capacity across European residential retrofits, though fuel cell segments command premium pricing in markets with aggressive carbon intensity benchmarks. Stirling engine systems occupy niche positions where acoustic footprint restrictions exclude reciprocating machinery from noise-sensitive institutional settings.
Germany's KBA and BAFA administer efficiency-linked equipment subsidies that directly influence micro CHP payback calculations for multi-family building owners. The EU F-Gas Regulation and national implementations across France, Italy, and the Netherlands progressively constrain refrigerant-based thermal technologies, redirecting capital toward combustion and electrochemical alternatives. Japan's METI residential fuel cell program demonstrates how sustained tariff support can manufacture demand scale independent of grid parity dynamics. Stakeholders must monitor how building efficiency codes in key jurisdictions redefine the economic boundary between standalone micro CHP and district heating interconnection.
Market Dynamics
The Micro CHP Market pivots on building efficiency codes that recalibrate the economic boundary between standalone distributed generation and district heating interconnection, forcing equipment manufacturers to optimize for retrofit compatibility rather than greenfield specifications.
Growth Catalysts
- Germany's KBA and BAFA efficiency-linked subsidies:These frameworks compress payback periods for multi-family building owners, accelerating gas engine system deployment across residential cooperatives in Berlin and Hamburg retrofit clusters.
- Stirling engine acoustic advantages:Noise-sensitive institutional settings in Dutch university campuses and Danish hospitals specify these systems where reciprocating machinery faces exclusion, creating protected niche demand.
- Japan's METI residential fuel cell tariff support:Sustained subsidy structures manufacture demand scale independent of grid parity dynamics, channeling investment toward solid oxide and polymer electrolyte membrane configurations.
Market Restraints
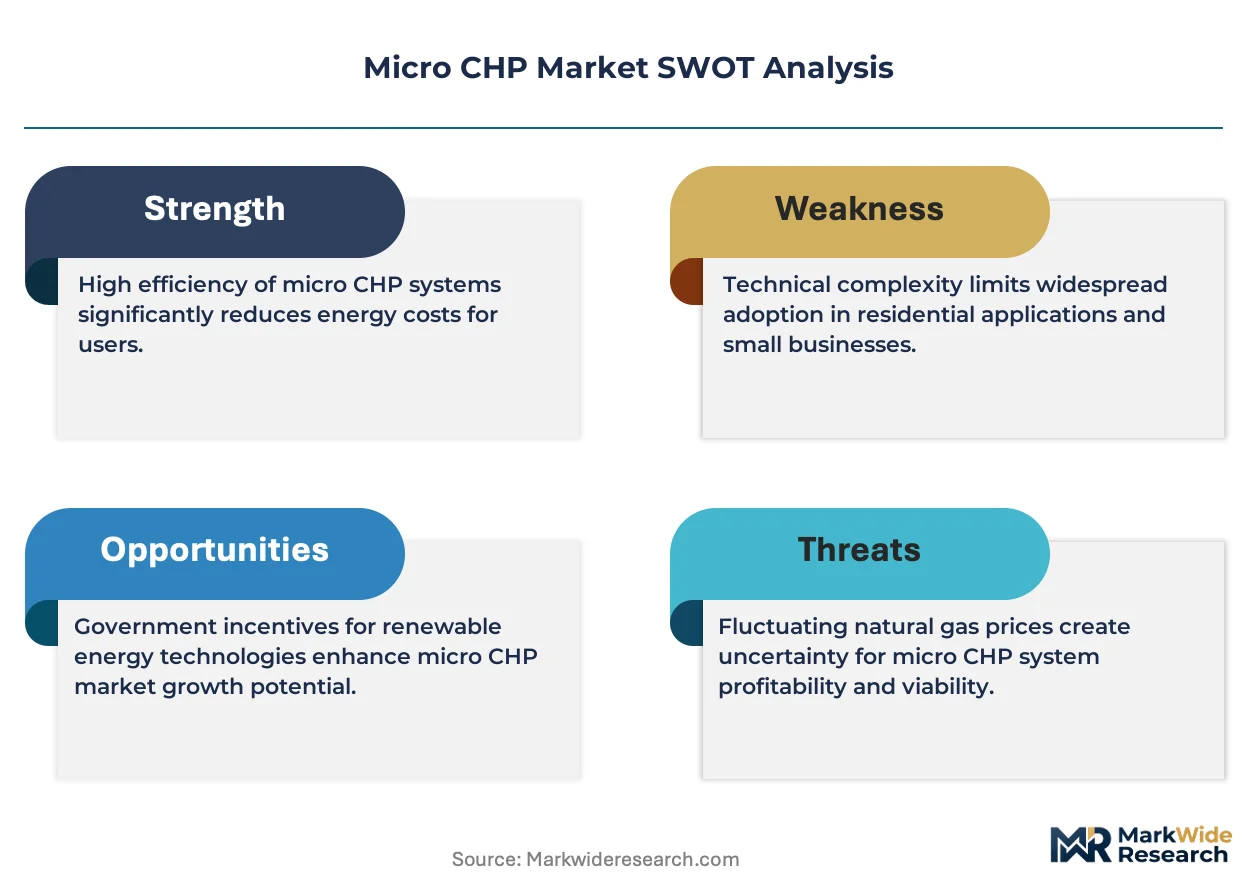
- Platinum group metal cost volatility:Fuel cell stack manufacturing depends on iridium and ruthenium catalysts subject to South African and Russian supply concentration, compressing margins during commodity spikes.
- EU F-Gas Regulation refrigerant constraints:Progressive phase-down of hydrofluorocarbon-based thermal technologies limits heat pump alternatives but also creates installation complexity for hybrid micro CHP-heat pump configurations.
- Lithium-ion battery substitution:Behind-the-meter storage paired with rooftop solar achieves comparable energy arbitrage for residential prosumers without thermal output requirements, eroding addressable market in mild climates.
Strategic Opportunities
- Polish district heating interconnection gaps:Legacy coal-dependent municipal networks in Kraków and Wrocław face decarbonization mandates, creating retrofit openings for gas engine micro CHP as bridge technology.
- Electrolyzer-fuel cell convergence:Power-to-gas installations enable hydrogen-fed solid oxide systems to operate as reversible units, expanding revenue streams through grid balancing services.
- Utility-led equipment leasing channels:E.ON and EnBW pilot programs remove upfront capital barriers for apartment building associations, shifting procurement from asset purchase to opex-based contracts.
Industry Challenges
- Fuel cell stack certification timelines:TÜV Rheinland and Kiwa testing protocols for solid oxide systems require 18-24 month validation cycles, delaying product launches and freezing engineering specifications.
- Legacy boiler integration complexity:Viessmann and Buderus control architectures use proprietary communication protocols, forcing third-party micro CHP manufacturers to develop expensive gateway interfaces for hydraulic compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro CHP Market |
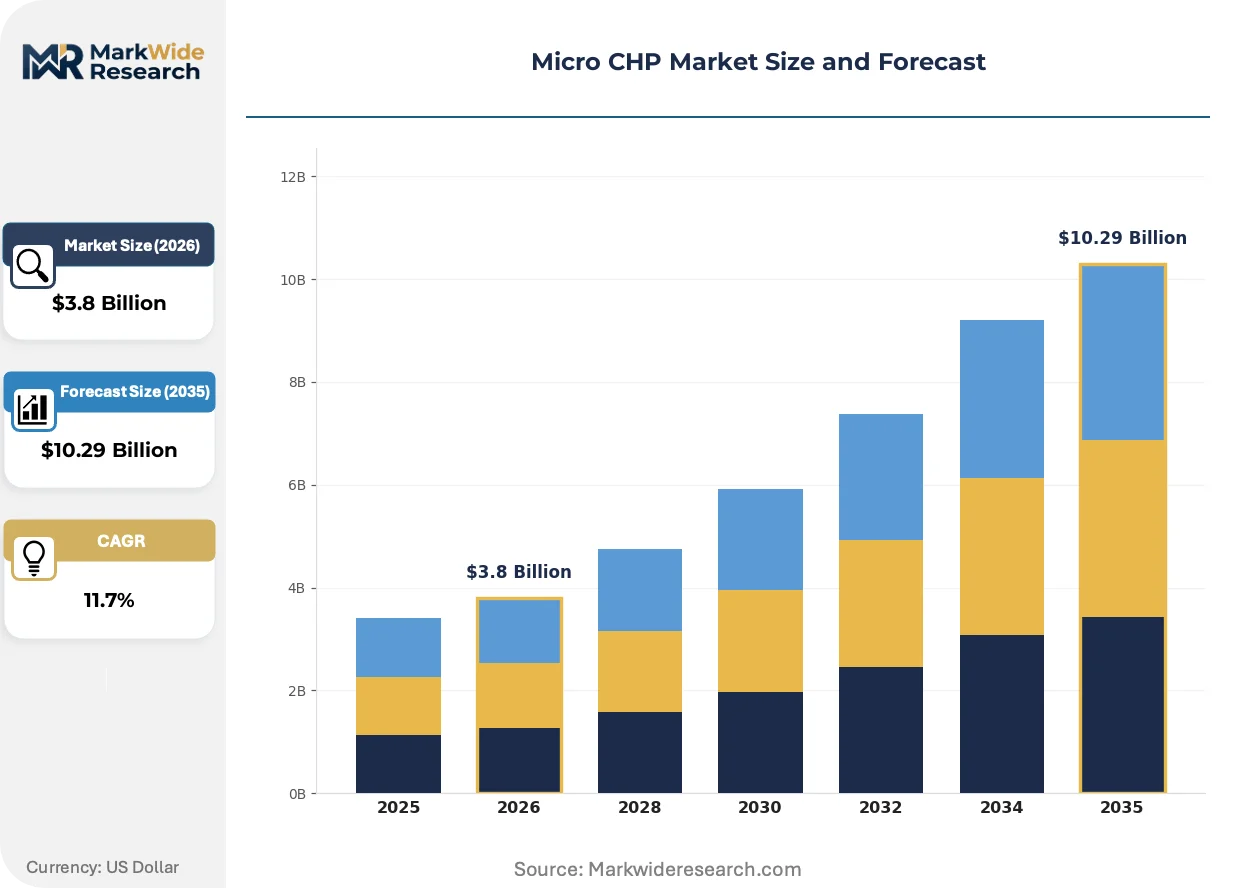
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Engines, Stirling Engines, Fuel Cells, Micro Turbines End User: Residential, Commercial, Industrial, Institutional Technology: Reciprocating, Thermoelectric, Combined Heat and Power, Renewable Installation: On-site, Multi-family Units, Standalone, Integrated Systems |
| Companies Covered | Viessmann Group, Yanmar Holdings, Vaillant Group, BDR Thermea Group, 2G Energy, AISIN Corporation, Panasonic Corporation, EC Power, Ceres Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro CHP Market Emerging Trajectories
Electrochemical conversion architectures are displacing mechanical combustion across premium urban installations, while regulatory tightening on nitrogen oxide emissions accelerates technology substitution in dense European housing stock.
Solid oxide fuel cell technology achieves electrical efficiencies above 50 percent in sub-megawatt installations through ceramic electrolyte operation at 700-800°C. Commercial property developers in Frankfurt and Munich specify these systems for new multi-family construction where carbon intensity benchmarks exclude gas engine alternatives. This performance tier is displacing premium reciprocating machinery from flagship urban projects, compressing addressable volume for conventional suppliers.
The EU F-Gas Regulation and national implementations across France, Italy, and the Netherlands progressively constrain refrigerant-based thermal technologies. This regulatory architecture redirects capital toward combustion and electrochemical alternatives while complicating hybrid system designs that combine heat pumps with micro CHP backup. Northern European retrofit clusters respond by prioritizing fuel cell configurations with sub-ppm pollutant profiles that preempt local air quality objections.
Building energy management system integration now determines equipment selection for multi-family developers. Automated demand response protocols require open Modbus or BACnet interfaces that legacy gas engine controllers often lack, forcing procurement teams toward newer fuel cell platforms with native IoT architectures. This specification shift is most visible in Dutch social housing corporation tenders, where centralized monitoring capabilities carry weighted scoring premiums.
Micro CHP Market Segmentation
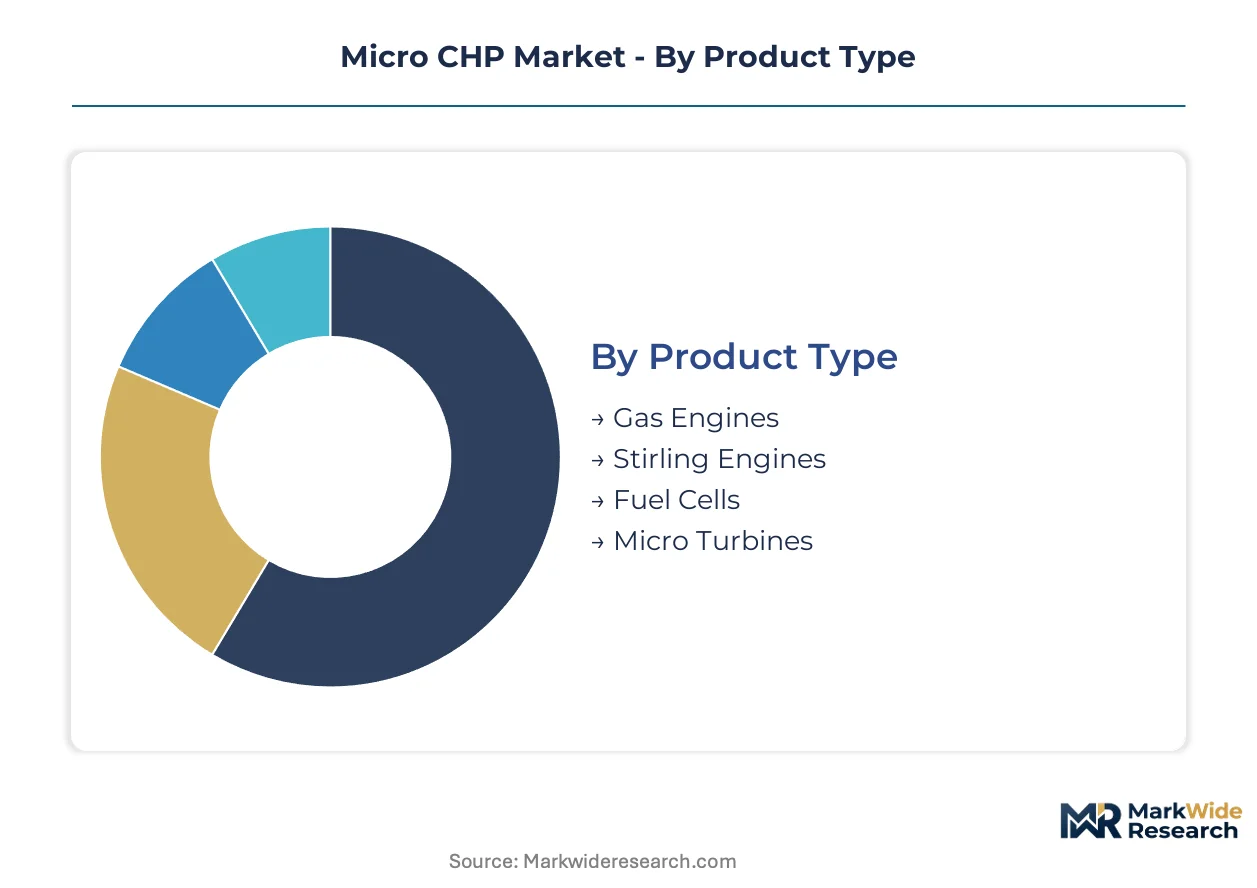
Segmentation in the Micro CHP Market reveals how technology choices map to distinct economic boundaries and regulatory environments. Equipment specifications diverge sharply between residential retrofits requiring acoustic compliance and commercial installations prioritizing electrical efficiency.
Product Type:
Gas engines dominate German and Polish domestic installations where established service networks reduce operational risk. Fuel cells command premium positioning in Japanese residential programs and Dutch urban clusters with stringent emissions ceilings.
- Gas Engines:Reciprocating internal combustion configurations achieve 25-35% electrical efficiency through spark-ignited natural gas operation. Demand concentrates in Berlin and Hamburg multi-family retrofits where KBA subsidy eligibility hinges on proven efficiency thresholds. BAFA equipment incentives compress payback periods below seven years for cooperative housing associations.
- Fuel Cells:Solid oxide and polymer electrolyte membrane variants electrochemically convert fuel without mechanical combustion, eliminating nitrogen oxide emissions entirely. METI tariff support in Japan sustains deployment scale independent of grid parity; Frankfurt developers specify these for new construction exceeding carbon intensity benchmarks. Platinum group metal costs in stack manufacturing create margin vulnerability during commodity spikes.
- Stirling Engines:External combustion with closed-cycle gas displacement operates below 70 dB acoustic footprint, satisfying Dutch university campus specifications where reciprocating machinery faces exclusion.
- Micro Turbines:Radial flow compressor-turbine combinations suit industrial process heat applications requiring exhaust temperatures above 500°C.
Gas engines hold the largest share; momentum sits with fuel cells.
End User:
Cost tier stratification separates premium commercial specifications from standardized residential packages. Institutional procurement emphasizes lifecycle operating cost over capital expenditure.
- Residential:Single-family and multi-family installations below 50 kW electrical output constitute the volume base. Northern European retrofit clusters in Denmark and the Netherlands drive replacement cycles for aging boiler infrastructure.
- Commercial:Office buildings and retail complexes in Munich and Frankfurt specify solid oxide systems for new construction where local air quality regulations exclude combustion alternatives. Electrical efficiencies above 50% justify premium capital outlay through reduced grid import dependency.
- Industrial:Small-scale manufacturing facilities with continuous thermal demand profiles achieve optimal capacity utilization factors.
- Institutional:Hospitals and universities in noise-sensitive Dutch and Danish locations mandate Stirling engine configurations for acoustic compliance.
Residential captures the volume base; commercial delivers the steepest expansion trajectory.
Technology:
Application context determines whether mechanical or electrochemical conversion delivers superior economics. Grid interconnection standards and building management system compatibility increasingly influence selection.
- Reciprocating:Piston-driven mechanical conversion dominates European gas engine deployments with established service infrastructure and parts availability.
- Thermoelectric:Semiconductor-based solid-state generation occupies niche applications requiring extreme reliability without moving components.
- Combined Heat and Power:Simultaneous electricity and useful thermal output from single fuel input achieves 80-90% total system efficiency through exhaust heat recovery.
- Renewable:Biogas-fed and hydrogen-ready configurations align with EU Green Deal decarbonization pathways for district heating interconnection.
Combined heat and power remains the core architecture; renewable-fed variants gain share fastest.
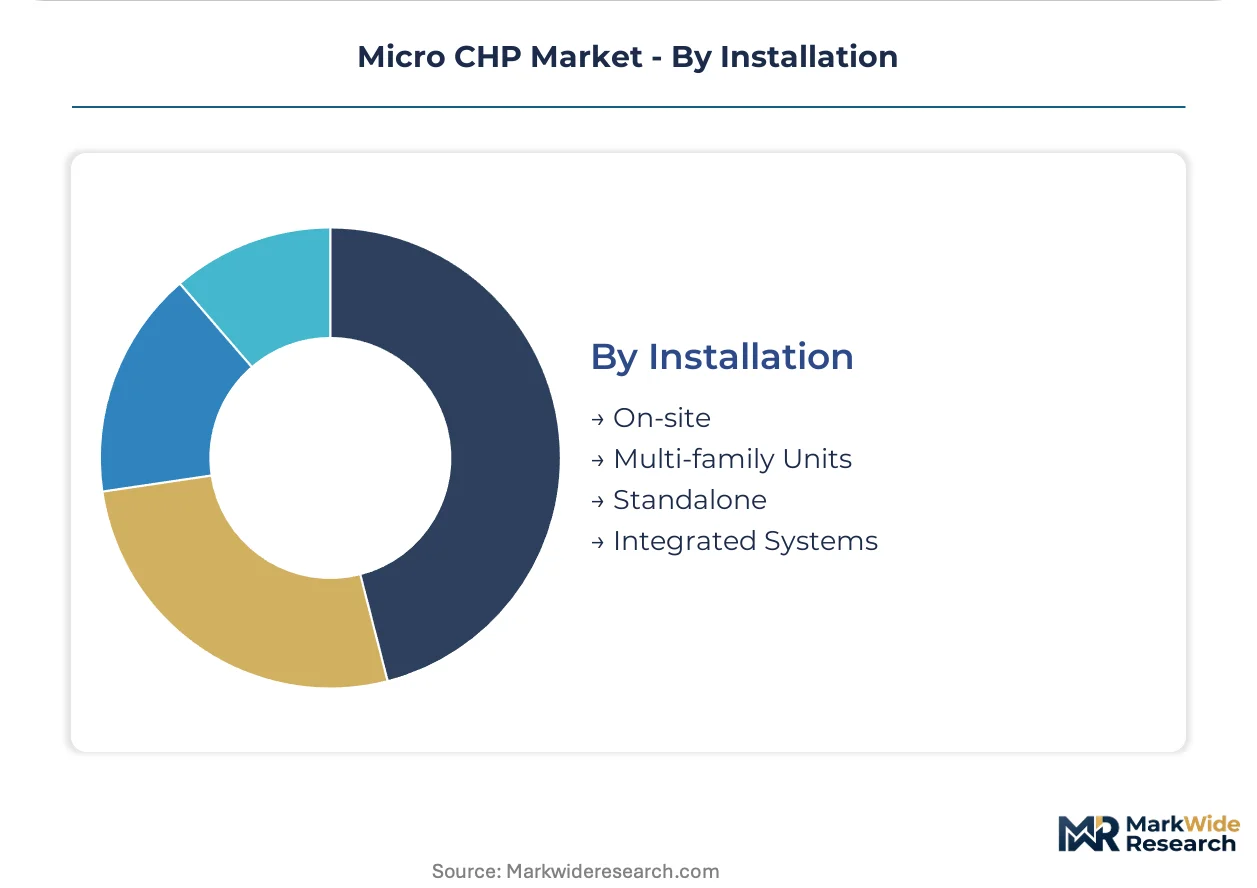
Installation:
Customer type and site constraints shape deployment modality. Retrofit compatibility requirements dominate European demand while Asian markets favor integrated new-build specifications.
- On-site:Building-attached generation eliminates distribution losses and enables behind-the-meter energy arbitrage for prosumers with thermal demand.
- Multi-family Units:Centralized systems serving apartment blocks achieve economies of scale unavailable to single-family installations. E.ON and EnBW leasing programs remove upfront capital barriers for building associations.
- Standalone:Grid-independent configurations serve remote locations where distribution infrastructure extension proves uneconomical.
- Integrated Systems:Hybrid designs combining micro CHP with heat pumps or solar thermal face complexity from EU F-Gas Regulation refrigerant constraints.
Multi-family units dominate European retrofit activity; integrated systems face regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export gas engine systems to Polish retrofit clusters while Japanese fuel cell producers supply residential programs across East Asian metropolitan zones. Equipment trade flows follow subsidy corridors established by national efficiency programs.
Germany
KBA and BAFA efficiency-linked equipment subsidies compress payback periods below seven years for multi-family building owners. The F-Gas Regulation implementation redirects capital away from refrigerant-based thermal technologies toward combustion alternatives. Berlin and Hamburg retrofit clusters accelerate gas engine deployment across residential housing cooperatives.
Japan
METI residential fuel cell tariff support manufactures demand scale independent of grid parity dynamics. The national subsidy framework channels investment toward solid oxide and polymer electrolyte membrane configurations. Tokyo and Osaka metropolitan areas concentrate deployment of sub-50kW electrochemical systems in dense urban housing stock.
Netherlands
Dutch social housing corporations mandate open Modbus or BACnet interfaces for building energy management system integration. The EU F-Gas Regulation and national implementations constrain refrigerant-based hybrid configurations. Rotterdam and Amsterdam urban clusters prioritize fuel cell systems with sub-ppm pollutant profiles to preempt local air quality objections.
Poland
Legacy coal-dependent municipal networks in Kraków and Wrocław face decarbonization mandates creating retrofit openings for bridge technologies. National building efficiency codes recalibrate economic boundaries between standalone distributed generation and district heating interconnection. Silesian and Lower Silesian voivodeships concentrate gas engine micro CHP deployment as transitional infrastructure.
United States
FERC interconnection standards and state-level net metering policies shape behind-the-meter economics for commercial building prosumers. EPA emissions regulations influence technology selection in dense urban air quality non-attainment zones. Northeast Corridor metropolitan areas from Boston to Washington evaluate fuel cell configurations for premium commercial installations.
Micro CHP Market Vendor Landscape
Player mix skews toward diversified heating equipment conglomerates with established boiler distribution channels. Market structure consolidates around vertically integrated manufacturers controlling component supply and service infrastructure. Strategic archetypes include legacy boiler specialists bundling micro CHP with conventional heating hardware, and fuel cell pure-plays pursuing electrochemical efficiency premiums. Dominant competitive moves encompass strategic partnerships for building management system integration and technology licensing for geographic market entry.
Among Germany-based heating conglomerates, Viessmann Group and Vaillant Group occupy positions within the established distribution archetype, leveraging proprietary control architectures for hydraulic compatibility. Ceres Power exemplifies the fuel cell technology specialist tier, representing solid oxide electrochemical conversion capabilities. Yanmar Holdings anchors the compact gas engine fabrication segment, with Japanese industrial conglomerate positioning in Asian commercial building markets.
| Leading Market Players |
|---|
| Viessmann Group |
| Yanmar Holdings |
| Vaillant Group |
| BDR Thermea Group |
| 2G Energy |
| AISIN Corporation |
| Panasonic Corporation |
| EC Power |
| Ceres Power |
| Others |
Supply Flow & Price Mechanics
Long-term equipment leasing contracts pioneered by E.ON and EnBW lock in supply access for apartment building associations while compressing price visibility across the ownership-to-service transition. These opex-based structures shift procurement risk from capital expenditure to predictable monthly outlays, reshaping how manufacturers calibrate revenue recognition and component sourcing strategies.
Pricing Analysis
Current-generation solid oxide fuel cell systems command capital premiums two to three times above prior-generation gas engine equivalents, while next-generation reversible electrolyzer-fuel cell hybrids promise further price stratification. Three-tier pricing structure across premium, standard, and economy levels separates electrochemical configurations with TÜV Rheinland certification from uncertified reciprocating machinery and refurbished boiler-integrated units. Cost compression in standard-tier gas engines is intensifying because Viessmann and Vaillant bundle micro CHP with conventional heating hardware at discounted package rates. Residential cooperative housing associations exhibit the highest price sensitivity due to collective decision-making friction, while Frankfurt commercial developers purchasing solid oxide systems for new construction show minimal elasticity given carbon intensity compliance mandates.
Supply Chain Analysis
Inventory lead times for solid oxide fuel cell ceramic electrolytes extend 18-24 months due to limited high-temperature furnace capacity, constraining manufacturer responsiveness to demand spikes. Component fabrication concentrates in Germany for precision gas engine castings, Japan for polymer electrolyte membrane assemblies, and South Korea for balance-of-plant electronics. Platinum group metal catalysts draw from South African iridium and Russian ruthenium sources, creating acute margin vulnerability during commodity spikes. Single-source vulnerability in ceramic powder supply threatens solid oxide stack production schedules. Distribution runs through established boiler OEM service networks rather than independent channels, privileging incumbents with legacy heating equipment relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micro CHP sector approaches a platform-economics inflection where building energy management system interoperability determines equipment selection. Open Modbus and BACnet protocol adoption by Dutch social housing corporations signals ecosystem consolidation around standardized data interfaces.
For Market Incumbents: Fortify proprietary control architecture dominance by acquiring gateway interface specialists capable of bridging third-party micro CHP units to legacy boiler hydraulics. Deepen backward integration into platinum group metal recycling to offset catalyst cost volatility from South African and Russian supply concentration. The threat of lithium-ion battery substitution paired with rooftop solar demands defensive positioning through thermal output bundling that electrochemical storage cannot replicate. For New Entrants and Emerging Players: Lead with fuel cell stack certification acceleration as a service differentiator, targeting the 18-24 month TÜV Rheinland validation bottleneck that freezes incumbent engineering specifications. Polish district heating interconnection gaps in Kraków and Wrocław offer the most penetrable geography, where legacy coal-dependent municipal networks face decarbonization mandates without established local suppliers. A utility-led equipment leasing partnership model removes upfront capital barriers that stall cooperative housing association procurement decisions. For Investors and Strategic Acquirers: Fuel cell pure-plays with demonstrated solid oxide electrical efficiency above 50 percent represent the priority acquisition archetype, as these capabilities displace premium reciprocating machinery from flagship urban projects. Long-term viability hinges on hydrogen-ready system architectures that enable reversible power-to-gas operation for grid balancing revenue streams. Watch for electrolyzer-fuel cell convergence announcements as the inflection signal indicating which technology platforms will capture power-to-gas integration premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Building Energy Management System Integration | Open protocol adoption by Dutch housing corporations rewards native IoT architectures with tender scoring premiums. |
| Platinum Group Metal Recycling Investment | Captive catalyst recovery from decommissioned stacks insulates margins against South African supply disruptions. |
| Utility-Led Equipment Leasing Channels | E.ON and EnBW pilot programs shift procurement from asset purchase to opex-based contracts for housing associations. |
| Hydrogen-Ready System Certification | EU Green Deal alignment enables power-to-gas revenue streams through reversible solid oxide operation. |
| Acoustic Compliance Specialization | Stirling engine configurations below 70 dB capture protected niche demand from Dutch university and Danish hospital tenders. |
Methodological Framework
A spread of perspectives from utility planning officers, multi-family housing cooperative board members, building energy management system integrators, and TÜV Rheinland certification engineers converged on the working assumptions underlying demand forecasts. These primary insights combined with secondary validation from KBA and BAFA subsidy disbursement records, METI residential fuel cell deployment statistics, EU F-Gas Regulation implementation timelines, and E.ON and EnBW pilot program disclosures. Bottom-up equipment shipment data triangulated against top-down building stock retrofit penetration rates.
Segmentation dimensions modeled span product type, end user, technology conversion architecture, and installation modality across the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical subsidy program uptake patterns and building efficiency code implementation schedules. Fuel cell stack manufacturing cost curves and platinum group metal price trajectories informed technology-specific penetration assumptions. Regional splits incorporated national decarbonization pathway commitments and district heating infrastructure maturity.
Forecasts assume regulatory continuity in Germany's KBA and BAFA frameworks, Japan's METI tariff support, and EU F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Power Generation Technologies Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Thermal Power Market
Power Generation
Distributed Power Generation Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Power Plant EPC Market
Power Generation
Commercial Gensets Market
Power Generation
East Africa Power Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
South East Asia Power Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Australia Thermal Power Market
Power Generation
North America Distributed Power Generation Market