
 Aeroderivative Gas Turbine Market | 2026-2036
Aeroderivative Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Aeroderivative Gas Turbine Market Analysis
Ceramic matrix composites is shifting from niche aerospace use toward hot-section components in aeroderivative turbines, cutting cooling requirements and extending maintenance intervals. GE Vernova leverages its LM6000 and LMS100 platforms to anchor the power generation segment with dual-fuel flexibility. Siemens Energy competes through its SGT-A35 series, which dominates the offshore oil and gas sector with compact footprint and rapid start capability. Rolls-Royce Holdings Plc specializes in marine-propulsion derivatives, drawing on Trent engine heritage for naval and commercial vessel applications.
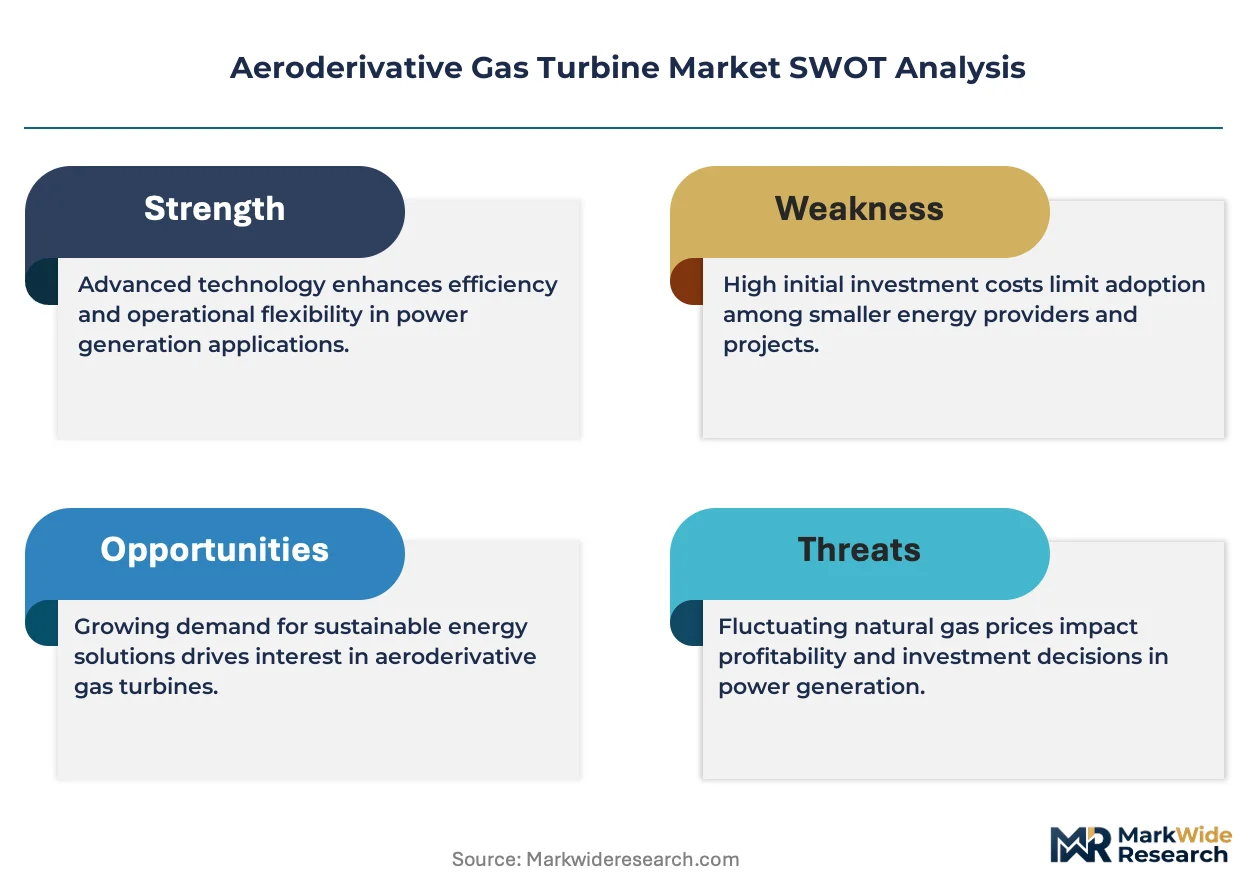
An aeroderivative gas turbine is a lightweight, high-efficiency gas turbine adapted from aircraft jet engines, typically operating at pressure ratios above 30:1 and firing temperatures exceeding 1,400 degrees Celsius for mechanical drive or electrical power generation. Its primary purpose is to deliver fast-ramping, flexible power for grid stabilization, offshore platforms, and naval propulsion where weight and response speed matter. Combined Heat and Power applications capture the fastest growth as industrial facilities seek total thermal efficiency above 80 percent, while Power Generation remains the largest value pool due to utility-scale peaking installations. Oil and Gas end users sustain premium pricing for containerized turbine packages that withstand remote environmental conditions.
EPA standards under the Clean Air Act mandate Best Available Control Technology for new turbines, while the EU F-Gas Regulation phases down hydrofluorocarbon use in cooling systems tied to turbine auxiliaries. FAA airworthiness certification protocols for original aero-engines indirectly govern structural integrity standards that manufacturers transfer to industrial derivatives. Stakeholders must monitor carbon-border adjustment mechanisms and hydrogen-blending mandates, as fuel-flexibility investments made now will determine competitive position when decarbonization deadlines harden.
Market Dynamics
Ceramic matrix composites are compressing cooling-system mass in hot-section components while EPA and EU F-Gas regulations force combustor redesigns, creating simultaneous pull and push forces across the value chain.
Growth Catalysts
- Grid Balancing Mandates:FERC Order 2222 in the United States enables distributed energy resources to participate in wholesale markets, accelerating utility deployments of fast-ramping aeroderivative units for peaking power and frequency regulation.
- Offshore Platform Electrification:North Sea operators are replacing diesel generators with gas turbine packages to cut carbon intensity, leveraging compact footprints and helicopter-transportable modules for remote installations.
- Hydrogen Fuel Flexibility:Blending-ready combustor designs are absorbing R&D investment as operators anticipate EU hydrogen backbone infrastructure deadlines and carbon-border adjustment exposure.
Market Restraints
- Superalloy Supply Concentration:Single-source dependence on vacuum induction melting capacity in the United States and Germany creates input vulnerability for turbine disk and blade forgings.
- EPA Best Available Control Technology:New source performance standards under the Clean Air Act impose capital-intensive selective catalytic reduction and oxidation catalyst systems that extend project payback periods.
- Battery Storage Substitution:Lithium-ion grid batteries are capturing frequency regulation and short-duration peaking contracts that aeroderivative turbines previously dominated, compressing addressable market scope.
Strategic Opportunities
- Industrial CHP Underpenetration:Data centers in the United States are adopting turbine-based combined cooling, heat and power systems to secure 99.999% uptime while qualifying for IRA investment tax credits.
- Marine Electrification Gap:Naval surface combatant programs in the United Kingdom and Japan are specifying integrated electric propulsion with aeroderivative prime movers, opening vessel-class expansion.
- EU F-Gas Phase-Down:Hydrofluorocarbon restrictions on cooling system auxiliaries are creating retrofit demand for turbine packages with alternative refrigerant architectures and sealed magnetic bearings.
Industry Challenges
- Hot-Section Repair Technician Scarcity:Specialized welding and coating restoration skills for directionally solidified superalloys are concentrating at a handful of FAA-certified repair stations, extending turnaround times.
- Dual-Certification Burden:Derivative turbines must satisfy both FAA airworthiness protocols for original aero-engines and ISO 3977 industrial gas turbine standards, duplicating test programs and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeroderivative Gas Turbine Market |
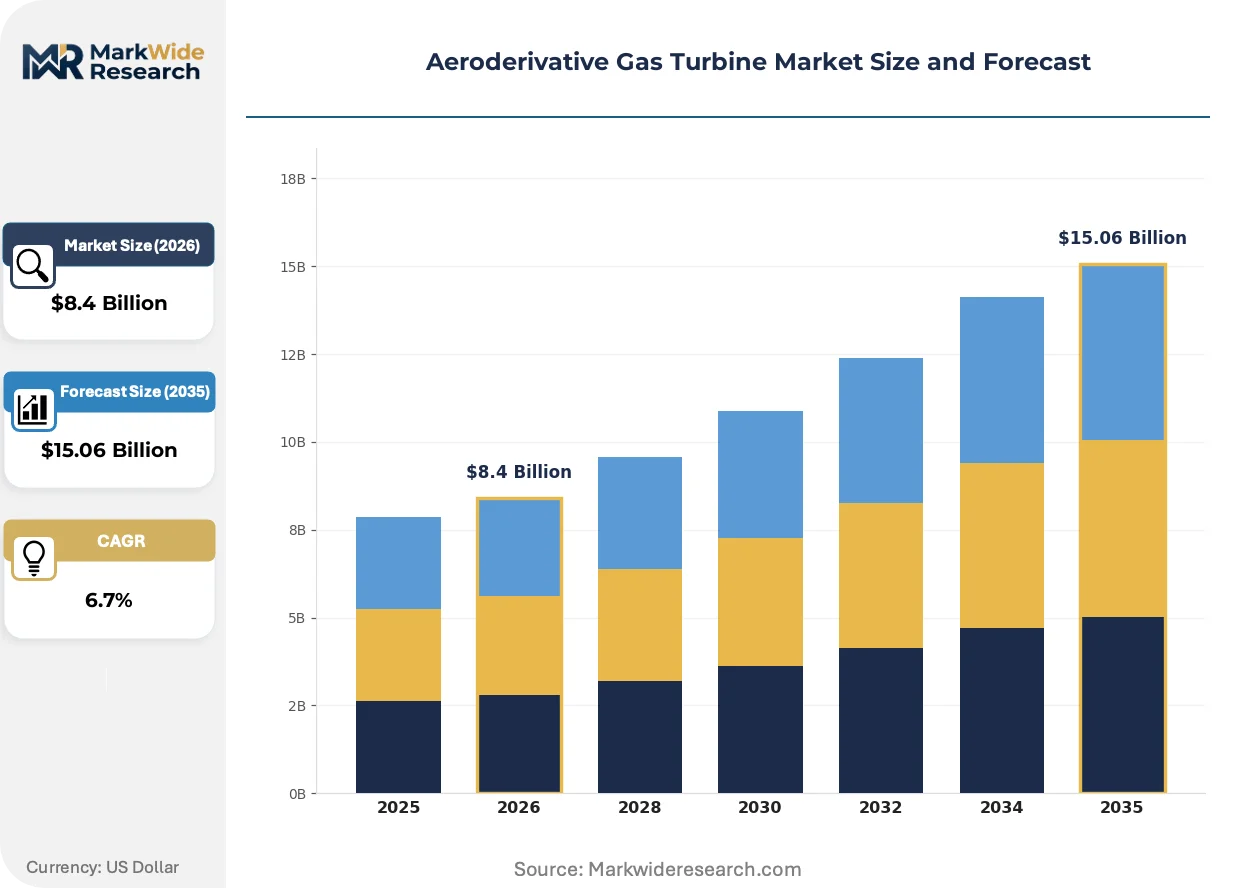
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Industrial, Micro Turbines, Combined Heat and Power Application: Power Generation, Marine Propulsion, Oil & Gas, Industrial Processes End User: Utilities, Oil and Gas Companies, Manufacturers, Aerospace Installation: Standalone Units, Integrated Systems, Containerized Turbines, Modular Solutions |
| Companies Covered | GE Vernova Inc., Siemens Energy AG, Rolls-Royce Holdings Plc, Mitsubishi Heavy Industries Ltd., Pratt and Whitney, Solar Turbines Inc., Baker Hughes Co., Kawasaki Heavy Industries Ltd., Ansaldo Energia Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeroderivative Gas Turbine Market Emerging Trajectories
Additive manufacturing is penetrating turbine component supply chains, enabling topology-optimized combustor liners and reducing lead times for obsolete part reproduction.
Ceramic matrix composites is absorbing thermal barrier coating functions in first-stage vanes and blades, cutting cooling air requirements by fifteen to twenty percent. Power utilities with cyclic duty profiles are piloting these inserts in LM6000-class turbines to extend hot-section inspection intervals. The technology is absorbing maintenance budget allocations that previously flowed to superalloy replacement programs.
The EU F-Gas Regulation mandates an eighty percent hydrofluorocarbon phase-down by 2030, forcing auxiliary cooling system redesigns. Turbine packagers are specifying magnetic bearing oil-free compressors and CO2-based cooling loops to eliminate fluorinated gas dependence. Offshore oil and gas installations in Norwegian and UK waters face the steepest compliance timelines and are driving supplier qualification programs.
Long-term service agreements are fragmenting into modular, event-based contracts. Industrial facilities are unbundling parts, repairs, and technical advisory into separate procurement streams, displacing traditional power-by-the-hour structures. This pattern is most visible among independent power producers in Texas and California who maintain in-house combustion inspection capabilities.
Aeroderivative Gas Turbine Market Segmentation
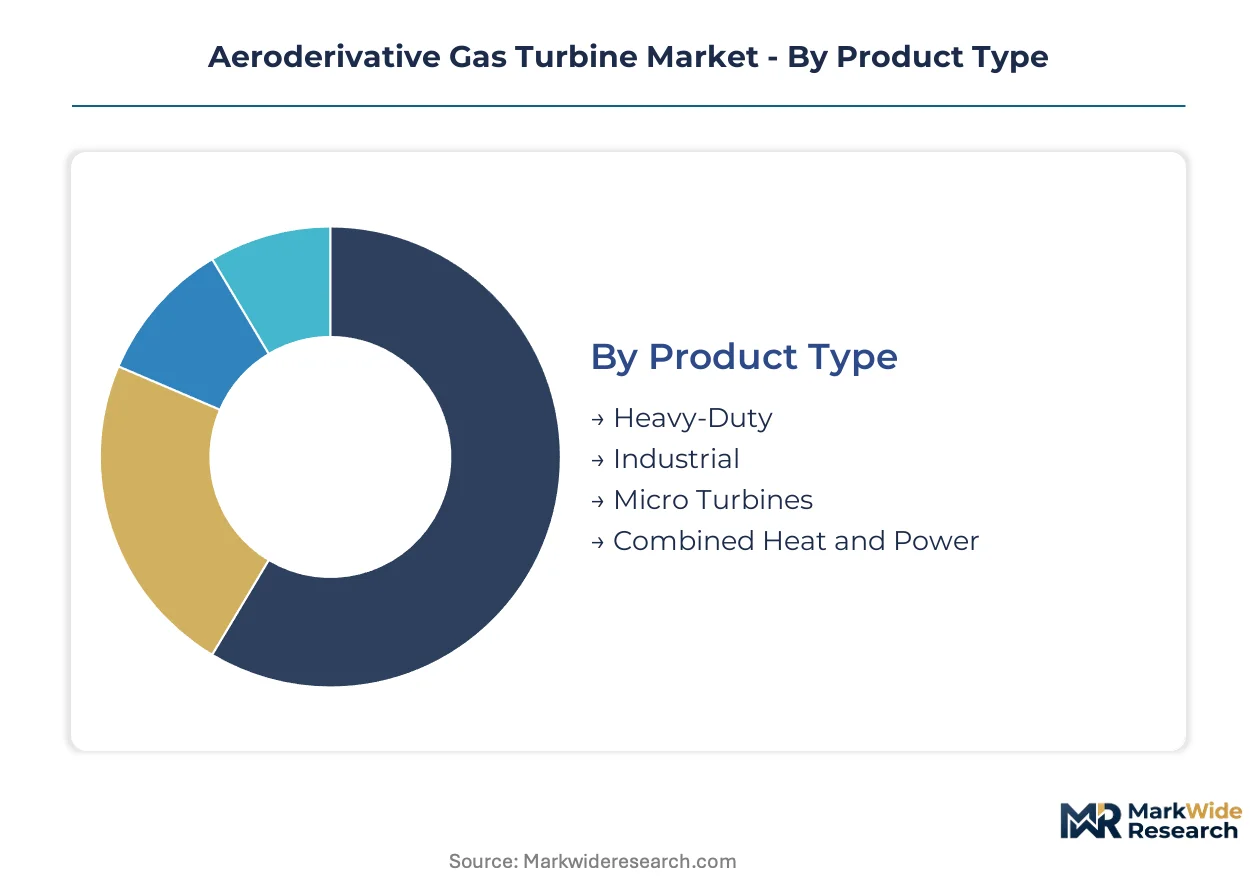
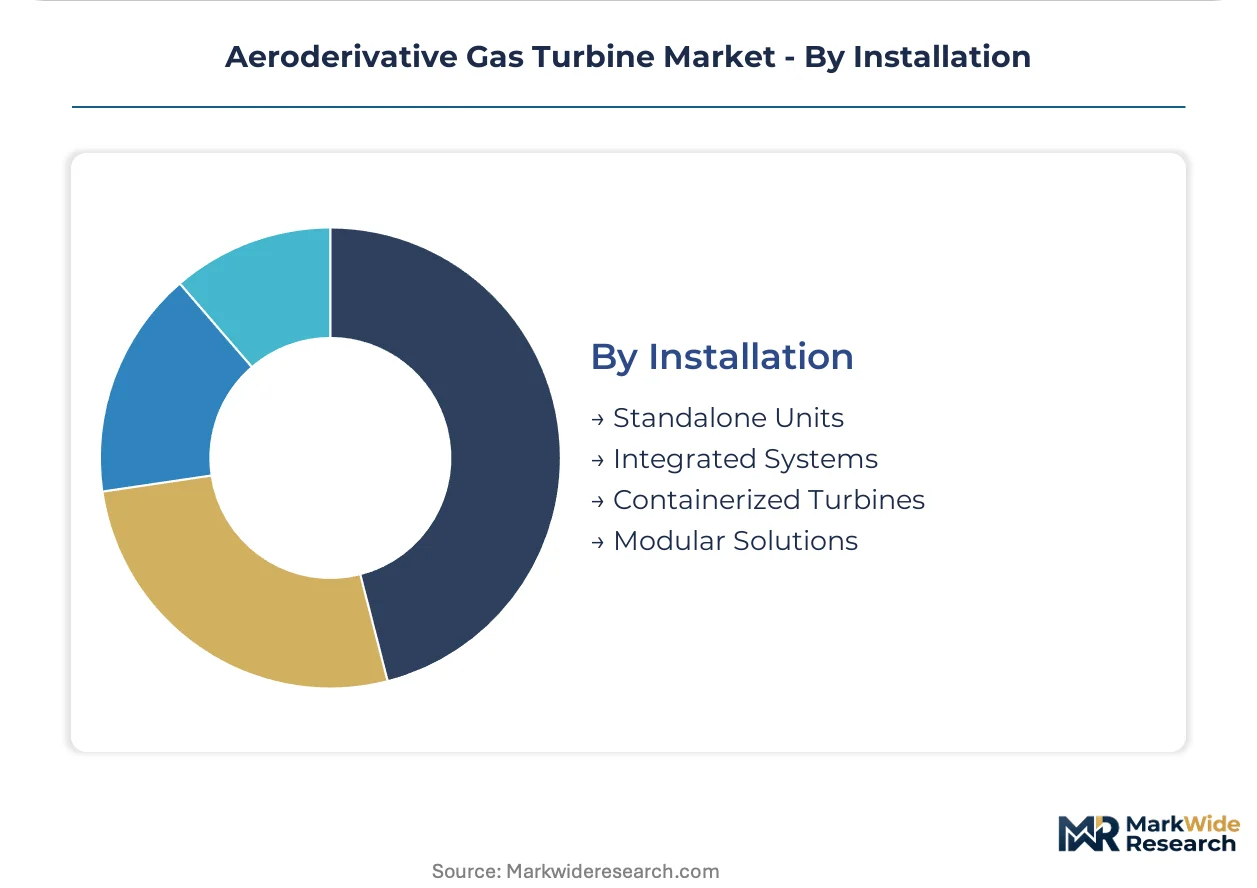
Segmentation in aeroderivative gas turbines reveals how technology heritage, deployment constraints, and buyer procurement power reshape competitive boundaries. Each category isolates distinct value pools where pressure ratios, fuel flexibility, and maintenance architectures determine supplier selection.
Product Type:
Buyers prioritize thermal efficiency and ramp rate specifications when selecting turbine classes for their duty cycles.
- Heavy-Duty:These units operate at pressure ratios exceeding 30:1 with firing temperatures above 1,400 degrees Celsius, delivering baseload and intermediate power for utility fleets. United States independent power producers favor heavy-duty aeroderivatives for FERC Order 2222 grid balancing participation, where rapid start capability commands premium capacity payments.
- Combined Heat and Power:CHP configurations capture exhaust thermal energy to achieve total system efficiency above 80 percent, serving industrial facilities with steady thermal loads. Data centers in Texas and California are adopting turbine-based CCHP systems to secure 99.999 percent uptime while qualifying for IRA investment tax credits.
- Industrial:Mid-scale turbines bridge peaking and mechanical drive applications with modular maintenance architectures.
- Micro Turbines:Sub-megawatt units target distributed generation nodes where footprint constraints and remote fuel access dominate site selection.
Heavy-Duty leads on scale; Combined Heat and Power leads on momentum.
Application:
End-use duty profiles dictate combustor design priorities and service interval economics.
- Power Generation:Peaking and grid stabilization applications exploit sub-10-minute start times and deep turndown ratios. United States utilities expanding aeroderivative fleets for frequency regulation absorb the largest volume of new unit deliveries.
- Oil & Gas:Offshore platform electrification and pipeline compression demand containerized packages with helicopter-transportable footprints. North Sea operators replacing diesel generators with gas turbine packages drive premium pricing for environmental compliance and compact modularity.
- Marine Propulsion:Naval surface combatant programs specify integrated electric propulsion with aeroderivative prime movers for weight-critical vessel classes.
- Industrial Processes:Mechanical drive applications in petrochemical and refining sectors prioritize fuel flexibility for hydrogen blending readiness.
Power Generation commands installed base; Oil & Gas commands margin premiums.
End User:
Procurement sophistication and in-house technical capability separate buyer tiers.
- Utilities:Vertically integrated power companies negotiate long-term service agreements with predictable parts provisioning. Their fleet standardization programs favor dual-fuel flexibility to hedge against natural gas price volatility.
- Oil and Gas Companies:Supermajors and independents specify containerized turbine packages for remote environmental resilience. Their capital allocation cycles tie turbine procurement to field development timelines and carbon intensity reduction targets.
- Manufacturers:Industrial facilities with captive power needs evaluate CHP economics against grid purchase alternatives and thermal load profiles.
- Aerospace:Defense contractors and engine OEMs source derivatives for military propulsion programs requiring FAA airworthiness heritage.
Utilities lead on unit volume; Oil and Gas Companies lead on specification intensity.
Installation:
Site constraints and mobilization logistics determine packaging architecture selection.
- Containerized Turbines:Pre-integrated skids with weatherized enclosures enable rapid deployment to offshore platforms and remote mining operations. Norwegian and UK North Sea installations face steep EU F-Gas compliance timelines, driving qualification programs for alternative refrigerant architectures.
- Modular Solutions:Scalable turbine blocks allow capacity expansion without full plant redesign, serving data centers and industrial campuses with phased load growth. Modular procurement patterns fragment traditional power-by-the-hour service structures into unbundled parts and repair contracts.
- Standalone Units:Single-turbine installations anchor distributed generation nodes with minimal auxiliary integration.
- Integrated Systems:Fully engineered turbine-generator-heat recovery packages optimize for specific site thermal and electrical load profiles.
Containerized Turbines lead on deployment velocity; Modular Solutions lead on contract structure innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast petrochemical corridor anchors global aeroderivative turbine deployment, with shale gas abundance and FERC Order 2222 grid modernization programs driving utility-scale peaking installations and distributed power nodes.
United States
Independent power producers in Texas and California are expanding fast-ramping turbine fleets for frequency regulation and grid balancing services. EPA Best Available Control Technology mandates under the Clean Air Act require selective catalytic reduction systems on new installations. The Permian Basin and Eagle Ford shale formations concentrate demand for mechanical drive applications in gas processing and pipeline compression.
Germany
Industrial CHP facilities in the Rhine-Ruhr and Bavarian chemical corridors are retrofitting turbine packages to meet EU F-Gas Regulation hydrofluorocarbon phase-down deadlines. The country's national energy regulator enforces strict emissions standards for new gas-fired capacity. Hamburg and Bremen port complexes are piloting hydrogen-blending ready turbines for maritime and logistics electrification.
United Kingdom
North Sea platform operators are replacing diesel generators with containerized aeroderivative packages to cut carbon intensity and meet offshore electrification targets. The EU F-Gas Regulation drives auxiliary cooling system redesigns for Norwegian and UK waters installations. Aberdeen and Great Yarmouth serve as primary logistics hubs for helicopter-transportable turbine module deployment.
Japan
Naval surface combatant programs are specifying integrated electric propulsion with aeroderivative prime movers for weight-critical vessel classes. METI promotes hydrogen fuel flexibility investments through national decarbonization roadmaps. The Nagoya-Tokyo industrial corridor hosts maintenance facilities for hot-section repair and ceramic matrix composite component qualification.
Saudi Arabia
Remote oil and gas field developments are absorbing containerized turbine packages for power generation and mechanical drive in harsh desert environments. The national petroleum regulator mandates emissions controls for new upstream facilities. The Eastern Province concentrates demand for rapid-deployment modular systems tied to field development timelines.
Aeroderivative Gas Turbine Market Vendor Landscape
Global majors compete with regional champions across technology licensing and service network coverage, producing a tiered structure where full-line OEMs anchor premium segments and specialized packagers capture niche applications. The vendor base clusters around three archetypes: diversified industrial conglomerates with aero-engine heritage, energy-focused turbine specialists, and regional fabricators serving localized mechanical drive markets. Competitive moves center on long-term service agreement restructuring and fuel-flexibility R&D partnerships.
Within the diversified conglomerate tier, GE Vernova Inc. and Siemens Energy AG occupy positions defined by dual-fuel platform breadth and utility-scale installation density. Rolls-Royce Holdings Plc exemplifies the aero-heritage specialist archetype, drawing on civil aviation engine lineages for marine and industrial derivatives. Mitsubishi Heavy Industries Ltd. and Kawasaki Heavy Industries Ltd. represent Japanese industrial groupings with integrated propulsion and power generation capabilities. These five entities collectively anchor competitive dynamics across peaking power, offshore oil and gas, and naval propulsion segments.
| Leading Market Players |
|---|
| GE Vernova Inc. |
| Siemens Energy AG |
| Rolls-Royce Holdings Plc |
| Mitsubishi Heavy Industries Ltd. |
| Pratt and Whitney |
| Solar Turbines Inc. |
| Baker Hughes Co. |
| Kawasaki Heavy Industries Ltd. |
| Ansaldo Energia Spa |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance deadlines gate qualified supply for auxiliary cooling systems and premium-tier pricing access, as only turbine packagers with magnetic bearing and CO2-loop architectures can serve Norwegian and UK North Sea installations facing the steepest hydrofluorocarbon phase-down timelines.
Pricing Analysis
Input-cost pass-through from vacuum induction melting capacity constraints in the United States and Germany flows directly into turbine disk and blade forging premiums. Contract-based long-term offtake structures dominate, with price differentiation hinging on dual-fuel flexibility certification and after-sales service bundling. Cost compression in standard-tier units is intensifying because lithium-ion battery substitution erodes frequency regulation contract margins. Independent power producers in Texas exhibit highest price sensitivity, while offshore oil and gas supermajors absorb premium pricing for containerized environmental resilience.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility demand, while specialized packagers serve offshore and marine segments through distributor networks. Manufacturing concentrates in the United States, Germany, and Japan, with ceramic matrix composite qualification centers anchoring in Japan and the United Kingdom. The supply chain draws from nickel-based superalloy feedstock, precision casting capacity, and FAA-certified repair station networks. Single-source vulnerability in vacuum induction melting creates structural risk. Distribution runs through OEM direct sales for utilities and EPC-integrated procurement for offshore platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Best Available Control Technology mandates and EU F-Gas hydrofluorocarbon phase-downs continuously refresh equipment replacement demand.
For Market Incumbents: Extend hot-section repair service networks to counter technician scarcity at FAA-certified stations, locking in aftermarket revenue streams. Deepen backward integration into ceramic matrix composite manufacturing to capture margin from cooling-system displacement. Battery storage substitution threatens frequency regulation pricing power. For New Entrants and Emerging Players: FERC Order 2222 in the United States opens a window for distributed energy resource aggregators to capture grid balancing contracts with fast-ramping aeroderivative units. Target data center combined cooling, heat and power installations in Texas and California, where IRA investment tax credits reduce customer acquisition friction. Pursue modular service contract unbundling as a go-to-market angle against traditional power-by-the-hour incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among regional packagers with helicopter-transportable containerized capabilities but limited service network coverage. Long-term viability hinges on hydrogen-blending combustor R&D positioning ahead of EU hydrogen backbone infrastructure deadlines. Watch carbon-border adjustment mechanism implementation timelines as the inflection signal for fuel-flexibility premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Combustor Development | Positions OEMs for EU hydrogen backbone deadlines and carbon-border adjustment exposure. |
| Ceramic Matrix Composite Manufacturing Scale-Up | Captures margin from fifteen to twenty percent cooling air reduction in hot-section components. |
| Long-Term Service Agreement Restructuring | Responds to independent power producer preference for unbundled parts and repair procurement. |
| FAA-Repair Station Network Expansion | Addresses hot-section technician scarcity extending turnaround times for superalloy restoration. |
| Magnetic Bearing Oil-Free Compressor Qualification | Enables EU F-Gas compliance for offshore platform auxiliary cooling system retrofits. |
Methodological Framework
Multiple input streams — executive interviews with utility planning officers and IPP project developers, EPC contractor technical assessments, and fuel supply specialist market intelligence — were reconciled against secondary validation from EIA capacity data, FERC interconnection filings, IEA power generation reports, and project development databases. Bottom-up unit deployment tracking and top-down market sizing triangulated volume estimates across the analysis window.
Historical deployment patterns were cross-referenced against expert panel input on regulatory compliance timelines and technology substitution risks. Segmentation modeling captured product type, application duty profile, end-user procurement sophistication, and installation architecture across regional grid types. CAGRs were derived from unit shipment trajectories and average selling price evolution, with hydrogen infrastructure buildout assumptions and emissions regulation enforcement intensity as key forecast inputs.
Revisions become necessary when EPA enforcement intensity shifts, EU F-Gas phase-down accelerates, or ceramic matrix composite qualification timelines extend beyond base assumptions. Forecasts reflect documented assumptions on shale gas price trajectories and battery storage cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Thailand Power Generation EPC Market
Power Generation
Iraq Power EPC Market
Power Generation
Distributed Generation Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Stirling Engine Market
Power Generation
Power Plant EPC Market
Power Generation
Venezuela Power Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Malaysia Power Market
Power Generation
Canada Power EPC Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Distributed Power Generation Market
Power Generation
Steam Turbine Market
Power Generation
Commercial Gensets Market
Power Generation
Australia Thermal Power Market
Power Generation
Global Power Generation Market