
 Peaking Power Plant Market | 2026-2036
Peaking Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Peaking Power Plant Market Outlook
Merchant independent power producers are unwinding legacy reliance on utility offtake as corporate renewable buyers seek firming capacity. NextEra Energy Inc. leverages its Florida renewables fleet to anchor hybrid peaking configurations. Wärtsilä Oyj Abp dominates the reciprocating engine segment with modular fast-start plants. General Electric Company extends its gas turbine overhaul expertise into battery-gas hybrid retrofits.
A peaking power plant is a generation asset engineered for rapid dispatch within minutes to hours, typically achieving full output in under ten minutes and operating fewer than fifteen percent of annual hours to cover demand spikes and grid instability. These facilities bridge supply gaps when baseload units cannot respond quickly enough to load fluctuations or renewable output drops. Gas turbine installations lead installed capacity globally due to their unmatched ramp rates and mature supply chains, while battery storage represents the fastest-expanding technology category as lithium-ion costs decline and grid operators rewrite interconnection rules. Diesel generator sets retain niche positions in remote industrial zones and island grids where fuel logistics override emissions concerns.
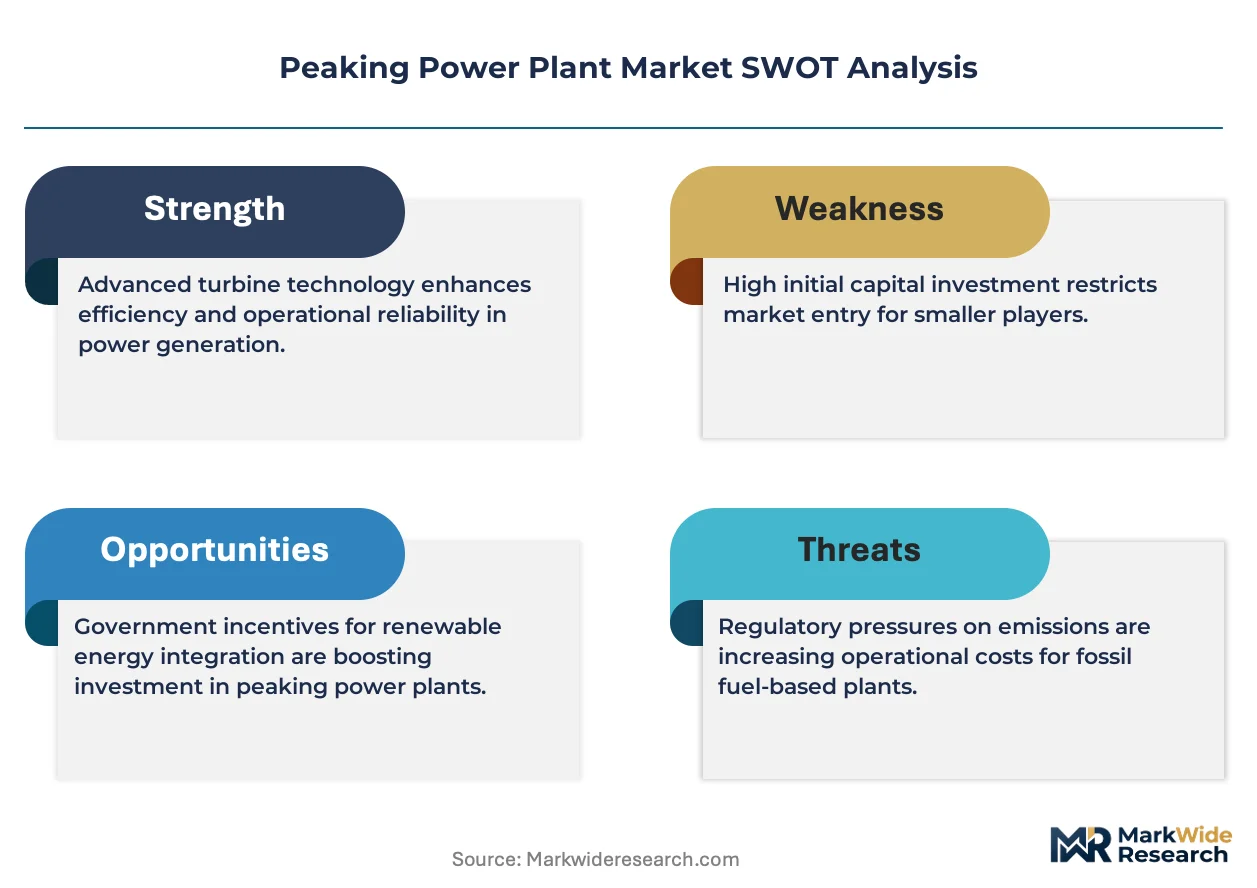
The US EPA enforces stationary source emissions limits under the Clean Air Act that force older peaking plants toward retirement or costly retrofit, while FERC Order 2222 enables distributed energy resources to compete in wholesale capacity markets. Germany's KBA and federal grid regulator Bundesnetzagentur enforce strict emissions testing for reciprocating engines in combined heat and power configurations. Stakeholders must decide whether to retrofit existing gas turbines with hydrogen blending capability or accelerate replacement with battery storage as capacity market auctions increasingly penalize carbon intensity.
Market Dynamics
The US EPA's updated emissions standards for stationary combustion sources are forcing a wholesale technology refresh across installed peaking capacity, compressing asset life cycles and redrawing competitive positions between gas turbine retrofits and battery-gas hybrid configurations.
Growth Catalysts
- Interconnection rule reforms:FERC Order 2222 enables distributed energy resources to compete in wholesale capacity markets, unlocking revenue streams for battery storage and reciprocating engine clusters previously excluded from grid services.
- Texas and California net-load volatility:ERCOT and CAISO face the steepest demand ramps globally as solar generation collapses at sunset, creating sustained procurement pull for sub-ten-minute ramp capability.
- Lithium-ion cost trajectories:Declining battery cell prices allow four-hour storage configurations to undercut new-build gas peakers on levelized cost in select markets, accelerating technology substitution.
Market Restraints
- Steel and specialty alloy input costs:Gas turbine rotor forgings and heat-resistant superalloys face volatile pricing tied to nickel and cobalt supply concentration in Indonesia and the Democratic Republic of Congo.
- Clean Air Act compliance deadlines:The US EPA's stationary source emissions limits impose retrofit costs that render marginal peaking plants economically unviable, accelerating stranded asset risk for merchant operators.
- Battery duration limitations:Lithium-ion systems beyond four hours suffer steep cost escalation, leaving multi-day renewable lulls uncovered and preserving gas turbine relevance in firming portfolios.
Strategic Opportunities
- Hydrogen blending retrofits:Existing gas turbine infrastructure in Germany and the Netherlands offers a platform for incremental decarbonization as hydrogen supply chains mature under EU Green Deal funding mechanisms.
- Hybrid configuration standardization:Converging battery storage with reciprocating engines creates dispatch flexibility that single-technology plants cannot match, opening premium pricing in capacity auctions.
- Corporate renewable firming contracts:Direct power purchase agreements with technology companies and data center operators bypass traditional utility offtake, capturing margin from sustainability-linked procurement mandates.
Industry Challenges
- Grid code synchronization complexity:Battery-gas hybrid plants must satisfy divergent interconnection standards across ISOs, stretching engineering resources and delaying commercial operation dates.
- Specialized commissioning expertise:Fast-start reciprocating engine installations require technicians trained in Wärtsilä and MAN Energy Solutions control systems, creating bottlenecks in project execution timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peaking Power Plant Market |
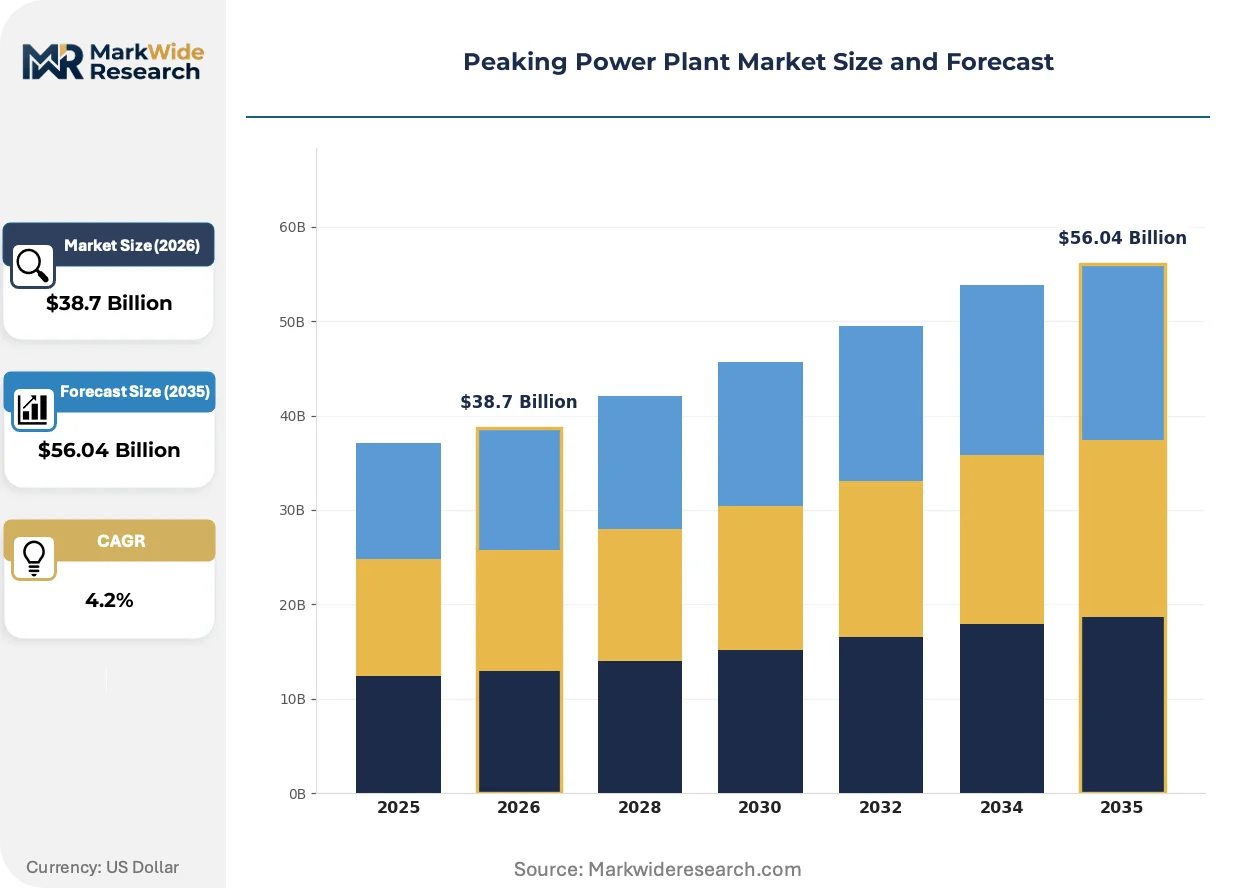
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gas Turbine, Diesel Generator, Hydro Power, Battery Storage Application: Load Management, Emergency Backup, Renewable Integration, Frequency Regulation End User: Utilities, Independent Power Producers, Industrial Users, Commercial Facilities Technology: Combined Cycle, Simple Cycle, Reciprocating Engine, Flywheel Storage |
| Companies Covered | The Southern Company, NextEra Energy Inc., Enel S.p.A, Wärtsilä Oyj Abp, General Electric Company, Siemens AG, Duke Energy Corporation, ENGIE SA, NRG Energy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peaking Power Plant Market Strategic Shifts
Technology trajectories in peaking power are diverging sharply between incremental gas turbine efficiency gains and modular battery storage scale-up, with regulatory pressure acting as the forcing function rather than market economics alone.
Gas turbine technology is bifurcating between legacy frame machines retrofitted for hydrogen blending and aero-derivative units optimized for sub-five-minute starts. Grid operators in Texas and California are procuring the latter almost exclusively for net-load ramp services. This split is compressing the addressable market for mid-range turbines that lack either extreme flexibility or deep decarbonization pathways.
The US EPA enforces stationary source emissions limits that force older simple-cycle plants toward retirement or selective catalytic retrofit, while FERC Order 2222 simultaneously enables distributed resources to capture capacity payments. Merchant independent power producers face a binary choice: absorb capital costs for emissions compliance or cede market position to battery storage entrants. The Southwest Power Pool and Midcontinent ISO regions show the most acute asset retirement pressure.
Corporate buyers are unbundling renewable energy certificates from firming capacity, creating separate procurement streams that value carbon-free generation and dispatchable reliability independently. Data center operators in Northern Virginia and Phoenix now contract directly with hybrid plant developers, bypassing traditional utility intermediaries. This channel disintermediation concentrates demand in hyperscale clusters and fragments the customer base for conventional merchant peakers.
Peaking Power Plant Market Segmentation
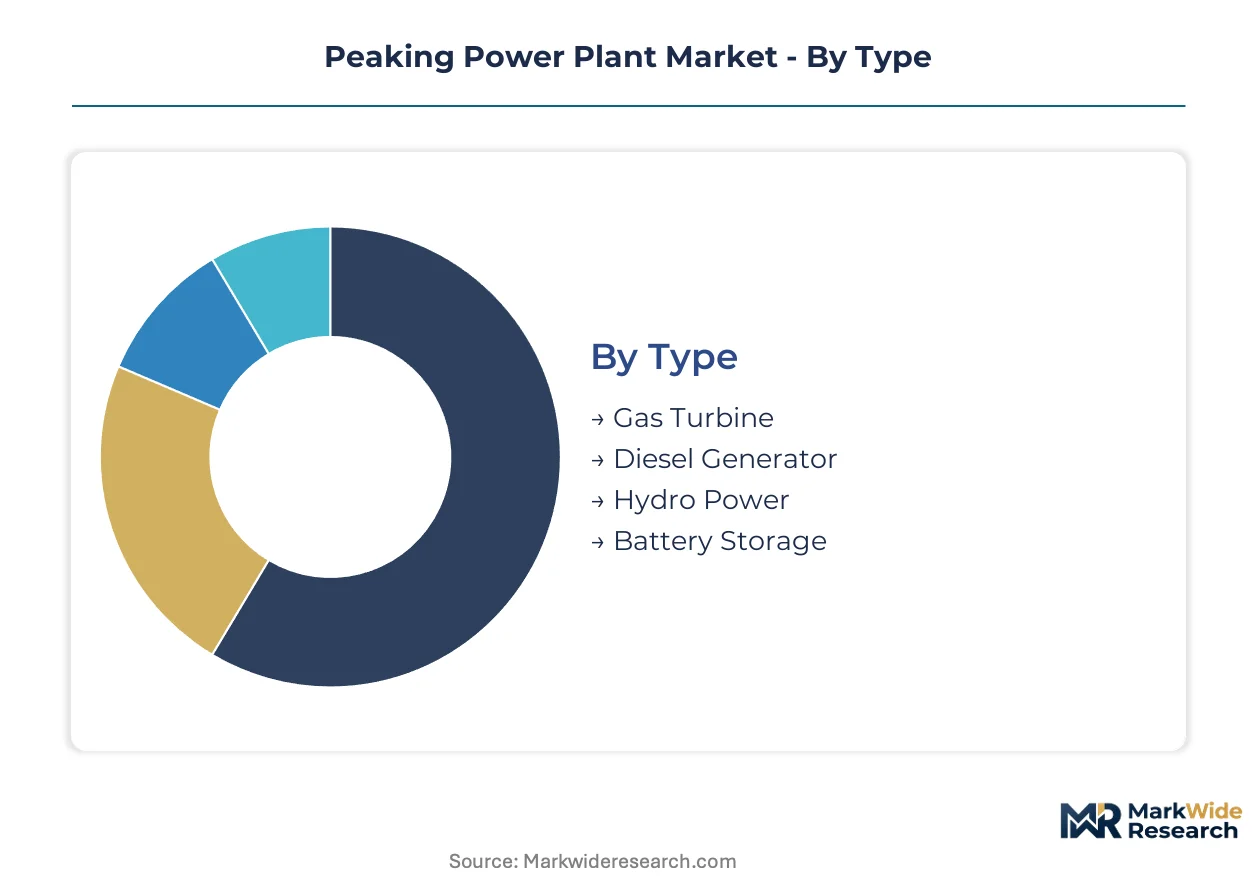
Peaking power plant segmentation reveals diverging technology economics as battery storage disrupts traditional gas turbine procurement. Grid operators and corporate buyers now evaluate assets through distinct lenses: ramp rate, carbon intensity, and contract flexibility.
Type:
Gas turbines face acute substitution pressure from lithium-ion systems in sub-four-hour applications, while diesel generators confront regulatory phase-out in developed markets.
- Gas Turbine:Aero-derivative units achieve sub-five-minute starts and dominate ERCOT and CAISO procurement for net-load ramp services. Frame machines face stranded asset risk as hydrogen blending retrofits compete with battery replacement economics.
- Battery Storage:Lithium-ion configurations undercut new-build gas peakers on levelized cost in Texas and California markets. Four-hour duration systems capture the bulk of interconnection queue capacity, though multi-day lulls preserve gas relevance.
- Diesel Generator:Remote industrial zones and island grids sustain niche demand where fuel logistics override emissions compliance timelines.
- Hydro Power:Pumped storage facilities provide multi-hour firming in mountainous geographies with limited battery supply chain access.
Gas turbine installations anchor the volume base while battery storage gains share at the steepest rate.
Application:
Application segmentation tracks the unbundling of energy and capacity value streams as corporate buyers separate renewable certificates from firming contracts.
- Load Management:Covers demand spikes during summer peaks and industrial ramp events. Texas and California grid operators procure dedicated ramp capability as solar generation collapses at sunset.
- Renewable Integration:Fastest-expanding application category as data center operators in Northern Virginia and Phoenix contract directly with hybrid plant developers for firming capacity.
- Emergency Backup:Critical facilities and microgrids maintain diesel reciprocating engines for black-start capability beyond battery duration limits.
- Frequency Regulation:Battery storage dominates this service for its millisecond response precision, displacing gas turbine spinning reserves in organized markets.
Load management commands the largest procurement volumes while renewable integration climbs the fastest.
End User:
Customer-type segmentation reflects channel disintermediation as hyperscale buyers bypass traditional utility intermediaries.
- Utilities:Vertically integrated operators in the Southwest Power Pool and Midcontinent ISO face acute asset retirement pressure from EPA emissions deadlines.
- Independent Power Producers:Merchant developers unwind legacy utility offtake reliance to pursue corporate renewable firming contracts directly.
- Industrial Users:Energy-intensive manufacturing clusters procure captive peaking capacity to manage exposure to real-time pricing volatility.
- Commercial Facilities:Data center and logistics operators concentrate demand in Northern Virginia and Phoenix for sustainability-linked procurement mandates.
Utilities retain the largest installed base while independent power producers expand most quickly.
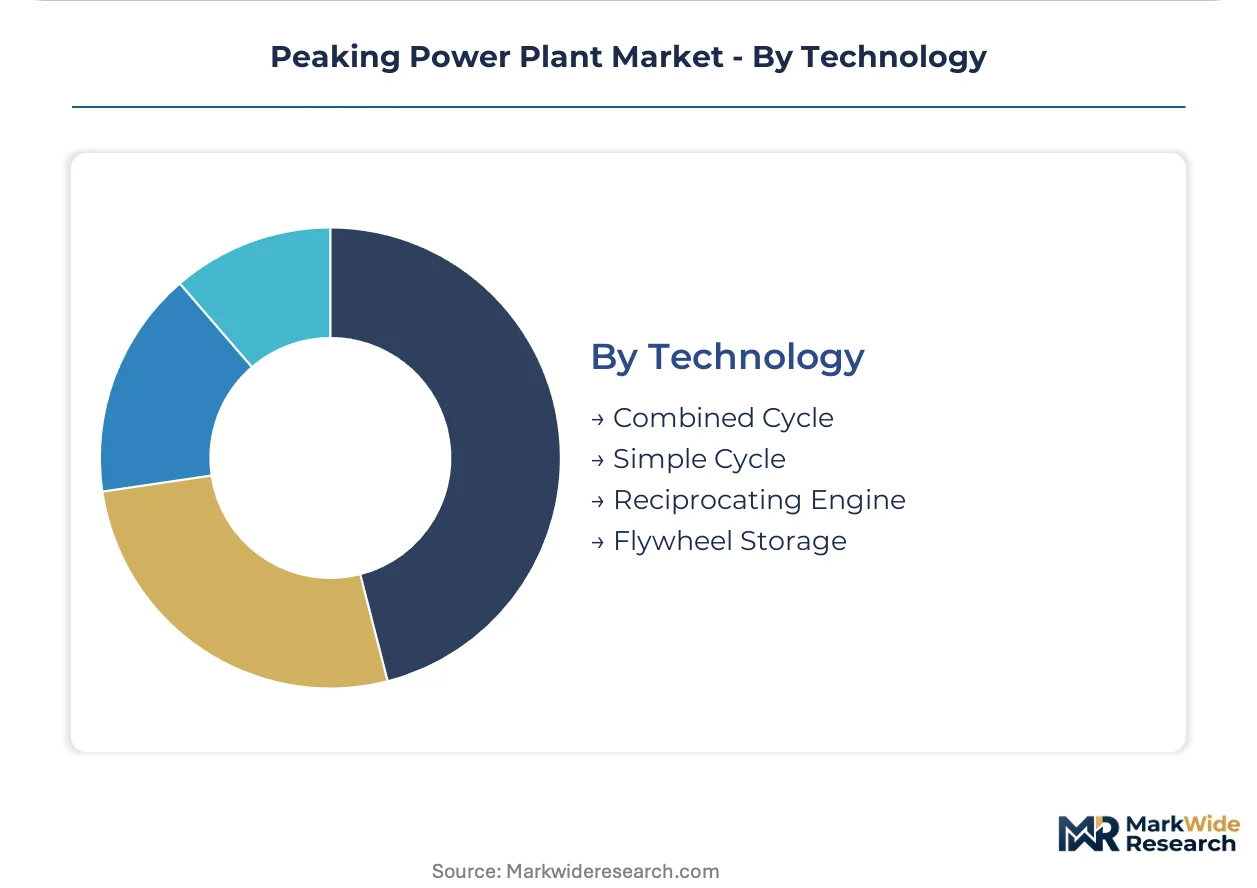
Technology:
Technology segmentation bifurcates between thermal assets optimized for hydrogen pathways and electrochemical systems scaling through manufacturing cost curves.
- Simple Cycle:Legacy gas turbine installations face EPA-mandated retrofit or retirement decisions as stationary source emissions limits tighten compliance timelines.
- Reciprocating Engine:Wärtsilä and MAN Energy Solutions modular plants achieve sub-ten-minute starts with lower minimum load than frame turbines. Germany's KBA enforces strict emissions testing for combined heat and power configurations.
- Combined Cycle:Baseload-captive technology with limited peaking relevance due to thermal mass constraints on ramp rates.
- Flywheel Storage:Niche frequency regulation applications where cycling durability exceeds lithium-ion economic thresholds.
Simple cycle installations dominate current capacity while reciprocating engines capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ERCOT interconnection in Texas anchors North American peaking procurement as solar penetration drives extreme net-load ramps. Germany's hydrogen pipeline network shapes European retrofit strategies. China's ultra-high-voltage transmission corridors concentrate battery-gas hybrid deployments in coastal load centers.
United States
ERCOT and CAISO face the steepest demand ramps globally as solar generation collapses at sunset. The EPA enforces stationary source emissions limits under the Clean Air Act that force older simple-cycle plants toward retirement. Data center clusters in Northern Virginia and Phoenix now contract directly with hybrid plant developers for firming capacity.
Germany
The KBA and Bundesnetzagentur enforce strict emissions testing for reciprocating engines in combined heat and power configurations. EU Green Deal funding mechanisms accelerate hydrogen blending retrofits for existing gas turbine infrastructure. Industrial load centers in the Ruhr Valley and Bavaria anchor demand for modular fast-start plants.
China
Ultra-high-voltage transmission corridors from western solar bases to eastern load centers create volatility management needs. The MEE implements dual carbon goals that tighten emissions standards for stationary combustion sources. Yangtze River Delta manufacturing clusters procure captive peaking capacity to manage exposure to real-time pricing volatility.
India
State electricity boards in Maharashtra and Gujarat face acute ramping requirements as renewable penetration crosses critical thresholds. The CEA mandates frequency regulation standards that favor fast-start technologies over legacy thermal assets. Tamil Nadu's industrial corridors sustain demand for diesel reciprocating engines where grid reliability remains inconsistent.
Australia
The National Electricity Market experiences extreme price volatility as coal retirements accelerate and renewable output fluctuates. AEMO reforms interconnection standards to enable distributed energy resources in wholesale capacity markets. Mining clusters in Western Australia's Pilbara region maintain isolated diesel microgrids beyond transmission network reach.
Peaking Power Plant Market Competitive Environment
Listed utilities compete with private engineering specialists across technology platform choices. Merchant independent power producers unwind legacy reliance on utility offtake to pursue corporate renewable firming contracts directly. The vendor base clusters around three strategic archetypes: integrated utilities with captive renewables fleets, modular engine specialists with fast-start expertise, and industrial conglomerates with gas turbine overhaul capabilities. Competitive moves concentrate on battery-gas hybrid configuration partnerships and hydrogen blending retrofit licensing.
Within the integrated utility tier, NextEra Energy Inc. and Duke Energy Corporation exemplify players leveraging captive renewables fleets to anchor hybrid peaking configurations. Wärtsilä Oyj Abp occupies a distinct position among modular fast-start specialists, while General Electric Company and Siemens AG represent industrial conglomerates extending gas turbine expertise into battery integration services.
| Leading Market Players |
|---|
| The Southern Company |
| NextEra Energy Inc. |
| Enel S.p.A |
| Wärtsilä Oyj Abp |
| General Electric Company |
| Siemens AG |
| Duke Energy Corporation |
| ENGIE SA |
| NRG Energy Inc. |
| Others |
Value Chain & Pricing Dynamics
EPA Clean Air Act compliance deadlines for stationary combustion sources gate both supplier qualification and price differentiation, forcing asset owners toward either costly retrofit investments or accelerated replacement cycles that bifurcate the equipment market into emissions-compliant and stranded-asset tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement. Premium aero-derivative gas turbines from GE and Siemens command price premiums for sub-five-minute ramp capability. Standard frame machines face price erosion as battery storage undercuts on levelized cost in Texas and California. Economy diesel generators retain niche pricing power only in remote industrial zones where fuel logistics override emissions compliance. Independent power producers exhibit highest price sensitivity, while corporate data center buyers prioritize reliability over cost.
Supply Chain Analysis
Strait of Malacca transit security underwrites nickel and cobalt supply flows for gas turbine superalloys and battery cathode materials. Indonesia and the Democratic Republic of Congo anchor upstream mining concentration. South Korea and Japan dominate specialty steel forging for rotor components. Lithium processing draws from Chile and Argentina brine operations. Single-source vulnerability in rare earth refining creates exposure to export restriction shocks. Distribution runs through original equipment manufacturer direct sales and EPC contractor bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peaking power plant deployment sits in early-cycle expansion as corporate renewable procurement mandates create parallel demand streams for firming capacity independent of traditional utility procurement cycles.
For Market Incumbents: Fortify hydrogen blending retrofit capabilities before EU Green Deal funding windows close. Absorb Wärtsilä or MAN Energy Solutions fast-start engine specialists to anchor modular plant market share. Battery storage entrants threaten merchant gas turbine positions in ERCOT and CAISO capacity auctions.
For New Entrants and Emerging Players: Anchor in corporate renewable firming contracts with hyperscale data center operators in Northern Virginia and Phoenix. Battery-gas hybrid configurations offer the most penetrable technology wedge against entrenched gas turbine vendors. Pursue direct power purchase agreement structures that bypass utility intermediaries entirely.
For Investors and Strategic Acquirers: EPA stationary source emissions standard enforcement reshapes the acquisition landscape toward stranded-asset risk differentiation. Five-to-ten-year viability hinges on retrofit optionality versus replacement economics. Target reciprocating engine specialists with hydrogen-ready control systems. Watch FERC Order 2222 implementation pace as distributed resource market access inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Blending Retrofit Program | Extends gas turbine asset life under EU Green Deal funding mechanisms in Germany and the Netherlands. |
| Battery-Gas Hybrid Configuration Partnership | Captures premium capacity pricing in ERCOT and CAISO net-load ramp services procurement. |
| Corporate Renewable Firming Contract | Bypasses utility intermediaries to serve data center operators with sustainability-linked procurement mandates. |
| Fast-Start Reciprocating Engine Scale-Up | Meets Wärtsilä and MAN Energy Solutions technician bottlenecks through certified training program expansion. |
| Grid Code Synchronization Standardization | Reduces commercial operation date delays across divergent ISO interconnection requirements. |
Study Parameters
A spread of perspectives from utility planning officers, independent power producer project developers, EPC contractors, grid operators, and fuel supply specialists converged on the working assumptions. Primary interview insights combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition tracking and top-down regulatory impact assessment triangulated market sizing.
Segmentation dimensions modeled span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derived from installed capacity forecasts cross-referenced against technology substitution curves and emissions compliance timelines. Technology cost trajectories for lithium-ion cells and hydrogen supply chain maturation fed scenario-weighted projections across the analysis window.
Material uncertainties — battery duration cost breakthroughs, hydrogen infrastructure buildout pace, EPA enforcement stringency — sit outside the modeled envelope. Forecasts reflect assumptions about corporate procurement mandate persistence and grid operator interconnection queue reform implementation. Practitioners should keep alternative scenarios live as FERC Order 2222 distributed resource market participation rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Micro CHP Market
Power Generation
Canada Power EPC Market
Power Generation
Oilfield Power Generation Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Malaysia Power Market
Power Generation
Commercial Gensets Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
Tunisia Power Market
Power Generation
Power Plant EPC Market
Power Generation
Distributed Generation Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Iraq Power EPC Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Brazil Power Plant EPC Market