
 Redox Flow Battery Market | 2026-2036
Redox Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Redox Flow Battery Market Intelligence
Aftermarket electrolyte refurbishment and stack replacement revenue is tilting toward long-duration asset owners with twenty-year service contracts. Sumitomo Electric Industries leverages its integrated vanadium supply chain to control lifecycle costs for Japanese utility deployments. VRB Energy anchors its expansion strategy on containerized vanadium systems for China's state-grid storage tenders. Invinity Energy Systems differentiates through modular iron-chromium chemistry designed for industrial microgrids in Europe and North America.
A redox flow battery stores electrochemical energy in liquid electrolytes separated by an ion-exchange membrane, enabling independent scaling of power and energy capacity through tank volume and stack area adjustments. These systems deliver four to twelve hours of continuous discharge, making them purpose-built for shifting renewable generation across daily and seasonal demand cycles. Vanadium technology occupies the dominant share of operational capacity due to its single-element electrolyte eliminating cross-contamination. Zinc-Bromine chemistry is gaining traction in cost-sensitive utility tenders where energy density constraints are secondary to capital expenditure limits. Containerized Systems lead form-factor deployment for grid storage applications requiring rapid site commissioning and transportable asset recovery.
China's MIIT enforces GB standards for battery energy storage system safety and grid interconnection, directing domestic procurement toward certified vanadium flow manufacturers. The EU Green Deal and F-Gas Regulation are tightening environmental performance thresholds for long-duration storage competing against lithium-ion alternatives. Australia's CEA and grid operators mandate frequency response capabilities that favor flow batteries with unlimited cycling capacity. Stakeholders must monitor electrolyte leasing models and recycling infrastructure development as these determine total-cost-of-ownership competitiveness against emerging solid-state alternatives.
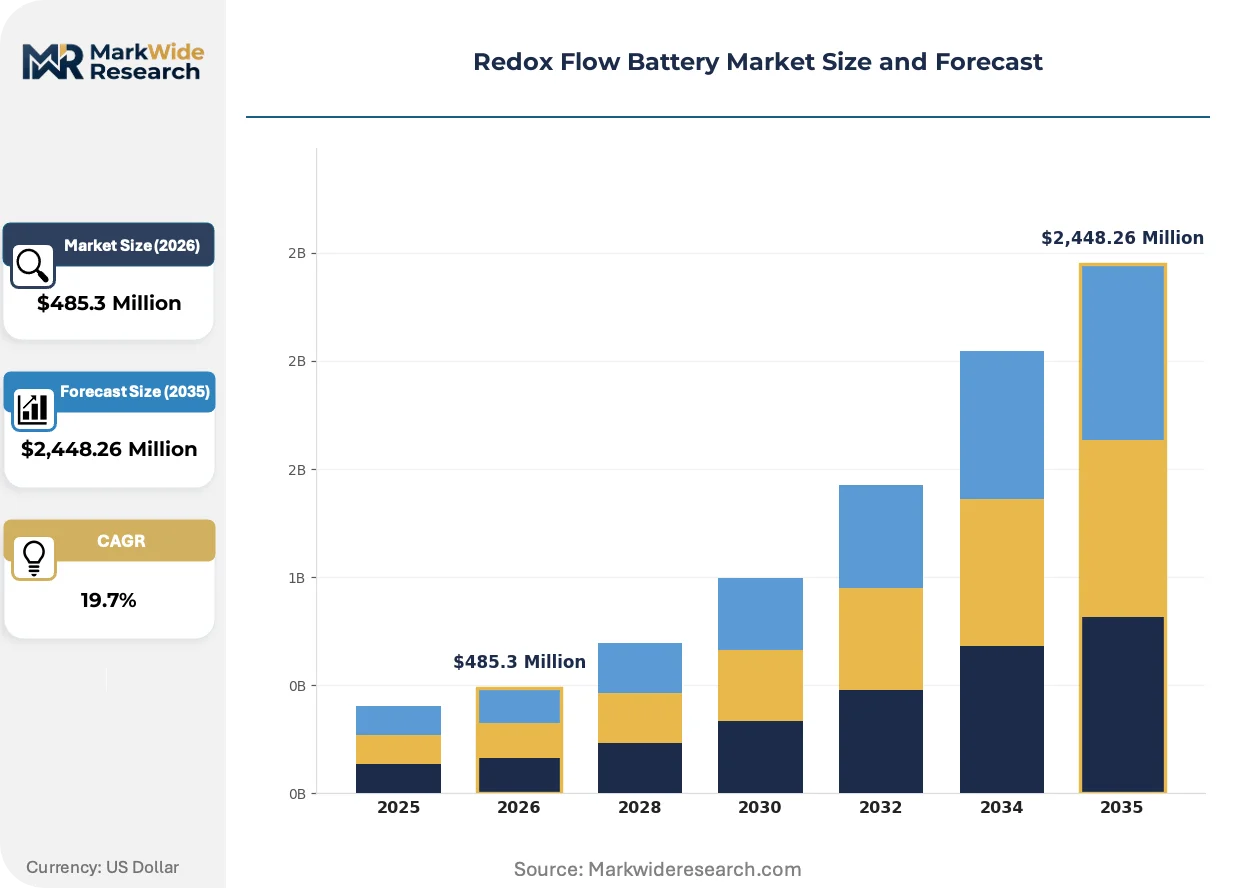
Market Dynamics
Utility-scale renewable integration mandates are compressing procurement timelines for long-duration storage, forcing developers to pre-qualify flow battery vendors before electrolyte supply chains localize. This structural pressure is redistributing competitive advantage toward manufacturers with captive vanadium refining or alternative chemistries.
Growth Catalysts
- Australia's CEA frequency response mandates:Grid operators require unlimited cycling capacity for ancillary services, disqualifying lithium-ion from certain tender categories and reserving market share for flow battery technologies.
- China's dual carbon goals:State-grid storage tenders now specify domestic electrolyte production, redirecting manufacturing investment toward vanadium refining capacity expansion.
- Vanadium single-element chemistry:Elimination of cross-contamination risk reduces operational complexity for utility asset managers evaluating twenty-year service contracts.
Market Restraints
- Vanadium price volatility:Steel industry demand fluctuations for ferrovanadium feedstock create input cost uncertainty that compresses project financing margins.
- China supply concentration:Domestic electrolyte production capacity dominates global vanadium pentoxide refining, creating geographic single-point-of-failure risk for non-Chinese developers.
- Energy density constraints:Zinc-bromine and vanadium systems require larger footprints than lithium-ion alternatives, limiting deployment in land-constrained urban substations.
Strategic Opportunities
- India's renewable purchase obligations:State electricity regulators mandate storage co-location for solar parks, creating first-mover advantage for containerized flow battery vendors.
- Electrolyte leasing models:Asset-light financing structures separate energy ownership from chemistry ownership, reducing upfront capex barriers for industrial microgrid adopters.
- Iron-chromium chemistry convergence:Abundant raw material availability enables cost positioning below vanadium systems for price-sensitive utility tenders.
Industry Challenges
- Membrane stack manufacturing skill scarcity:Ion-exchange membrane fabrication requires polymer chemistry expertise concentrated in fuel cell industries, creating hiring bottlenecks for scale-up operations.
- GB standards compliance timelines:China's MIIT certification process for battery energy storage system safety extends product qualification cycles, delaying revenue recognition for new market entrants.
- Legacy SCADA integration complexity:Utility control systems require custom protocol translation for flow battery management systems, inflating commissioning costs and project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Redox Flow Battery Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $2,448.26 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vanadium, Zinc-Bromine, Iron-Chromium, Organic Flow Batteries Application: Grid Storage, Renewable Integration, Backup Power, Electric Vehicle Charging End User: Utilities, Industrial Sector, Commercial Facilities, Residential Users Form Factor: Containerized Systems, Modular Units, Large Scale Installations, Small Scale Solutions |
| Companies Covered | Rongke Power, VRB Energy, Sumitomo Electric Industries, SCHMID Group, Largo Inc., Invinity Energy Systems, ESS Inc., Primus Power, CellCube (Enerox GmbH), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Redox Flow Battery Market Strategic Shifts & Innovations
Electrolyte formulation advances and modular system architectures are compressing installation timelines while regulatory pressure on battery safety is hardening procurement specifications. These forces are converging to reposition flow batteries within the long-duration storage hierarchy.
Hybrid vanadium-organic redox couples are hybridizing electrochemical stability with cost reduction potential. European industrial microgrid operators are piloting these formulations for eight-to-ten hour discharge applications. The technology is hybridizing the performance envelope between conventional vanadium systems and emerging organic alternatives, forcing incumbent suppliers to accelerate R&D timelines or cede mid-duration market segments.
The EU F-Gas Regulation is tightening containment requirements for fluorinated membrane materials used in ion-exchange separators. Industrial consequences include accelerated qualification of hydrocarbon-based membrane alternatives and supply contract renegotiations for stack manufacturers. German and Dutch utility procurement teams are now specifying fluorine-free membrane stacks for projects above fifty megawatt-hours, compressing the addressable market for incumbent membrane suppliers.
Asset owners are unbundling after-sales service contracts from initial equipment supply, creating standalone revenue pools for electrolyte refurbishment and stack replacement specialists. This behavior shift fragments the traditional single-vendor model and opens channel entry points for third-party service providers. The pattern is most visible in Australian utility deployments where twenty-year service contracts now specify competitive tendering for major maintenance events.
Redox Flow Battery Market Segmentation
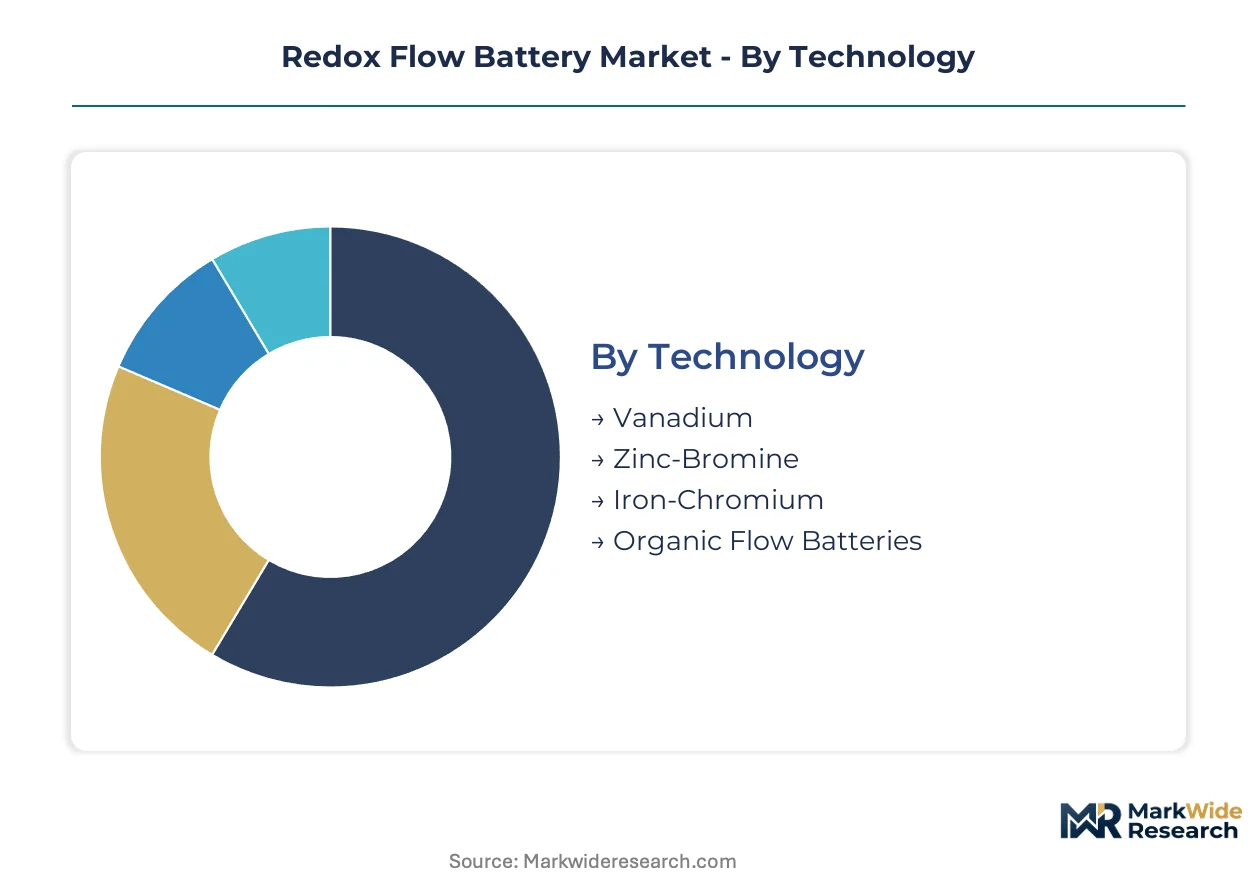
Technology chemistry and deployment scale determine financing structures and service contract terms across redox flow battery procurement. Application requirements and end-user risk profiles further stratify vendor selection criteria and electrolyte ownership models.
Technology:
Electrochemical stability and raw material availability define the use-case spectrum from utility-scale tenders to industrial microgrids.
- Vanadium:Single-element electrolyte eliminates cross-contamination and enables indefinite cycling without capacity degradation. Australia's CEA frequency response mandates reserve tender categories for this chemistry due to unlimited cycling capacity requirements.
- Zinc-Bromine:Lower capital cost positioning suits cost-sensitive utility tenders where energy density constraints are secondary. India's renewable purchase obligations for solar park storage are concentrating procurement toward this chemistry for price-sensitive state electricity regulators.
- Iron-Chromium:Abundant raw materials enable cost positioning below vanadium systems. Industrial microgrid deployments in land-constrained European facilities favor this chemistry for mid-duration discharge applications.
- Organic Flow Batteries:Hybrid vanadium-organic couples are piloting eight-to-ten hour discharge for European industrial operators seeking electrochemical stability with cost reduction.
The dominant share belongs to Vanadium, while Zinc-Bromine is closing the gap fastest.
Application:
Discharge duration requirements and grid interconnection standards segment procurement by revenue model and asset ownership structure.
- Grid Storage:Four-to-twelve hour continuous discharge shifts renewable generation across daily demand cycles. China's state-grid storage tenders specify domestic electrolyte production, redirecting manufacturing investment toward vanadium refining capacity.
- Renewable Integration:Co-location mandates for solar and wind farms require long-duration cycling without degradation. Australia's tightening renewable portfolio standards are compressing procurement timelines for pre-qualified flow battery vendors.
- Backup Power:Critical facility resilience applications prioritize immediate response over cycling economics. Commercial facilities in the United States specify containerized systems for rapid site commissioning.
- Electric Vehicle Charging:Peak shaving and demand charge management for high-power charging stations. Land constraints at urban substations limit deployment to modular units with smaller footprints.
Grid Storage commands the largest installed base, though Renewable Integration is expanding most quickly as portfolio standards tighten across multiple jurisdictions.
End User:
Capital availability and technical expertise determine electrolyte ownership models and service contract structures.
- Utilities:Twenty-year service contracts with competitive tendering for major maintenance events. Australian deployments now specify standalone revenue pools for electrolyte refurbishment and stack replacement.
- Industrial Sector:Behind-the-meter applications with custom SCADA integration requirements. German and Dutch procurement teams specify fluorine-free membrane stacks for projects above fifty megawatt-hours.
- Commercial Facilities:Asset-light financing through electrolyte leasing models reduces upfront capex barriers. Containerized systems enable transportable asset recovery for multi-site operators.
- Residential Users:Limited penetration due to system footprint requirements and installation complexity. Small scale solutions face competition from lithium-ion alternatives in space-constrained applications.
Utilities retain the dominant procurement volume, while Industrial Sector adoption is climbing the fastest as microgrid resilience investments accelerate.
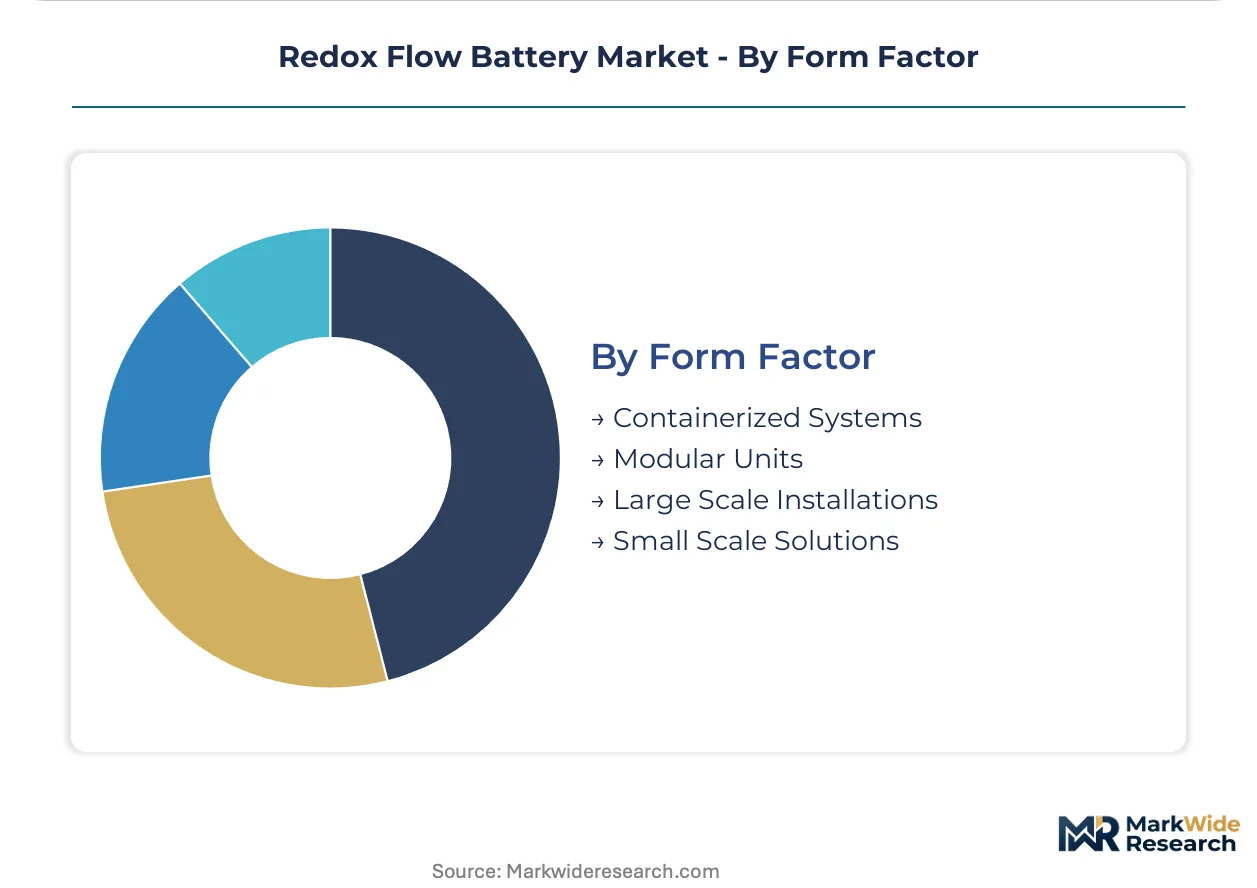
Form Factor:
Site constraints and commissioning timelines drive selection between factory-integrated and field-assembled configurations.
- Containerized Systems:Factory-integrated power conversion and thermal management enable rapid site commissioning. Grid storage applications requiring transportable asset recovery favor this form factor for utility-scale deployments.
- Modular Units:Independent scaling of power and energy capacity through stack area and tank volume adjustments. Industrial microgrids in Europe and North America specify this architecture for phased capacity expansion.
- Large Scale Installations:Custom-engineered tank farms and multi-stack arrays for hundred-megawatt-hour projects. China's MIIT GB standards compliance extends qualification cycles for these configurations.
- Small Scale Solutions:Skid-mounted or building-integrated systems for commercial and residential applications. Limited addressable market due to lithium-ion cost competitiveness at smaller capacities.
Containerized Systems hold the leading deployment share, with Modular Units gaining share fastest as industrial microgrid specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement in India and Australia contrasts with premium-tolerance in Japan and Germany, where twenty-year service contracts dominate financing structures. China's state-directed procurement sits between these poles, favoring domestic supply security over pure cost minimization.
China
State-grid storage tenders specify domestic electrolyte production, redirecting manufacturing investment toward vanadium refining capacity expansion. MIIT enforces GB standards for battery energy storage system safety and grid interconnection, directing procurement toward certified domestic manufacturers. Sichuan and Hubei provinces concentrate vanadium pentoxide refining operations serving state-grid deployment clusters.
Australia
CEA frequency response mandates require unlimited cycling capacity for ancillary services, disqualifying lithium-ion from certain tender categories. Tightening renewable portfolio standards compress procurement timelines for pre-qualified flow battery vendors. Queensland and New South Wales host utility-scale renewable integration projects specifying containerized systems for rapid site commissioning.
United States
FERC Order 2222 aggregation rules enable distributed energy resource participation in wholesale markets, expanding addressable demand for modular flow battery systems. IRA production tax credits reduce capital cost barriers for long-duration storage deployments. Texas and California concentrate utility-scale procurement, with industrial microgrid adoption accelerating across the Midwest manufacturing belt.
Japan
METI long-term decarbonization targets mandate grid-scale storage deployment to accommodate renewable generation expansion. Utility procurement teams specify twenty-year service contracts with competitive tendering for electrolyte refurbishment and stack replacement. Osaka and Tokyo metropolitan areas concentrate demonstration projects integrating flow batteries with existing transmission infrastructure.
Germany
EU F-Gas Regulation tightens containment requirements for fluorinated membrane materials, accelerating qualification of hydrocarbon-based membrane alternatives. Industrial procurement teams specify fluorine-free membrane stacks for projects above fifty megawatt-hours. North Rhine-Westphalia and Bavaria host industrial microgrid deployments favoring modular iron-chromium chemistry for mid-duration applications.
Redox Flow Battery Market Key Industry Players
Capability concentration sits with integrated electrolyte producers; scale advantage sits with containerized system fabricators. The vendor base stratifies across three tiers: captive vanadium refiners controlling input costs, modular architecture specialists serving industrial microgrids, and project developers bundling financing with equipment supply. Strategic moves center on backward integration into electrolyte production and geographic expansion through state-grid tender pre-qualification.
Among Asia-Pacific-based integrated manufacturers, Sumitomo Electric Industries and VRB Energy exemplify the captive supply chain archetype, while Invinity Energy Systems occupies a position within the modular system specialist tier. Rongke Power anchors the domestic Chinese supplier category, benefiting from state-grid procurement localization requirements. These named entities represent distinct competitive positioning strategies rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Rongke Power |
| VRB Energy |
| Sumitomo Electric Industries |
| SCHMID Group |
| Largo Inc. |
| Invinity Energy Systems |
| ESS Inc. |
| Primus Power |
| CellCube (Enerox GmbH) |
| Others |
Cost & Logistics Intelligence
Undercapacity in ion-exchange membrane fabrication is compressing stack manufacturing timelines and inflating procurement premiums for utility-scale developers. This bottleneck simultaneously elevates electrolyte refurbishment margins for aftermarket service providers and redirects capital toward captive vanadium refining investments.
Pricing Analysis
Aftermarket electrolyte refurbishment and stack replacement revenue drives lifetime value for asset owners holding twenty-year service contracts. Three-tier pricing structure across premium, standard, and economy levels separates certified vanadium systems from zinc-bromine alternatives and emerging iron-chromium configurations. Cost compression in containerized system deployments is intensifying as Chinese state-grid tenders mandate domestic electrolyte production. Industrial microgrid operators exhibit the highest price sensitivity due to land constraints and phased capacity expansion requirements, while Japanese utilities tolerate premium positioning for integrated lifecycle service bundling.
Supply Chain Analysis
Contract manufacturing concentration in vanadium pentoxide refining sits with Sichuan and Hubei province operations serving state-grid deployment clusters. The supply chain draws from South African and Russian vanadium feedstock, Chinese membrane fabrication capacity, and German hydrocarbon-based membrane alternatives. Single-source vulnerability in Chinese electrolyte production creates geographic concentration risk for non-domestic developers. Distribution runs through EPC contractors bundling financing with equipment supply for utility-scale tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procurement unbundles equipment supply from aftermarket service, creating standalone revenue pools for electrolyte refurbishment specialists and opening channel entry points beyond traditional single-vendor relationships.
For Market Incumbents: Pre-empt margin erosion in containerized system fabrication by securing captive vanadium refining capacity in Sichuan or Hubei provinces before state-grid tender localization requirements harden. Accelerate hydrocarbon-based membrane qualification to meet EU F-Gas Regulation specifications for fluorine-free stacks above fifty megawatt-hours.
For New Entrants and Emerging Players: Build out iron-chromium chemistry manufacturing for Indian solar park storage tenders where renewable purchase obligations concentrate price-sensitive procurement. Target Australian CEA frequency response mandates as the most penetrable application segment, leveraging unlimited cycling capacity requirements that disqualify lithium-ion alternatives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrolyte leasing model operators with twenty-year utility service contracts. Long-term viability across the projection horizon favors acquisition targets with backward integration into vanadium refining or hydrocarbon membrane fabrication. Watch for inflection in India's state electricity regulator storage mandates as the signal for accelerated capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vanadium Refining | Captive supply of electrolyte feedstock secures margin control for Chinese state-grid tenders. |
| Fluorine-Free Membrane Qualification | EU F-Gas Regulation compliance opens German and Dutch utility procurement above fifty megawatt-hours. |
| Electrolyte Leasing Model Deployment | Asset-light financing reduces upfront capex barriers for industrial microgrid adopters in Europe. |
| Containerized System Manufacturing Scale-Up | Factory-integrated thermal management enables rapid site commissioning for Australian renewable integration. |
| Iron-Chromium Chemistry Commercialization | Abundant raw material availability positions below vanadium systems for India's price-sensitive state regulators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, IPP project developers, EPC contractors, and vanadium refining plant managers. Secondary validation drew from EIA storage deployment data, IEA long-duration technology reports, FERC Order 2222 implementation filings, and project development databases tracking state-grid tender awards. Bottom-up capacity installation estimates triangulated against top-down policy mandate trajectories.
Calibration against historical deployment velocity across technology chemistry segments shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include electrochemical system type, discharge duration tier, project scale classification, and regional regulatory framework cluster. CAGRs were derived from policy mandate acceleration curves and electrolyte supply chain localization timelines. Forecast inputs incorporated vanadium price volatility indices and membrane manufacturing capacity utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-directed manufacturers or abrupt vanadium export restrictions would shift outcomes. Quarterly review of MIIT GB standards certification timelines and Indian state electricity regulator storage mandate announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Vanadium Redox Batteries Market
Batteries
Modular Battery Pack Market
Batteries
Norway Rechargeable Battery Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Sodium-Air Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
Rechargeable Battery Market
Batteries
Aluminum Based Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
Italy SLI Battery Market
Batteries
GCC Rechargeable Battery Market