
 Canada Power EPC Market | 2026-2036
Canada Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Power EPC Market Outlook
Utility-grade project specifications is collapsing the gap between traditional fossil and renewable EPC contracting in Canada. Stantec Inc. leverages its integrated design-build capability to anchor large-scale hydroelectric retrofits in British Columbia. EllisDon Corporation competes through its self-perform construction model that controls labor scheduling across nuclear refurbishment sites in Ontario.
Canada Power EPC encompasses the full-scope engineering, procurement, and construction of electricity generation, transmission, and distribution infrastructure, typically executed under lump-sum turnkey or cost-reimbursable contracts with performance guarantees on output capacity and grid-code compliance. The primary purpose is delivering capital-intensive energy assets from conceptual design through commissioning under fixed schedule and budget constraints. Solar and wind technology segments now attract the dominant share of new contractor bookings as provincial integrated resource plans prioritize zero-emission capacity additions. Grid-connected deployment configurations command the deepest margin pools due to their scale economies and streamlined interconnection standards with provincial transmission operators.
Health Canada and PMRA oversee environmental assessment protocols for large power projects, while provincial regulators including the Alberta Utilities Commission and Ontario Energy Board set interconnection technical standards and cost-recovery frameworks that directly shape contractor qualification requirements. The Canadian Standards Association and IEEE 1547-series grid interconnection standards further constrain equipment specifications and commissioning protocols for distributed and utility-scale assets. Stakeholders must monitor how the federal Clean Electricity Regulations tighten performance benchmarks and whether provincial permitting timelines compress to match contractor availability.
Market Dynamics
Federal investment tax credits for clean technology are compressing contractor mobilization timelines across Canada's power infrastructure sector, forcing EPC firms to restructure resource allocation models around accelerated renewable deployment schedules.
Growth Catalysts
- Clean Electricity Regulations:Federal performance benchmarks mandate zero-emission capacity additions, creating guaranteed procurement pipelines for grid-connected solar and wind installations.
- Ontario nuclear refurbishment:Provincial integrated resource plans prioritize baseload reliability, sustaining long-cycle EPC contracts for reactor life-extension projects.
- Alberta Utilities Commission interconnection standards:Streamlined technical protocols reduce commissioning delays, improving project IRR visibility for Prairie province developments.
Market Restraints
- Skilled trades concentration:Heavy construction labor pools concentrate in Ontario and British Columbia, creating mobilization bottlenecks for remote northern hydroelectric sites.
- Steel and copper input volatility:Transmission infrastructure fabrication depends on commodity-priced conductors, compressing fixed-price contract margins without escalation clauses.
- Provincial permitting fragmentation:Environmental assessment timelines vary across Quebec, Alberta, and British Columbia, extending pre-construction phases beyond contractor availability windows.
Strategic Opportunities
- Indigenous partnership frameworks:Equity participation models in British Columbia and northern territories unlock access to hydroelectric and transmission corridors previously constrained by land-claim negotiations.
- Grid-scale battery integration:Hybrid solar-plus-storage configurations in Alberta create new EPC scope bundles combining generation and duration assets under single turnkey contracts.
- Small modular reactor deployment:Saskatchewan and New Brunswick regulatory readiness for advanced nuclear creates first-mover positioning for firms with CNSC pre-licensing engagement.
Industry Challenges
- Commissioning engineer scarcity:Specialized grid-code compliance certification for IEEE 1547-series interconnection standards exceeds current training pipeline output, delaying project handovers.
- Multi-jurisdictional procurement coordination:Federal funding stacking with provincial clean electricity programs requires dedicated compliance staff to navigate overlapping application windows and reporting requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Power EPC Market |
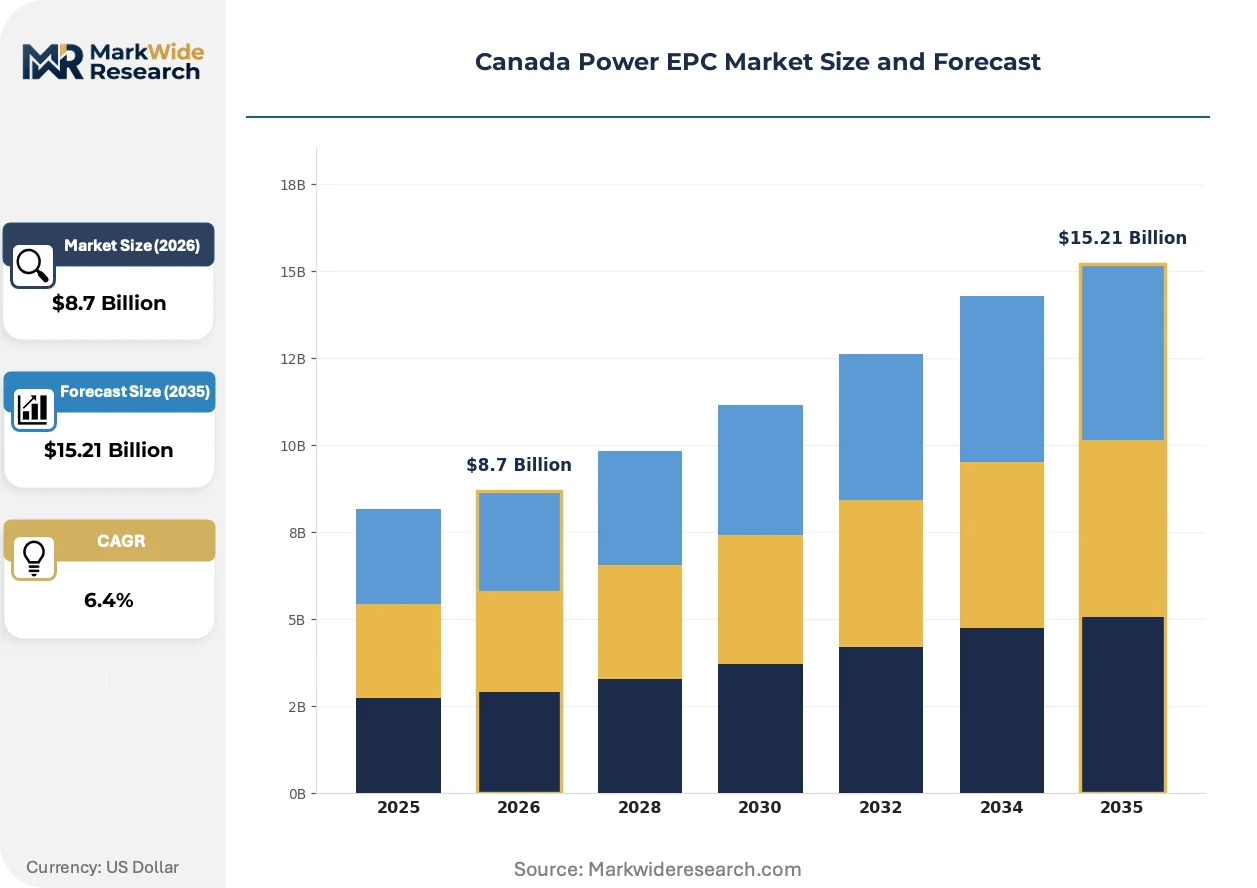
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Project Management Technology: Solar, Wind, Hydro, Biomass End User: Utilities, Industrial, Commercial, Government Deployment: Onshore, Offshore, Grid-Connected, Off-Grid |
| Companies Covered | CIMA+ Canada Inc., Stantec Inc., Valard Construction Ltd., EllisDon Corporation, PCL Construction Inc., Bantrel Co., Canadian Solar Inc., NorthGrid Solar Inc., Aecon Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Power EPC Market Strategic Shifts
Modular construction methodologies are compressing field assembly schedules for renewable generation assets, while digital twin deployment redefines commissioning protocols across Canada's provincial transmission networks.
Prefabricated electrical substations are decomposing traditional stick-built construction timelines for utility-scale solar farms. Alberta and Saskatchewan developers now specify factory-integrated switchgear and transformer modules to compress interconnection readiness. This approach is decomposing the conventional EPC phase-gate structure into parallel manufacturing and civil workstreams.
Health Canada and PMRA environmental assessment protocols are tightening cumulative effects analysis requirements for large power projects. Industrial consequence includes expanded baseline studies and extended consultation periods with Indigenous communities. Hydroelectric retrofit segments in British Columbia face the most pronounced timeline compression pressures as firms pre-position biophysical field teams.
Integrated design-build contracting is displacing traditional engineer-procure-construct sequential awards for nuclear refurbishment programs. Ontario Power Generation and Bruce Power now favor single-source accountability models that internalize interface risk. This pattern concentrates most visibly in the Golden Horseshoe corridor where labor mobility supports continuous site staffing.
Canada Power EPC Market Segmentation
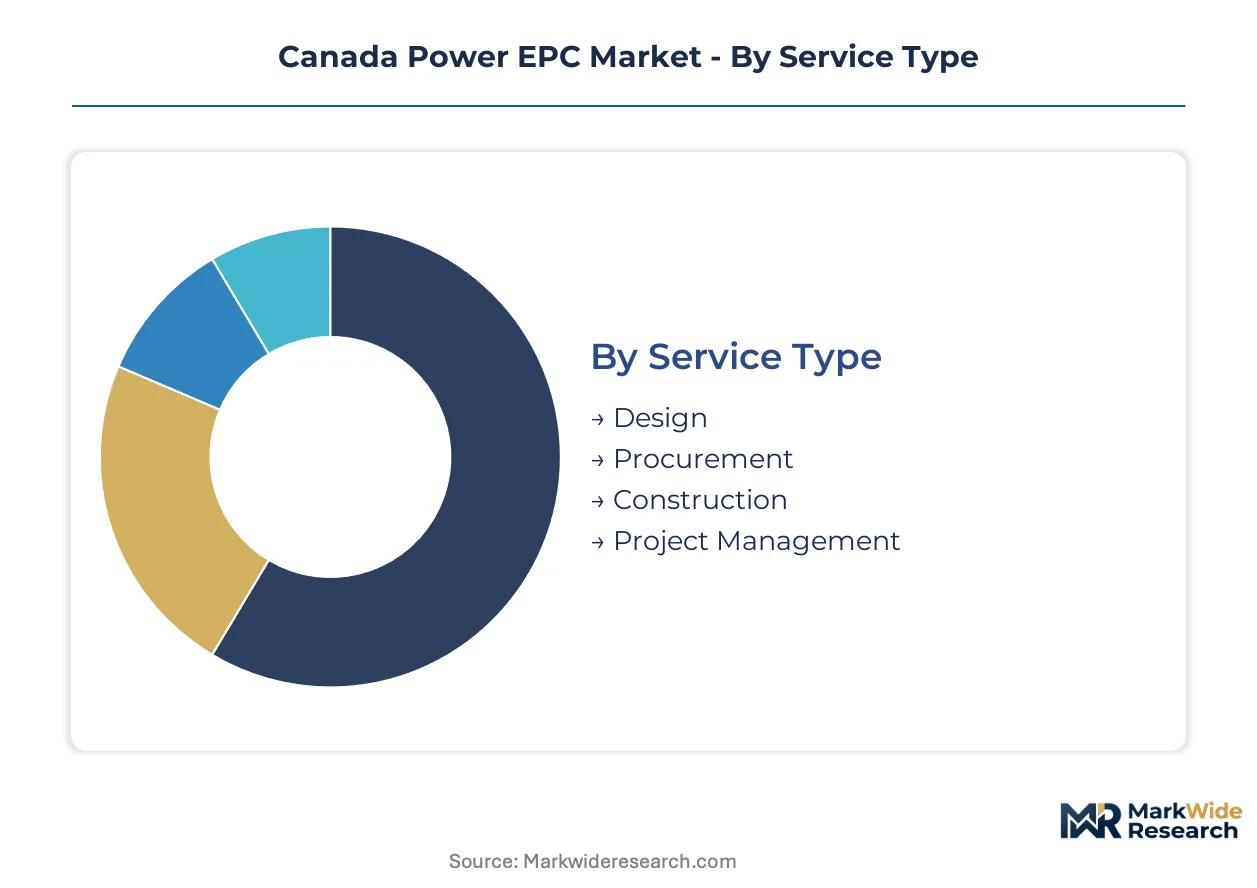
Power EPC contractors in Canada structure their service portfolios around distinct procurement patterns across provincial utilities and private developers. Segment boundaries determine margin profiles, risk allocation, and the specialized certifications required for market entry.
Service Type:
Engineering and construction services for Canadian power infrastructure split between domestic capability centers and cross-border specialist mobilization. Ontario and Quebec host the deepest design and project management talent pools, while procurement functions increasingly integrate with U.S. supply chains for major equipment packages.
- Design:Front-end engineering packages for hydroelectric retrofits and nuclear refurbishment dominate technical staffing in British Columbia and Ontario. Provincial utilities specify Canadian Standards Association compliance and Health Canada environmental protocols, limiting foreign engineering house participation without domestic partnership structures.
- Construction:Self-perform labor models concentrate in Ontario's nuclear corridor and Alberta's solar belt, where EllisDon and PCL Construction control craft scheduling through direct hiring rather than subcontractor tiers. Remote northern hydroelectric sites face mobilization bottlenecks due to skilled trades concentration in southern provinces.
- Procurement:Equipment sourcing for grid-connected solar and wind assets integrates U.S. inverter and turbine supply chains with Canadian balance-of-plant fabrication.
- Project Management:Integrated design-build accountability models displace sequential EPC awards for Ontario nuclear refurbishment, compressing interface risk into single-source contracts.
Construction holds the largest share; momentum sits with Project Management as single-source accountability models expand.
Technology:
Technology segments in Canadian power EPC reflect provincial integrated resource plan priorities and federal Clean Electricity Regulations performance benchmarks. Prairie provinces anchor utility-scale renewable deployment, while British Columbia and Quebec sustain hydroelectric dominance.
- Solar:Photovoltaic EPC contracts concentrate in Alberta and Saskatchewan where Alberta Utilities Commission interconnection standards streamline grid-code compliance. Factory-integrated substation modules compress commissioning timelines, with prefabricated switchgear specifications now standard for utility-scale farms.
- Wind:Onshore turbine installation commands the deepest margin pools across the Prairie provinces due to scale economies and established supply chains. Saskatchewan and Manitoba procurement pipelines favor wind for capacity additions that match federal zero-emission benchmarks without transmission infrastructure constraints.
- Hydro:Retrofit and run-of-river development dominates British Columbia and Quebec, with Indigenous partnership frameworks unlocking previously constrained transmission corridors.
- Biomass:Cogeneration installations serve northern Ontario and British Columbia forest products sectors under provincial renewable portfolio obligations.
Solar holds the largest share; Biomass is climbing the fastest as industrial heat decarbonization tightens compliance deadlines.
End User:
Customer segments diverge sharply in procurement sophistication and contract structure preferences. Provincial utilities command standardized technical specifications, while industrial offtakers negotiate bespoke performance guarantees.
- Utilities:Ontario Power Generation and provincial crown corporations drive nuclear refurbishment and hydroelectric retrofit demand through lump-sum turnkey awards with decade-long execution horizons.
- Industrial:Alberta oil sands operators and British Columbia mining consortiums procure behind-the-meter solar and combined heat-and-power assets under power purchase agreement structures that transfer operational risk to contractors.
- Commercial:Retail and data center developers in Toronto and Vancouver specify distributed solar with battery integration, constrained by municipal permitting timelines and IEEE 1547-series interconnection certification delays.
- Government:Federal and provincial infrastructure programs stack investment tax credits with clean electricity funding, requiring dedicated compliance staff to navigate overlapping application windows.
Utilities hold the largest share; Commercial is gaining share fastest as behind-the-meter deployment accelerates in major metropolitan markets.
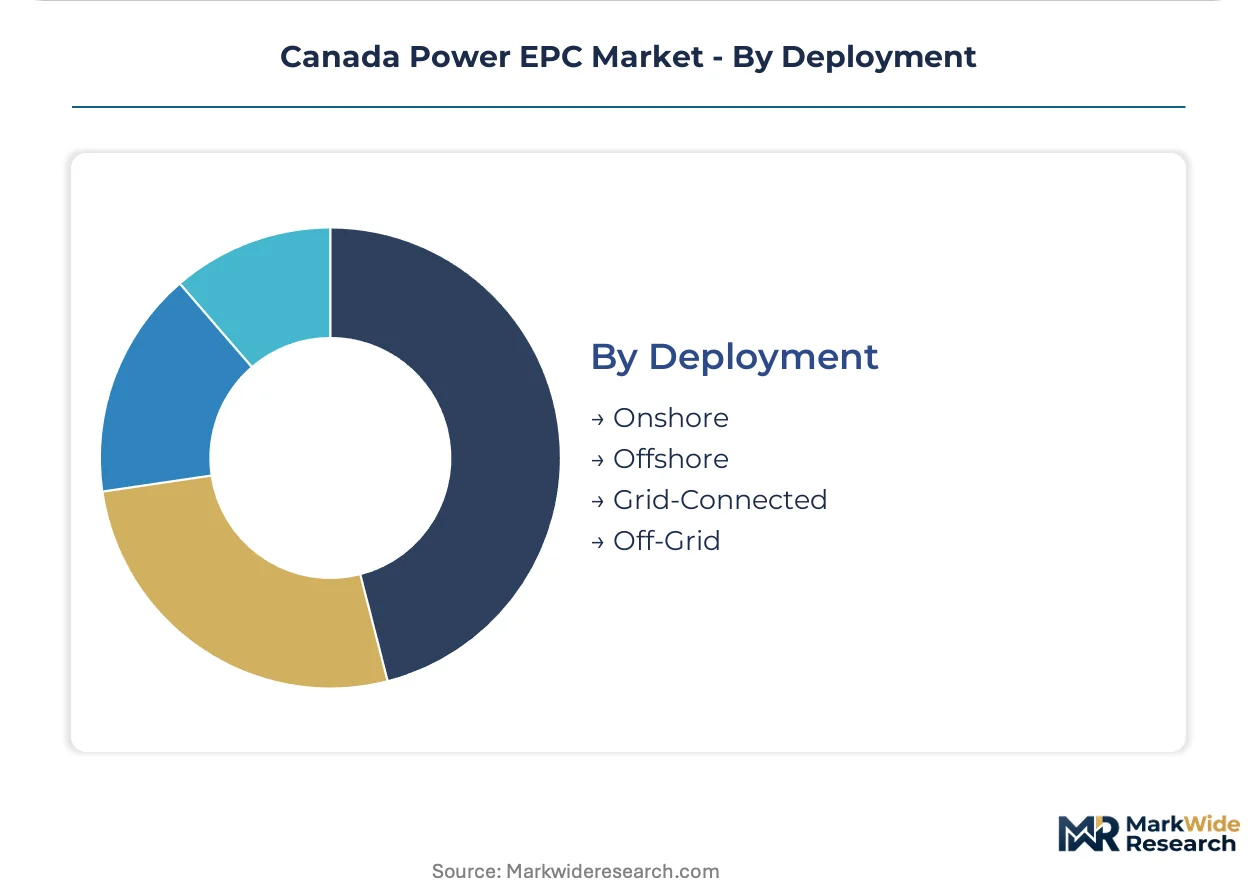
Deployment:
Configuration segments reflect geography-driven interconnection economics and provincial transmission operator technical standards. Grid-connected assets dominate contractor bookings due to streamlined cost-recovery frameworks.
- Grid-Connected:Utility-scale solar and wind installations across Alberta, Saskatchewan, and Ontario connect directly to provincial transmission networks under standardized interconnection protocols. These configurations command premium margins through scale economies and reduced commissioning uncertainty.
- Onshore:Land-based renewable development encompasses the full technology stack, with Prairie province wind and Ontario solar representing the highest-volume addressable market.
- Off-Grid:Remote community electrification in northern territories and Indigenous settlements relies on diesel hybridization with solar-battery microgrids, constrained by logistics costs and seasonal access limitations.
- Offshore:Atlantic Canada floating wind pilot programs in Nova Scotia and Newfoundland represent pre-commercial opportunity with specialized marine construction requirements and extended regulatory timelines.
Grid-Connected holds the largest share; Offshore shows the steepest expansion trajectory as Atlantic provinces advance floating wind regulatory frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario buyers prioritize single-source accountability for decade-long nuclear refurbishment cycles, while Alberta developers favor accelerated procurement for utility-scale solar with streamlined interconnection protocols. Quebec and British Columbia crown corporations maintain price stability through hydroelectric dominance, insulating their EPC markets from renewable commodity volatility.
Ontario
Ontario Power Generation and Bruce Power drive reactor life-extension demand through lump-sum turnkey awards spanning multiple years. The Ontario Energy Board sets cost-recovery frameworks and technical standards that shape contractor qualification requirements. The Golden Horseshoe corridor concentrates nuclear construction labor pools, enabling continuous site staffing for integrated design-build contracts.
Alberta
Utility-scale solar and wind installations dominate contractor bookings as the Alberta Utilities Commission streamlines grid-code compliance protocols. Federal investment tax credits for clean technology compress mobilization timelines across the province. Calgary and Edmonton anchor procurement activity for Prairie province developments with prefabricated substation specifications now standard.
British Columbia
Hydroelectric retrofits and run-of-river development sustain long-cycle EPC demand through BC Hydro and Indigenous partnership frameworks. Health Canada and PMRA environmental assessment protocols tighten cumulative effects analysis requirements for large power projects. The Lower Mainland hosts design talent pools while northern sites face mobilization bottlenecks due to skilled trades concentration in southern provinces.
Quebec
Hydro-Québec maintains provincial energy dominance through crown corporation procurement of transmission and generation infrastructure. The Canadian Standards Association and provincial regulators constrain equipment specifications for grid interconnection. Montreal and Quebec City concentrate engineering capabilities for francophone project execution across provincial and northern territory developments.
Saskatchewan
Saskatchewan Power Corporation procurement pipelines favor wind capacity additions matching federal zero-emission benchmarks. The province's regulatory readiness for small modular reactor deployment creates positioning opportunities for firms with Canadian Nuclear Safety Commission pre-licensing engagement. Saskatoon and Regina anchor utility procurement while remote community electrification relies on diesel hybridization with solar-battery microgrids.
Canada Power EPC Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Canada's power EPC sector. Integrated design-build specialists command premium positioning for nuclear and hydroelectric retrofits through single-source accountability models. Self-perform construction firms compete on labor scheduling control and direct craft hiring rather than subcontractor tiers. The dominant competitive moves center on Indigenous partnership frameworks for corridor access and modular construction methodologies for renewable commissioning compression.
Among Canadian engineering and construction houses, Stantec Inc. and EllisDon Corporation exemplify contrasting strategic archetypes. Stantec anchors large-scale infrastructure through integrated design-build capability concentrated in provincial utility relationships. EllisDon occupies a position defined by self-perform labor models that control construction scheduling across complex site environments. Valard Construction Ltd. represents the transmission and distribution specialist tier with established mobilization networks for remote northern deployment. These three firms collectively illustrate how domestic capability centers compete against cross-border specialist mobilization for major equipment packages and technical staffing.
| Leading Market Players |
|---|
| CIMA+ Canada Inc. |
| Stantec Inc. |
| Valard Construction Ltd. |
| EllisDon Corporation |
| PCL Construction Inc. |
| Bantrel Co. |
| Canadian Solar Inc. |
| NorthGrid Solar Inc. |
| Aecon Group Inc. |
| Others |
Value Chain & Pricing Dynamics
Prefabricated substation modules replacing stick-built electrical infrastructure are simultaneously relocating manufacturing capacity to U.S. Gulf Coast fabrication hubs and compressing field labor pricing premiums for Canadian solar developers. This substitution dynamic collapses the traditional phase-gate structure into parallel workstreams, redistributing margin capture from civil contractors to equipment integrators while exposing projects to cross-border logistics volatility.
Pricing Analysis
Long-term service and refurbishment contracts anchor lifetime value for nuclear and hydroelectric EPC providers, with Ontario Power Generation's decade-long reactor life-extension awards embedding multi-cycle maintenance revenue. Three-tier pricing structure across integrated design-build, hybrid EPC, and pure construction separates risk allocation models, with single-source accountability commanding premium positioning. Cost compression in renewable EPC is intensifying because factory-integrated equipment packages standardize scope and reduce customization premiums. Industrial offtakers in Alberta oil sands exhibit highest price sensitivity due to power purchase agreement structures that transfer operational risk, while provincial utilities show lowest sensitivity given cost-recovery frameworks.
Supply Chain Analysis
Port congestion at Vancouver and Prince Rupert, combined with container availability constraints on Asia-Pacific trade lanes, elevates inbound logistics costs for inverter and turbine equipment bound for Prairie province solar and wind sites. Equipment sourcing draws from U.S. inverter manufacturers, Chinese module suppliers, and European turbine OEMs, with Canadian balance-of-plant fabrication anchoring domestic content requirements. Copper conductor and structural steel dependencies expose contractors to commodity price volatility without escalation clauses in fixed-price awards. Distribution runs through provincial transmission operators with standardized interconnection protocols, though remote northern hydroelectric sites face single-source mobilization vulnerabilities from skilled trades concentration in Ontario and British Columbia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's power EPC market is approaching a platform-economics inflection as modular construction methodologies and digital twin deployment create interoperability standards that favor ecosystem orchestrators over pure-play contractors.
For Market Incumbents: Fortify integrated design-build capabilities through captive engineering talent retention in Ontario's nuclear corridor and British Columbia's hydroelectric markets, where Stantec's provincial utility relationships create switching-cost barriers. Deepen backward integration into prefabricated electrical substation manufacturing to capture margin pools migrating from field assembly to factory integration, insulating against EllisDon's self-perform labor scheduling advantages. For New Entrants and Emerging Players: Anchor in Saskatchewan's small modular reactor pre-licensing engagement pipeline, where Canadian Nuclear Safety Commission regulatory readiness creates first-mover positioning without incumbent crowding. Target Atlantic Canada floating wind pilot programs in Nova Scotia and Newfoundland, where specialized marine construction requirements and extended timelines deter established Prairie province contractors. Pursue Indigenous partnership frameworks as the primary go-to-market angle for transmission corridor access in British Columbia and northern territories. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated design-build specialists with decade-long utility relationships and modular construction IP. Long-term viability over the next decade hinges on exposure to nuclear refurbishment and grid-scale battery integration rather than commoditized solar EPC. Target acquisition archetypes include transmission and distribution specialists with northern mobilization networks and firms with Canadian Standards Association certification depth. Watch for Clean Electricity Regulations enforcement tightening as the signal indicating accelerated procurement velocity and contractor pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Design-Build Capability Expansion | Single-source accountability compresses interface risk for Ontario nuclear refurbishment awards. |
| Prefabricated Substation Manufacturing Scale-Up | Factory integration displaces stick-built timelines for Alberta utility-scale solar interconnection. |
| Indigenous Partnership Framework Formalization | Equity participation unlocks British Columbia hydroelectric transmission corridor access. |
| Small Modular Reactor Pre-Licensing Engagement | CNSC regulatory readiness positions first-mover advantage in Saskatchewan and New Brunswick. |
| Grid-Scale Battery Integration Scope Bundling | Hybrid solar-plus-storage contracts combine generation and duration assets under single turnkey awards. |
Study Parameters
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base, supplemented by regulatory filings with the Alberta Utilities Commission and Ontario Energy Board, Health Canada environmental assessment protocols, Canadian Standards Association technical standards, and federal Clean Electricity Regulations documentation. Secondary validation drew from EIA North American electricity data, IEA renewable deployment reports, and provincial integrated resource plan disclosures. Bottom-up project pipeline enumeration triangulated against top-down provincial capacity addition targets to establish market sizing.
Sensitivity analysis across commodity price scenarios, interconnection timeline variations, and regulatory enforcement intensity informed the projection framework. Segmentation dimensions modeled encompass service type, technology, end user, and deployment configuration across the analysis window. CAGRs derived from fitted growth curves applied to provincial procurement pipeline data, with federal investment tax credit uptake rates and provincial permitting velocity serving as key forecast inputs.
Material uncertainties — steel and copper input volatility, skilled trades availability fluctuations, and provincial permitting timeline dispersion — sit outside the modeled envelope. Forecasts reflect assumptions regarding Clean Electricity Regulations enforcement consistency and Indigenous consultation framework stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Stirling Engine Market
Power Generation
Steam Turbine Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Malaysia Power Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
India Gensets Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Variable Speed Generator Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Hydrogenerators Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Industrial Solar Generator Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Tunisia Power Market