
 On-Grid Solar Inverter Market | 2026-2036
On-Grid Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
On-Grid Solar Inverter Market Insights
Modular inverter-plus-storage bundling is realigning how utilities and commercial developers evaluate total cost of ownership against standalone hardware purchases. Huawei Technologies leverages its power electronics heritage to dominate integrated smart-string solutions for utility-scale deployments. Sungrow anchors its position through backward integration into energy storage systems, capturing margin pools that pure-play inverter rivals cannot access. SMA Solar Technology differentiates through German-engineered grid-forming inverters certified for the most demanding European network codes.
An on-grid solar inverter converts direct current from photovoltaic arrays into alternating current synchronized with utility frequency and voltage, typically achieving maximum power point tracking efficiencies above 98.5% and THD below 3% to satisfy grid interconnection standards. Its primary commercial purpose is enabling safe, code-compliant injection of solar generation into public distribution networks while providing telemetry for remote monitoring and grid stabilization services. String inverters now lead residential and commercial rooftop installations where balance-of-system simplicity and rapid commissioning outweigh the marginal efficiency gains of central alternatives. Central inverters retain dominance in utility-scale, ground-mounted arrays above 10 MW where economies of scale in maintenance and land utilization prove decisive. Microinverters occupy a premium niche in shaded or architecturally complex rooftops where module-level optimization recovers otherwise lost yield.
Germany's BNetzA enforces medium-voltage ride-through and reactive power provision that disqualifies legacy inverter designs from new project eligibility. India's CEA mandates stringent harmonic emission limits and anti-islanding protection through its Technical Standards for Connectivity Regulations, directly shaping product roadmaps for suppliers targeting the subcontinent. California's CAISO and the broader IEEE 1547-2018 framework in the United States require advanced grid support functions including frequency-watt and volt-watt responses that add firmware complexity but create barriers against uncertified imports. Stakeholders must monitor how evolving interconnection codes in priority markets redefine the minimum viable product specification and whether firmware-upgradable architectures can extend hardware lifecycles against tightening standards.
Market Dynamics
Grid-forming inverter firmware is absorbing the complexity of evolving interconnection codes, forcing manufacturers to architect hardware platforms capable of decade-long certification lifecycles against tightening ride-through and reactive power mandates.
Growth Catalysts
- Stringent European network codes:Germany's BNetzA mandates medium-voltage ride-through capabilities that disqualify legacy designs, creating replacement demand for certified equipment across utility-scale installations.
- Utility-scale solar expansion:Ground-mounted arrays above 10 MW are standardizing on central and string inverter architectures as grid parity eliminates feed-in tariff dependency in multiple jurisdictions.
- Domestic manufacturing incentives:India's PLI scheme for solar module and component production is reshaping procurement patterns toward locally certified inverter supply chains.
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor fabrication concentrates in East Asian foundries, exposing inverter manufacturers to input cost volatility and allocation constraints.
- Technical limitation of legacy firmware architectures:Non-upgradable control systems face obsolescence against IEEE 1547-2018's frequency-watt and volt-watt response requirements.
- Regulatory friction from divergent certification timelines:California's CAISO, Germany's BNetzA, and India's CEA maintain non-harmonized testing protocols that fragment product qualification costs.
Strategic Opportunities
- Underpenetrated commercial rooftop segments:India's CEA-mandated net metering expansion creates addressable market for string inverter deployments in mid-scale commercial installations.
- Technology convergence of inverter-plus-storage:DC-coupled battery integration is absorbing balance-of-system costs and enabling new revenue streams from ancillary grid services.
- Regulatory tailwind from US IRA manufacturing credits:Domestic content bonuses for utility-scale solar projects incentivize localized inverter assembly and component sourcing.
Industry Challenges
- Power electronics engineering talent scarcity:Grid-forming control algorithm development requires specialized firmware expertise that outstrips current graduate pipeline output.
- Certification timeline compression:Accelerated grid code revision cycles in Germany and California force parallel hardware and firmware validation tracks that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Grid Solar Inverter Market |
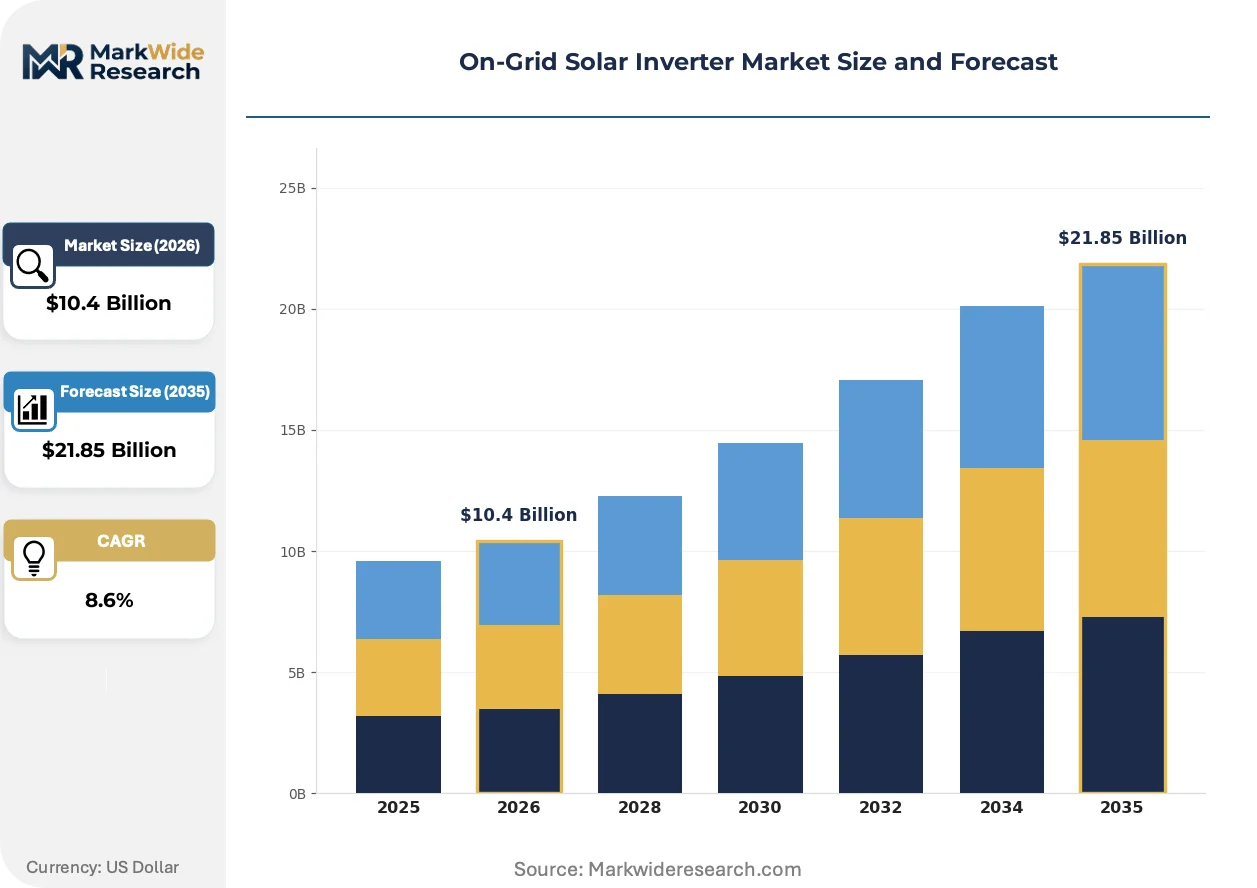
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $21.85 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Microinverters, Central Inverters, Power Optimizers Installation Type: Rooftop, Ground-mounted, Hybrid Systems, Commercial Scale End User: Residential, Commercial, Industrial, Utilities Technology: Wi-Fi Monitoring, Smart Grid Integration, Battery Storage, AC Coupling |
| Companies Covered | Huawei Technologies, Sungrow, SMA Solar Technology, Ginlong Technologies, GoodWe, Growatt New Energy, Solis, Fimer Group, Enphase Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Grid Solar Inverter Market Trends and Innovations
Silicon carbide power semiconductors and modular inverter architectures are absorbing switching losses and maintenance burdens that previously constrained system efficiency and uptime economics.
Silicon carbide MOSFETs are replacing silicon IGBTs in high-frequency switching applications, cutting thermal management requirements and enabling denser power conversion packaging. Utility-scale developers in the United States and China are specifying SiC-based string inverters for new procurement rounds. This transition is absorbing the efficiency gap between string and central inverter topologies, compressing the addressable market for traditional megawatt-scale central units.
California's CAISO and the broader IEEE 1547-2018 framework mandate frequency-watt, volt-watt, and volt-var responses that transform inverters from passive generation assets into active grid stabilization tools. European network operators under ENTSO-E guidelines are adopting comparable requirements. String inverter suppliers targeting North American utility-scale segments must embed these functions as standard firmware, not optional upgrades, to maintain project eligibility.
Asset owners are unbundling inverter hardware from long-term service contracts, compressing supplier margins on aftermarket maintenance and forcing manufacturers to compete on upfront equipment cost rather than lifecycle service revenue. This pattern concentrates in utility-scale procurement in the United States and India, where independent power producers prioritize capital expenditure minimization over vendor lock-in. Channel intermediaries specializing in spare parts and third-party commissioning are capturing margin pools that incumbent suppliers previously controlled.
On-Grid Solar Inverter Market Segmentation
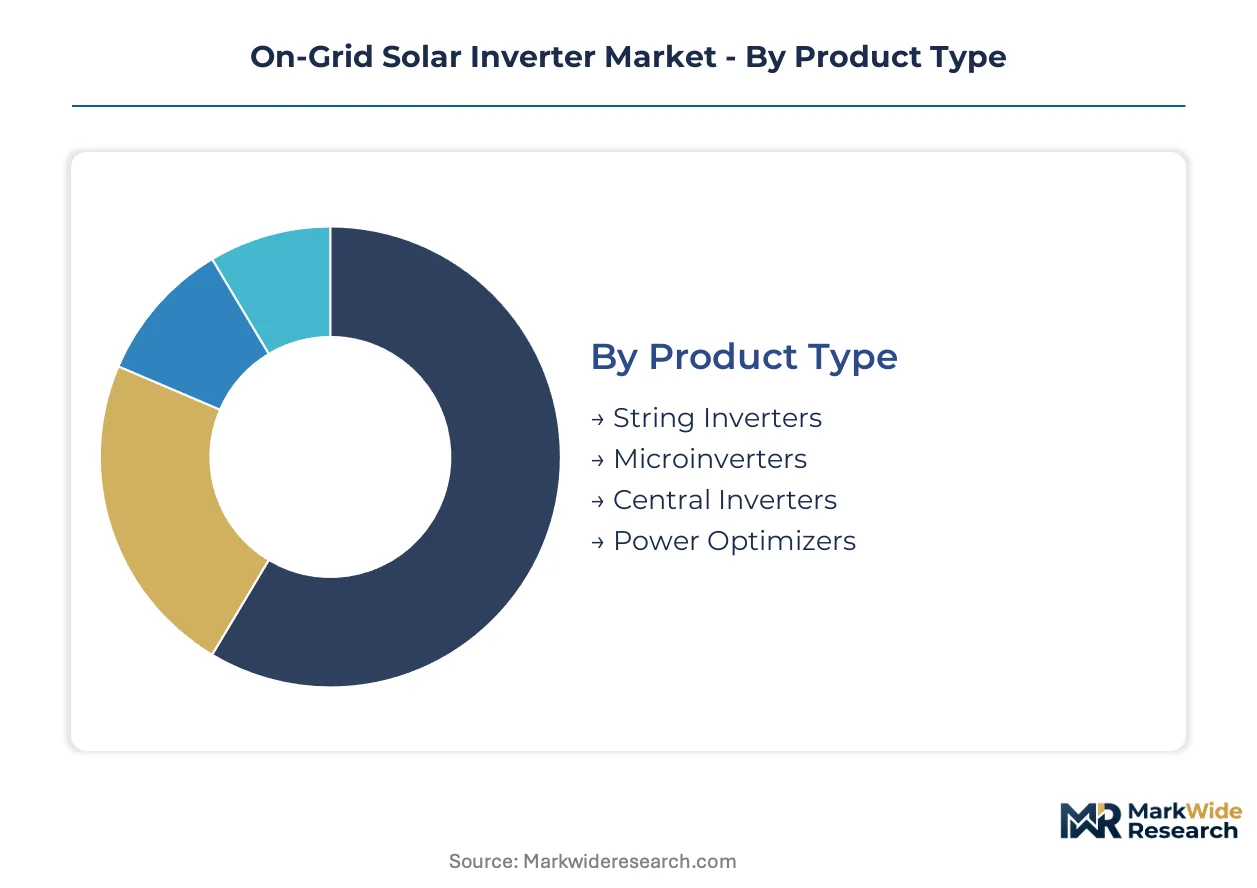
On-grid solar inverter procurement splits sharply across application contexts, with grid-code requirements, scale economics, and balance-of-system complexity driving divergent product specifications. Manufacturers architect distinct hardware-firmware combinations for each segment rather than deploying universal platforms.
Product Type:
Standardization dominates at utility scale while customization proliferates in distributed applications where site constraints vary.
- String Inverters:Modular AC conversion units typically rated 3-150 kW that aggregate DC inputs from multiple PV strings through independent maximum power point trackers. Demand concentrates in commercial rooftop installations across India and Germany where rapid commissioning and granular monitoring outweigh central inverter efficiency advantages. India's CEA-mandated net metering expansion accelerates procurement of three-phase string units for mid-scale commercial buildings.
- Central Inverters:Megawatt-scale power conversion systems housed in weatherized enclosures for utility-scale ground-mounted arrays above 10 MW capacity. Procurement clusters in China's northwestern provinces and the United States' southwestern states where land availability supports dense DC field configurations and centralized maintenance protocols.
- Microinverters:Module-level AC conversion devices eliminating string-level mismatch losses through per-panel optimization.
- Power Optimizers:DC-to-DC conditioning units paired with string inverters to enable module-level monitoring and shutdown compliance.
Leading the category by volume: String Inverters. Expanding most quickly: Microinverters in shaded residential applications.
Installation Type:
Volume scale differentiates this category, with mass-deployment segments commanding procurement leverage over bespoke configurations.
- Rooftop:Building-integrated or building-applied mounting configurations spanning residential garages to industrial warehouses, requiring inverters with IP65+ enclosures and rapid shutdown compliance. Germany's BNetzA fire safety codes and California's NEC Article 690.12 mandate module-level rapid shutdown, reshaping inverter specification toward optimizer-compatible or microinverter-based designs.
- Ground-mounted:Terrestrial rack or tracker-mounted arrays with unrestricted ventilation and maintenance access, favoring central or high-capacity string inverter architectures. China's Gobi Desert installations and India's Rajasthan solar parks standardize on 3.125 MW central inverter blocks for O&M efficiency.
- Hybrid Systems:Configurations combining PV generation with diesel backup or grid-interactive battery storage, requiring bi-directional inverter capabilities.
- Commercial Scale:Mid-sized installations typically 100 kW to 2 MW serving manufacturing facilities, data centers, and retail distribution networks.
Dominating procurement volume: Ground-mounted utility arrays. Steepest expansion trajectory: Commercial Scale behind India's net metering reforms.
End User:
Customer sophistication and procurement scale fragment inverter requirements across risk tolerance and technical capability.
- Residential:Single-family and multi-family building owners prioritizing installation simplicity, monitoring visibility, and warranty terms over absolute conversion efficiency. California's SGIP incentive program and Germany's KfW low-interest financing shape product selection toward storage-ready inverter platforms.
- Commercial:Corporate and institutional facility managers optimizing for demand charge reduction and sustainability reporting, driving specification of revenue-grade metering and API-accessible fleet management platforms.
- Industrial:Heavy manufacturing and process industries with high load factors and power quality requirements.
- Utilities:Vertically integrated and independent power producers with structured procurement processes, long-term service agreements, and grid-code certification as primary selection criteria.
Highest absolute demand: Utilities. Gaining share fastest: Commercial segment as corporate renewable procurement accelerates.
Technology:
Margin pools concentrate where firmware differentiation creates switching costs against commodity hardware.
- Wi-Fi Monitoring:Cloud-connected telemetry enabling remote performance diagnostics and predictive maintenance alerts through mobile applications.
- Smart Grid Integration:IEEE 1547-2018 and ENTSO-E compliant frequency-watt, volt-watt, and volt-var response capabilities transforming inverters into grid stabilization assets.
- Battery Storage:DC-coupled or AC-coupled energy storage integration enabling time-shift arbitrage, backup power, and ancillary service revenue streams.
- AC Coupling:Retrofit-friendly architecture allowing battery addition to existing PV installations without DC-side reconfiguration.
Commanding premium pricing: Smart Grid Integration. Climbing the fastest: Battery Storage as IRA manufacturing credits reshape project economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of on-grid solar inverters while India and the United States absorb the largest procurement volumes. Domestic content requirements in multiple jurisdictions are fragmenting supply chains into regional production clusters.
China
Massive utility-scale solar deployment in Xinjiang and Inner Mongolia sustains inverter demand at gigawatt scale. The National Energy Administration enforces grid-forming capability standards for new renewable installations. Ningbo and Shenzhen industrial corridors concentrate power electronics manufacturing capacity serving domestic and export markets.
United States
Independent power producers in Texas and California are standardizing on string and central inverter architectures for utility-scale procurement. The Inflation Reduction Act's domestic content bonuses incentivize localized inverter assembly and component sourcing. Arizona and Nevada desert solar parks specify high-capacity central inverter blocks for operational efficiency.
India
Aggressive renewable targets in Rajasthan and Gujarat are driving central and string inverter procurement for ground-mounted arrays above 100 MW. The Central Electricity Authority mandates stringent harmonic emission limits and anti-islanding protection through its Technical Standards for Connectivity Regulations. Maharashtra's commercial rooftop segment accelerates three-phase string unit adoption following net metering expansion.
Germany
Stringent medium-voltage ride-through requirements from the Federal Network Agency disqualify legacy inverter designs from new project eligibility. Bavaria and Baden-Württemberg industrial zones concentrate grid-forming inverter development for European export markets. Residential rooftop installations in North Rhine-Westphalia specify module-level rapid shutdown compliance reshaping inverter specification.
Australia
Queensland and New South Wales utility-scale solar farms are procuring string inverters with advanced grid support functions. The Australian Energy Market Operator mandates frequency response capabilities that align with IEEE 1547-2018 frameworks. Victoria's commercial and industrial segment shows accelerating demand for storage-ready inverter platforms.
On-Grid Solar Inverter Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product tiers. The market structure concentrates around three to five dominant suppliers controlling utility-scale procurement channels while fragmented regional players serve distributed rooftop segments. Strategic archetypes include integrated smart-string solution providers, backward-integrated energy storage system suppliers, and German-engineered grid-forming specialists. Capacity expansion and firmware certification acceleration represent the dominant competitive moves as grid code timelines compress.
Within the integrated solution tier, Huawei Technologies exemplifies power electronics heritage applied to utility-scale deployments. Sungrow anchors the backward-integrated archetype through captive energy storage system production. SMA Solar Technology occupies the premium engineering position with German-certified grid-forming architectures. These three manufacturers represent distinct strategic postures rather than uniform market presence.
| Leading Market Players |
|---|
| Huawei Technologies |
| Sungrow |
| SMA Solar Technology |
| Ginlong Technologies |
| GoodWe |
| Growatt New Energy |
| Solis |
| Fimer Group |
| Enphase Energy |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer spot prices cascade through power semiconductor foundries into three-tier pricing stratification across premium grid-forming, standard string, and economy central inverter tiers, with India's PLI domestic-content bonuses compressing landed-cost differentials against Chinese-origin equipment.
Pricing Analysis
Margin tightening in utility-scale central inverters traces to IGBT and SiC MOSFET allocation constraints at East Asian foundries, forcing manufacturers toward firmware-differentiated premium tiers. Price differentiation hinges on IEEE 1547-2018 certification grade and after-sales service bundling. Cost-down pressure on economy string units accelerates as Indian IPPs prioritize capital expenditure minimization over vendor lock-in. Commercial rooftop segments exhibit highest price sensitivity; utility-scale buyers with structured procurement processes demonstrate lowest.
Supply Chain Analysis
India's PLI scheme and the US IRA domestic-content bonuses are reshaping sourcing patterns toward localized assembly and component qualification. Power semiconductor fabrication concentrates in China, South Korea, and Taiwan. Inverter manufacturing draws from silicon carbide substrates, IGBT modules, and magnetics. Single-source vulnerability in SiC epitaxy equipment creates chokepoint exposure. Distribution runs through EPC contractors and utility procurement departments with long-term framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where Germany's BNetzA medium-voltage ride-through mandates create certification moats that disqualify non-compliant entrants from European utility-scale eligibility.
For Market Incumbents: To counter firmware-obsolescence risk in legacy architectures, accelerate grid-forming certification pipelines for IEEE 1547-2018 and ENTSO-E codes. Capacity addition in Arizona and Gujarat captures IRA and PLI incentives while reducing tariff exposure. Channel control through captive spare-parts networks defends aftermarket margin pools against third-party intermediaries. For New Entrants and Emerging Players: The premium-economy price gap in India's commercial rooftop segment offers white-space entry behind CEA-mandated net metering expansion. Target Maharashtra and Gujarat mid-scale installations with three-phase string units certified to local harmonic emission limits. Go-to-market leverage rests on rapid commissioning protocols and optimizer-compatible designs for BNetzA fire safety compliance. For Investors and Strategic Acquirers: Distressed-cycle entries favor German-engineered grid-forming specialists with captive firmware development capabilities in Bavaria industrial zones. Long-term viability over the projection horizon hinges on decade-long certification lifecycles against tightening ride-through mandates. Watch for IEEE 1547-2018 implementation deadlines as inflection indicators for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Firmware Certification | Unlocks eligibility under Germany's BNetzA and California's CAISO interconnection codes. |
| Silicon Carbide Supply Agreement | Secures wafer allocation from East Asian foundries for next-generation string inverter platforms. |
| Domestic Content Assembly | Captures IRA manufacturing credits and PLI incentives in the United States and India. |
| Energy Storage Integration | Absorbs balance-of-system costs through DC-coupled battery architectures for utility-scale developers. |
| Third-Party Service Partnership | Defends aftermarket revenue against unbundling trends in US and Indian procurement. |
Research Methodology
Document review covered FERC interconnection filings, EIA project databases, and CEA technical standards, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from IEA renewable energy reports, IEEE standards documentation, and customs trade data for power semiconductor imports. Bottom-up project pipelines and top-down regulatory capacity targets were triangulated to constrain estimation variance.
Historical deployment trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, installation scale, end-user sophistication, and regional regulatory framework. CAGRs were derived from slope-constrained curve fitting against announced project backlogs and policy target trajectories. Forecast inputs incorporated grid-code revision timelines and domestic-content incentive phase-ins.
Inputs from utility procurement departments and EPC contractors were available through the study window; gaps in forward-looking SiC wafer capacity announcements introduce uncertainty bands around cost-down assumptions. Forecasts reflect documented policy targets and interconnection queue data. Regulatory acceleration or semiconductor supply disruption could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Off Grid Solar Market