
 Japan Combined Heat and Power Market | 2026-2036
Japan Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Combined Heat and Power Market Foresight
Third-party project finance and equipment leasing is narrowing the competitive field to firms with balance-sheet capacity or captive financing arms. Mitsubishi Heavy Industries leverages its integrated turbine manufacturing and EPC capabilities to anchor large-scale industrial installations. Yanmar Holdings specializes in compact reciprocating engine systems that dominate commercial and small-scale residential applications. Tokyo Gas sustains its position through utility-linked leasing structures that reduce customer capital burdens.
Combined heat and power systems simultaneously generate electricity and useful thermal energy from a single fuel source, typically achieving total fuel utilization rates exceeding eighty percent through sequential energy extraction. Gas turbine-based configurations serve baseload industrial facilities requiring high-pressure steam, while reciprocating engine units address commercial buildings with lower thermal-to-electric ratios. The application dimension shows industrial sites commanding the largest installed capacity share, though healthcare and hospitality end users represent the fastest-expanding demand pool as resilience priorities reshape procurement patterns.
METI enforces efficiency standards under the Act on Rationalizing Energy Use, while JIS certification requirements govern equipment interoperability and safety compliance for grid-connected systems. The country's national pharmaceutical regulator does not directly oversee CHP deployment, but prefectural building codes and fire safety ordinances create localized approval bottlenecks that manufacturers must navigate. Stakeholders should monitor hydrogen blending mandates and carbon pricing mechanisms as these frameworks will determine retrofit economics for existing natural gas-fired installations.
Market Dynamics
METI's carbon neutrality roadmap and hydrogen blending mandates are compressing the economic viability window for conventional natural gas CHP systems while redirecting capital toward hydrogen-ready turbine configurations and fuel cell hybrids.
Growth Catalysts
- Feed-in tariff revisions:METI's adjusted pricing mechanisms for grid-exported power improve project economics for commercial-scale installations. Hospital campuses leverage these structures to offset resilience investments.
- Kanto corridor density:Tokyo's district heating networks and clustered industrial zones generate economies of scale that distributed energy developers exploit for multi-site deployment.
- Hydrogen-ready infrastructure:Prefectural governments in Osaka and Aichi are piloting hydrogen blending ratios that position early CHP adopters for fuel transition without asset stranding.
Market Restraints
- LNG import dependency:Japan's concentrated exposure to spot liquefied natural gas markets exposes CHP operators to input cost volatility that undermines long-term power purchase agreement pricing.
- Grid interconnection standards:JIS certification requirements for synchronous connection create localized approval bottlenecks that extend project timelines in prefectures with limited technical review capacity.
- Electrification substitution:Industrial heat pump deployments in food processing and textile sectors displace thermal demand that would otherwise anchor CHP economics.
Strategic Opportunities
- Healthcare resilience mandates:Post-disaster regulatory requirements for 72-hour autonomous power capacity at tertiary hospitals create a captive demand pool for modular reciprocating engine systems.
- Hokkaido cold-climate applications:The northern island's district heating infrastructure and heavy snowfall vulnerability to grid disruption create underpenetrated terrain for combined heat and power deployment.
- Equipment-as-a-service models:Tokyo Gas and independent lease structures are reducing customer capital burdens and expanding addressable demand among mid-sized commercial facilities.
Industry Challenges
- Turbomachinery technician scarcity:Japan's aging workforce and limited vocational pipeline for gas turbine maintenance create service bottlenecks that constrain fleet availability rates.
- Legacy control system integration:Industrial facilities with proprietary SCADA architectures face protocol incompatibility when retrofitting modern CHP units with remote monitoring capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Combined Heat and Power Market |
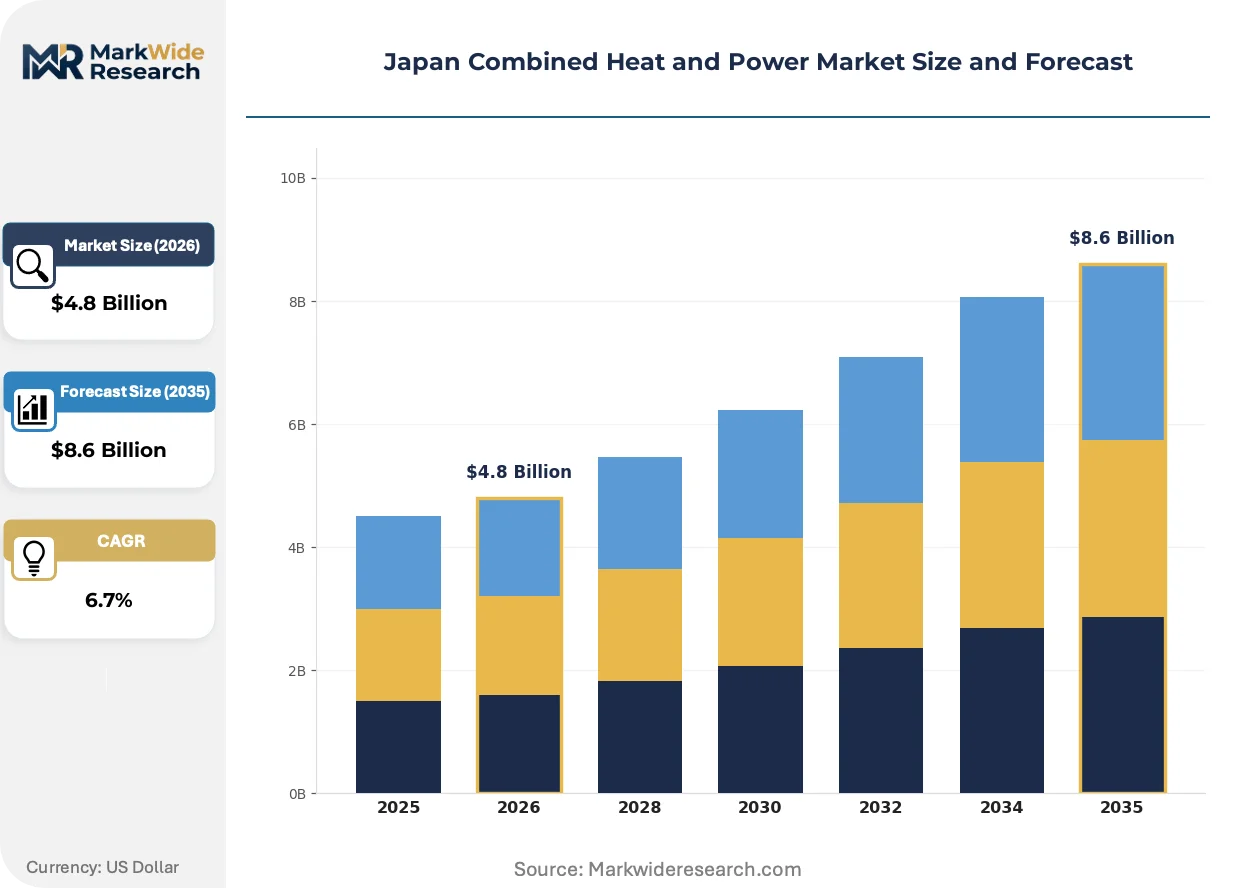
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbine, Steam Turbine, Reciprocating Engine, Microturbine Application: Industrial, Residential, Commercial, Institutional Fuel Type: Natural Gas, Biogas, Diesel, Coal End User: Manufacturing, Healthcare, Hospitality, Education |
| Companies Covered | Osaka Gas Co Ltd, Fuji Electric Co Ltd, Mitsubishi Heavy Industries Ltd, JFE Engineering Corporation, IHI Corporation, Kawasaki Heavy Industries Ltd, Yanmar Holdings Co Ltd, General Electric Company, Tokyo Gas Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Combined Heat and Power Market Shifts & Advancements
Digital twin architectures and predictive maintenance platforms are compressing operational expenditure structures while hydrogen combustion research redefines fuel flexibility specifications for next-generation turbine fleets.
Advanced combustion monitoring systems using real-time flame imaging and spectral analysis are digitizing maintenance scheduling for gas turbine-based CHP units. Heavy manufacturing campuses in the Keihin industrial belt are deploying these systems to extend mean time between overhauls. The technology is digitizing service contract structures by enabling performance-guarantee pricing tied to actual availability rather than scheduled intervals.
METI's Act on Rationalizing Energy Use enforces minimum thermal efficiency thresholds that disqualify aging single-cycle generators from renewal eligibility. Industrial facilities must either retrofit with waste heat recovery or replace assets entirely. The regulation most affects mid-sized chemical processors in the Chukyo manufacturing zone, where prefectural energy auditors are conducting accelerated compliance inspections.
Hospital procurement committees are unbundling long-term service agreements from initial equipment purchases, creating competitive tension between OEM captive service arms and independent maintenance providers. Tokyo metropolitan medical centers now separately tender for spare parts logistics and technical labor. This pattern concentrates in the Kanto region where healthcare consolidation has produced centralized procurement functions with specialized engineering staff.
Japan Combined Heat and Power Market Segmentation
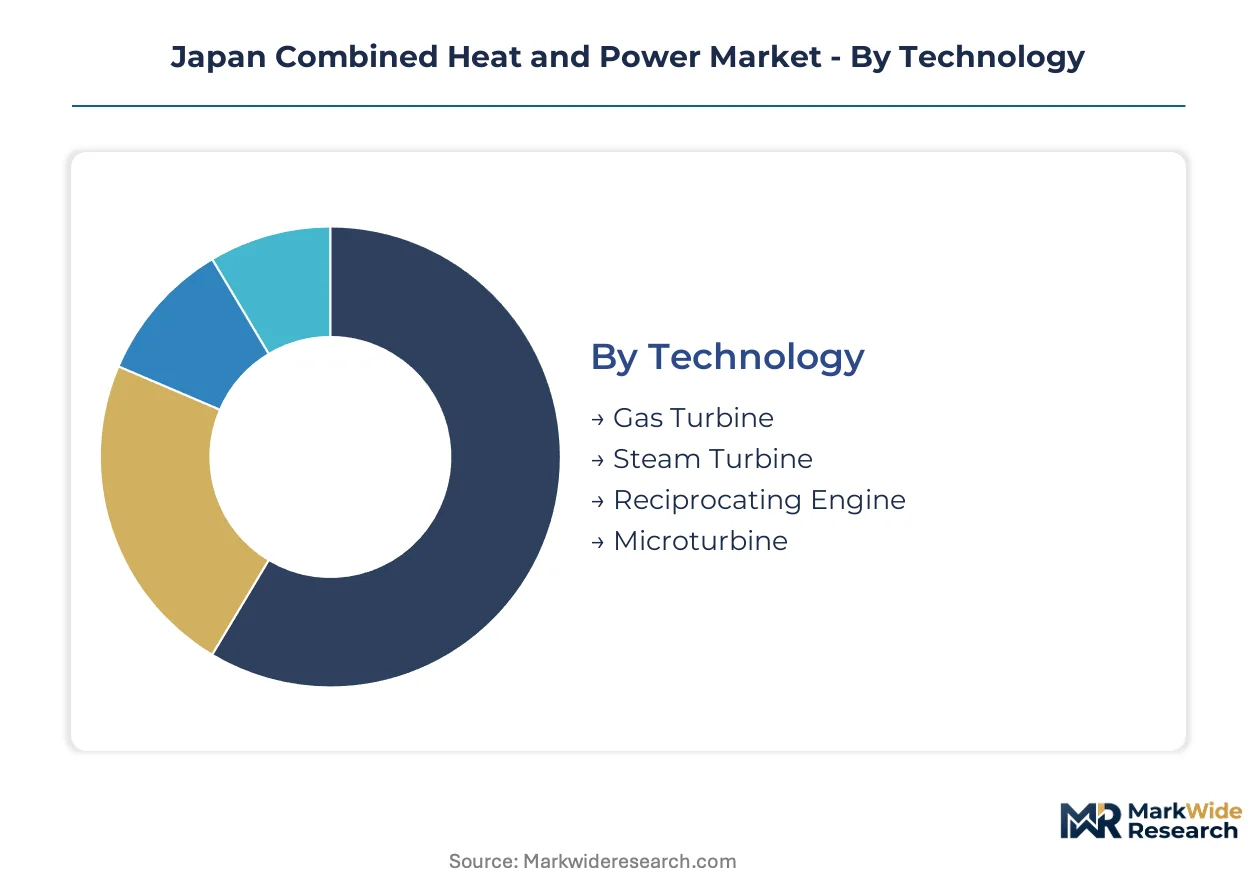
Technology configurations, fuel choices, and end-use applications segment Japan's CHP market into distinct procurement patterns. Each dimension carries different regulatory triggers, maintenance cycles, and capital recovery timelines that reshape vendor positioning across prefectural markets.
Technology:
Reciprocating engine systems turn over fastest with 8-12 year replacement cycles, while steam turbine infrastructure persists for 25-30 years, creating divergent aftermarket revenue pools.
- Reciprocating Engine:Compact modular units burn natural gas or biogas with thermal outputs suited to commercial buildings below 5MW electric capacity. Hospital campuses in Tokyo and Osaka deploy these for 72-hour autonomous power mandates under post-disaster regulations.
- Gas Turbine:Heavy-duty configurations achieve combined cycle efficiencies above 80% through high-pressure steam extraction. Keihin industrial belt chemical processors anchor demand for 10-50MW baseload installations requiring continuous thermal supply.
- Steam Turbine:Legacy infrastructure dominates pulp and paper facilities with waste fuel integration from process streams.
- Microturbine:Emerging deployments target small commercial sites with sub-MW capacity needs and limited maintenance access.
Reciprocating engines dominate installed base. Gas turbines are where expansion concentrates for hydrogen-ready retrofit pathways.
Application:
Cost tier stratification separates industrial megaprojects from distributed commercial deployments, with institutional procurement governed by resilience budgets rather than thermal efficiency optimization.
- Industrial:Large-scale installations exceeding 50MW thermal output serve chemical processing, steel, and pulp sectors with 24/7 steam demand. METI's Act on Rationalizing Energy Use enforces efficiency audits that accelerate replacement of aging single-cycle assets in Chukyo manufacturing zones.
- Commercial:Mid-scale systems address hotels, data centers, and retail complexes with variable thermal loads. Tokyo Gas utility-linked leasing structures reduce capital barriers for facilities under 10,000 square meters.
- Institutional:Universities and government facilities prioritize fuel security over marginal cost optimization.
- Residential:Single-family and small multi-family units deploy sub-5kW fuel cell hybrids under residential energy efficiency subsidy programs.
Industrial applications anchor revenue concentration. Commercial installations are climbing the fastest as equipment-as-a-service models proliferate.
Fuel Type:
Supply concentration and carbon intensity create divergent margin structures, with pipeline gas commanding premium pricing stability against volatile LNG spot exposure.
- Natural Gas:Pipeline and LNG-sourced methane powers 85% of installed capacity, with hydrogen blending pilots in Osaka and Aichi positioning infrastructure for fuel transition. METI's carbon neutrality roadmaps compress the economic window for unabated natural gas systems.
- Biogas:Agricultural and wastewater digestion streams serve rural food processing facilities with captive fuel supply.
- Diesel:Emergency backup configurations persist in remote island installations with grid reliability concerns.
- Coal:Limited residual deployments in legacy steel and cement facilities face accelerated phase-out under prefectural emissions ordinances.
Natural gas dominates installed base. Biogas is gaining share fastest as agricultural cluster developers exploit feed-in tariff structures.
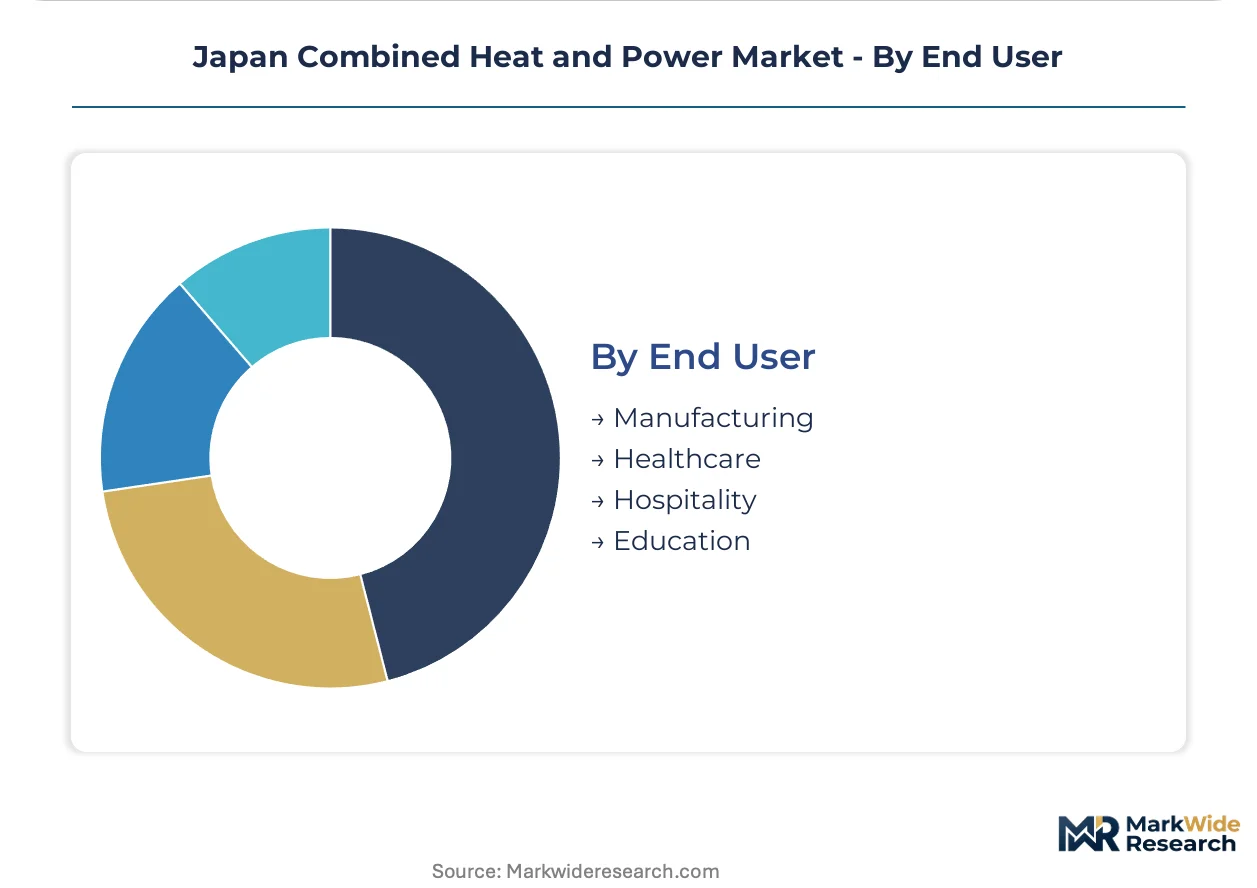
End User:
Customer type determines procurement sophistication, with consolidated healthcare systems deploying specialized engineering staff against fragmented hospitality owner-operators relying on vendor-managed service contracts.
- Healthcare:Tertiary hospitals and medical campuses require 72-hour autonomous power capacity under post-disaster regulatory mandates. Tokyo metropolitan procurement committees unbundle equipment from service agreements, creating competitive tension between OEM captive arms and independent maintenance providers.
- Manufacturing:Chemical, steel, and food processors anchor baseload thermal demand with continuous operation requirements.
- Hospitality:Hotels and resorts prioritize thermal comfort reliability over marginal efficiency optimization.
- Education:University campuses exploit district heating network density for multi-building cogeneration deployment.
Manufacturing dominates installed capacity. Healthcare is expanding most quickly as resilience mandates reshape capital allocation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial energy buyers cluster in Japan's coastal manufacturing belts, with healthcare and commercial facilities driving distributed deployment across metropolitan corridors. Prefectural governments shape local deployment timelines through building codes and disaster resilience mandates.
Kanto/Tokyo
Hospital campuses and data centers anchor demand for modular reciprocating engine systems. METI's feed-in tariff revisions improve project economics for grid-exported power in the capital region. The Keihin industrial belt hosts chemical processors deploying 10-50MW gas turbine installations for continuous steam supply.
Kansai/Osaka
Prefectural hydrogen blending pilots position early CHP adopters for fuel transition without asset stranding. Osaka Gas utility-linked leasing structures reduce capital barriers for commercial facilities under 10,000 square meters. The Osaka Bay manufacturing zone concentrates steel and pulp facilities with legacy steam turbine infrastructure.
Chubu/Nagoya
METI's Act on Rationalizing Energy Use accelerates replacement of aging single-cycle assets in the Chukyo manufacturing zone. Prefectural energy auditors conduct compliance inspections across mid-sized chemical processors. Toyota-supplier industrial parks generate captive thermal demand for distributed cogeneration deployment.
Hokkaido
District heating infrastructure and heavy snowfall vulnerability to grid disruption create underpenetrated terrain for CHP deployment. Cold-climate applications favor combined heat and power over electrification alternatives for thermal reliability. Sapporo's municipal energy planning incorporates resilience priorities for isolated island grid conditions.
Kyushu
Semiconductor fabrication facilities drive precision power quality requirements for on-site generation. Biogas from agricultural digestion streams serves rural food processing clusters with captive fuel supply. Fukuoka's port industrial zone faces LNG import cost volatility that complicates long-term power purchase agreement pricing.
Japan Combined Heat and Power Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers. Heavy industrial conglomerates anchor large-scale installations through integrated manufacturing and EPC capabilities. Compact system specialists dominate commercial and residential segments through modular product architectures. Competitive moves concentrate on hydrogen-ready equipment development and equipment-as-a-service financing structures.
Among Japan-based industrial conglomerates, Mitsubishi Heavy Industries Ltd, IHI Corporation, and Kawasaki Heavy Industries Ltd occupy positions anchored in turbomachinery manufacturing heritage. These entities exemplify the integrated-player archetype combining prime mover production with project execution capabilities. Their market presence reflects decades of utility-scale power plant supply relationships repurposed toward distributed energy applications.
| Leading Market Players |
|---|
| Osaka Gas Co Ltd |
| Fuji Electric Co Ltd |
| Mitsubishi Heavy Industries Ltd |
| JFE Engineering Corporation |
| IHI Corporation |
| Kawasaki Heavy Industries Ltd |
| Yanmar Holdings Co Ltd |
| General Electric Company |
| Tokyo Gas Co Ltd |
| Others |
Supply & Pricing Matrix
The Keihin industrial belt's freight corridors from Yokohama Port to Chukyo manufacturing zones transmit LNG import cost volatility directly into equipment pricing tiers, concentrating margin pressure on mid-scale commercial installers while rewarding turbine OEMs with captive EPC capabilities.
Pricing Analysis
Cost-plus contracts indexed to JCC crude oil benchmarks dominate long-term service agreements for gas turbine installations. Price differentiation hinges on JIS certification tier and bundled remote monitoring capabilities. Pricing pressure stems from spot LNG exposure that compresses margins for independent IPPs. Hospital procurement committees exhibit lowest price sensitivity due to resilience mandate compliance deadlines.
Supply Chain Analysis
Tariff exposure between Japan and Australian LNG suppliers dominates input cost risk for turbine operators. Turbomachinery draws from domestic casting foundries in Nagoya and imported precision components from Germany and the United States. Single-source vulnerability concentrates in high-temperature alloy forgings for combustion hardware. Distribution runs through utility-linked leasing structures and independent EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
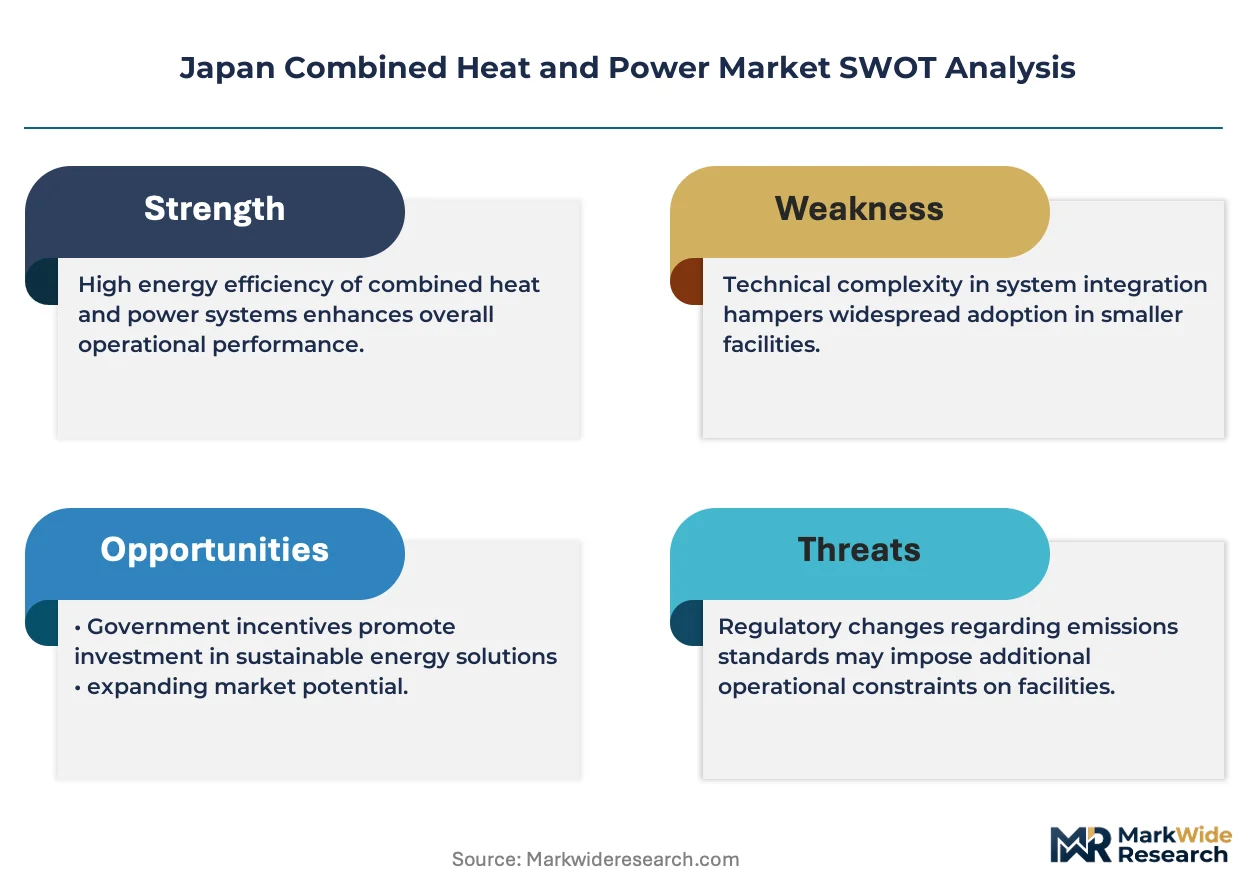
The Japan CHP market constitutes a defensive moat anchored in regulatory entrenchment—METI efficiency mandates and JIS certification requirements create switching costs that protect incumbent turbine OEMs from commoditization.
For Market Incumbents: Harden hydrogen-ready product roadmaps against fuel cell substitution threats in hospital segments. Deepen backward integration into precision casting capabilities to offset alloy supply bottlenecks. Secure prefectural energy auditor relationships to influence compliance inspection timelines for asset replacement cycles.
For New Entrants and Emerging Players: Mid-market commercial buildings in Hokkaido represent the most penetrable entry point given underpenetrated district heating infrastructure and limited incumbent service presence. Equipment-as-a-service financing structures bypass capital barrier constraints that protect established leasing channels. Target food processing clusters with biogas integration capabilities to exploit feed-in tariff arbitrage.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated industrial conglomerates seeking to monetize non-core turbomachinery divisions. Long-term viability favors hydrogen-combustion patent portfolios and captive maintenance contract backlogs over pure manufacturing assets. Monitor METI hydrogen blending mandate acceleration as inflection signal for retrofit demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Development | Positions installed base for METI fuel transition mandates without asset stranding. |
| Equipment-as-a-Service Expansion | Tokyo Gas leasing structures reduce customer capital barriers in commercial segments. |
| Digital Twin Platform Deployment | Enables performance-guarantee pricing tied to actual availability rather than scheduled intervals. |
| Prefectural Auditor Relationship Building | Accelerates compliance inspection timelines for Chukyo manufacturing zone asset replacements. |
| Biogas Integration Capability | Captures feed-in tariff structures for agricultural cluster food processing facilities. |
Research Methodology
Desk research of METI regulatory filings, JIS certification databases, and prefectural energy audit reports preceded structured interviews with utility planning officers, hospital procurement directors, EPC project developers, and aftermarket service heads. Secondary validation drew from customs trade data, IEA country reports, and equipment manufacturer technical disclosures. Bottom-up installation tracking and top-down fuel consumption estimates were triangulated for market sizing.
Fixed assumptions held METI carbon neutrality roadmap targets and hydrogen blending pilot timelines constant across the projection horizon. The analytical framework modeled technology configuration, application scale, fuel type, and end-user procurement sophistication as core segmentation dimensions. CAGRs were derived from regression analysis of historical deployment rates against regulatory trigger points. Forecast inputs incorporated LNG import price scenarios and district heating network expansion plans.
Macroeconomic conditions sit as an overlay; deviation in yen-dollar exchange rates or spot LNG pricing would shift project finance viability and equipment import costs. Forecasts reflect documented assumptions regarding METI policy continuity and JIS standard revision timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Global Power Grid System Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Gas Gensets Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Canada Power EPC Market
Power Generation
Shore Power Market
Power Generation
North America Distributed Power Generation Market
Power Generation
India Gensets Market
Power Generation
East Africa Power Market
Power Generation
Subsea Power Grid System Market
Power Generation
Industrial Solar Generator Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
India Thermal Power Plant Market