
 Tunisia Power Market | 2026-2036
Tunisia Power Market Size, Share, and Industry Trends Forecast 2026-2036
Tunisia Power Market Analytics
Modular project packaging is restructuring buyer choice in Tunisia's power sector, as developers unbundle generation assets from transmission obligations to reduce offtake risk. Carthage Power Company anchors conventional capacity through its gas-fired fleet near Bizerte. Scatec leverages its North African development platform to compete for utility-scale solar concessions. Voltalia specializes in distributed generation solutions that navigate regulatory complexity for commercial and industrial clients.
Tunisia power encompasses electricity generation, transmission, and distribution infrastructure operating across voltage classes from low-voltage distribution at 220-400V to high-voltage transmission at 225kV, serving a grid where peak demand exceeds 4,000MW during summer cooling loads. Solar dominates new capacity additions as photovoltaic technology achieves the lowest levelized cost among available generation options. Gas turbine technology sustains baseload reliability through combined-cycle configurations that integrate with intermittent renewable output. The residential end-user segment shows rising distributed generation adoption as net metering enables rooftop solar self-consumption with surplus feed-in.
Tunisia's Ministry of Energy and Mines oversees licensing under the renewable energy law, while the national utility STEG manages grid codes and interconnection standards that determine project bankability. The country's national energy regulator sets tariff methodologies that shape investor returns across concession periods. Stakeholders must monitor upcoming auction rounds and grid reinforcement timelines to calibrate capital deployment against evolving offtake structures.
Market Dynamics
The 2015 renewable energy law and its net metering framework are fragmenting buyer-seller relationships in Tunisia's power sector, enabling industrial offtakers to bypass traditional utility procurement and contract directly with independent generators.
Growth Catalysts
- Industrial self-consumption frameworks:Phosphate processing and cement manufacturing facilities are deploying captive solar arrays under Tunisia's renewable energy law to hedge against grid tariff volatility.
- STEG grid reinforcement:The national utility's transmission expansion into southern governorates is unlocking utility-scale solar development where irradiance peaks.
- Net metering activation:Residential and commercial rooftop installations are accelerating as surplus generation earns feed-in credits against consumption bills.
Market Restraints
- Gas import dependency:Combined-cycle plants rely on Algerian pipeline supply and LNG spot markets, exposing STEG to fuel cost pass-through limitations under regulated end-user tariffs.
- Grid code compliance costs:Connection standards for intermittent renewable assets impose transformer and synchronization equipment burdens that erode project returns in rural interconnection zones.
- Land tenure complexity:Utility-scale solar concessions in southern Tunisia face customary land claims and state property classification disputes that delay permitting timelines.
Strategic Opportunities
- Gabès industrial corridor:Phosphate chemical complexes and desalination facilities present concentrated demand for hybrid solar-gas solutions with islanding capability.
- Green hydrogen pilot zones:The Ministry of Energy and Mines is designating southern regions for electrolyzer deployment tied to export-oriented ammonia production.
- Behind-the-meter storage pairing:Battery integration with commercial rooftop solar is emerging as a bankable configuration for peak shaving under time-of-use tariff structures.
Industry Challenges
- Grid integration engineering:Distribution network operators lack standardized protocols for voltage regulation with high renewable penetration, forcing project-specific studies.
- Local content requirements:The renewable energy law mandates domestic sourcing thresholds that outstrip current manufacturing capacity for mounting structures and cabling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunisia Power Market |
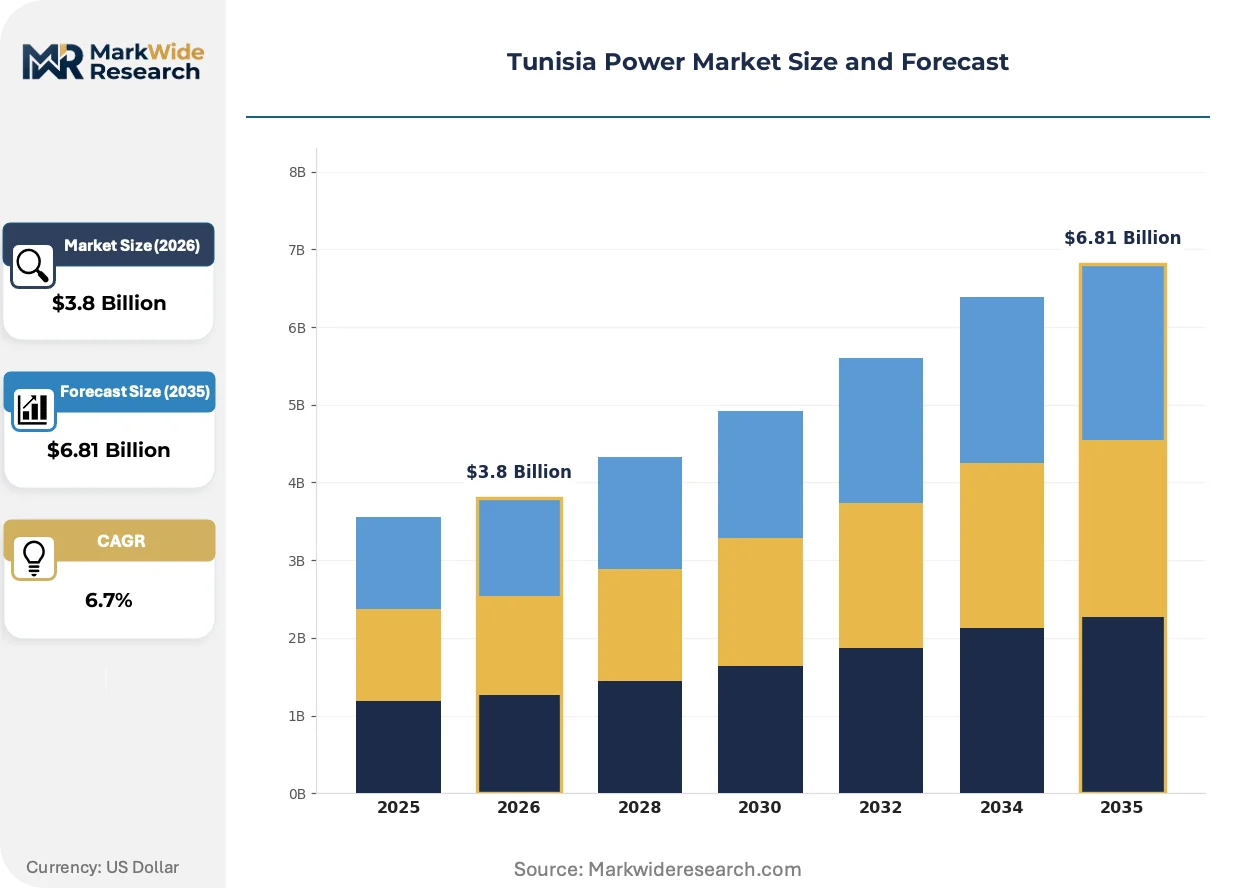
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar, Wind, Hydro, Biomass Technology: Photovoltaic, Concentrated Solar Power, Turbines, Gas Turbine End User: Residential, Industrial, Commercial, Government Installation: Onshore, Offshore, Utility-Scale, Distributed Generation |
| Companies Covered | Société Tunisienne de l'Électricité et du Gaz (STEG), Carthage Power Company, Scatec, Qair International, Voltalia, Ansaldo Energia, General Electric Company, Nur Energie, Seeraj Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunisia Power Market Evolving Landscape
Bifacial photovoltaic modules and string inverter architectures are compressing balance-of-system costs for Tunisian developers, while digital substation automation is reshaping how STEG manages intermittent renewable inflows at transmission interfaces.
String inverter technology is overtaking central inverter configurations in utility-scale Tunisian solar farms. Developers favor distributed power electronics for their granular fault isolation and reduced DC cabling losses. This shift is overtaking traditional engineering-procurement-construction contracting models that bundled single-point inverter responsibility.
Tunisia's renewable energy law and its implementing decrees are mandating competitive auction mechanisms for solar concessions above 10MW capacity. The Ministry of Energy and Mines now requires tariff bids below STEG's avoided cost, compressing developer margins. Industrial offtakers are responding by accelerating direct bilateral negotiations for smaller distributed projects exempt from auction rounds.
Commercial and industrial buyers are unbundling energy procurement from asset ownership, favoring power purchase agreements with third-party financiers over balance-sheet capex. This restructuring is displacing traditional equipment vendor relationships where manufacturers offered turnkey construction. The pattern concentrates in Tunis and Sfax manufacturing zones where creditworthy offtakers attract competitive developer bidding.
Tunisia Power Market Segmentation
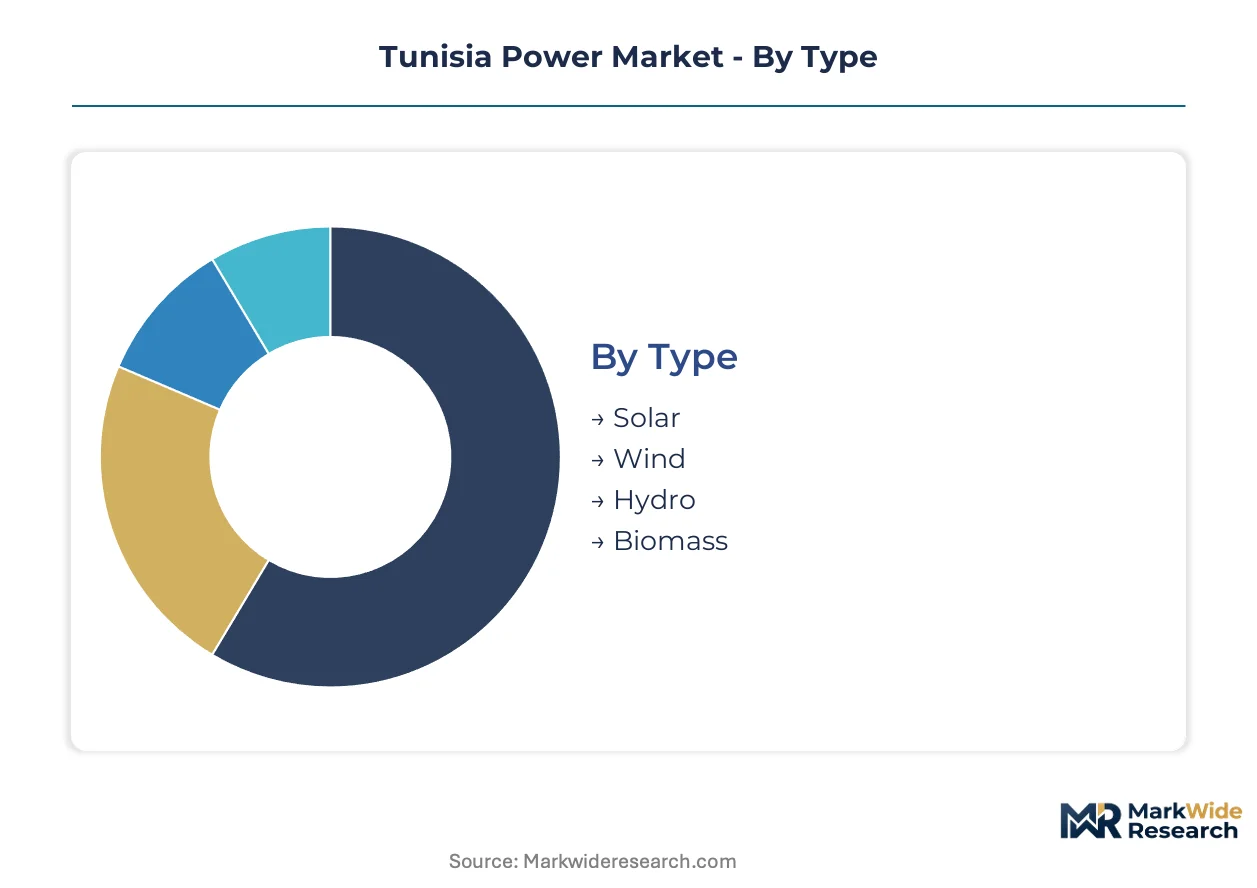
Segmentation in Tunisia's power market reveals how capital allocates across generation technologies, installation scales, and customer categories. Each dimension carries distinct regulatory treatment under the 2015 renewable energy law, shaping developer economics and offtake structures.
Type:
Supply concentrates in solar generation assets where irradiance peaks in southern governorates and interconnection capacity is expanding fastest.
- Solar:Photovoltaic arrays dominate new capacity additions, leveraging Tunisia's 2,500+ annual sun hours. Phosphate processing facilities in Gabès and cement plants near Sfax are deploying captive solar under self-consumption frameworks to hedge grid tariff volatility.
- Wind:Onshore turbines concentrate in northern regions with consistent Mediterranean wind patterns. Grid code compliance costs for intermittent output and land tenure disputes in rural zones constrain project timelines.
- Hydro:Existing run-of-river facilities provide dispatchable baseload with limited expansion potential. Aging infrastructure in the Kasserine region requires rehabilitation investment.
- Biomass:Agricultural residue-fired plants serve localized industrial heat demand. Olive processing cooperatives in Sidi Bouzid present captive feedstock opportunities.
Today's leader: Solar. Tomorrow's challenger: Wind.
Technology:
Cost tier differentiation separates mature photovoltaic deployment from emerging concentrated solar configurations requiring specialized engineering.
- Photovoltaic:Bifacial modules and string inverter architectures compress balance-of-system costs. Distributed power electronics enable granular fault isolation, displacing traditional central inverter contracting models.
- Concentrated Solar Power:Parabolic trough systems with thermal storage offer dispatchable renewable output for industrial corridors. Higher capex and water consumption requirements limit deployment to utility-scale concessions.
- Turbines:Horizontal-axis wind turbines anchor onshore wind farms with standardized IEC class certifications. Grid integration studies impose project-specific voltage regulation protocols.
- Gas Turbine:Combined-cycle configurations sustain baseload reliability through Algerian pipeline supply and LNG spot procurement. STEG's regulated tariff structure limits fuel cost pass-through exposure.
Photovoltaic commands current deployment volume. Concentrated Solar Power offers the steepest expansion trajectory if storage economics improve.
End User:
Customer type determines procurement channel access, with industrial offtakers leveraging direct bilateral negotiations exempt from competitive auction rounds.
- Industrial:Phosphate chemical complexes and desalination facilities present concentrated demand for hybrid solar-gas solutions. Creditworthy manufacturing zones in Tunis and Sfax attract competitive developer bidding for power purchase agreements.
- Residential:Rooftop solar adoption accelerates under net metering frameworks enabling surplus feed-in credits. Grid reinforcement timelines in urban distribution networks constrain interconnection capacity.
- Commercial:Behind-the-meter storage pairing with rooftop solar emerges as a bankable configuration for peak shaving under time-of-use tariff structures.
- Government:Public building portfolios and municipal infrastructure drive standardized procurement through STEG-managed concession frameworks.
Industrial offtakers lead procurement innovation. Residential distributed generation is gaining share fastest as net metering activation spreads.
Installation:
Geography and scale determine regulatory pathway, with utility-scale projects facing competitive auction mandates above 10MW capacity thresholds.
- Utility-Scale:Solar concessions above 10MW require tariff bids below STEG's avoided cost under Ministry of Energy and Mines auction mechanisms. Southern governorates with transmission expansion unlock development where irradiance peaks.
- Distributed Generation:Commercial and industrial rooftop installations below auction thresholds enable direct bilateral negotiations. Third-party financiers displace balance-sheet capex through power purchase agreement structures.
- Onshore:Wind and solar deployment concentrates in accessible terrain with established road infrastructure and grid proximity.
- Offshore:Mediterranean offshore wind remains pre-commercial with seabed leasing frameworks under development by national energy regulators.
Utility-scale anchors generation capacity. Distributed generation offers the fastest regulatory pathway for commercial and industrial offtakers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tunisia's power sector emerged from French colonial infrastructure investments in the early 20th century, with the Compagnie Tunisienne de l'Électricité et du Gaz establishing generation and distribution networks that STEG later nationalized in 1962.
Grand Tunis
The capital region concentrates manufacturing demand from automotive suppliers and textile exporters seeking behind-the-meter solar under net metering frameworks. The Ministry of Energy and Mines administers licensing for commercial rooftop installations exceeding 30kW capacity. Industrial zones in La Soukra and Borj Cédria host captive generation projects that bypass STEG's regulated tariff structure.
Sfax Governorate
Cement manufacturing clusters and olive processing cooperatives drive distributed generation procurement in Tunisia's second-largest city. The 2015 renewable energy law enables direct bilateral power purchase agreements for installations below auction thresholds. Sfax-Thyna industrial park attracts third-party financiers offering energy-as-a-service models to creditworthy offtakers.
Gabès Region
Phosphate chemical complexes and desalination facilities present concentrated demand for hybrid solar-gas configurations with islanding capability. The national energy regulator designates this corridor for pilot green hydrogen zones tied to export-oriented ammonia production. Groupe Chimique Tunisien facilities anchor industrial load centers where developers compete for long-term offtake contracts.
Southern Governorates
Tozeur, Kebili, and Tataouine host utility-scale solar concessions where irradiance exceeds 2,500 annual sun hours and transmission expansion unlocks grid interconnection. Competitive auction mechanisms mandate tariff bids below STEG's avoided cost for projects above 10MW capacity. The Ministry of Energy and Mines prioritizes this region for electrolyzer deployment feeding European green hydrogen offtake.
Bizerte Governorate
Gas-fired generation infrastructure anchors baseload reliability near the Algerian pipeline interconnection point. Carthage Power Company operates combined-cycle capacity that integrates with intermittent renewable output from northern wind farms. The region's grid stability supports voltage regulation protocols for high renewable penetration scenarios.
Tunisia Power Market Competitive Landscape
The competitive structure tilts toward hybrid archetypes combining development expertise with balance-sheet capacity for long-dated power purchase agreements. Developer-finance partnerships dominate procurement channels as industrial offtakers reject balance-sheet capex in favor of third-party ownership structures. Three archetypes define positioning: utility-scale concessionaires bidding auction rounds, distributed generation specialists navigating regulatory complexity for commercial clients, and integrated gas operators sustaining baseload reliability. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with developers securing land positions ahead of grid reinforcement timelines.
Among North African development platforms, Scatec exemplifies the utility-scale concessionaire archetype through competitive auction participation. Voltalia occupies a position within the distributed generation tier, structuring bilateral negotiations for commercial and industrial clients exempt from mandatory bidding rounds. Carthage Power Company anchors conventional capacity provision, representing the integrated gas operator model that sustains grid stability amid renewable intermittency.
| Leading Market Players |
|---|
| Société Tunisienne de l'Électricité et du Gaz (STEG) |
| Carthage Power Company |
| Scatec |
| Qair International |
| Voltalia |
| Ansaldo Energia |
| General Electric Company |
| Nur Energie |
| Seeraj Energy |
| Others |
Value Network & Pricing Analysis
Industrial offtakers in phosphate processing and cement manufacturing anchor pricing power through long-term power purchase agreements that bypass STEG's regulated tariff structure. The 2015 renewable energy law enables direct bilateral negotiations, compressing developer margins while securing price certainty for creditworthy buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Tunisia power market. Premium tiers attach to hybrid solar-gas configurations with islanding capability for Gabès industrial corridors, while standard tiers cover utility-scale solar concessions bid below STEG's avoided cost. Economy tiers capture residential net metering installations with surplus feed-in credits. Price differentiation rests on interconnection capacity availability and grid code compliance burden. Cost compression in utility-scale segments intensifies because competitive auction mechanisms mandate tariff underbidding. Industrial offtakers exhibit lowest price sensitivity due to captive generation hedging against grid volatility, while residential rooftop adopters face highest sensitivity to upfront capex requirements.
Supply Chain Analysis
Module refurbishment and inverter remanufacturing flows remain underdeveloped in Tunisia's power sector, creating stranded asset risk for early-generation solar installations. Geographic supply concentration centers on China for photovoltaic modules, Germany for string inverter electronics, and Algeria for pipeline gas feedstock. Raw material dependencies span polysilicon ingots, lithium-ion battery cells for storage pairing, and high-grade steel for mounting structures. Single-source vulnerability in polysilicon procurement from Chinese manufacturers exposes project timelines to export restriction risk. Distribution runs through EPC contractors with North African development platforms, who bundle engineering and construction risk for utility-scale concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tunisia power market functions as a regulatory compounder where the 2015 renewable energy law and its net metering implementing decrees continuously expand addressable demand through successive auction rounds and self-consumption frameworks.
For Market Incumbents: Lock in land positions in southern governorates ahead of STEG transmission expansion timelines. Secure grid interconnection reservations for utility-scale solar concessions before competitive auction saturation compresses returns further. Deepen backward integration into mounting structure fabrication to satisfy local content mandates that outstrip domestic manufacturing capacity. Prioritize hybrid solar-gas engineering capabilities for Gabès industrial corridor opportunities where phosphate chemical complexes demand islanding reliability. For New Entrants and Emerging Players: Begin with distributed generation specialization for commercial and industrial rooftop installations below 10MW auction thresholds. Target Sfax manufacturing zones and Tunis automotive supplier parks where creditworthy offtakers seek energy-as-a-service models without balance-sheet capex. Penetrate behind-the-meter storage pairing configurations for peak shaving under time-of-use tariff structures, leveraging third-party financier relationships that displace traditional equipment vendor turnkey contracting. For Investors and Strategic Acquirers: European utilities with North African development mandates are the most active acquirer in this space, seeking operational solar assets with long-dated power purchase agreements. The five-to-ten year viability window favors developers with established Ministry of Energy and Mines licensing relationships and proven grid code compliance track records. Acquisition target archetypes include distributed generation specialists with bilateral negotiation expertise and utility-scale concessionaires with southern governorate land banks. Monitor upcoming auction round participation rates and STEG transmission reinforcement announcements as early signals of developer margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term offtake contracts with Groupe Chimique Tunisien anchor project financeability for Gabès corridor developments. |
| Grid Interconnection Reservation | Early STEG queue positioning in Tozeur and Kebili unlocks utility-scale solar development where irradiance peaks. |
| Local Content Compliance Investment | Domestic mounting structure fabrication satisfies renewable energy law thresholds that outstrip current manufacturing capacity. |
| Hybrid Solar-Gas Configuration | Islanding capability integration addresses phosphate processing reliability requirements in designated green hydrogen pilot zones. |
| Behind-the-Meter Storage Pairing | Battery integration with commercial rooftop solar enables peak shaving under evolving time-of-use tariff structures. |
Research Methodology
Coverage spans North African power markets with primary inputs from each, combining structured interviews with utility planning officers at STEG, independent power producer project developers, EPC contractors with regional development platforms, and grid operators managing transmission expansion timelines. Secondary validation draws from IEA renewable energy reports, EIA country analysis briefs, FERC regulatory precedent filings for comparable market structures, and project development databases tracking concession awards. Bottom-up capacity addition modeling triangulates against top-down macroeconomic demand projections.
Rate-of-change decomposition separates volume growth into capacity factor improvements, technology cost declines, and regulatory activation effects across the analysis window. Segmentation dimensions modeled include fuel source bifurcation between solar and gas generation, project scale tiering across utility-scale and distributed generation thresholds, regulatory framework differentiation between auction mandates and bilateral exemptions, and regional grid type classification by transmission reinforcement status. CAGRs derive from iterative convergence of demand elasticity estimates and supply cost curve positioning, with photovoltaic module price trajectories and Algerian pipeline gas contract renegotiation patterns as key forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to Algerian fuel supply, currency devaluation impacts on imported equipment costs, and abrupt renewable energy law amendment. Forecasts reflect documented assumptions regarding STEG grid reinforcement execution timelines and industrial offtaker creditworthiness stability. Practitioners should monitor Ministry of Energy and Mines auction round frequency adjustments and electrolyzer pilot zone designation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Europe Distributed Power Generation Market
Power Generation
United Kingdom Power Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Australia Thermal Power Market
Power Generation
Global Power Generation Market
Power Generation
Gas Gensets Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Indonesia Power Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Global Power Grid System Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Stirling Engine Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Power Generation Technologies Market
Power Generation
Distributed Power Generation Market