
 Utility Solar PV EPC Market | 2026-2036
Utility Solar PV EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Solar PV EPC Market Analysis
Market Context
Utility procurement channels for solar engineering, procurement, and construction services is tilting toward direct developer-to-EPC contracting models that bypass traditional general contractors. First Solar leverages its integrated thin-film module manufacturing to capture downstream EPC margins across utility-scale projects in the American Southwest. Sterling and Wilson anchors its competitive position through specialized desert installation expertise and grid interconnection capabilities in Middle Eastern markets. JUWI AG competes by combining European project development experience with modular construction methodologies that compress commissioning timelines.
Technical Definition and Structural Segments
Utility Solar PV EPC encompasses the end-to-end design, equipment sourcing, civil works, module mounting, electrical integration, and grid connection of photovoltaic generating stations typically exceeding 20 MWac capacity, with single-axis tracking systems and 1500 V DC string architecture now standard for minimizing balance-of-system costs. The primary commercial purpose is delivering turnkey renewable generation assets that achieve guaranteed production thresholds under power purchase agreements. Utility-scale project size segments dominate absolute capacity additions and capital deployment, while bifacial technology segments command premium EPC pricing due to specialized mounting and albedo optimization requirements. Service-type segments reveal construction and procurement as the margin-intensive phases where EPC firms exercise greatest supply chain control.
Regulatory Frame and Outlook
India's Central Electricity Authority mandates domestic content requirements under the Approved List of Models and Manufacturers, while the US Federal Energy Regulatory Commission governs interstate transmission interconnection queues that determine project commercialization timelines. The EU Green Deal and F-Gas Regulation collectively shape module import standards and inverter cooling system specifications across European utility pipelines. Stakeholders must monitor interconnection queue reform proceedings and evolving domestic manufacturing incentive structures as decisive variables for EPC backlog visibility and margin sustainability.
Market Dynamics
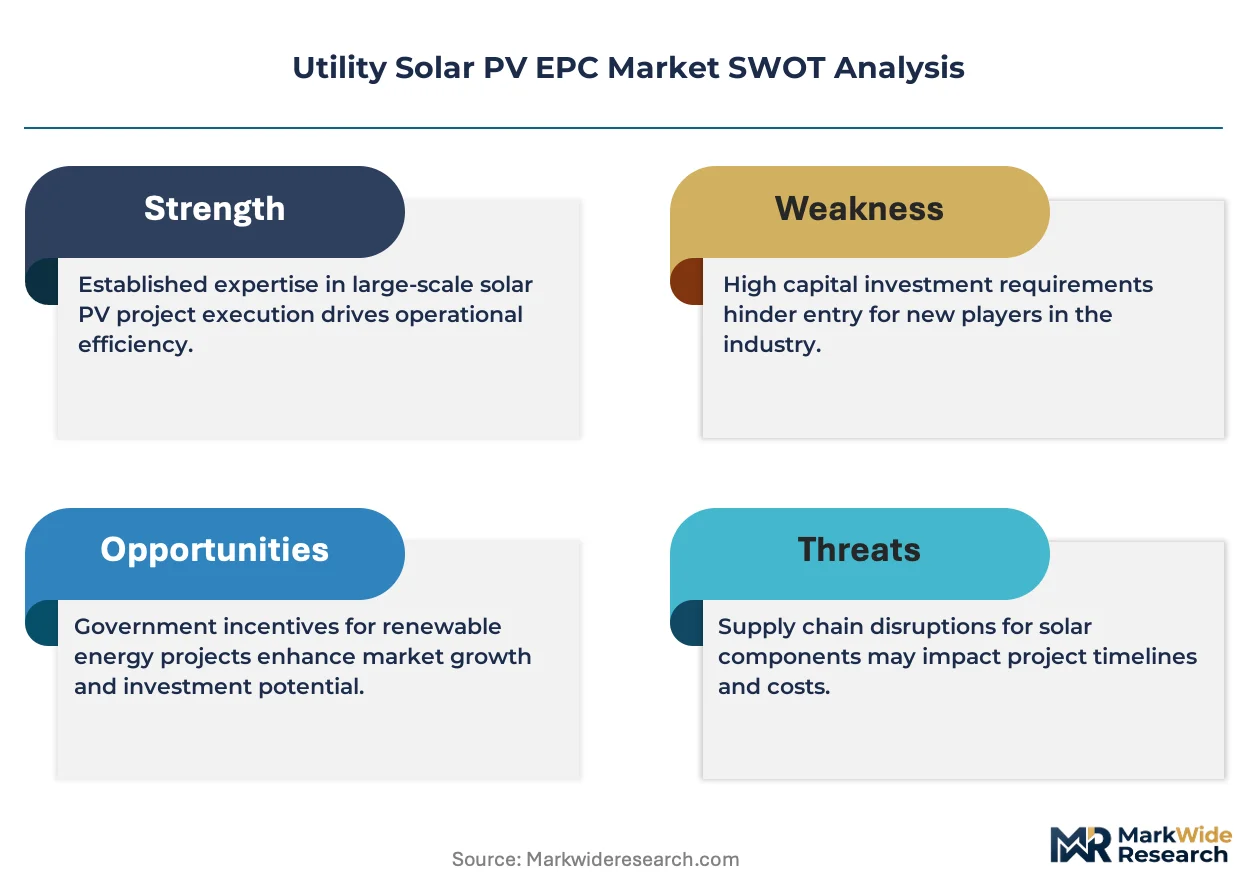
Utility-scale solar EPC contracting is consolidating around direct developer relationships as procurement bypasses traditional general contractors, compressing margin pools for intermediary construction firms and elevating integrated module-to-EPC providers.
Growth Catalysts
- Domestic Content Mandates:India's CEA Approved List of Models and Manufacturers redirects supply chains toward local module assembly, creating captive demand for Indian EPC execution capability.
- Interconnection Queue Reform:FERC proceedings on transmission access timelines accelerate project commercialization velocity across the American Southwest utility pipeline.
- Bifacial Technology Maturation:Albedo-optimized mounting systems and 1500 V DC string architecture reduce balance-of-system costs per watt, expanding project IRR thresholds for utility offtakers.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-origin material restrictions under US UFLPA and EU forced labor due diligence rules fragment module sourcing, elevating procurement risk premiums.
- Skilled Labor Scarcity:Certified solar electricians and HV grid interconnection engineers remain concentrated in Germany, California, and Gujarat, constraining execution bandwidth in emerging markets.
- Land Access Friction:Agricultural land-use conflicts and environmental review timelines under NEPA and equivalent state-level statutes extend pre-construction phases by 18-36 months in prime irradiance zones.
Strategic Opportunities
- Saudi Arabia Gigawatt Pipeline:NEOM and PIF-backed renewable targets create execution demand for desert installation expertise and grid-scale storage integration.
- Agrivoltaic Convergence:Dual-use land configurations combining sheep grazing or shade-tolerant crops with bifacial arrays open new project development categories in agricultural states.
- Green Hydrogen offtake:Electrolyzer load contracts tied to dedicated solar generation create EPC bundling opportunities around 24/7 clean power supply guarantees.
Industry Challenges
- Grid Synchronization Complexity:Utility-scale inverters must meet evolving IEEE 1547-2018 and local grid code requirements for frequency ride-through and reactive power support, extending commissioning testing protocols.
- Module Warranty Enforcement:Degradation rate disputes and performance guarantee claims create litigation exposure across 25-year asset lifecycles, demanding specialized EPC contractual indemnification structures.
Report Scope
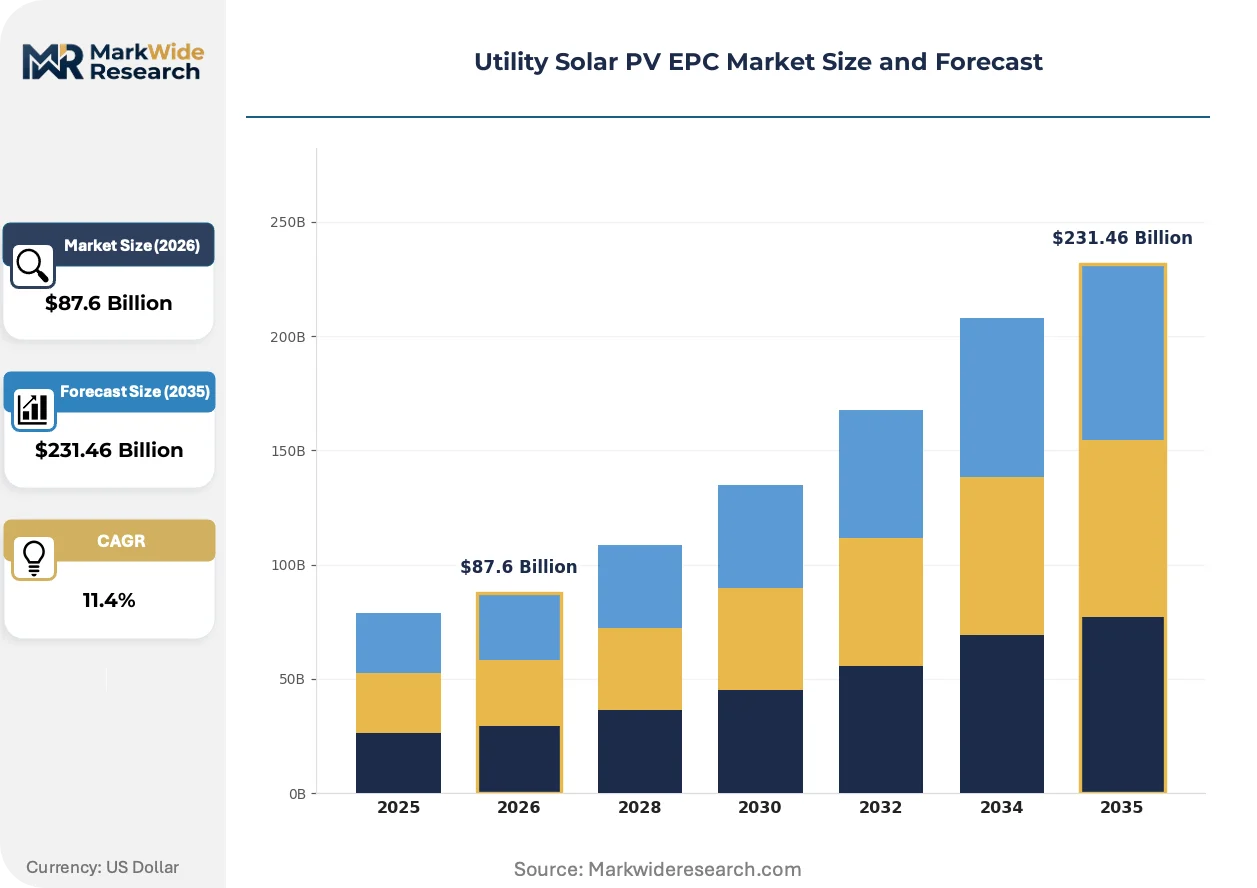
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Solar PV EPC Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Size: Small Scale, Medium Scale, Large Scale, Utility Scale End Use: Residential, Commercial, Industrial, Utilities Technology: Monocrystalline, Polycrystalline, Bifacial, Thin Film Service Type: Design, Procurement, Construction, Maintenance |
| Companies Covered | First Solar, Canadian Solar, Trina Solar, Sterling and Wilson, ACME Solar, BELECTRIC, JUWI AG, Swinerton Renewable Energy, Bharat Heavy Electricals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Solar PV EPC Market Emerging Trajectories
Digital construction methodologies and automated quality assurance systems are compressing project timelines while regulatory pressure on supply chain provenance is forcing traceability investments across module procurement.
Drone-mounted thermal imaging and LiDAR surveying is digitizing pre-construction site assessment and ongoing performance monitoring, enabling predictive maintenance scheduling. EPC firms deploying these systems reduce manual inspection labor by half and accelerate defect detection during commissioning. Major utility developers now mandate digital twin documentation as a handover deliverable, embedding asset management platforms from day one.
The EU F-Gas Regulation and US EPA SNAP program are phasing down hydrofluorocarbon refrigerants in inverter cooling systems, accelerating adoption of liquid-cooled and air-cooled architectures. String inverter suppliers must redesign thermal management to maintain efficiency ratings under new coolant constraints. European utility pipelines are prioritizing SF6-free switchgear and low-GWP cooling to preempt compliance costs and green financing eligibility requirements.
Direct EPC contracting between project developers and specialized construction firms is displacing traditional engineering-procure-construct general contractor intermediaries. This channel compression transfers margin from generalist builders to module-integrated EPC providers with captive supply chains. The shift is most visible in India and the American Southwest, where First Solar and domestic champions leverage manufacturing scale to capture downstream construction economics.
Utility Solar PV EPC Market Segmentation
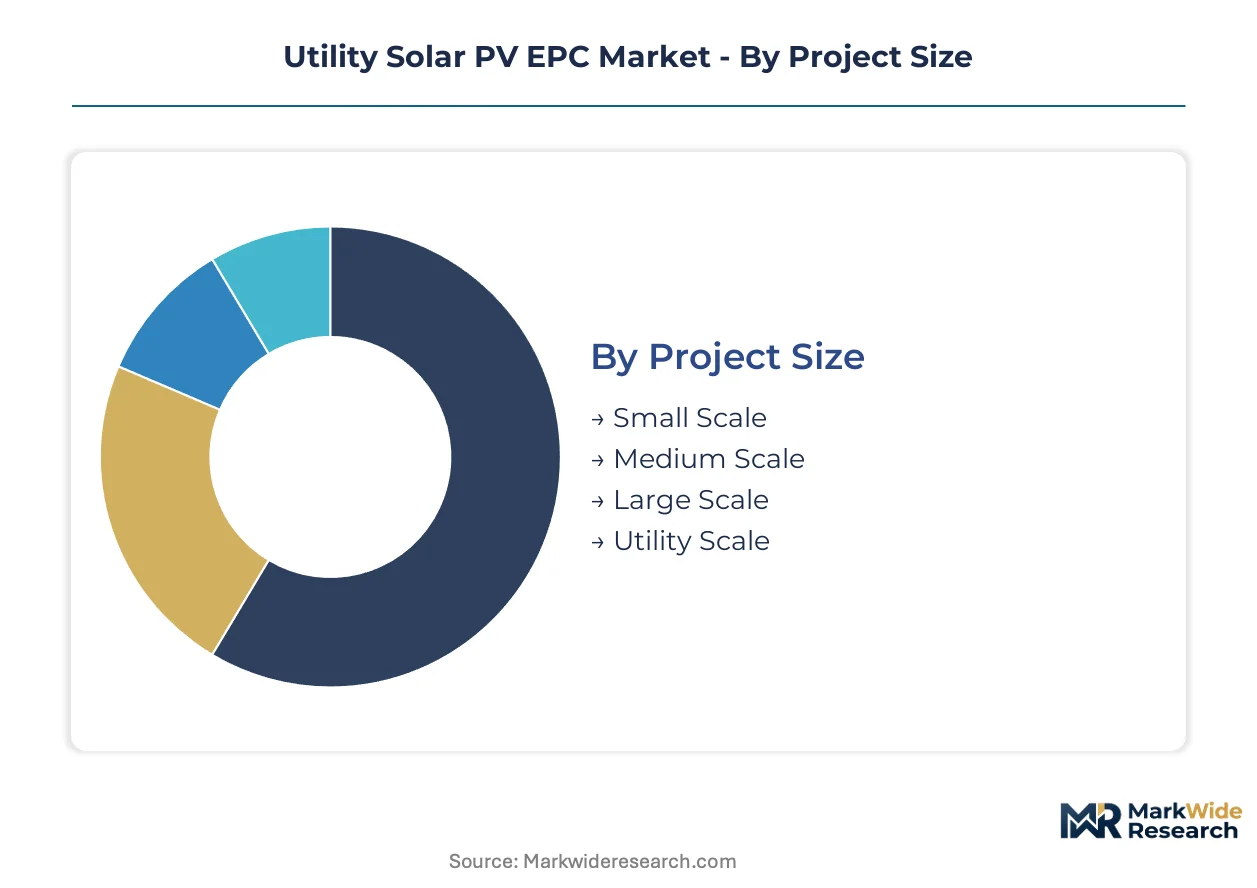
Segmentation in utility solar PV EPC contracting reveals how capital deployment, technology selection, and service bundling determine margin capture. Project developers align procurement strategies with specific segment characteristics to optimize balance-of-system costs and interconnection timelines.
Project Size:
Capacity tiers differentiate engineering complexity, labor specialization requirements, and developer capital access thresholds.
- Small Scale:Systems below 5 MWac serve distributed generation and community solar mandates. Indian state-level net metering policies and German EEG tariff structures concentrate procurement in these sub-utility configurations.
- Medium Scale:Installations from 5-20 MWac bridge commercial offtake and wholesale market participation. Texas ERCOT nodal pricing and Australian NEM spot market exposure drive merchant revenue stacking in this tier.
- Large Scale:Projects from 20-100 MWac dominate independent power producer portfolios. California CAISO queue positions and Spanish grid access permits determine development velocity for this capacity band.
- Utility Scale:Installations exceeding 100 MWac command dedicated transmission infrastructure and long-term PPA structuring. Saudi Arabia PIF-backed gigawatt pipelines and Indian SECI auctions anchor global demand concentration here.
Utility Scale holds installed capacity. Large Scale is rotating up the share rankings.
End Use:
Customer archetypes shape contracting risk allocation, financing structures, and operational performance guarantees.
- Residential:Behind-the-meter installations under 20 kWac with net metering or self-consumption economics. Australian STC incentives and Brazilian PROINFA distributed generation rules sustain deployment in this segment despite EPC margin compression.
- Commercial:C&I rooftops and carport configurations from 100 kWac to 5 MWac. California NEM 3.0 export compensation cuts and Vietnam direct power purchase agreement pilots are redirecting procurement toward onsite consumption optimization.
- Industrial:Large manufacturing load centers seeking 24/7 renewable supply through virtual PPAs or physical offtake. Green hydrogen electrolyzer loads in Spain and data center commitments in Virginia are expanding EPC bundling with storage integration.
- Utilities:Investor-owned and publicly owned generation portfolios procuring central-station assets. FERC Order 841 storage participation rules and India's green hydrogen mission are reshaping RFP specifications toward hybrid solar-plus-storage configurations.
Utilities command capital deployment. Industrial is climbing the fastest as corporate procurement accelerates.
Technology:
Module architecture determines mounting system design, albedo optimization requirements, and inverter string sizing.
- Monocrystalline:PERC and TOPCon cell structures with 21-23% module efficiency. Chinese manufacturing scale and Indian PLI scheme localization are concentrating supply for this dominant technology platform.
- Polycrystalline:Multi-crystalline silicon with cost advantages in price-sensitive emerging markets. Limited deployment in new utility pipelines as efficiency gaps widen against monocrystalline alternatives.
- Bifacial:Dual-glass modules capturing rear-side irradiance with 10-20% energy yield gains. Albedo-optimized mounting systems in Saudi Arabian desert installations and tracking configurations in Chilean Atacama sites command specialized EPC expertise and premium pricing.
- Thin Film:Cadmium telluride and CIGS architectures with superior temperature coefficients and low-light performance. First Solar's integrated manufacturing-to-EPC model dominates American Southwest utility deployment where heat and soiling conditions favor this technology.
Monocrystalline leads module shipments. Bifacial is gaining share fastest as tracking system compatibility improves.
Service Type:
Phase-specific contracting determines where EPC firms capture margin and assume performance risk.
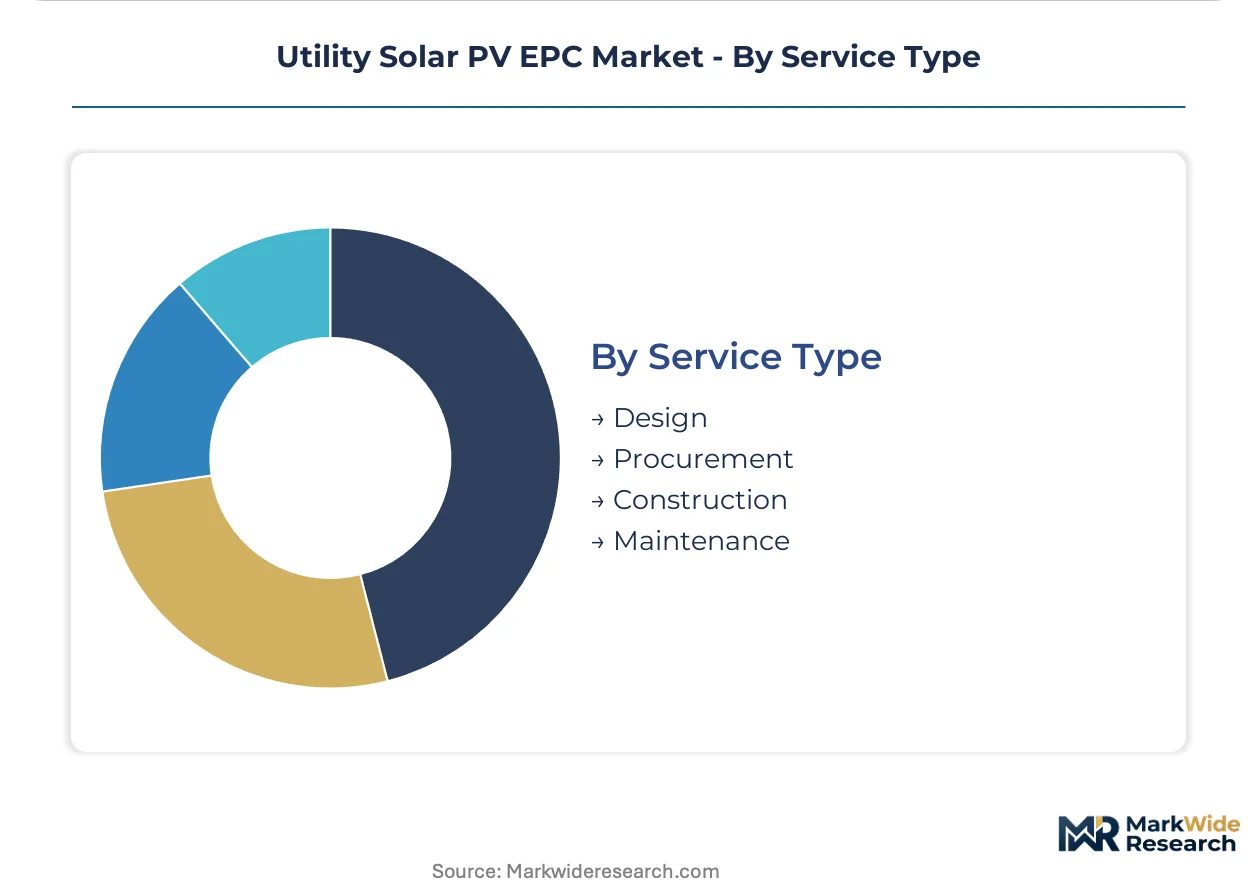
- Design:Site assessment, electrical engineering, and grid interconnection studies. IEEE 1547-2018 compliance documentation and CAISO generator interconnection request preparation concentrate specialized engineering fees in this phase.
- Procurement:Module, inverter, and balance-of-system sourcing with supply chain traceability requirements. US UFLPA enforcement and EU forced labor due diligence rules are elevating procurement risk premiums and documentation burdens.
- Construction:Civil works, mechanical assembly, and electrical integration with milestone-based payment structures. Desert installation expertise in the UAE and HV grid connection capability in Germany represent scarce execution bandwidth commanding margin premiums.
- Maintenance:O&M services including performance monitoring, corrective maintenance, and module cleaning. Drone-based thermal inspection and predictive analytics are digitizing service delivery and extending asset management contract durations.
Construction captures the largest revenue pool. Procurement is expanding most quickly as supply chain localization mandates deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC's interconnection queue reforms and India's CEA domestic content mandates are reshaping where capital deploys fastest. The United States, India, China, Saudi Arabia, and Germany concentrate utility-scale EPC execution bandwidth and regulatory innovation.
United States
Texas ERCOT nodal pricing and California CAISO interconnection queues drive gigawatt-scale procurement. FERC Order 2023 reforms accelerate transmission access timelines for Southwest utility pipelines. Arizona and Nevada desert installations anchor First Solar's integrated manufacturing-to-EPC model deployment.
India
SECI auctions and state-level renewable purchase obligations sustain 20+ GW annual installation targets. The PLI scheme for domestic module manufacturing redirects supply chains toward Gujarat and Tamil Nadu assembly hubs. Rajasthan's Bhadla and Pavagada solar parks concentrate execution demand for desert installation specialists.
China
Provincial renewable portfolio standards and state-owned utility procurement sustain the world's largest annual capacity additions. NEEA grid integration standards govern HV transmission connections for northwest desert installations. Xinjiang and Inner Mongolia project pipelines concentrate execution despite polysilicon sourcing scrutiny.
Saudi Arabia
PIF-backed gigawatt targets under Vision 2030 and NEOM renewable mandates create execution demand for bifacial tracking systems. The Saudi Electricity Company interconnects large-scale assets through dedicated transmission corridors. Tabuk and Al-Jouf regions concentrate project development for desert-optimized EPC capability.
Germany
EEG tariff degression schedules and EU Green Deal acceleration targets revive utility-scale deployment after years of distributed focus. The Bundesnetzagentur governs grid connection priority for renewable assets in northern wind-solar hybrid zones. Brandenburg and Saxony-Anhalt brownfield redevelopment sites concentrate tracking system installations.
Utility Solar PV EPC Market Vendor Landscape
Module-integrated EPC providers and specialized desert installation contractors split the market between captive supply chain control and execution expertise. The vendor base concentrates around three strategic archetypes: thin-film manufacturers with downstream construction arms, regional specialists with grid interconnection capabilities, and diversified industrial conglomerates with civil works scale. Dominant competitive moves include backward integration into module manufacturing and geographic expansion into Middle Eastern gigawatt pipelines.
Within the integrated-manufacturer tier, First Solar exemplifies thin-film-to-EPC vertical control. Among regional specialists, Sterling and Wilson occupies a position anchored in Middle Eastern desert execution. JUWI AG represents the European project-development-to-construction archetype with modular methodology deployment. These three sit within distinct competitive vectors rather than direct overlap.
| Leading Market Players |
|---|
| First Solar |
| Canadian Solar |
| Trina Solar |
| Sterling and Wilson |
| ACME Solar |
| BELECTRIC |
| JUWI AG |
| Swinerton Renewable Energy |
| Bharat Heavy Electricals Limited |
| Others |
Supply Flow & Price Mechanics
Xinjiang polysilicon concentration tilts module procurement economics toward Southeast Asian cell assembly hubs, amplifying pricing power for integrated EPC providers with captive thin-film supply. India's PLI scheme and US UFLPA enforcement fragment sourcing pathways, forcing buyers to absorb traceability premiums or switch technology platforms entirely.
Pricing Analysis
Desert installation premiums in Saudi Arabia diverge from standardized EPC rates in Gujarat solar parks by margins reflecting specialized labor scarcity. Three-tier pricing structure across premium, standard, and economy levels separates bifacial tracking expertise from commodity fixed-tilt execution and basic procurement-only contracts. Cost compression in standard-tier construction is intensifying as Indian domestic module capacity floods adjacent EPC markets. Utility developers with hybrid solar-plus-storage mandates demonstrate lowest price sensitivity, while merchant IPPs in ERCOT nodal zones face acute margin pressure.
Supply Chain Analysis
Tariff exposure between China and the United States dominates procurement risk calculus, redirecting module flows through Vietnamese and Thai assembly facilities with elevated documentation burdens. Polysilicon refining in Xinjiang, cell manufacturing in Southeast Asia, and inverter production in Germany anchor the tier-one supplier map. Polysilicon ingots, glass substrates, and aluminum racking systems constitute the critical input trinity. Single-source vulnerability persists for 1500 V string inverters with grid-forming capability. Distribution runs through direct developer-to-EPC contracting channels that displace general contractor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among sovereign wealth funds and national utilities with gigawatt-scale procurement pipelines, fragmenting EPC margin pools and elevating integrated manufacturers with captive project pipelines.
For Market Incumbents: Harden project execution bandwidth in desert installation corridors through specialized HV grid interconnection engineering retention. Deepen backward integration into tracking system manufacturing to defend margin position against module-integrated competitors. The Saudi PIF and Indian SECI auction concentration represents the core threat to independent EPC contractors lacking manufacturing scale. For New Entrants and Emerging Players: Agrivoltaic convergence zones in agricultural states present execution white space with limited incumbent specialization. Target bifacial albedo optimization services as the most penetrable technical niche, bundling sheep grazing land management with array performance guarantees. A go-to-market angle anchored in drone-based thermal inspection and predictive O&M analytics accelerates commissioning credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors EPC firms with modular construction methodologies and European project development track records. Long-term viability across the projection horizon hinges on grid interconnection queue positioning and domestic content compliance capability. Acquisition targets should demonstrate desert execution expertise or HV substation integration capability. The signal to watch is FERC interconnection reform implementation velocity as inflection indicator for backlog visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tracking Systems | Captures balance-of-system margins previously ceded to specialized racking suppliers in Saudi gigawatt pipelines. |
| Desert Installation Certification Program | Addresses skilled labor scarcity through accredited training pipelines for bifacial albedo optimization. |
| Green Hydrogen EPC Bundling | Combines solar generation with electrolyzer load contracts under 24/7 clean power supply guarantees. |
| Digital Twin Asset Handover | Embeds predictive maintenance platforms from commissioning day, extending O&M contract durations. |
| Domestic Content Compliance Service | Navigates India's CEA Approved List and US UFLPA documentation burdens for developer clients. |
Methodological Framework
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, grid operators, and module supply specialists converged on the working assumptions underlying capacity and value estimates. Primary fieldwork combined structured interviews with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up installation tracking and top-down regulatory pipeline assessment were triangulated to anchor forecast boundaries.
Demand-supply-balance framing modeled utility-scale procurement velocity against interconnection queue clearance rates and domestic manufacturing capacity buildout across the projection horizon. Segmentation dimensions included project capacity tier, module technology platform, service type phase, and regional regulatory framework. CAGRs were derived from capacity-weighted average pricing trajectories and technology substitution curves. Forecast inputs incorporated bifacial penetration rates and storage co-location mandates as demand accelerators.
Practitioners should monitor interconnection queue reform proceedings, PLI scheme capacity allocation announcements, and polysilicon trade policy shifts for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Global Crystalline Solar Cells Market