
 Oil Pipeline Infrastructure Market | 2026-2036
Oil Pipeline Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Pipeline Infrastructure Market Analysis
API 5L X80 and X100 grade specifications is bifurcating procurement patterns across major trunkline projects. Enbridge Inc. leverages its Mainline system modernization to sustain throughput leadership across the Canadian-US corridor. Kinder Morgan Inc. anchors Trans Mountain expansion capacity, while Energy Transfer LP dominates Gulf Coast crude export logistics through its Nederland terminal complex.
Oil pipeline infrastructure comprises steel-conveyance systems engineered to API 5L, ASME B31.4, and ISO 3183 standards, typically operating at pressures between 600 and 1,440 psi for crude oil transmission over distances exceeding 1,000 kilometers. Onshore steel pipe installations occupy the largest installed base, though subsea composite pipe deployments are gaining share in deepwater tieback applications. Oil and gas companies command the dominant end-user segment, while refined products pipelines retain higher tariff stability due to demand inelasticity from Midwest and Northeast US markets.
PHMSA enforces integrity management protocols under 49 CFR Part 195, while EPA spill prevention mandates shape containment investment. API RP 1160 and NACE SP0169 standards govern corrosion control, directly influencing coating and cathodic protection specifications. Stakeholders must weigh stranded asset risk against replacement cycle timing as electrification policies and carbon border adjustments reshape long-term throughput commitments.
Market Dynamics
Permian Basin production growth is forcing midstream operators to accelerate pipeline replacement cycles while PHMSA tightens integrity management mandates under 49 CFR Part 195, compressing the window between inspection and remediation.
Growth Catalysts
- API 5L X80 grade specifications:Higher-strength steel reduces wall thickness requirements, cutting material costs for long-haul trunklines while maintaining pressure ratings above 1,200 psi.
- Petrochemical complex expansion:Gulf Coast ethylene crackers and derivative units are pulling additional crude volumes through dedicated feedstock pipelines.
- Smart pigging technology maturation:In-line inspection tools with axial magnetic flux leakage sensors now detect crack anomalies below two millimeters, extending predictive maintenance intervals.
Market Restraints
- Specialized steel supply concentration:API 5L X80 and X100 plate production clusters in South Korean and Japanese mills, exposing projects to alloy surcharge volatility.
- Electrification policy trajectory:State-level clean fuel standards in California and New York are eroding long-term throughput commitments from refiners.
- Carbon border adjustment exposure:EU CBAM phase-in threatens Gulf Coast export economics for carbon-intensive crudes lacking certified low-carbon intensity scores.
Strategic Opportunities
- Hydrogen blending infrastructure:Existing crude pipelines in the Netherlands and Germany are being retrofitted for hydrogen service under national hydrogen backbone strategies.
- CO2 transport repurposing:Decommissioned oil gathering systems in Texas and Louisiana offer ready conduit for carbon capture and sequestration projects.
- Digital twin integration:Real-time pressure and flow simulation layered atop SCADA systems is enabling dynamic capacity optimization without physical expansion.
Industry Challenges
- Weld inspector certification backlog:API 1104-qualified radiographic interpreters face eighteen-month training pipelines, delaying construction schedules.
- Legacy cathodic protection retrofit complexity:Pre-1980 pipelines with coal-tar enamel coatings require complete excavation for impressed current system upgrades.
- Landowner easement renegotiation friction:Twenty-year renewal cycles are triggering rate disputes as agricultural land values in the Bakken region triple since original agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Pipeline Infrastructure Market |
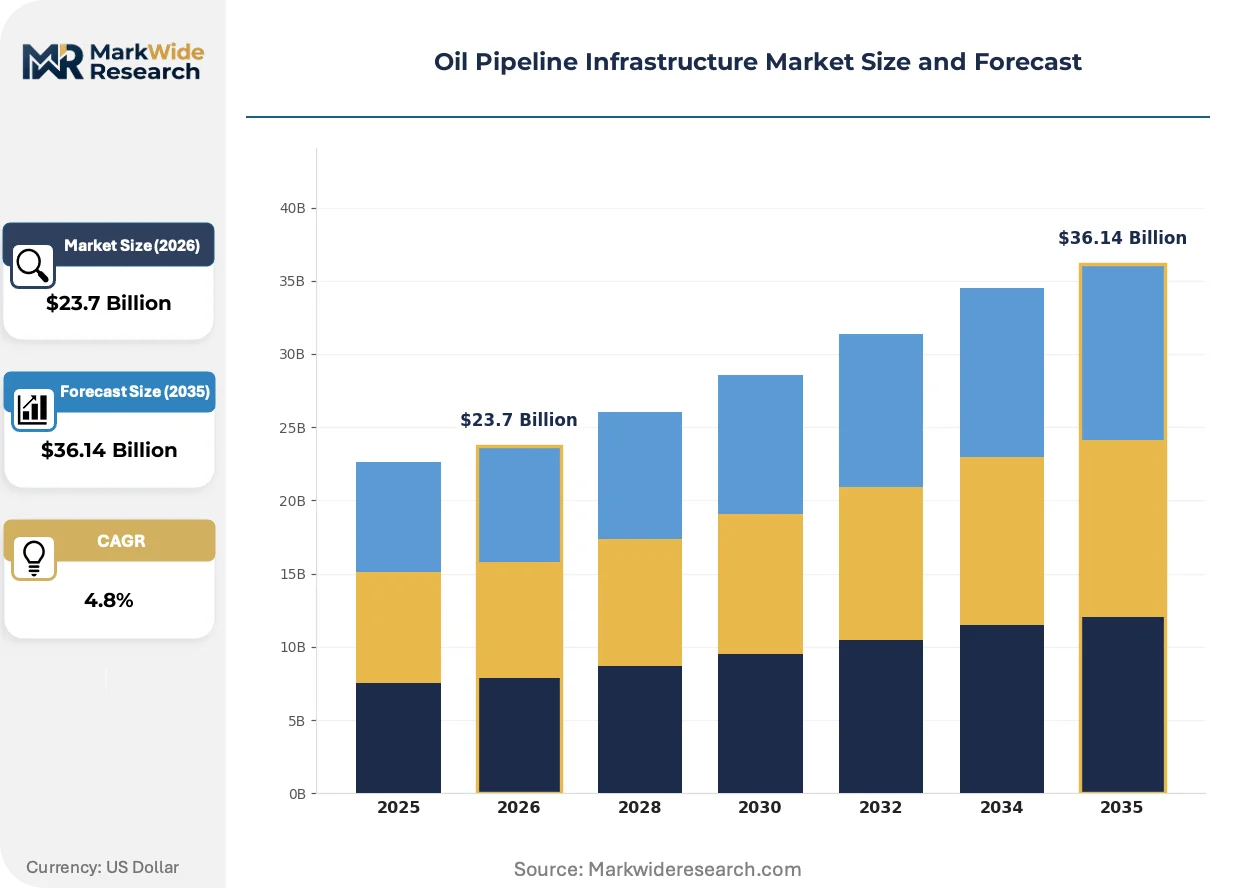
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Refined Products, Multi-Product Installation Type: Onshore, Offshore, Subsea, Aboveground End User: Oil & Gas Companies, Utilities, Industrial Users, Shipping Companies Technology: Steel Pipe, Composite Pipe, Thermoplastic Pipe, Others |
| Companies Covered | Enbridge Inc., Kinder Morgan Inc., Energy Transfer LP, TC Energy Corp., Pembina Pipeline Corp., Enterprise Products Partners L.P., Williams Companies Inc., ONEOK Inc., Plains All American Pipeline, L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Pipeline Infrastructure Market Emerging Trajectories
Pipeline integrity management is migrating from calendar-based inspection to condition-based monitoring, with fiber-optic sensing and satellite leak detection compressing incident response windows from hours to minutes.
Composite flexible pipe with thermoplastic polymer pressure barriers is supplanting rigid steel for subsea tiebacks in water depths exceeding 1,500 meters. Petrobras and Equinor are specifying this technology for pre-salt developments off Brazil and Norway. The shift is enabling single-lay vessel deployment, reducing offshore installation spreads by forty percent versus conventional steel-lay methods.
EPA's updated methane emissions standards under the Inflation Reduction Act impose leak detection and repair frequencies of quarterly for compressor stations above certain throughput thresholds. Operators must deploy optical gas imaging or equivalent technologies, with non-compliance penalties indexed to social cost of carbon calculations. Gathering and boosting segments in the Permian and DJ Basins face the steepest compliance cost escalations.
Buyers are consolidating engineering-procurement-construction contracts under lump-sum turnkey structures rather than cost-plus arrangements. Majors like ExxonMobil and Chevron are pushing risk onto contractors for geotechnical variability and regulatory delay. This transfer is most pronounced in Gulf Coast export terminal projects, where EPC margins have compressed three percentage points since 2022.
Oil Pipeline Infrastructure Market Segmentation
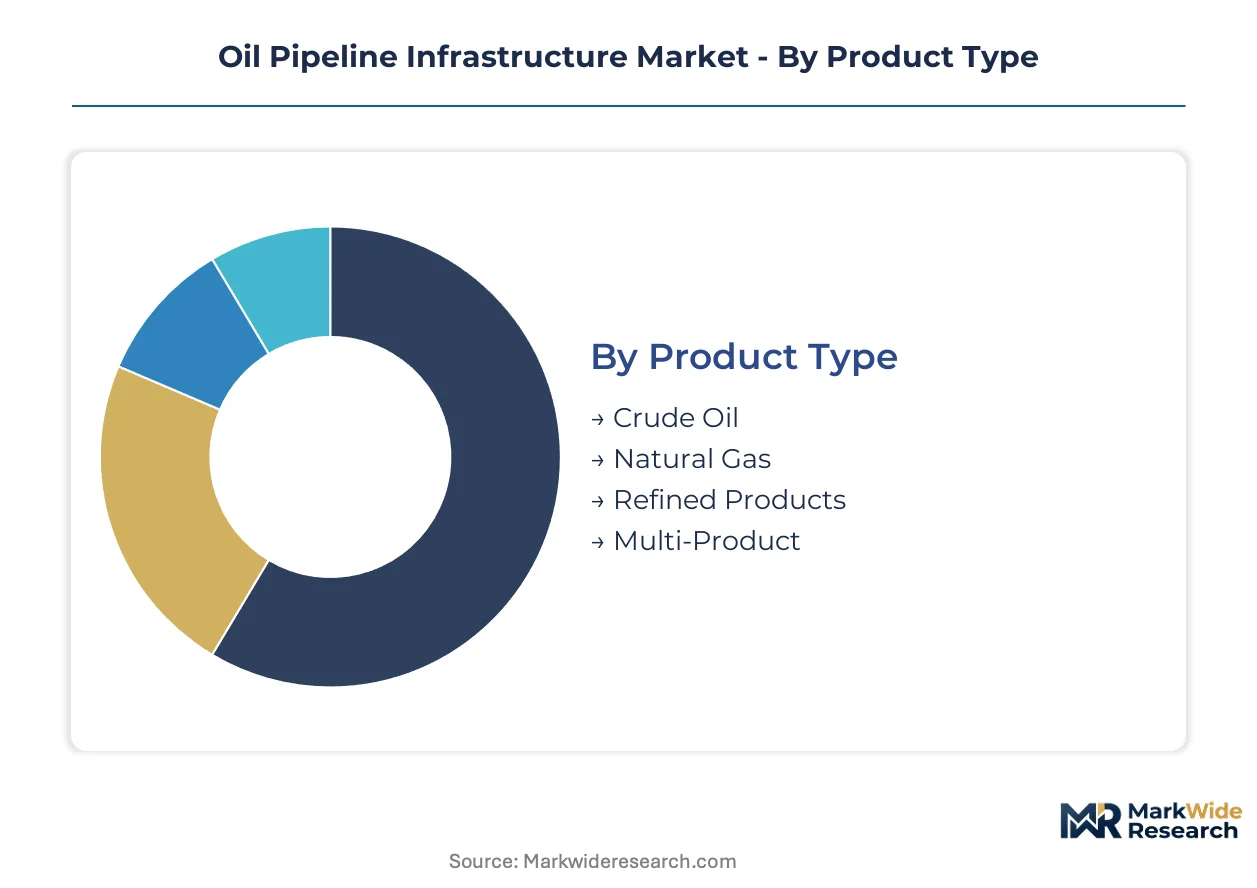
Pipeline infrastructure segmentation reveals distinct procurement patterns across product types and installation environments. Each dimension carries specific regulatory, material, and operational constraints that shape investment decisions and vendor selection criteria.
Product Type:
Crude oil and refined products pipelines dominate domestic throughput volumes, while multi-product systems anchor export corridor economics.
- Crude Oil:API 5L X80 and X100 grade specifications define material procurement for long-haul trunklines exceeding 1,000 kilometers. Permian Basin gathering systems and Gulf Coast export terminals in Texas and Louisiana concentrate replacement cycle demand as PHMSA tightens integrity mandates.
- Refined Products:Dedicated gasoline, diesel, and jet fuel pipelines operate under tariff structures with higher stability due to demand inelasticity from Midwest and Northeast US markets. Colonial Pipeline and Explorer Pipeline systems demonstrate this segment's resistance to throughput volatility.
- Natural Gas:Transmission pipelines bridge production basins to industrial load centers under FERC jurisdiction.
- Multi-Product:Batch-segregated systems enable flexible export logistics from Nederland and Corpus Christi terminals.
Crude oil pipelines command the established base. The steepest expansion runs through refined products infrastructure serving petrochemical feedstock demand.
Installation Type:
Cost tiers separate buried onshore networks from capital-intensive subsea developments requiring specialized lay vessels.
- Onshore:Buried steel pipe installations represent the largest installed base, typically operating at pressures between 600 and 1,440 psi. Landowner easement renegotiation friction in the Bakken region and Permian Basin compresses project timelines as agricultural land values escalate renewal disputes.
- Subsea:Composite flexible pipe with thermoplastic polymer pressure barriers is displacing rigid steel for tiebacks in water depths exceeding 1,500 meters. Petrobras pre-salt developments off Brazil and Equinor Norwegian fields specify this technology for single-lay vessel deployment.
- Offshore:Platform-to-platform connections in Gulf of Mexico shallow water face hurricane resilience requirements.
- Aboveground:Permian Basin pump stations and compressor facilities concentrate aboveground infrastructure replacement cycles.
Onshore buried systems retain the dominant share. Subsea composite installations are climbing the fastest as deepwater pre-salt fields advance development schedules.
End User:
Customer concentration varies sharply, with integrated majors driving trunkline investment and independent operators shaping gathering system demand.
- Oil & Gas Companies:Majors including ExxonMobil and Chevron consolidate engineering-procurement-construction contracts under lump-sum turnkey structures, transferring geotechnical and regulatory delay risk to contractors. Gulf Coast export terminal projects exhibit the most pronounced margin compression for EPC providers.
- Utilities:Regulated transmission operators prioritize tariff stability and rate-base growth over throughput maximization.
- Industrial Users:Petrochemical complexes along the Gulf Coast pull dedicated feedstock pipeline capacity.
- Shipping Companies:Marine terminal operators at Nederland and Corpus Christi coordinate export logistics infrastructure.
Oil and gas companies anchor capital deployment. Industrial users are expanding most quickly as ethylene cracker capacity additions accelerate.
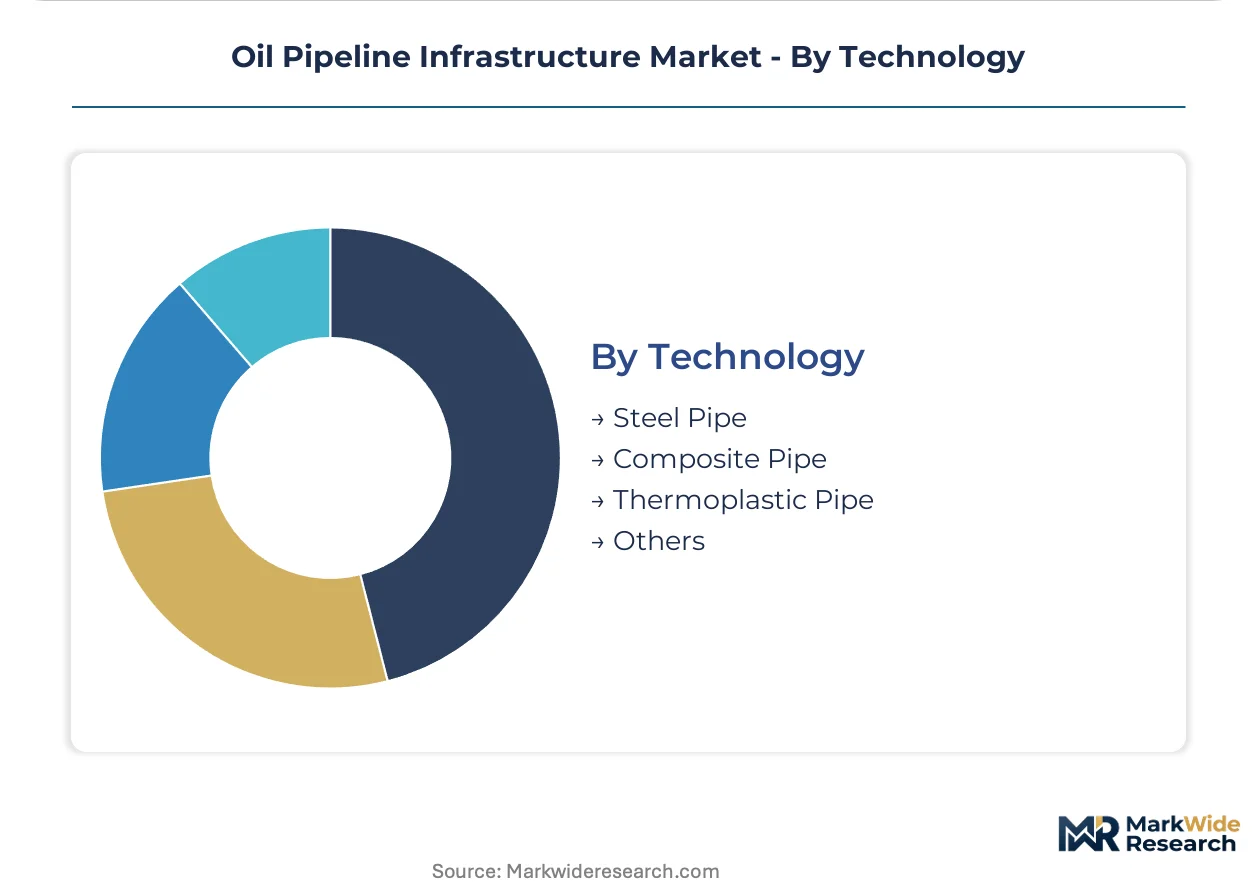
Technology:
Material selection bifurcates between high-strength steel for pressure-rated trunklines and polymer composites for corrosion-resistant subsea applications.
- Steel Pipe:API 5L, ASME B31.4, and ISO 3183 standards govern manufacturing specifications. South Korean and Japanese mills concentrate API 5L X80 and X100 plate production, exposing projects to alloy surcharge volatility and supply chain concentration risk.
- Composite Pipe:Thermoplastic pressure barriers enable corrosion immunity without cathodic protection systems. Deepwater tieback specifications from Petrobras and Equinor validate this technology for pre-salt and North Sea developments.
- Thermoplastic Pipe:Spoolable systems gain share in onshore gathering applications requiring rapid deployment.
- Others:Ductile iron and concrete pressure pipe retain niche roles in specific utility applications.
Steel pipe retains the incumbent position. Composite systems are gaining share fastest in subsea environments where corrosion resistance and installation efficiency outweigh material cost premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export corridor economics are redrawing pipeline investment maps as production basins compete for terminal access. Crude differentials and carbon intensity regulations now determine route viability more than distance alone.
United States
Permian Basin throughput expansion drives Gulf Coast export terminal construction. PHMSA's 49 CFR Part 195 integrity mandates compress inspection-to-remediation windows. The Nederland-Corpus Christi corridor concentrates new capacity additions serving waterborne export markets.
Canada
Western Canadian Select price differentials sustain Mainline system modernization investments. The Canada Energy Regulator oversees cross-border certificate applications under the Canadian Energy Regulator Act. Alberta's oil sands production anchors trunkline utilization rates through the US Midwest corridor.
Brazil
Pre-salt field development accelerates subsea composite pipeline deployment. ANP licensing requirements govern offshore installation permits and environmental compliance. The Santos Basin deepwater cluster drives flexible pipe specifications for single-lay vessel economics.
Norway
North Sea electrification policies reshape tieback infrastructure planning. Equinor's Johan Sverdrup development validates thermoplastic barrier technology for carbon-efficient production. The Norwegian Petroleum Directorate enforces pipeline safety regulations under the Petroleum Activities Act.
China
Strategic petroleum reserve filling sustains long-haul trunkline utilization. MIIT and NEA coordinate pipeline routing approvals under national energy security frameworks. The Xinjiang-to-eastern-coast corridor exemplifies state-directed infrastructure prioritization.
Oil Pipeline Infrastructure Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory navigation capabilities. The market structure concentrates around integrated midstream operators with contiguous asset footprints spanning gathering, transmission, and terminal functions. Three archetypes dominate: scale-driven trunkline operators, basin-specialized gatherers, and export-terminal-anchored logistics integrators. Consolidation pressure favors contiguous bolt-on acquisitions over greenfield development, while tariff recontracting cycles create windows for competitive repositioning.
Within the North American integrated tier, Enbridge Inc., Kinder Morgan Inc., and Energy Transfer LP exemplify distinct strategic postures. Enbridge occupies a position emphasizing cross-border corridor control. Kinder Morgan anchors large-scale expansion execution capabilities. Energy Transfer represents terminal-centric export logistics integration. These three structures illustrate how geographic footprint specialization, capital structure discipline, and regulatory relationship depth combine to define competitive position in an asset-heavy, permit-constrained environment.
| Leading Market Players |
|---|
| Enbridge Inc. |
| Kinder Morgan Inc. |
| Energy Transfer LP |
| TC Energy Corp. |
| Pembina Pipeline Corp. |
| Enterprise Products Partners L.P. |
| Williams Companies Inc. |
| ONEOK Inc. |
| Plains All American Pipeline, L.P. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with take-or-pay provisions lock in both API 5L X80 plate access and tariff visibility for Gulf Coast trunkline developers, insulating EPC contractors from alloy surcharge volatility while committing shippers to minimum volume guarantees regardless of throughput fluctuations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across API certification grade, volume commitment scale, and cathodic protection bundling. Cost compression in standard-grade trunkline segments is intensifying because South Korean mill concentration limits supplier competition. Independent Permian Basin operators exhibit the sharpest price sensitivity, while integrated majors with captive throughput demonstrate inelastic demand for premium X100 specifications.
Supply Chain Analysis
South Korea and Japan anchor API 5L X80 and X100 plate production, with Chinese thermoplastic composite manufacturers feeding subsea flexible pipe demand. High-strength steel draws from nickel-molybdenum alloy feedstock, while thermoplastic barriers rest on specialized polymer resin supply. Single-source vulnerability concentrates in South Korean mill capacity for pressure-rated plate. Distribution runs through mill-direct contracts to EPC fabricators, with limited spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pipeline infrastructure is approaching a platform-economics inflection as digital twin interoperability standards enable third-party capacity optimization services atop incumbent SCADA systems, transforming proprietary networks into shared logistics platforms.
For Market Incumbents: Consolidate contiguous gathering footprints in the Permian Basin to defend against independent midstream entrants with lower cost of capital. Acquire API 1104-certified welding contractors to circumvent eighteen-month inspector certification backlogs. Prioritize cathodic protection retrofit programs before PHMSA enforcement windows tighten further. For New Entrants and Emerging Players: Digital twin integration services represent a service-layer gap where incumbents under-serve, particularly for dynamic capacity optimization without physical expansion. Target independent Permian producers lacking in-house integrity management capabilities. Deploy fiber-optic sensing partnerships as the go-to-market angle, bypassing heavy steel-infrastructure capital requirements. For Investors and Strategic Acquirers: Capital is best deployed toward basin-specialized gatherers with contiguous acreage positions and regulatory permit depth rather than greenfield trunkline development. Long-term viability hinges on hydrogen blending retrofit optionality and CO2 transport repurposing potential. Watch for FERC certificate approval velocity as the inflection indicator for permitting risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| API 5L X100 Grade Transition | Higher-strength specifications reduce material intensity for long-haul Permian-Gulf Coast corridors. |
| Smart Pigging Technology Deployment | Axial magnetic flux leakage sensors from vendors like NDT Global compress crack-detection thresholds below two millimeters. |
| Hydrogen Backbone Retrofit | Dutch and German national strategies validate repurposing existing crude lines for hydrogen service. |
| Digital Twin Platform Integration | Real-time SCADA layering enables dynamic capacity optimization without physical loop expansions. |
| CO2 Transport Repurposing | Decommissioned Texas and Louisiana gathering systems offer ready conduit for carbon capture projects. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with midstream planning officers, EPC procurement leads, PHMSA compliance directors, and terminal logistics managers; and secondary validation through FERC filings, EIA pipeline throughput databases, PHMSA incident reports, and API standards documentation. Bottom-up project-level aggregation triangulated against top-down regional capacity assessments.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, installation environment, pressure rating tier, and end-user concentration. CAGRs were derived from throughput elasticity modeling against Permian Basin production forecasts and refinery feedstock demand curves. Forecast inputs incorporated PHMSA integrity mandate compliance cost trajectories and alloy surcharge volatility indices.
Underlying assumptions cover regulatory enforcement continuity, steel mill capacity expansion schedules, and carbon border adjustment implementation timelines, with deviation risk concentrated in electrification policy acceleration and stranded asset repricing. Recalibration cycles align with material shifts in FERC certificate issuance velocity and API specification revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
High Temperature Overhead Conductor Market