
 Iraq Power EPC Market | 2026-2036
Iraq Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Power EPC Market Foresight
Long-term operations and maintenance contracts is recalibrating how power assets transfer from construction to revenue service in Iraq. General Electric Company leverages its existing turbine installed base to secure aftermarket service agreements. Siemens AG anchors its regional presence through localized repair capabilities and training centers. MAPNA Group competes on cost-engineered solutions tailored to Iraq's fuel availability constraints.
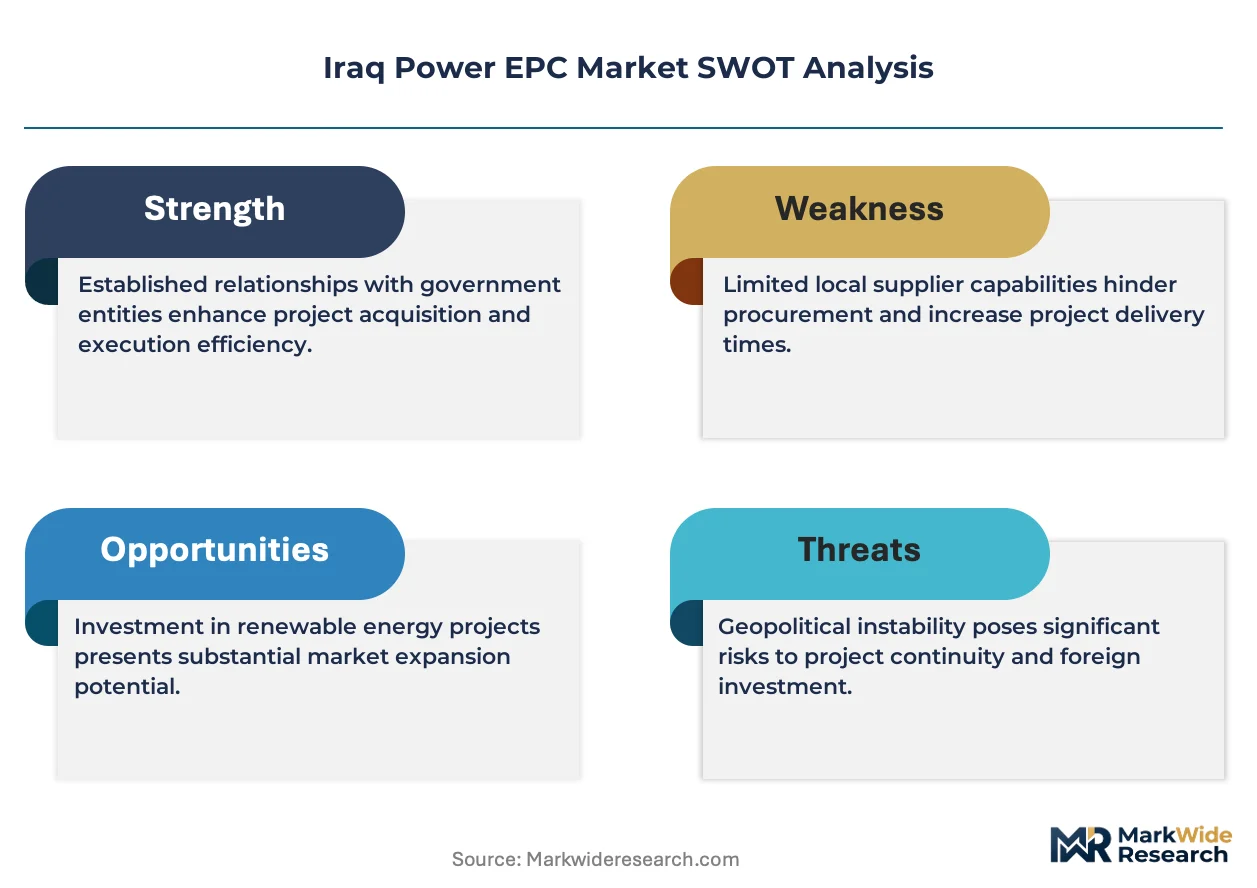
Iraq Power EPC encompasses the integrated design, sourcing, and build-out of electricity generation and transmission infrastructure, typically involving gas turbine installations rated from 100 MW to over 1,500 MW alongside substation and grid interconnection works. The primary purpose is delivering turnkey capacity that connects to the national grid under fixed-price, schedule-bound contracts. Engineering and procurement services command premium margins due to specialized technical staffing shortages, while mega projects dominate the value pool despite longer award cycles. Renewable energy sources represent the fastest-growing segment as Iraq diversifies beyond gas-dependent generation.
Iraq's Ministry of Electricity sets capacity targets and tariff frameworks that determine project bankability, while the country's national standards body enforces equipment certification requirements for grid-connected assets. International lenders apply World Bank and IFC environmental and social safeguard standards that shape contractor eligibility and technology selection. Stakeholders must monitor how fuel subsidy reforms and independent power producer framework negotiations reshape contract structures and risk allocation.
Market Dynamics
Iraq's chronic generation shortfall and Ministry of Electricity rehabilitation mandates are compressing project timelines and forcing contractors toward faster-deploying modular solutions. The structural pressure to reduce outages in Baghdad and Basra load centers is overriding traditional procurement cycles.
Growth Catalysts
- Ministry of Electricity rehabilitation programs:Baghdad's directive to modernize aging gas turbine fleets creates immediate demand for turnkey EPC contracts. Procurement officers prioritize fixed-price agreements that transfer completion risk to contractors.
- Industrial load center expansion:Basra province petrochemical complexes and steel mills require baseload capacity additions. These facilities demand 24/7 reliability that grid-connected captive power solutions provide.
- Dual-fuel turbine flexibility:Technology enabling rapid fuel switching between natural gas and liquid fuels addresses Iraq's gas supply intermittency. Contractors specify these units to meet dispatch requirements during pipeline disruptions.
Market Restraints
- Specialized welding and turbine technician scarcity:Iraq's technical training infrastructure produces insufficient certified craft labor for precision rotating equipment installation. Contractors import skilled crews from Turkey and India, inflating project overhead.
- Equipment certification bottlenecks:The country's national standards body enforces prolonged testing protocols for grid-synchronization hardware. Foreign manufacturers face 6-12 month approval cycles that delay project mobilization.
- Import dependency for high-grade steel and switchgear:Domestic metal fabrication capacity cannot produce pressure-rated boiler components or 400kV GIS enclosures. Supply concentrates in Chinese and South Korean mills exposed to shipping rate volatility.
Strategic Opportunities
- Karbala and Najaf province industrial zones:Religious tourism infrastructure and emerging manufacturing clusters in central Iraq remain underserved by reliable grid supply. Early-mover contractors can anchor regional maintenance depots.
- Solar-gas hybrid integration:Photovoltaic arrays paired with existing thermal assets reduce fuel consumption during peak irradiance hours. This configuration aligns with Ministry directives to diversify beyond gas-dependent generation.
- Performance-linked O&M contracting:Long-term service agreements tied to availability guarantees replace traditional time-and-materials models. Baghdad utilities increasingly prefer outcome-based risk transfer for post-construction asset management.
Industry Challenges
- Security clearance and site access protocols:Contractor personnel movement through Anbar and Saladin provinces requires coordination with multiple military and tribal authorities. These procedures inject unpredictable delays into logistics scheduling.
- Legacy SCADA integration complexity:New substation automation systems must interface with decades-old control architectures deployed by the Ministry of Electricity. Protocol translation and cybersecurity hardening extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Power EPC Market |
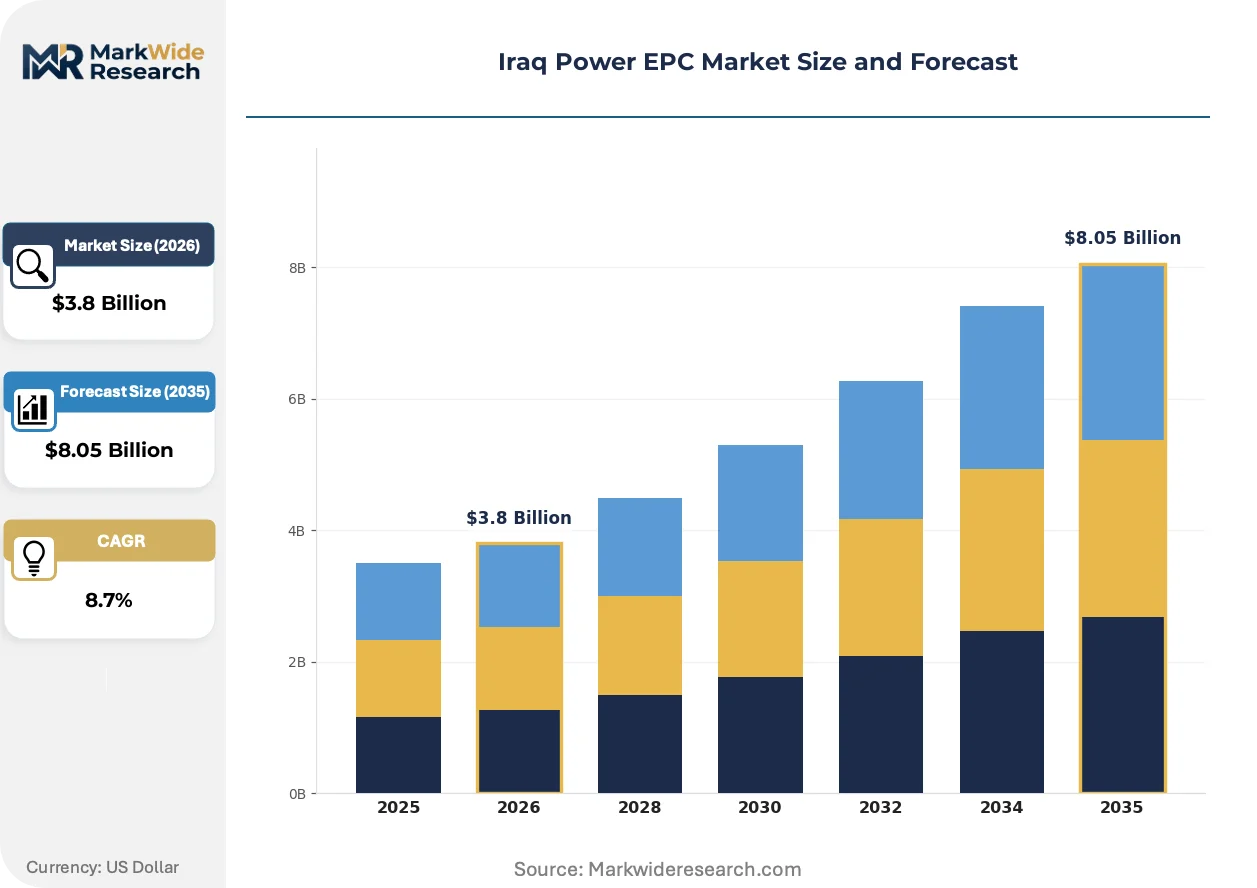
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management Energy Source: Renewable, Natural Gas, Coal, Nuclear End User: Utilities, Industrial Sector, Government, Commercial Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | General Electric Company, Mytilineos S.A, North Power Company Ltd, MAPNA Group, Power Generation Engineering and Service Company, Shamara Holding Group, Siemens AG, Hyundai Engineering & Construction Co., Ltd., Unitech EPC Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Power EPC Market Shifts & Advancements
Technology convergence and procurement model evolution are reconfiguring how power infrastructure delivers value in Iraq. Contractors now compete on operational outcomes rather than construction milestones alone.
Mobile gas turbine power plants mounted on skids or barges are electrifying rapid-deployment strategies for emergency capacity additions. Baghdad utilities facing summer peak deficits adopt these units to bypass multi-year civil works timelines. The technology compresses traditional EPC schedules from 36 months to under 12, enabling contractors to capture premium pricing for speed-to-reliability.
Iraq's Ministry of Electricity tariff framework revisions are mandating cost-reflective pricing mechanisms that improve project bankability. Independent power producer negotiations now incorporate indexed fuel clauses and dollar-denominated offtake agreements. Domestic utilities and international lenders align on World Bank safeguard standards that shape environmental compliance and resettlement protocols for greenfield sites.
After-sales service unbundling is separating long-term maintenance from initial construction contracts. Basra industrial buyers increasingly source turbines from one contractor and O&M from specialized service providers with localized repair capabilities. This disaggregation pressures traditional EPC firms to defend margin through captive parts logistics rather than bundled pricing.
Iraq Power EPC Market Segmentation
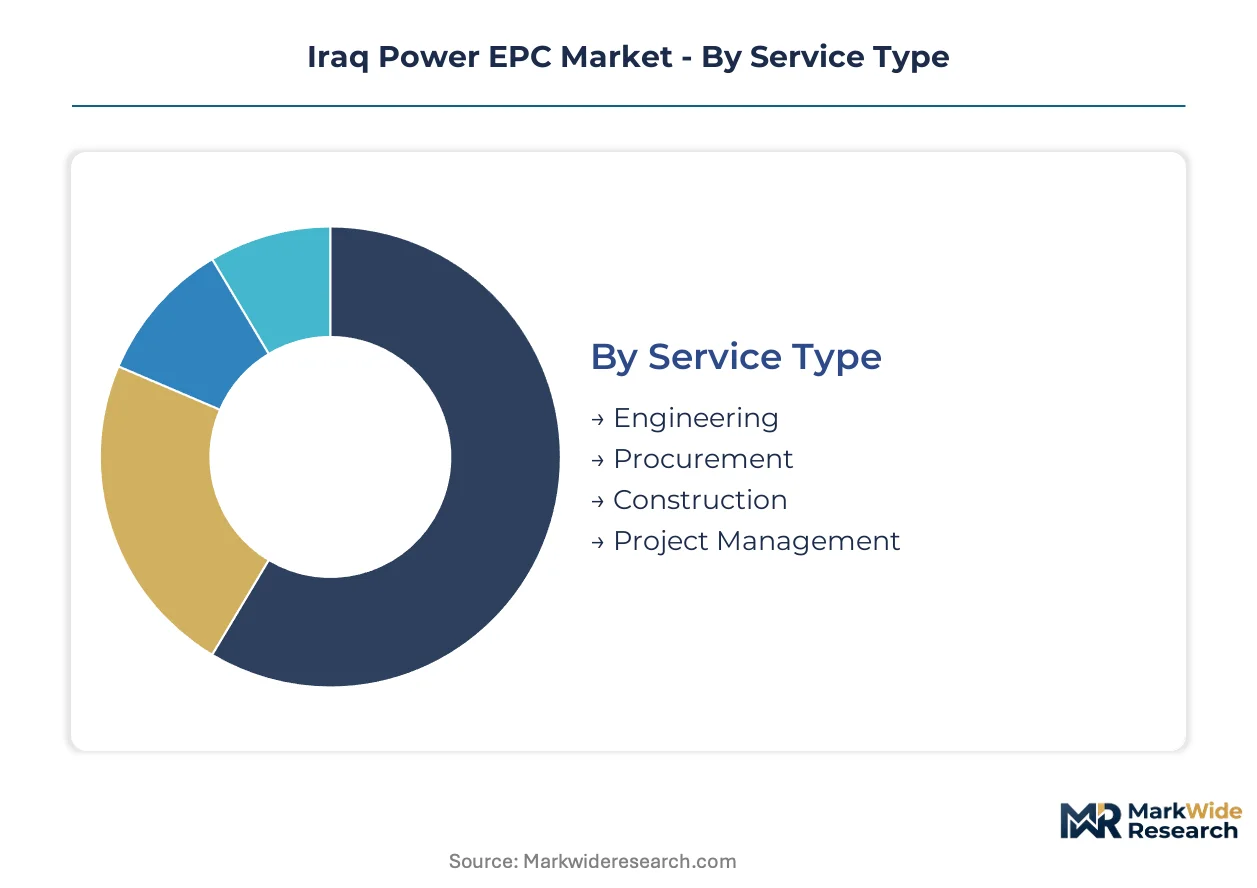
Segmentation in Iraq Power EPC reveals how contract structures, fuel choices, and client risk appetites fragment procurement strategies. Baghdad's Ministry of Electricity applies divergent certification requirements across service types and energy sources, reshaping contractor eligibility and technology selection.
Service Type:
Equipment certification from Iraq's national standards body applies unevenly across service categories, with grid-synchronization hardware facing 6-12 month approval cycles while project management consultancies operate under lighter oversight.
- Engineering:Front-end design and technical specification services command premium margins due to specialized staffing shortages in turbine thermodynamics and grid stability modeling. Baghdad utilities concentrate demand here for complex baseload additions where design errors carry catastrophic completion risk.
- Procurement:Sourcing and vendor qualification activities concentrate high-value equipment from Chinese and South Korean mills for pressure-rated components. Basra industrial buyers prioritize procurement contractors with established customs clearance protocols and security coordination capabilities for Anbar province transit.
- Construction:Field installation and civil works face acute certified welder scarcity, forcing contractors to import Turkish and Indian craft crews.
- Project Management:Schedule and cost oversight services see rising demand as fixed-price contracts transfer completion risk to EPC consortia.
Leading the category by volume: Engineering. Growing fastest: Project Management.
Energy Source:
Cost tiers separate segments sharply, with nuclear carrying capital multiples above gas turbine baselines and solar-gas hybrids occupying a mid-tier position optimized for fuel subsidy exposure.
- Renewable:Photovoltaic and wind installations align with Ministry directives to diversify beyond gas-dependent generation. Karbala and Najaf province industrial zones drive concentrated demand for solar-gas hybrid configurations that reduce fuel consumption during peak irradiance.
- Natural Gas:Gas turbine installations rated 100 MW to 1,500 MW constitute the established revenue base, though supply intermittency forces dual-fuel flexibility specifications. Basra petrochemical complexes require 24/7 reliability that grid-connected gas capacity provides.
- Coal:Solid fuel plants face environmental compliance hurdles under World Bank safeguard standards applied by international lenders.
- Nuclear:Baseload atomic generation remains pre-commercial in Iraq, with no active procurement pipeline.
Dominating contract value: Natural Gas. Expanding most quickly: Renewable.
End User:
Customer type determines risk allocation structures, with utilities preferring turnkey completion guarantees while industrial buyers unbundle construction from long-term O&M.
- Utilities:Baghdad and Basra province grid operators drive mega-project demand under Ministry of Electricity rehabilitation mandates. These clients prioritize fixed-price agreements that transfer completion risk and require contractors to navigate equipment certification bottlenecks.
- Industrial Sector:Petrochemical complexes and steel mills in Basra require captive baseload solutions with 24/7 availability guarantees. Performance-linked O&M contracting is displacing time-and-materials models among these buyers.
- Government:Ministry of Electricity procurement officers set capacity targets and tariff frameworks that determine project bankability.
- Commercial:Religious tourism infrastructure in Karbala and Najaf provinces generates emerging demand for reliable distributed generation.
Commanding the largest contract flow: Utilities. Gaining share fastest: Industrial Sector.
Project Size:
Supply concentration intensifies at scale, with mega projects demanding consortia structures that combine international turbine suppliers with regional civil contractors.
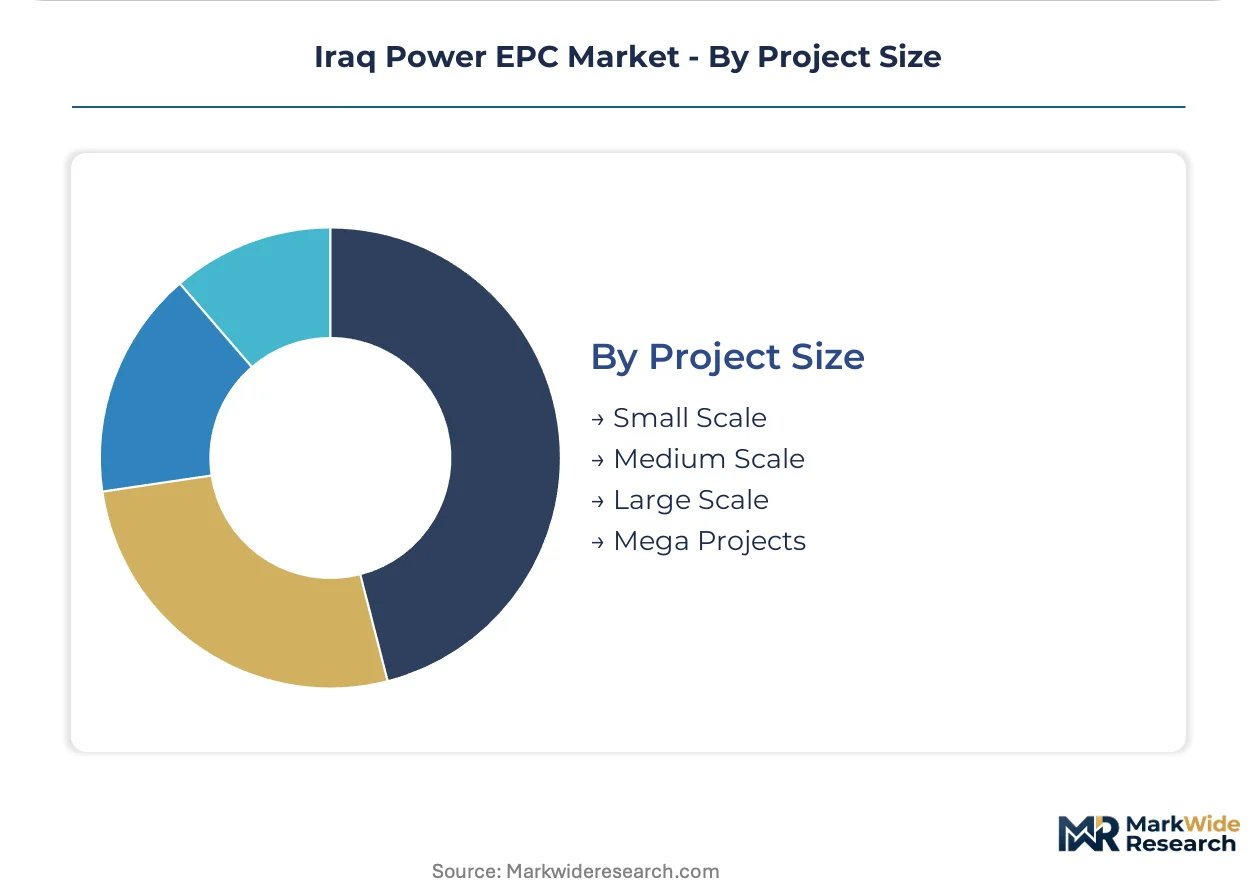
- Small Scale:Mobile gas turbine units mounted on skids or barges compress deployment timelines from 36 months to under 12 for emergency capacity additions. Baghdad utilities facing summer peak deficits adopt these for rapid electrification.
- Medium Scale:Modular solutions in the 100-300 MW range balance speed-to-reliability with economies of scale, attracting contractors with localized repair capabilities.
- Large Scale:300-800 MW installations dominate the value pool despite longer award cycles and complex SCADA integration with legacy Ministry control architectures.
- Mega Projects:Installations exceeding 800 MW require multi-year mobilization and coordination with multiple military and tribal authorities for site access through Anbar and Saladin provinces.
Highest revenue concentration: Mega Projects. Steepest expansion trajectory: Small Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iraq's generation capacity lags peak demand by approximately ten gigawatts, forcing reliance on imports from Iran and Turkey while domestic construction struggles with fuel supply intermittency and security constraints across transmission corridors.
Baghdad Governorate
Chronic summer outages exceeding sixteen hours daily drive Ministry of Electricity procurement toward mobile gas turbine solutions. The national standards body enforces six-to-twelve month certification cycles for grid-synchronization hardware. Sadr City and Karrada industrial zones absorb emergency capacity additions through barge-mounted units that bypass civil works timelines.
Basra Governorate
Petrochemical complexes and steel mills demand twenty-four-seven baseload reliability that grid-connected captive power provides. World Bank environmental safeguard standards applied by international lenders shape contractor eligibility for large-scale installations. The Umm Qasr port corridor concentrates equipment staging and customs clearance activities for southern Iraq projects.
Karbala and Najaf Governorates
Religious tourism infrastructure and emerging manufacturing clusters remain underserved by reliable grid supply. Ministry directives to diversify beyond gas-dependent generation accelerate solar-gas hybrid procurement for these central provinces. The Najaf Industrial City anchors regional demand for distributed generation with performance-linked O&M contracting.
Anbar and Saladin Governorates
Security clearance protocols and tribal coordination requirements inject unpredictable delays into logistics scheduling across these western corridors. Military authorities control site access for transmission line routes connecting Baghdad to Jordan and Syria. The Haditha thermal station rehabilitation exemplifies how contractor personnel movement constraints reshape project mobilization strategies.
Kurdistan Region
Erbil and Sulaymaniyah utilities operate semi-independently from Baghdad's procurement frameworks, attracting distinct contractor consortia. Localized repair capabilities and training centers anchor regional service provider presence. The Khor Mor gas field expansion supports captive power solutions for cement and steel production in the Dukan industrial zone.
Iraq Power EPC Market Competitive Landscape
Top-tier vendors anchor turnkey mega-project execution, while mid-tier specialists compete on modular speed-to-reliability and localized maintenance capabilities. The vendor base stratifies across three archetypes: integrated turbine-OEMs with captive service networks, regional EPC consortia combining international equipment with local civil contractors, and niche mobile power providers deploying skid-mounted emergency units. Competitive positioning hardens through performance-linked long-term service agreements and strategic partnerships with Baghdad utilities for rehabilitation program access.
Within the integrated OEM tier, General Electric Company and Siemens AG occupy positions defined by installed base leverage and aftermarket service anchoring. MAPNA Group exemplifies the regional specialist archetype with cost-engineered solutions calibrated to Iraqi fuel constraints. Hyundai Engineering & Construction Co., Ltd. represents the Korean EPC consortium model that pairs equipment sourcing with construction management capabilities across Middle Eastern power infrastructure.
| Leading Market Players |
|---|
| General Electric Company |
| Mytilineos S.A |
| North Power Company Ltd |
| MAPNA Group |
| Power Generation Engineering and Service Company |
| Shamara Holding Group |
| Siemens AG |
| Hyundai Engineering & Construction Co., Ltd. |
| Unitech EPC Solutions |
| Others |
Supply & Pricing Matrix
Mobile gas turbine deployment on skids and barges is compressing project timelines from thirty-six months to under twelve, simultaneously collapsing civil works cost structures and concentrating procurement power among contractors with rapid-mobilization capabilities. This production-method transition rewards speed-to-reliability over traditional fixed-asset economics, reshaping how Baghdad utilities evaluate total cost of ownership.
Pricing Analysis
Margin tightening in mega-project EPC contracts reflects Baghdad's Ministry of Electricity preference for fixed-price agreements that transfer completion risk to contractors. Three-tier pricing structure across premium, standard, and economy levels separates turbine-OEM bundled solutions from regional EPC consortia and mobile power providers. Price differentiation hinges on after-sales service bundling and dual-fuel flexibility certification. Basra industrial buyers show lowest price sensitivity due to twenty-four-seven reliability requirements, while utilities prioritize cost-down pressure on standardized units.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean mills for pressure-rated boiler components and 400kV GIS enclosures. High-grade steel, switchgear assemblies, and precision rotating equipment draw from concentrated East Asian fabrication hubs. Supply chain risk centers on shipping rate volatility through the Strait of Hormuz and Umm Qasr port congestion. Distribution runs through EPC contractor-led logistics coordination with customs clearance specialists and tribal security protocols for Anbar province transit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq Power EPC is consolidating around contractors with captive service networks and rapid-deployment capabilities, as chronic generation shortfalls and compressed procurement cycles force out traditional civil-works-dependent players.
For Market Incumbents: Deploy performance-linked O&M contracting to defend margin position against unbundling trends separating construction from long-term service. Anchor regional maintenance depots in Karbala and Najaf provinces to capture emerging industrial zone demand. Counter mobile power provider encroachment through dual-fuel turbine flexibility specifications that address Baghdad's gas supply intermittency. For New Entrants and Emerging Players: Launch via solar-gas hybrid integration models targeting Ministry directives to diversify beyond gas-dependent generation. Prioritize Karbala and Najaf religious tourism infrastructure as the most penetrable segment, where grid undersupply creates captive power opportunities. Establish localized repair capabilities and training centers to compete on outcome-based availability guarantees rather than construction milestones. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional EPC consortia with established customs clearance protocols and security coordination capabilities. Five-to-ten year viability favors contractors with backward integration into turbine parts logistics and captive maintenance networks. Monitor fuel subsidy reform negotiations as the critical inflection signal for project bankability and contract structure evolution.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Gas Turbine Fleet Expansion | Compresses deployment timelines from thirty-six months to under twelve for Baghdad summer peak deficits. |
| Solar-Gas Hybrid Integration | Aligns with Ministry directives to diversify generation while reducing fuel consumption during peak irradiance. |
| Performance-Linked O&M Contracting | Replaces time-and-materials models with outcome-based risk transfer for post-construction asset management. |
| Localized Repair Capability Investment | Establishes regional maintenance depots in underserved Karbala and Najaf industrial zones. |
| Dual-Fuel Flexibility Certification | Addresses Iraq's gas supply intermittency through rapid fuel switching between natural gas and liquid fuels. |
Research Methodology
Ministry of Electricity procurement databases, EIA Middle East power sector reports, and FERC international project filings formed the secondary backbone for market sizing and technology trend identification. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation through bottom-up project pipeline analysis and top-down macroeconomic triangulation. Field perspectives from fuel supply specialists and aftermarket service heads anchored operational reality checks against documented capacity targets.
Historical trendline analysis of awarded EPC contracts across fuel source, generation capacity tier, project scale, and regional grid type established baseline growth patterns. Analytical framework approach modeled volume and value outputs across the projection horizon through segmentation-dimensional regression. CAGRs were derived from installed capacity additions, rehabilitation program timelines, and independent power producer framework negotiation progress. Forecast inputs incorporated Ministry tariff framework revisions and World Bank safeguard standard compliance requirements.
Fuel subsidy reform implementation delays, security clearance protocol disruptions, and equipment certification bottleneck extensions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding Ministry procurement priority shifts and international lender environmental compliance timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Steam Turbine Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Peaking Power Plant Market
Power Generation
Global Black Start Generator Market
Power Generation
Power Plant EPC Market
Power Generation
Microturbine Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Global Turbines Market
Power Generation
Captive Power Plant Market
Power Generation
Global Power Generation Market