
 Indonesia Power Market | 2026-2036
Indonesia Power Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Power Market Outlook
Indonesia is rewriting its generation mix through archipelago-wide capacity build-outs spanning geothermal fields in Sumatra and coal-fired complexes in Java. PT PLN (Persero) anchors the transmission backbone through its monopoly over Perusahaan Listrik Negara infrastructure. Pertamina leverages upstream fuel supply chains to dominate gas-to-power project feedstock. Adaro Energy competes in mine-mouth generation, converting captive coal reserves into baseload electricity.
Indonesia power encompasses the generation, transmission, and distribution of electrical energy across an archipelagic grid characterized by system inertia requirements of 50 Hz and voltage classes from 20 kV distribution to 500 kV extra-high-voltage transmission. The primary purpose is to supply reliable electricity to industrial, commercial, and residential consumers across 17,000 islands. Thermal capacity still dominates installed megawatts, though solar project pipelines accelerate fastest among technology segments as rooftop and utility-scale PV attract independent power producer bids. Small and medium scale distributed systems gain traction in outer islands where grid extension costs exceed localized renewable minigrid economics.
MEMR sets electricity tariff policy and governs power purchase agreements through ministerial regulation, while BSN enforces SNI standards for generation equipment and grid interconnection compliance. The OJK and BI shape project finance availability through infrastructure lending mandates and rupiah stability mechanisms. Stakeholders must monitor RUPTL revision cycles and renewable energy tariff negotiations to anticipate procurement windows.
Market Dynamics
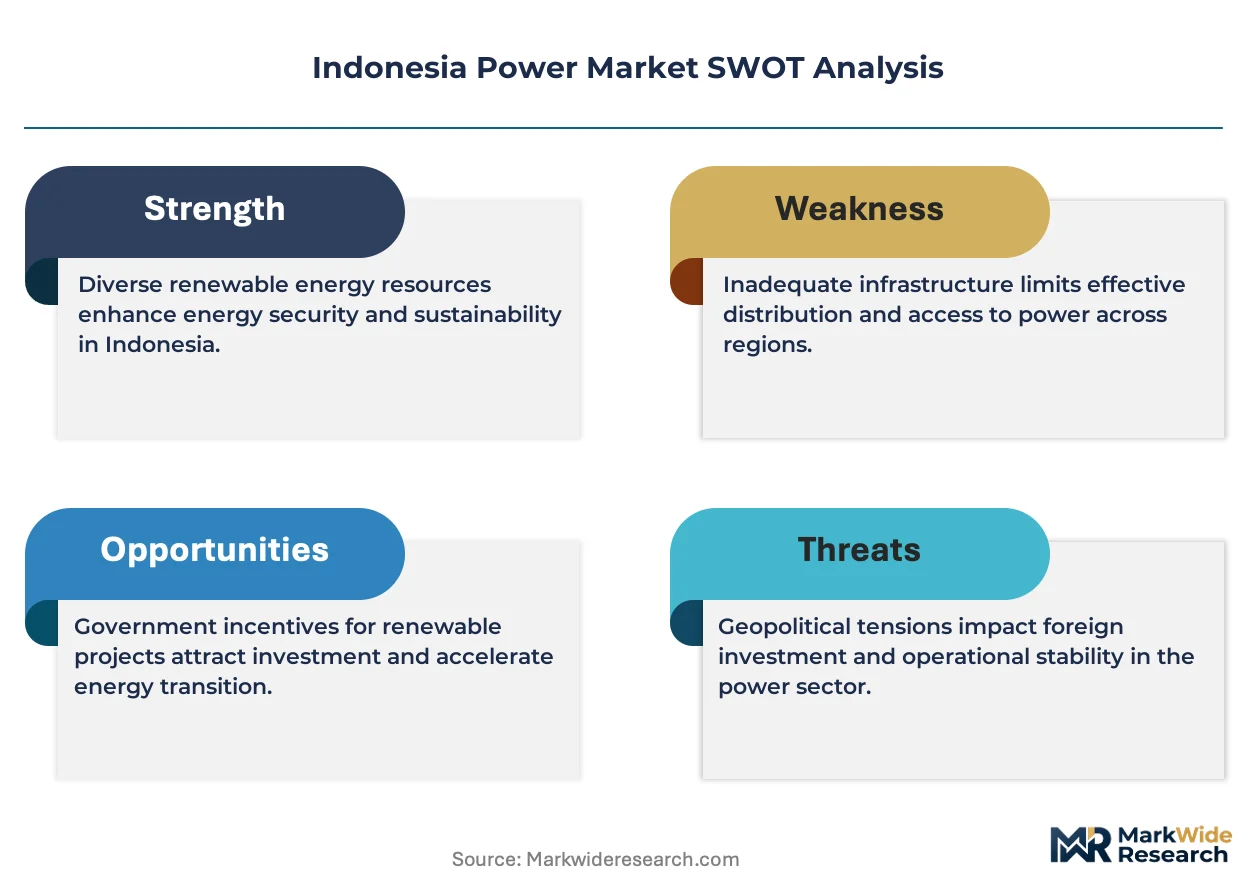
Java-Bali grid saturation is forcing generation investment toward outer island clusters where PLN's RUPTL procurement targets 35 GW of renewable additions through independent power producer auctions.
Growth Catalysts
- MEMR electrification mandates:Village electrification targets accelerate mini-grid deployments across Maluku and Papua where grid extension remains uneconomical.
- Industrial load expansion:Smelter investments in Sulawesi and North Maluku drive captive power demand requiring dedicated generation capacity.
- Geothermal resource commercialization:Sumatra's volcanic belt offers 29 GW of untapped geothermal potential now attracting exploration permits.
Market Restraints
- Domestic coal price volatility:DMO pricing rules cap fuel costs for PLN but create supply uncertainty when export arbitrage widens.
- Transmission bottlenecks:Java-Bali interconnection capacity limits power evacuation from Sumatra geothermal fields.
- Limited gas infrastructure:Pipeline gaps in eastern archipelago regions prevent gas-to-power project economics from clearing hurdle rates.
Strategic Opportunities
- Kalimantan industrial zones:New capital city Nusantara and surrounding smelter corridors require 10 GW of dedicated baseload supply.
- Net metering expansion:MEMR rooftop solar regulations enable commercial and industrial behind-the-meter installations.
- Battery storage pairing:Lithium-ion cost curves allow solar-plus-storage configurations to compete with diesel minigrids in remote islands.
Industry Challenges
- Land acquisition timelines:Perhutanan and agrarian ministry permits for transmission right-of-way extend project schedules by 18-24 months.
- Grid code compliance:SNI interconnection standards for inverter-based resources create certification backlogs for solar developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Power Market |
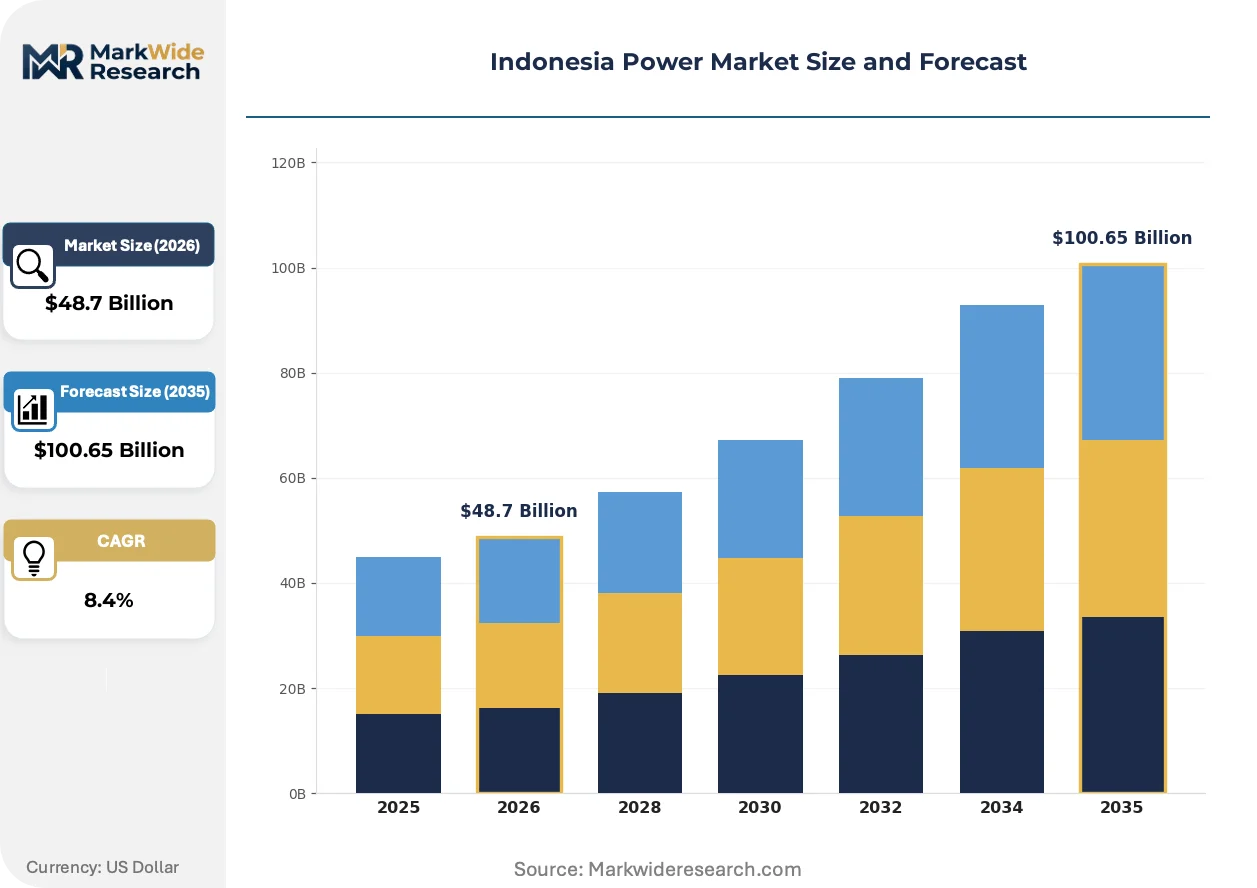
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-Renewable, Thermal, Hydropower Technology: Solar, Wind, Biomass, Coal End User: Residential, Commercial, Industrial, Government Capacity: Small Scale, Medium Scale, Large Scale, Extra Large |
| Companies Covered | PT PLN (Persero), PT Pertamina, Adaro Energy, PT Paiton Energy, Star Energy Geothermal, Cirebon Electric Power, PT Indonesia Power, Medco Power Indonesia, Jawa Satu Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Power Market Strategic Shifts
Digitalization of grid operations and distributed resource integration are compressing traditional utility business models while opening procurement pathways for non-utility generation.
Advanced metering infrastructure is digitizing revenue protection and load forecasting across PLN's distribution network. State-owned utility operators deploy smart meters in Jakarta and Surabaya commercial zones to reduce technical losses. Real-time consumption visibility is digitizing demand response programs that shave peak loads during dry-season capacity constraints.
MEMR ministerial regulation on renewable energy tariffs revises feed-in mechanisms to attract independent power producer equity. The policy replaces cost-plus benchmarks with competitive auction ceilings for solar and wind projects. Developers in Sumatra and Sulawesi are restructuring power purchase agreements to align with these tariff corridors.
Corporate renewable energy procurement is accelerating direct power purchase agreements between load centers and generators. Textile and data center operators in Batang and Cikarang industrial estates negotiate bilateral contracts bypassing PLN retail tariffs. This buyer-driven contracting concentrates in Java where grid access and creditworthy offtakers overlap.
Indonesia Power Market Segmentation
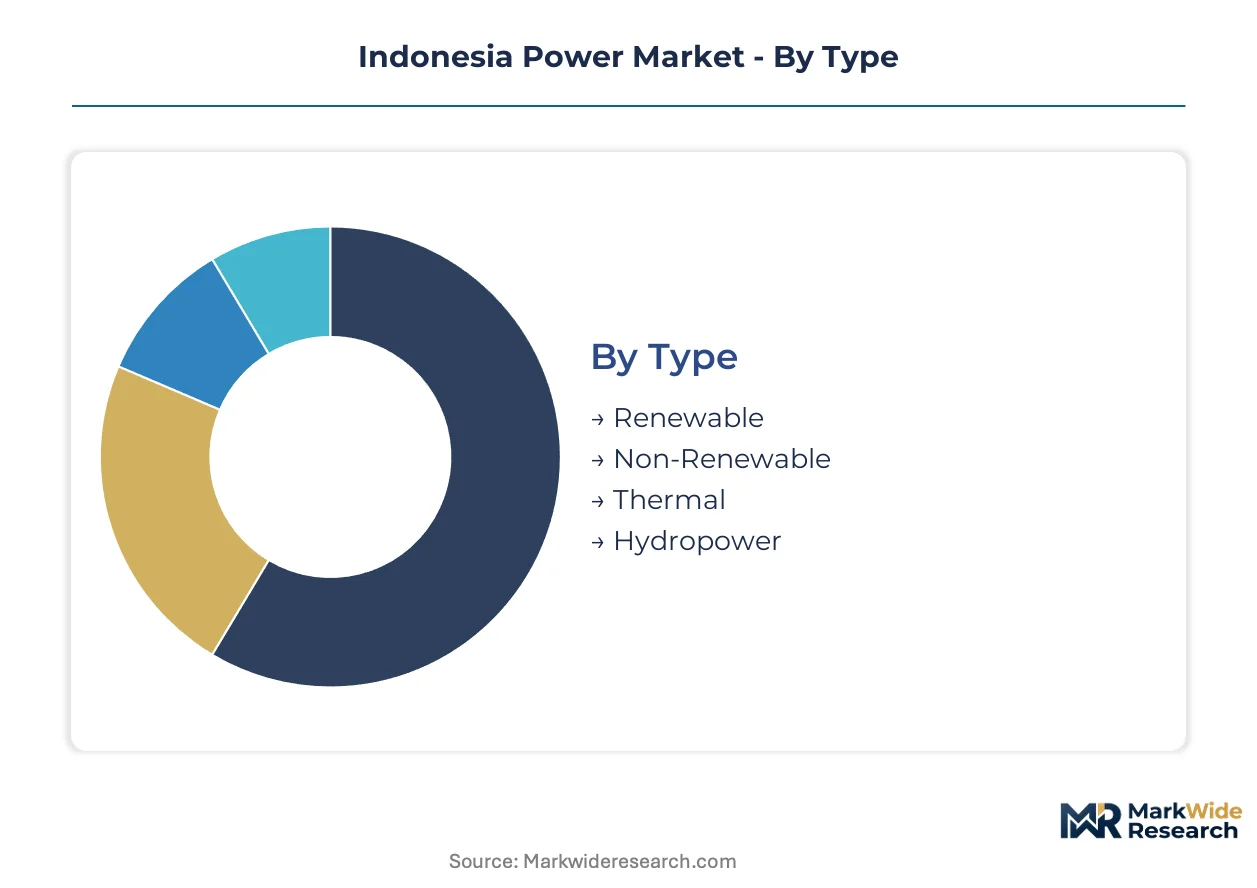
Indonesia's archipelagic geography fragments generation economics across 17,000 islands, making segmentation essential for matching technology choices to fuel availability, grid access, and load density. Each dimension reveals distinct procurement pathways and regulatory interfaces that shape investor returns.
Type:
Mature baseload technologies dominate current megawatt counts, while emerging renewable categories capture policy-driven procurement windows.
- Renewable:Geothermal, solar, wind, and biomass installations qualify for MEMR feed-in tariff mechanisms and PLN RUPTL auction slots. Project pipelines concentrate in Sumatra's volcanic belt and Java-Bali distributed grids where interconnection capacity exists.
- Non-Renewable:Diesel and oil-fired peaking plants serve outer island clusters lacking pipeline gas or grid backbone. High fuel logistics costs limit these to emergency reserve roles despite fast deployment timelines.
- Thermal:Coal and gas-fired complexes anchor Java-Bali baseload supply. Mine-mouth coal units in Kalimantan and Sulawesi leverage captive fuel reserves to compress delivered energy costs below import parity.
- Hydropower:Run-of-river and reservoir schemes in Papua and Sulawesi harness steep terrain gradients. Seasonal flow variability restricts capacity factors during dry months.
Thermal capacity handles the majority of throughput; renewable is the fastest mover on share.
Technology:
Cost tier stratification separates utility-scale dispatchable assets from distributed variable generation.
- Solar:Photovoltaic modules dominate new capacity additions through MEMR competitive auctions and rooftop net metering schemes. Utility-scale projects in West Java and East Nusa Tenggara pair with battery storage to displace diesel minigrids.
- Wind:Onshore turbines in South Sulawesi and Nusa Tenggara face interconnection bottlenecks despite excellent resource profiles. Grid code compliance for inverter-based resources extends commissioning timelines.
- Biomass:Palm oil residue and rice husk combustion serves captive industrial loads in Sumatra and Kalimantan. Feedstock supply contracts with plantation operators determine project bankability.
- Coal:Ultra-supercritical units in Java and Sumatra provide frequency regulation services essential for grid stability. Domestic market obligation pricing rules cap fuel costs but create supply uncertainty during export arbitrage spikes.
Coal handles the majority of throughput; solar is expanding most quickly on share.
End User:
Application intensity varies from price-sensitive residential tariffs to industrial loads seeking behind-the-meter alternatives.
- Residential:Subsidized tariff tiers under PLN's social obligation mandate dominate consumption patterns. Village electrification targets accelerate mini-grid deployments across Maluku and Papua.
- Commercial:Shopping malls, hotels, and office complexes in Jakarta and Surabaya deploy rooftop solar under MEMR net metering regulations to offset retail tariff exposure.
- Industrial:Smelter investments in Sulawesi and North Maluku drive captive power demand requiring dedicated generation capacity. Nickel processing loads seek direct power purchase agreements bypassing PLN retail.
- Government:Public buildings and street lighting fall under regional budget procurement. Nusantara new capital construction creates concentrated demand for reliable baseload supply.
Industrial offtake handles the majority of throughput; commercial is climbing the fastest on share.
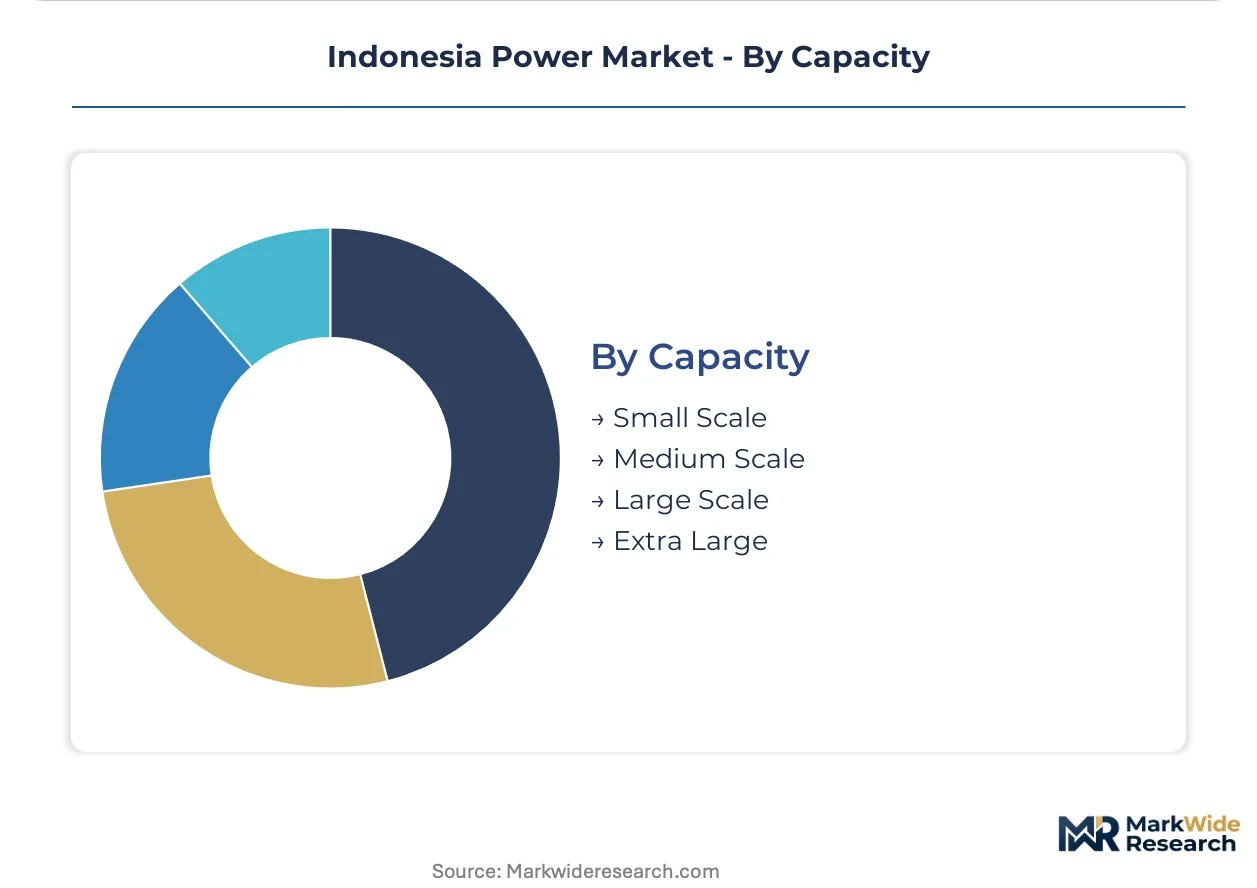
Capacity:
Volume thresholds determine regulatory jurisdiction, financing structures, and grid interconnection voltage classes.
- Small Scale:Sub-1 MW diesel generators and solar home systems serve unelectrified villages beyond PLN grid extension economics. Productive use appliances drive load growth in outer island communities.
- Medium Scale:1-50 MW biomass and small hydro projects qualify for simplified licensing under MEMR regulation. Industrial estates in Batang and Cikarang host captive gas engines.
- Large Scale:50-250 MW geothermal and combined-cycle gas units anchor regional grids. PLN power purchase agreements provide offtake certainty through 25-30 year tenors.
- Extra Large:Above-250 MW coal and hydro complexes require presidential regulation and international project finance. Java-Bali interconnection upgrades precede remote resource evacuation.
Large scale projects handle the majority of throughput; small scale is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generation capacity concentrates in Java where PLN's transmission backbone anchors national supply, while investment pipelines shift toward outer island clusters as grid saturation limits new interconnection slots. The archipelago's fragmented geography fragments economics across 17,000 islands, making sub-regional analysis essential for matching technology choices to load density and fuel access.
Java-Bali Grid
Industrial smelter corridors in Cikarang and Batang drive baseload demand requiring dedicated coal and gas-fired capacity. MEMR's electricity tariff policy governs power purchase agreements through ministerial regulation, capping retail exposure for energy-intensive manufacturers. Jakarta and Surabaya commercial zones absorb the majority of distributed generation additions as rooftop solar accelerates behind-the-meter installations.
Sumatra
Geothermal fields along the volcanic belt offer untapped renewable potential now attracting exploration permits from independent power producers. PLN's RUPTL procurement targets capacity additions through competitive auctions, though transmission bottlenecks limit power evacuation to Java-Bali load centers. Medan and Palembang industrial estates anchor regional demand for captive gas-to-power projects.
Sulawesi
Nickel processing investments in Morowali and Konawe drive captive power demand requiring dedicated generation capacity outside PLN's retail structure. MEMR electrification mandates accelerate mini-grid deployments in Central Sulawesi villages where grid extension remains uneconomical. Makassar port infrastructure shapes fuel logistics for diesel peaking plants serving outer island clusters.
Kalimantan
Nusantara new capital construction creates concentrated demand for reliable baseload supply across 10 GW of planned dedicated capacity. Mine-mouth coal units leverage captive fuel reserves to compress delivered energy costs below import parity for smelter corridors. BSN enforces SNI standards for generation equipment compliance as infrastructure build-outs accelerate.
Papua and Maluku
Village electrification targets accelerate solar-diesel hybrid mini-grid deployments across archipelagic regions lacking pipeline gas or transmission backbone. Battery storage pairing allows solar-plus-storage configurations to displace diesel generation as lithium-ion cost curves improve. Jayapura and Ambon anchor regional load centers where localized renewable economics exceed grid extension costs.
Indonesia Power Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying generation equipment and fuel feedstock. The market structures around state-owned utility dominance with independent power producers competing for RUPTL auction slots. Three archetypes prevail: vertically integrated fuel-to-power conglomerates, renewable-focused independent developers, and state-backed transmission monopolists. Competitive moves concentrate on strategic partnerships for project development and portfolio diversification across technology segments.
Among state-owned platform operators, PT PLN (Persero) and PT Indonesia Power occupy positions anchoring transmission and generation infrastructure. Independent developers including Star Energy Geothermal and Medco Power Indonesia exemplify the renewable-focused archetype competing for exploration permits and offtake contracts. Fuel-integrated conglomerates such as PT Pertamina and Adaro Energy represent backward integration into power generation from upstream supply chains.
| Leading Market Players |
|---|
| PT PLN (Persero) |
| PT Pertamina |
| Adaro Energy |
| PT Paiton Energy |
| Star Energy Geothermal |
| Cirebon Electric Power |
| PT Indonesia Power |
| Medco Power Indonesia |
| Jawa Satu Power |
| Others |
Value Chain & Pricing Dynamics
Kalimantan's mine-mouth coal clusters concentrate fuel supply leverage that cascades through PLN's tariff negotiations and independent power producer bidding corridors. This geographic supply anchor shapes how generation costs transmit into regulated electricity tariffs across Java-Bali industrial load centers.
Pricing Analysis
MEMR ministerial regulation dictates the pricing tier structure through cost-plus benchmarks for legacy power purchase agreements and competitive auction ceilings for renewable procurement. Three-tier pricing separates baseload coal contracts from mid-tier gas-to-power arrangements and emerging solar-plus-storage bids. Price differentiation hinges on fuel cost pass-through mechanisms and interconnection voltage class. Cost compression in renewable auctions intensifies as lithium-ion pairing improves project economics. Industrial offtakers in smelter corridors exhibit lowest price sensitivity due to captive power alternatives, while subsidized residential tiers face strict tariff caps.
Supply Chain Analysis
Extended payment terms from state-owned offtakers strain developer working capital, driving supply-chain finance facilities through infrastructure lending mandates. Equipment sourcing concentrates in China, South Korea, and Japan for turbines, switchgear, and photovoltaic modules. Project development draws from domestic civil construction capacity, imported generation equipment, and captive coal reserves. Single-source vulnerability runs through critical mineral processing for battery storage components. Distribution runs through PLN's monopoly transmission backbone with last-mile extension to outer island clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized geothermal drilling expertise and transmission right-of-way permitting capability represent acute bottlenecks constraining project velocity. Developers who secure these scarce assets capture disproportionate auction allocations.
For Market Incumbents: Insulate generation portfolios from renewable auction price erosion by accelerating geothermal resource commercialization in Sumatra's volcanic belt. Secure long-term coal supply contracts with domestic miners before export arbitrage widens. Deepen backward integration into fuel logistics to defend margin position against independent power producer entrants with direct fuel access. For New Entrants and Emerging Players: Outer island solar-diesel hybrid mini-grids in Maluku and Papua represent the most penetrable entry point where PLN grid extension economics fail. Battery storage pairing with rooftop installations in Surabaya commercial zones offers secondary white-space. Pursue direct corporate power purchase agreements with nickel smelter operators in Sulawesi bypassing PLN retail tariffs entirely. For Investors and Strategic Acquirers: Long-term, this sits as a regulated utility infrastructure play because MEMR electrification mandates guarantee offtake volume through presidential regulation-backed procurement. Target developers holding exploration permits in untapped geothermal fields with proven resource estimates. Watch RUPTL revision cycles for early signals of auction window acceleration or tariff ceiling adjustments.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Exploration Permit Acquisition | Secures exclusive resource rights in Sumatra's volcanic belt ahead of competitive auction rounds. |
| Mine-Mouth Coal Integration | Captive fuel reserves compress delivered energy costs below import parity for Kalimantan smelter supply. |
| Solar-Plus-Storage Configuration | Lithium-ion cost curves enable displacement of diesel minigrids across Papua archipelagic clusters. |
| Direct Corporate Power Purchase Agreement | Bilateral contracts with Batang textile operators bypass PLN retail tariff exposure. |
| Transmission Right-of-Way Pre-Positioning | Perhutanan permits secured 18-24 months ahead compress project schedules for Java-Bali interconnection. |
Study Parameters
A standing panel of utility planning officers, independent power producer project developers, EPC contractors, and grid operators provided ongoing calibration across primary interviews and secondary validation. PLN RUPTL procurement databases, MEMR ministerial regulations, IEA Southeast Asia energy outlooks, and project finance disclosure records anchored quantitative baselines. Bottom-up project pipeline aggregation triangulated against top-down electrification demand forecasts.
Scenario-bracketing framed low, base, and high cases across the projection horizon without prescribing fixed year markers. Segmentation dimensions modeled encompass fuel source, generation capacity tier, end-use intensity, and regional grid interconnection status. CAGRs derived from installed capacity build-out trajectories and tariff-adjusted revenue per megawatt-hour. Forecast inputs incorporated geothermal resource temperature gradients and domestic coal price volatility bands.
Practitioners should monitor RUPTL revision cycles, renewable energy tariff renegotiations, and presidential regulation shifts for early signals of procurement window timing. Forecasts reflect documented assumptions on electrification penetration rates and industrial load growth. Macroeconomic rupiah instability, MEMR policy discontinuity, or transmission bottleneck resolution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Myanmar Power Generation EPC Market
Power Generation
LAMEA Microturbine Market
Power Generation
Residential Solar Generator Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Gas Gensets Market
Power Generation
Captive Power Generation Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Microturbine Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Variable Speed Generator Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
South East Asia Power Market
Power Generation
Ocean Thermal Energy Conversion Plant Market