
 Myanmar Power Generation EPC Market | 2026-2036
Myanmar Power Generation EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Power Generation EPC Market Foresight
Industrial manufacturing electrification is expanding faster than commercial build-outs across Myanmar's power generation EPC landscape. Mitsubishi Heavy Industries Group leverages its gas turbine technology leadership to anchor large-scale combined-cycle projects near Thilawa Special Economic Zone. TTCL Public Company Limited competes through its regional procurement networks and Thai-Myanmar cross-border engineering capabilities.
Myanmar Power Generation EPC encompasses the full-scope engineering, procurement, and construction of electricity generation facilities, typically involving turbine-generator sets rated from 10 MW to over 500 MW, civil works for dam or plant infrastructure, and grid interconnection switchyards. Hydropower dominates installed EPC backlog due to Myanmar's river basin geography, while solar is gaining fastest traction as module costs decline and irradiation data improves. Mega Projects command disproportionate margin pools given sovereign-backed financing and extended commissioning timelines.
Myanmar's Ministry of Electricity and Energy and the country's national environmental regulator shape project approval timelines, with hydropower EPC contracts facing intensified environmental impact assessment requirements. The Electric Power Generation Enterprise enforces grid code compliance that determines generator technical specifications and interconnection standards. Stakeholders must monitor whether foreign contractor licensing rules tighten and how domestic content requirements evolve for future tender rounds.
Market Dynamics
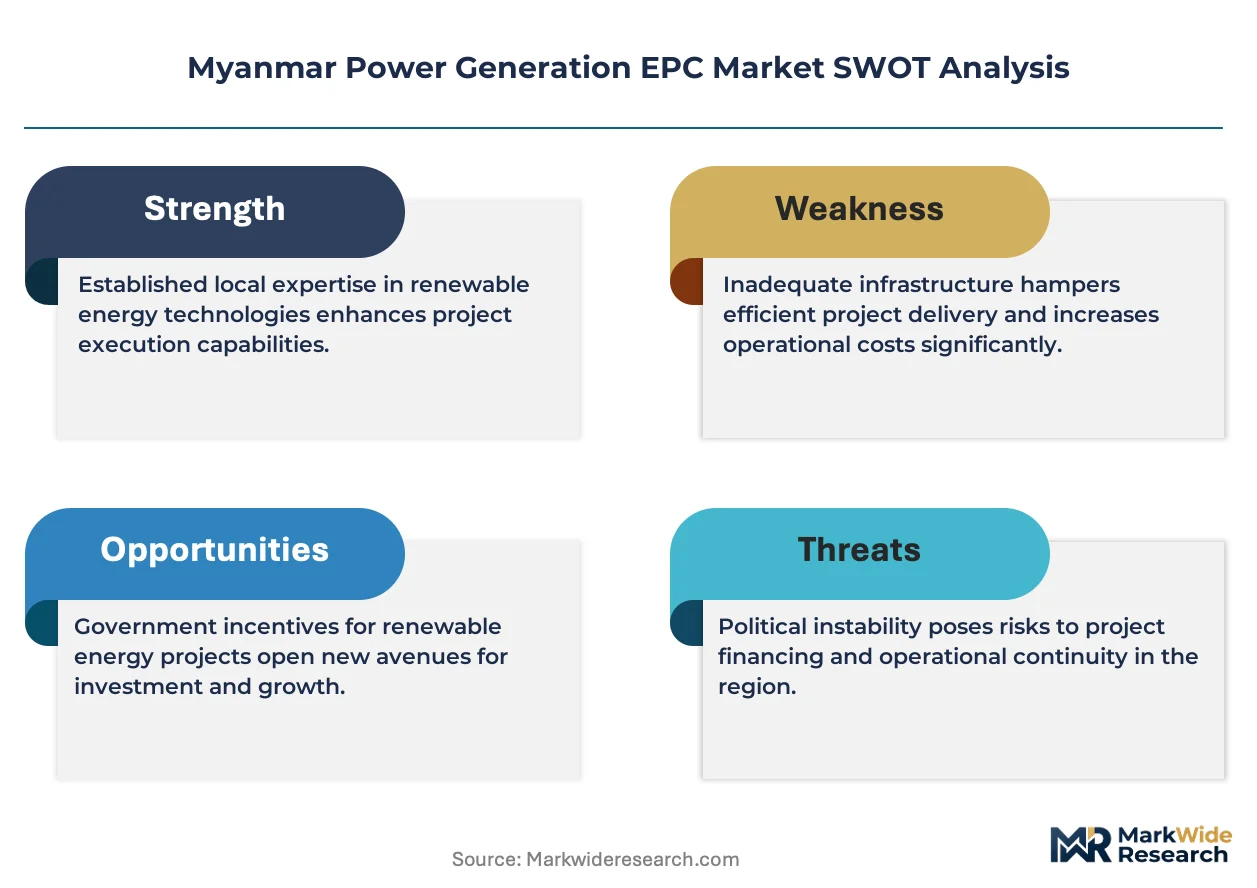
Myanmar's power generation EPC sector faces acute pressure from feed-in tariff recalibration and sovereign financing constraints that compress contractor margins while extending project timelines. The Ministry of Electricity and Energy's renewable procurement framework is simultaneously attracting independent power producers and exposing EPC firms to currency volatility on dollar-denominated equipment imports.
Growth Catalysts
- Industrial Electrification Mandates:Manufacturing clusters in Yangon and Mandalay are driving demand for captive power solutions as grid reliability remains inconsistent. Textile and food processing facilities are commissioning gas-fired and solar hybrid systems to ensure production continuity.
- Solar PV Cost Trajectory:Module price declines have repositioned utility-scale solar as the lowest-cost generation option for greenfield EPC contracts. Irradiation mapping across the central dry zone is unlocking bankable project pipelines previously deemed marginal.
- Hydropower Rehabilitation Framework:Aging dam infrastructure built during the 1980s requires comprehensive EPC overhaul to restore nameplate capacity. The Electric Power Generation Enterprise is prioritizing turbine-generator replacements at facilities along the Thanlwin River basin.
Market Restraints
- Import Dependency for Turbine Equipment:Myanmar lacks domestic heavy manufacturing for gas turbine rotors, generator stators, and high-voltage switchgear. Contractors face extended lead times and forex exposure on Korean, Japanese, and Chinese equipment procurement.
- Environmental Assessment Bottlenecks:Hydropower EPC contracts face intensified scrutiny from the country's national environmental regulator. Revised impact assessment protocols are adding 12-18 months to project approval cycles for greenfield dam construction.
- Grid Interconnection Standards:The Electric Power Generation Enterprise enforces technical specifications that often exceed regional ASEAN norms. Generator synchronization and protection system compliance requires specialized engineering not available within Myanmar's domestic labor pool.
Strategic Opportunities
- Ayeyarwady Delta Solar Corridors:Unmet electrification demand across Delta townships presents distributed generation opportunities below the 30 MW threshold requiring sovereign guarantee. Mini-grid and commercial-industrial rooftop segments remain underserved by current EPC capacity.
- Cross-Border Thai Engineering Partnerships:Thai contractors with established Myanmar operations can leverage regional supply chains and Baht-denominated financing to undercut competitors dependent on volatile Kyat-Dollar conversions. Border provinces offer logistics advantages for equipment staging.
- Domestic Content Localization:Evolving local participation requirements for civil works, transmission line construction, and operations staffing create partnership opportunities for foreign EPC firms. Training and technology transfer provisions are becoming tender evaluation criteria.
Industry Challenges
- Commissioning Engineer Scarcity:Myanmar produces insufficient electrical engineers with hands-on turbine-generator commissioning experience. EPC contractors must import Thai, Indian, or Chinese specialists, inflating project overhead and creating visa processing delays.
- Legacy Hydropower Asset Integration:Rehabilitation contracts require interfacing with Soviet-era and Chinese-built control systems lacking documentation. Reverse engineering and custom protocol translation consume unbudgeted engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Power Generation EPC Market |
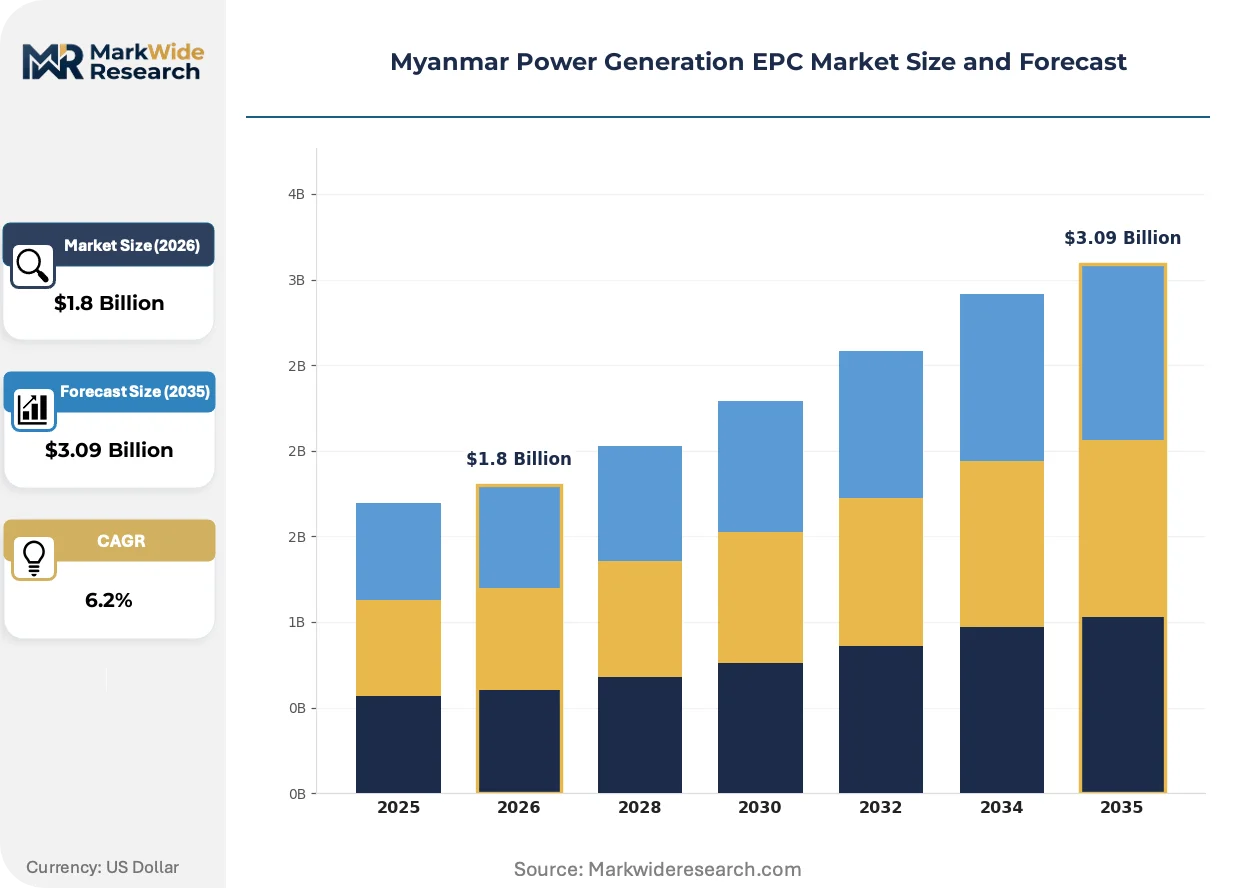
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydropower, Natural Gas, Solar, Wind Service Type: Design, Procurement, Construction, Commissioning End User: Government, Industrial, Commercial, Utilities Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Zeya & Associates Co. Ltd., Hyundai Engineering and Construction Corporation Limited, TTCL Public Company Limited, Mitsubishi Heavy Industries Group, Sumitomo Corporation, Snowy Mountains Engineering Corporation Holdings Limited, Parami Energy Group of Companies, Marubeni Corporation, EAM Myanmar Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Power Generation EPC Market Shifts & Advancements
Digitalization of project delivery and modular construction methods are compressing EPC timelines while improving cost predictability. Contractors are deploying drone-based site surveying and prefabricated substation assemblies to offset skilled labor constraints.
Floating solar photovoltaic technology is expanding into Myanmar's reservoir infrastructure. The technology enables generation on dam impoundments without land acquisition conflicts. State-owned hydropower operators are piloting 10-50 MW floating arrays at existing facilities to diversify revenue streams. The approach is expanding into the EPC contracting scope as a hybrid rehabilitation-plus-expansion model.
Myanmar's Ministry of Electricity and Energy is revising renewable energy law to standardize power purchase agreement templates. The regulatory change reduces legal negotiation overhead for independent power producers. Solar and wind EPC segments are responding by accelerating pre-development activity ahead of competitive tender rounds.
Buyer concentration among state-owned utilities is fragmenting as manufacturing estates and special economic zones procure directly through engineering contracts. Thilawa and Dawei SEZ authorities are bypassing central procurement to negotiate faster project execution. This pattern is most visible in Yangon Region where industrial load growth outpaces transmission expansion.
Myanmar Power Generation EPC Market Segmentation
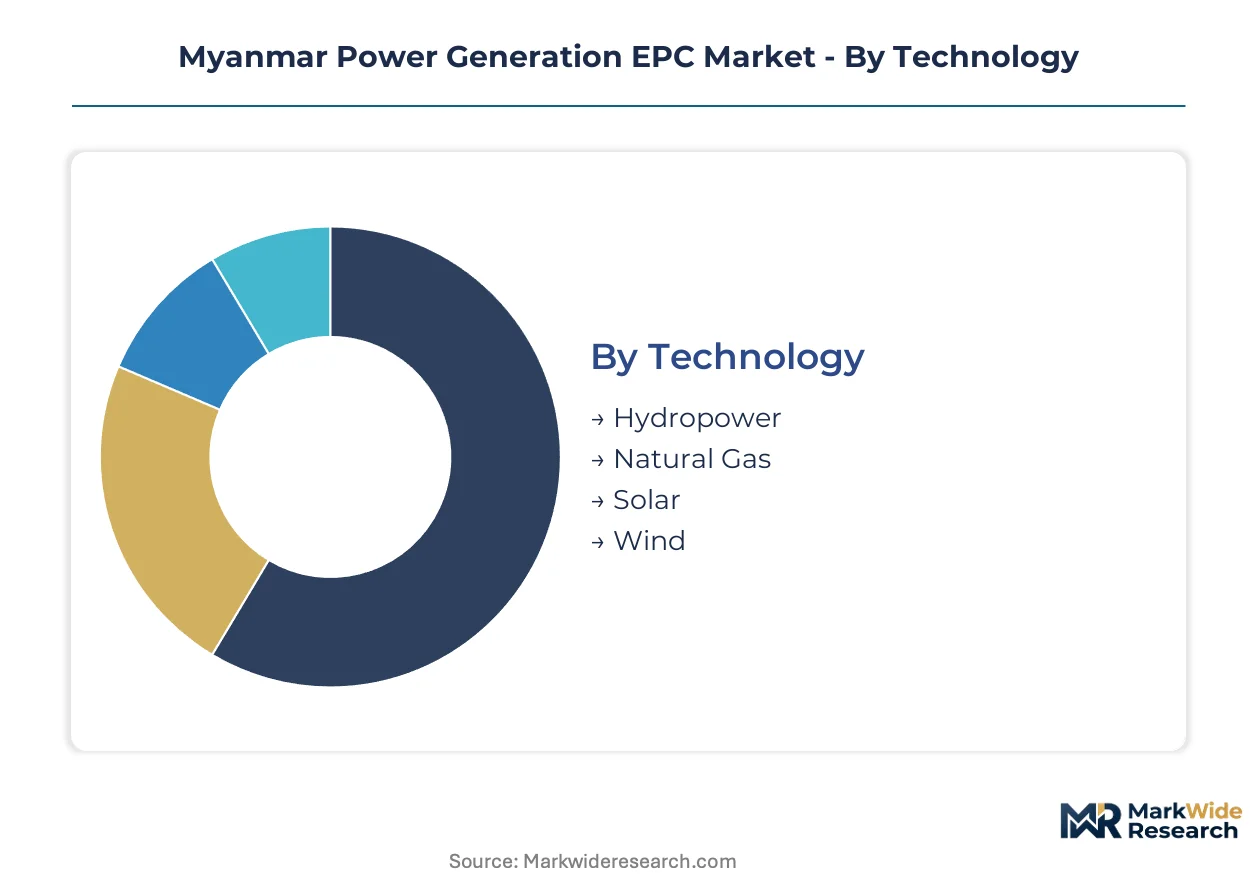
Technology choice dictates contractor specialization, equipment sourcing networks, and financing structures across Myanmar's power generation EPC landscape. Service delivery models and end-user procurement patterns further fragment competitive positioning among engineering firms.
Technology:
Technology selection determines civil works intensity, equipment import dependencies, and environmental permitting complexity.
- Hydropower:Run-of-river and reservoir-based schemes dominate Myanmar's installed base. Rehabilitation contracts along the Thanlwin River basin concentrate demand for turbine-generator replacements, though extended environmental assessments now add 12-18 months to greenfield approvals.
- Natural Gas:Combined-cycle configurations anchor grid-scale capacity additions near Thilawa Special Economic Zone. Mitsubishi Heavy Industries leverages its gas turbine leadership to capture these projects, facing forex exposure on Japanese and Korean equipment imports.
- Solar:Utility-scale PV and floating arrays on reservoir impoundments are gaining fastest traction as module costs decline. Irradiation mapping across the central dry zone is unlocking bankable pipelines previously deemed marginal.
- Wind:Early-stage resource assessment is underway in coastal Rakhine and Tanintharyi regions. Limited mesoscale data and grid interconnection constraints restrict near-term EPC contract flow.
Mature deployment sits with hydropower. Newer deployment is concentrated in solar.
Service Type:
Contract scope boundaries are shifting as owners unbundle packages to accelerate procurement timelines.
- Design:Front-end engineering packages require specialized hydrological modeling for dam projects and irradiation analysis for solar farms. Domestic engineering capacity concentrates in Yangon-based consultancies with limited turbine-generator specification experience.
- Procurement:Equipment sourcing spans Chinese solar modules, Korean switchgear, and Japanese gas turbines. Contractors face Kyat-Dollar volatility on dollar-denominated imports, with Thai Baht-denominated financing offering competitive alternatives for border-proximate projects.
- Construction:Civil works for hydropower involve dam infrastructure, tunnels, and powerhouse construction. Local content requirements favor Myanmar subcontractors for earthworks and transmission line erection.
- Commissioning:Synchronization testing and grid code compliance require imported specialists from Thailand, India, or China. Visa processing delays and premium labor rates inflate project overhead.
Full-scope EPC contracts concentrate procurement risk with single contractors. Unbundled service packages are expanding as independent power producers seek faster execution.
End User:
Procurement authority fragmentation is reshaping contract award patterns across customer categories.
- Government:Ministry of Electricity and Energy tenders dominate sovereign-guaranteed mega projects. Feed-in tariff recalibration and financing constraints compress margins while extending timelines.
- Industrial:Manufacturing clusters in Yangon and Mandalay are commissioning captive gas-fired and solar hybrid systems. Textile and food processing facilities prioritize production continuity over grid reliability.
- Commercial:Shopping centers and hotels in Yangon Region are deploying rooftop PV behind-the-meter. Distributed generation below 30 MW avoids sovereign guarantee requirements.
- Utilities:Electric Power Generation Enterprise enforces grid code compliance exceeding regional ASEAN norms. State-owned procurement is fragmenting as SEZ authorities bypass central tendering.
Utility procurement anchored historical EPC volume. Industrial self-generation is climbing the fastest as manufacturing electrification outpaces transmission expansion.
Project Size:
Scale thresholds determine financing structures, regulatory oversight intensity, and contractor qualification requirements.
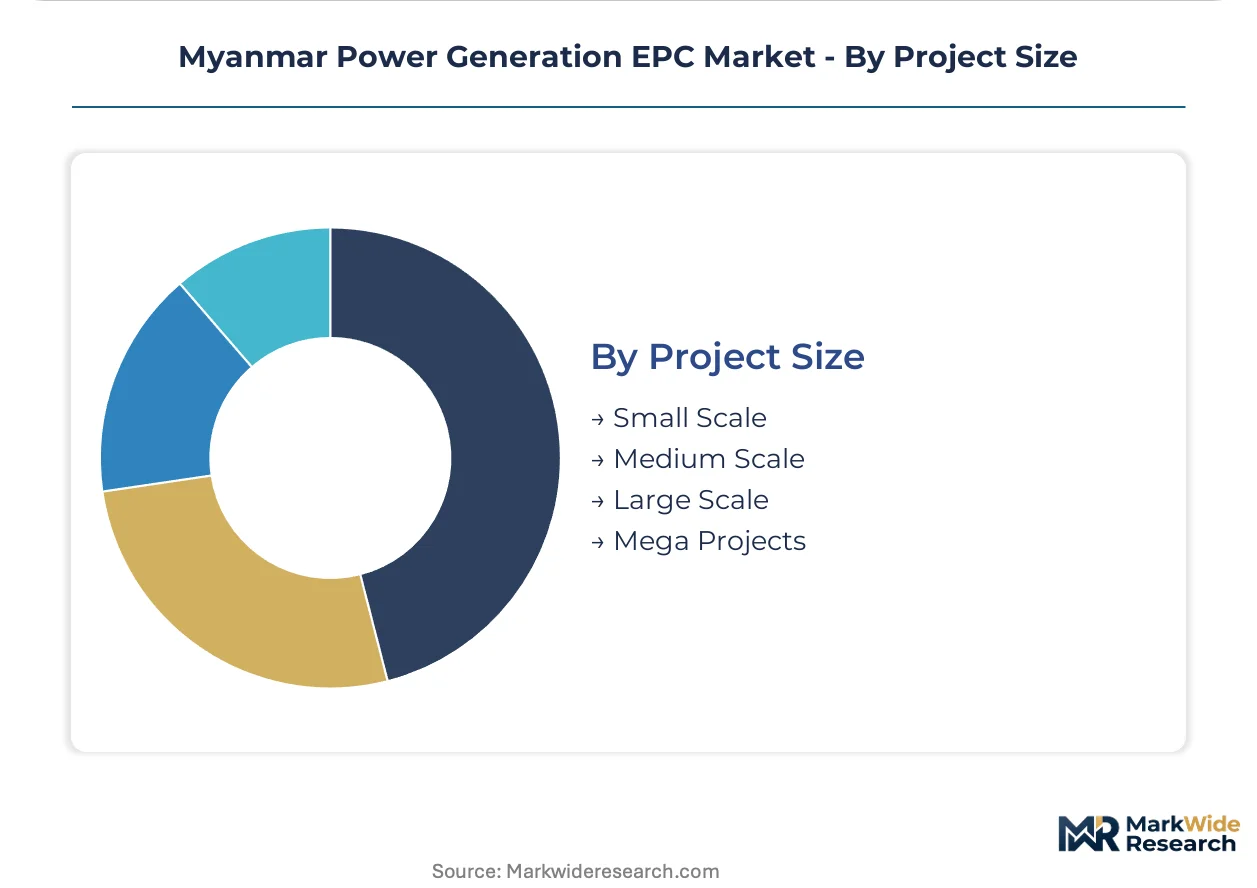
- Small Scale:Mini-grid and commercial-industrial rooftop systems below 10 MW. Ayeyarwady Delta townships present distributed opportunities underserved by current EPC capacity.
- Medium Scale:10-50 MW utility solar and gas-fired plants. Floating solar pilots at existing hydropower reservoirs fall within this bracket.
- Large Scale:50-200 MW greenfield developments requiring multi-source financing. Environmental impact assessments intensify at this threshold.
- Mega Projects:Exceeding 200 MW with sovereign-backed financing and extended commissioning timelines. Command disproportionate margin pools but concentrate execution risk.
Mega project pipelines are stagnating under financing constraints. Medium-scale solar EPC contracts are expanding most quickly as development timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Myanmar generates insufficient electricity to meet industrial demand, forcing manufacturing clusters to self-supply power through captive EPC contracts. Consumption growth in Yangon and Mandalay outpaces transmission expansion, creating distributed generation opportunities across the central dry zone and Ayeyarwady Delta.
Yangon Region
Thilawa Special Economic Zone drives gas-fired combined-cycle demand as textile and food processing facilities prioritize production continuity. The Ministry of Electricity and Energy enforces grid code compliance exceeding regional ASEAN norms for interconnection approvals. Industrial townships in Hlaingthaya and Shwepyitha are commissioning solar hybrid systems behind-the-meter to offset grid unreliability.
Mandalay Region
Manufacturing electrification mandates from the central government accelerate captive power deployment across cement and ceramics clusters. The Electric Power Generation Enterprise prioritizes turbine-generator replacements at aging facilities along the Irrawaddy River corridor. Solar irradiation mapping across the central dry zone is unlocking bankable utility-scale pipelines previously deemed marginal.
Ayeyarwady Region
Unmet electrification demand across Delta townships presents mini-grid opportunities below the 30 MW sovereign guarantee threshold. Feed-in tariff recalibration by the Ministry of Electricity and Energy attracts independent power producers to distributed generation segments. Pathein and Myaungmya sub-regions remain underserved by current EPC contractor capacity.
Tanintharyi Region
Dawei Special Economic Zone authorities bypass central procurement to negotiate faster project execution for industrial load growth. The national environmental regulator intensifies impact assessment protocols for coastal wind resource development. Early-stage mesoscale data collection is underway in Rakhine-adjacent waters, though grid interconnection constraints restrict near-term contract flow.
Myanmar Power Generation EPC Market Competitive Landscape
Top-tier vendors anchor mega-project EPC contracts with sovereign-backed financing, while mid-tier regional specialists compete for distributed generation and industrial captive power segments. The vendor base stratifies across three tiers: Japanese and Korean conglomerates with gas turbine technology leadership, Thai contractors leveraging cross-border logistics and Baht-denominated financing, and domestic Myanmar firms capturing civil works and local content mandates. Strategic archetypes include technology licensors, regional procurement integrators, and hybrid rehabilitation specialists. Competitive positioning concentrates on cross-border partnership structures and domestic content localization capabilities.
Within the technology-licensor tier, Mitsubishi Heavy Industries Group anchors large-scale combined-cycle positioning near Thilawa Special Economic Zone. TTCL Public Company Limited exemplifies the regional procurement archetype, leveraging Thai-Myanmar cross-border engineering capabilities and Baht-denominated financing to undercut competitors exposed to Kyat-Dollar volatility. Hyundai Engineering and Construction Corporation Limited occupies a position among Korean EPC contractors competing for hydropower rehabilitation frameworks along the Thanlwin River basin.
| Leading Market Players |
|---|
| Zeya & Associates Co. Ltd. |
| Hyundai Engineering and Construction Corporation Limited |
| TTCL Public Company Limited |
| Mitsubishi Heavy Industries Group |
| Sumitomo Corporation |
| Snowy Mountains Engineering Corporation Holdings Limited |
| Parami Energy Group of Companies |
| Marubeni Corporation |
| EAM Myanmar Ltd. |
| Others |
Supply & Pricing Matrix
Captive equipment sourcing from Japanese and Korean turbine manufacturers anchors both supply security and premium pricing power for gas-fired combined-cycle projects near Thilawa Special Economic Zone. This backward integration into proprietary gas turbine technology insulates Mitsubishi Heavy Industries from Kyat-Dollar volatility while commanding margin premiums unavailable to procurement-dependent competitors.
Pricing Analysis
Lead-time premiums for expedited Korean and Japanese gas turbine deliveries compress contractor margins on urgent industrial captive power projects. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation driven by sovereign guarantee backing and domestic content compliance levels. Cost compression in solar EPC tiers is intensifying because module price declines outpace balance-of-system cost reductions. Industrial manufacturing clusters in Yangon exhibit the highest price sensitivity due to grid unreliability forcing redundant system investments, while sovereign-backed mega projects show lowest sensitivity given concessional financing structures.
Supply Chain Analysis
Domestic content mandates from Myanmar's Ministry of Electricity and Energy are reshaping sourcing patterns toward Thai border-proximate logistics corridors and local civil works subcontractors. Equipment supply concentrates in Japan, South Korea, and China for gas turbines, generator sets, and solar modules respectively. Raw material dependencies span high-grade steel castings for turbine rotors, polysilicon ingots for PV cells, and copper busbar for switchgear assemblies. Single-source vulnerability from concentrated Japanese gas turbine licensors creates structural procurement risk. Distribution runs through Yangon port customs clearance and overland Thai-Myanmar border corridors for time-critical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's power generation EPC sector is consolidating around contractors with captive technology access and cross-border financing capabilities. Sovereign financing constraints and feed-in tariff recalibration are forcing weaker procurement-dependent players toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from Thai Baht-denominated financing competitors by deepening backward integration into turbine maintenance and spare parts inventory within Myanmar. Secure exclusive channel control over Dawei and Thilawa Special Economic Zone industrial procurement offices before regional specialists establish presence. The emerging threat of Chinese EPC firms with state-backed financing demands preemptive certification investment in ISO 9001 and grid code compliance capabilities. For New Entrants and Emerging Players: Begin with mini-grid and commercial-industrial rooftop segments below 30 MW across Ayeyarwady Delta townships, where incumbent capacity remains thinnest and sovereign guarantee requirements do not apply. Target captive solar-gas hybrid systems for textile and food processing facilities in Hlaingthaya and Shwepyitha industrial townships. A direct equipment-leasing go-to-market angle bypasses upfront capital constraints that limit competitor penetration. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Thai regional specialists seeking Myanmar operational platforms and technology licensors requiring local execution capability. Long-term viability favors contractors with demonstrated grid code compliance and established Electric Power Generation Enterprise relationships. The signal to watch is Ministry of Electricity and Energy tender frequency for medium-scale solar, which indicates sovereign procurement commitment and financing availability.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Engineering Partnership | Thai-Myanmar logistics corridors reduce Kyat-Dollar exposure on equipment imports. |
| Domestic Content Localization | Local civil works compliance satisfies Ministry of Electricity and Energy tender evaluation criteria. |
| Floating Solar Technology Integration | Reservoir-mounted PV diversifies revenue for state-owned hydropower operators. |
| Grid Code Certification Investment | Electric Power Generation Enterprise technical specifications exceed regional ASEAN norms. |
| Captive Power System Deployment | Industrial self-generation addresses manufacturing cluster electrification mandates. |
Research Methodology
Independent corroboration across primary interviews with EPC contractors, IPP project developers, and Electric Power Generation Enterprise planning officers, combined with secondary validation through Ministry of Electricity and Energy tender announcements, FERC-equivalent grid interconnection filings, and regional development bank project databases, underwrites the qualitative findings. Bottom-up project pipeline aggregation and top-down macroeconomic energy demand modeling provide triangulation checks.
Rate-of-change decomposition separates volume growth from unit price movements across the projection horizon. Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed capacity buildout trajectories and equipment cost curves. Key inputs encompass solar module price indices, gas turbine delivery lead times, and hydropower rehabilitation backlogs along the Thanlwin River basin.
Feed-in tariff recalibration, sovereign financing availability, and foreign contractor licensing rule changes are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented analytical boundaries and stated scenario conditions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Third Generation Energy Sources Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Indonesia Power Market
Power Generation
Micro CHP Market
Power Generation
Industrial Solar Generator Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Thailand Power Generation EPC Market
Power Generation
Thermal Power Market
Power Generation
Steam Turbine Market
Power Generation
Distributed Generation Market
Power Generation
Global Power Generation Market
Power Generation
United Kingdom Power Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Australia Thermal Power Market
Power Generation
Japan Thermal Power Plant Market