
 Retail Electricity Market | 2026-2036
Retail Electricity Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Electricity Market Analysis
Market Context
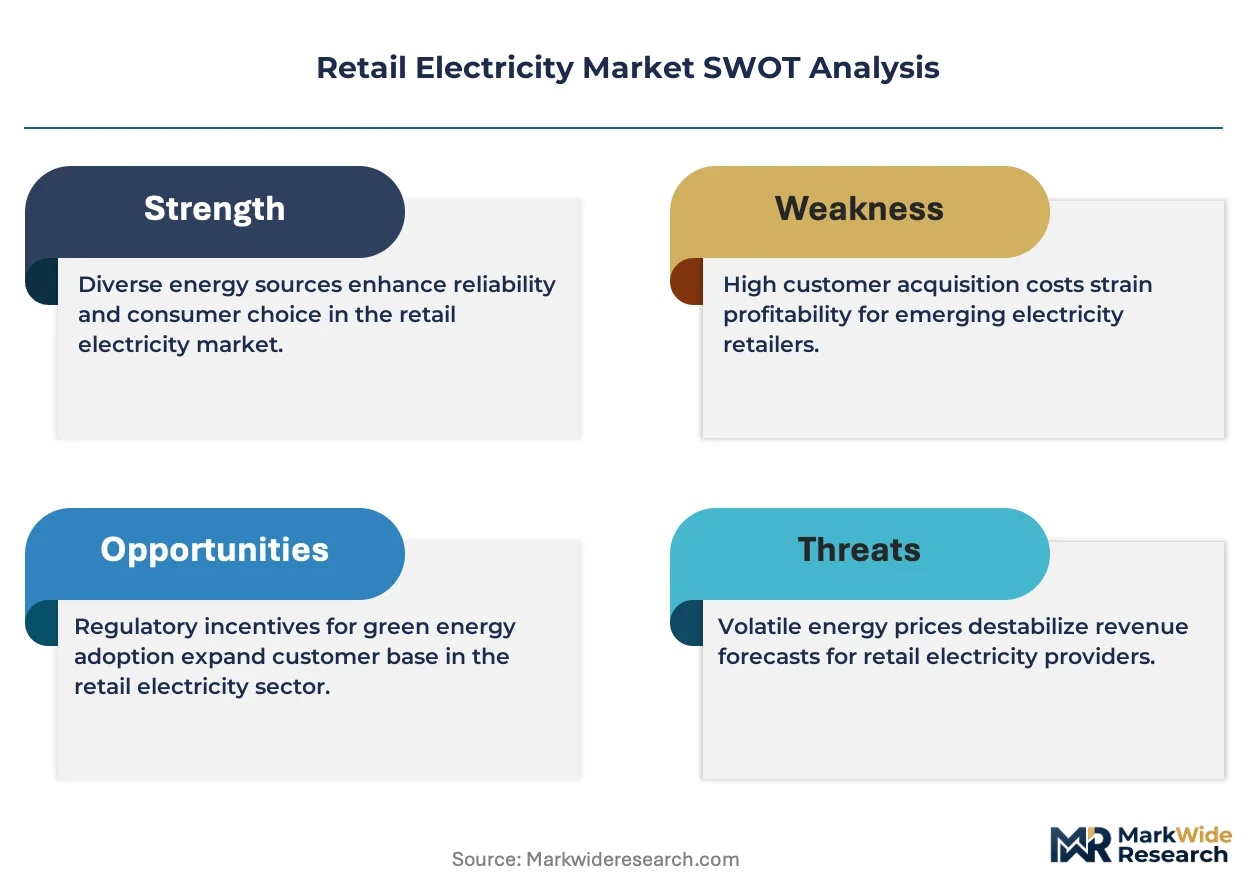
Net metering reform is expanding the cost-of-entry calculus for new retail electricity providers across deregulated US states. NRG Energy leverages its multi-state generation fleet to anchor retail pricing power in Texas and the Northeast. Direct Energy competes through bundled home services that reduce customer churn in volatile markets. Shell Energy North America specializes in renewable energy certificates and carbon-neutral products for corporate offtakers.
Technical Definition and Structural Segments
Retail electricity denotes the final sale of electrical energy to end-use consumers through regulated or competitive market structures, typically delivered at 120-480 volts alternating current via distribution networks operated by local utilities. The primary commercial purpose centers on bridging wholesale generation markets with differentiated customer service, billing, and risk-management products. Fixed-rate contracts dominate residential customer retention strategies, while time-of-use pricing captures the fastest-growing segment among commercial and industrial buyers managing peak demand charges. Prepaid and pay-as-you-go models occupy niche positions targeting credit-constrained households, though margin pools remain thinner due to higher servicing costs and elevated churn.
Regulatory Framework
FERC Order 2222 and state-level public utility commission rules are reshaping distributed energy resource aggregation, enabling retail providers to stack value streams behind the meter. EPA power plant emissions standards and state renewable portfolio standards jointly constrain fuel-mix choices, pushing retail portfolios toward wind, solar, and battery-backed offerings. Stakeholders must monitor interconnection queue backlogs and transmission access reforms, as these bottlenecks determine whether retail green promises translate into physical delivery.
Market Dynamics
Data center load growth is forcing retail electricity providers to restructure procurement portfolios around 24/7 carbon-free matching, compressing traditional annual REC contracting into hourly granularity requirements.
Growth Catalysts
- Inflation Reduction Act tax credits:Production and investment credits for solar, wind, and storage are lowering the delivered cost of renewable-heavy retail products, expanding addressable customer segments in deregulated US states.
- Hourly load matching:Corporate buyers with science-based targets are demanding time-stamped clean energy procurement, creating premium product tiers that capture margin above commodity rates.
- Texas ERCOT market depth:The state's liquid wholesale market and retail choice framework attract commercial buyers seeking direct exposure to nodal pricing volatility with managed downside.
Market Restraints
- Interconnection queue congestion:Grid connection backlogs stretching 3-5 years in high-demand zones prevent retail providers from backing green tariffs with new physical generation assets.
- Natural gas price volatility:Gas-fired generation still anchors marginal pricing in most ISOs, exposing fixed-rate retail contracts to basis risk when forward curves spike.
- Utility franchise rights:Regulated incumbent utilities in partially deregulated states retain default service obligations that limit competitive retail penetration in residential segments.
Strategic Opportunities
- Behind-the-meter aggregation:FERC Order 2222 compliance at state PUCs enables retail providers to monetize customer-sited batteries and EVs as virtual power plants.
- Industrial electrification clusters:Hydrogen, steel, and chemical producers seeking firm clean power represent underserved load segments with multi-decade contract horizons.
- Dynamic pricing platforms:Real-time rate engines linked to wholesale ISO data streams allow retail providers to capture value from price-responsive commercial demand.
Industry Challenges
- Data science talent scarcity:Retail providers struggle to hire quantitative analysts capable of modeling hourly price shapes and optimizing storage dispatch algorithms.
- Legacy billing system integration:Acquiring customers from incumbent utilities requires mapping to proprietary interval data formats and settlement systems that vary by distribution territory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Electricity Market |
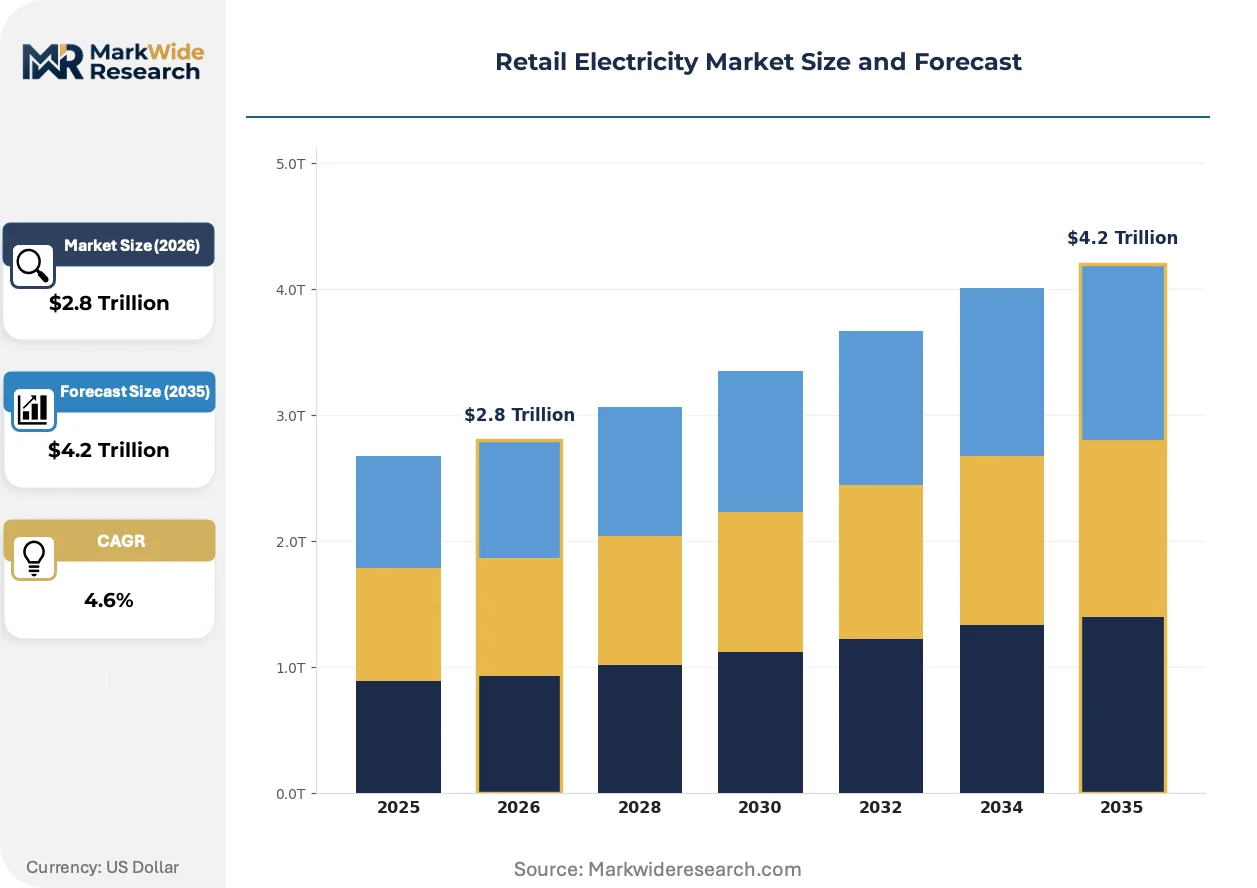
| Market Size in 2026 | $2.8 Trillion |
| Market Size in 2035 | $4.2 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fixed Rate, Variable Rate, Time-of-Use, Prepaid Customer Type: Residential, Commercial, Industrial, Non-Profit Billing Model: Monthly Billing, Usage-Based, Flat Fee, Pay-As-You-Go Contract Length: Short Term, Long Term, No Contract, Flexible |
| Companies Covered | Florida Power & Light Company, Virginia Electric & Power Company, NRG Energy, Shell Energy North America, Direct Energy, Reliant Energy, Green Mountain Energy, MP2 Energy, Freepoint Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Electricity Market Emerging Trajectories
Retail electricity is fragmenting into specialized product architectures that separate commodity energy from layered risk-management and sustainability services. Three developments are compressing the traditional bundled model.
Battery storage is modularizing retail product design. Containerized lithium-ion systems are dropping below four-hour duration economics, enabling retail providers to offer firming services without long-term tolling contracts. Commercial buyers in California and Texas are adopting storage-backed fixed rates that cap exposure to peak pricing events. This technology is modularizing the capital structure of retail supply, shifting asset ownership from balance-sheet-heavy generators to distributed customer sites.
FERC Order 2222 implementation across state public utility commissions is unlocking distributed energy resource aggregation. The rule compels ISOs to allow retail providers to bid aggregated customer loads and generation into wholesale markets. Texas and California regulators have issued compliance orders, while Northeast states lag in rulemaking. Commercial and industrial segments with behind-the-meter solar and batteries gain the most, as retail providers can now stack wholesale energy, capacity, and ancillary service revenues.
Corporate buyers are unbundling sustainability verification from energy procurement. Large commercial offtakers now contract separately for hourly matched clean power, REC retirement, and emissions accounting services. This disintermediation pressures traditional retail providers who bundled these functions. Technology and financial services firms with dedicated energy procurement teams are driving this shift most aggressively in California and Virginia data center corridors.
Retail Electricity Market Segmentation
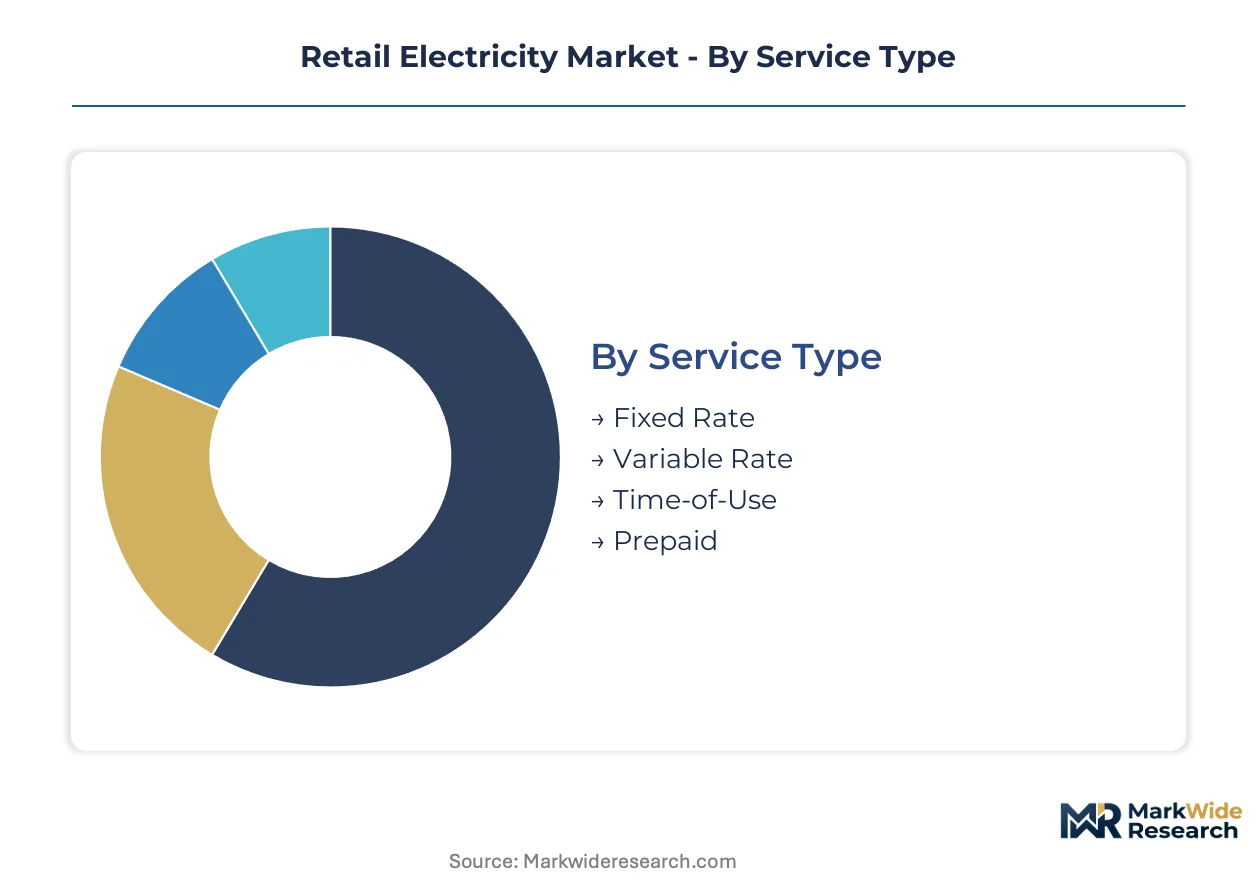
Retail electricity providers structure product architectures around risk transfer mechanisms and customer liquidity profiles. Segmentation determines procurement strategy, hedging intensity, and the granularity of data infrastructure required for billing and settlement operations.
Service Type:
Customization spans from fully hedged price certainty to exposure-linked dynamic rates that shift wholesale volatility onto customers.
- Fixed Rate:Locks energy charges at a constant cents-per-kWh for the contract duration regardless of wholesale price movements. Commercial buyers in Texas and California concentrate here, seeking budget predictability amid ERCOT nodal volatility and CAISO congestion events.
- Variable Rate:Ties monthly bills to indexed wholesale benchmarks or provider-specific cost adjustments. Residential customers with payment flexibility and tolerance for seasonal swings drive uptake in competitive retail choice markets.
- Time-of-Use:Applies differentiated rates across peak, shoulder, and off-peak intervals to shape consumption patterns. Industrial facilities with shiftable process loads in California's SGIP territories capture arbitrage value.
- Prepaid:Requires customers to fund accounts before consumption, with balance-triggered disconnections replacing traditional credit collections. Credit-constrained households in Texas municipal utility territories form the core addressable base.
Most installed capacity flows through Fixed Rate contracts. Expansion is steepest in Time-of-Use as AMI penetration enables interval metering at scale.
Customer Type:
Margin profiles diverge sharply across segments, with acquisition costs and churn rates scaling inversely with account size and contract sophistication.
- Residential:Encompasses single-family homes, apartments, and master-metered multi-unit dwellings. Churn-sensitive providers bundle home services and deploy autopay incentives to reduce switching in Texas and Pennsylvania retail choice zones.
- Commercial:Covers small businesses, retail chains, and office buildings with moderate load flexibility. Demand concentrates in deregulated states where tenants bear direct supply costs rather than embedded landlord charges.
- Industrial:Serves manufacturing, mining, and processing facilities with high load factors and voltage-level interconnections. Data center operators in Northern Virginia and Texas represent the fastest-expanding subsegment, driving 24/7 carbon-free procurement requirements.
- Non-Profit:Includes hospitals, universities, and government entities with tax-exempt status and mission-driven sustainability targets. These buyers prioritize fixed-rate renewable products with direct project attribution over commodity savings.
Revenue concentration sits with Industrial accounts. Customer acquisition investment is climbing fastest in Commercial segments as providers compete for electrifying small business loads.
Billing Model:
Operational complexity and working capital intensity vary with meter read frequency and payment collection architecture.
- Monthly Billing:Standard post-pay cycle based on cumulative interval or estimated reads. The dominant collection method across residential and small commercial portfolios in established retail choice markets.
- Usage-Based:Charges align with actual consumption captured through smart meter data streams. Industrial buyers with sub-hourly telemetry in PJM and ERCOT territories favor this precision for demand charge management.
- Flat Fee:Predictable periodic payment regardless of consumption volume, typical in all-inclusive rental arrangements and certain municipal utility structures.
- Pay-As-You-Go:Real-time balance debiting tied to smart meter communication, prevalent in prepaid residential offerings and mobile-enabled emerging market deployments.
Transaction volume flows predominantly through Monthly Billing. Infrastructure investment is accelerating most quickly in Usage-Based models as AMI deployment extends interval data access.
Contract Length:
Hedging requirements and customer lifetime value calculations shift materially across commitment horizons.
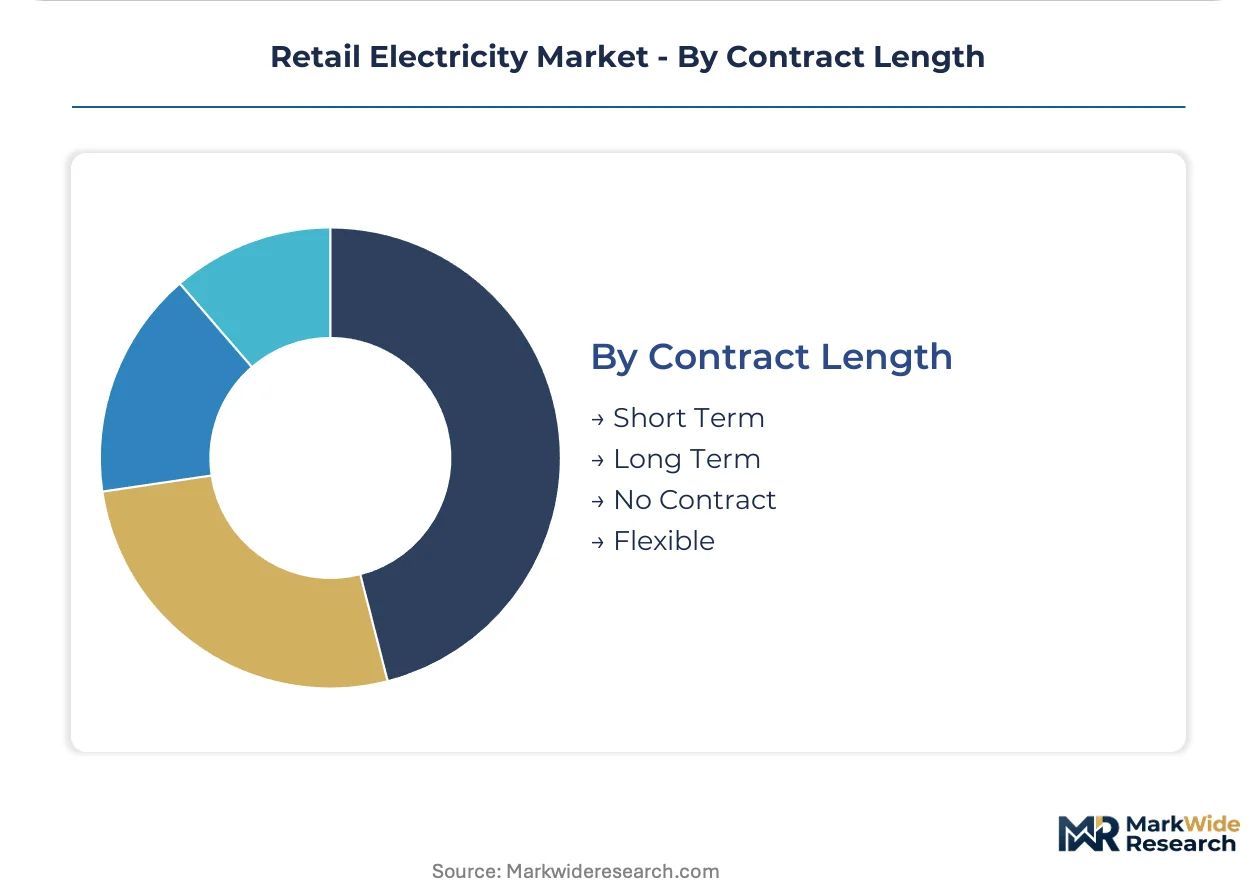
- Short Term:Agreements spanning months to one year, enabling rapid repricing in volatile wholesale conditions. Commercial buyers with uncertain facility tenures in Texas nodal markets favor this flexibility.
- Long Term:Multi-year commitments that support renewable project financing and physical hedge structures. Data center operators in Virginia and Arizona negotiate these for clean energy matching obligations.
- No Contract:Month-to-month service with termination at will, carrying premium rates to offset elevated churn risk. Residential switchers in Pennsylvania and Ohio retail choice programs populate this segment.
- Flexible:Hybrid structures with core baseload commitments and adjustable volumetric bands. Industrial facilities with production variability in California's SGIP markets utilize these for demand response participation.
Most retail load sits under Long Term contracts. Portfolio growth is sharpest in Flexible structures as buyers seek to optimize behind-the-meter asset dispatch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California host the deepest talent pools for electricity trading and risk management, drawing quantitative analysts from Houston energy corridors and Silicon Valley clean-tech clusters.
United States
Data center load expansion in Northern Virginia and Dallas-Fort Worth is reshaping procurement patterns. FERC Order 2222 implementation varies by state PUC, with Texas and California ahead of Northeast jurisdictions. ERCOT's nodal market in Texas attracts commercial buyers seeking direct wholesale price exposure with managed downside.
Germany
Industrial electrification clusters in the Ruhr and Bavaria drive demand for 24/7 carbon-free power matching. The EU Green Deal and national coal phase-out regulations accelerate renewable portfolio requirements. Berlin-Brandenburg data center corridors negotiate long-term power purchase agreements with hourly granularity.
United Kingdom
Corporate renewable procurement concentrates in London and Southeast commercial property markets. Ofgem's regulatory framework governs supplier licensing and consumer protection standards. Scotland's wind generation surplus feeds into English retail green tariffs through cross-border trading mechanisms.
Australia
Commercial and industrial solar-plus-storage adoption accelerates in New South Wales and Queensland mining regions. The Australian Energy Regulator oversees retail market conduct and pricing transparency obligations. Melbourne and Sydney fintech clusters drive demand for time-of-use products with interval metering.
Japan
Corporate buyers in Tokyo and Osaka metro areas seek renewable energy certificates for RE100 commitments. METI's electricity market reforms enable retail competition in previously bundled service territories. Kyushu and Hokkaido renewable generation zones face interconnection constraints limiting retail green product expansion.
Retail Electricity Market Vendor Landscape
The competitive structure tilts toward generation-backed integrated providers with multi-state footprints. Tier-one positions cluster around utilities with captive generation fleets, while independent retail marketers compete on digital customer acquisition and specialized sustainability products. Two strategic archetypes dominate: vertically integrated energy majors leveraging upstream assets for retail pricing power, and technology-enabled specialists offering granular clean energy matching. M&A activity concentrates on distributed energy resource platforms and behind-the-meter aggregation capabilities.
Within the integrated provider tier, NRG Energy and Direct Energy exemplify generation-anchored retail strategies. Shell Energy North America occupies a position bridging commodity trading expertise with corporate sustainability procurement. These three represent distinct competitive vectors: fleet-backed pricing power, bundled service retention, and certificate-based clean product structuring.
| Leading Market Players |
|---|
| Florida Power & Light Company |
| Virginia Electric & Power Company |
| NRG Energy |
| Shell Energy North America |
| Direct Energy |
| Reliant Energy |
| Green Mountain Energy |
| MP2 Energy |
| Freepoint Energy Solutions |
| Others |
Supply Flow & Price Mechanics
Henry Hub natural gas futures cascade through wholesale generation markets into retail electricity pricing tiers, compressing margins for fixed-rate providers when forward curves spike while rewarding those with upstream generation control or storage-backed product architectures.
Pricing Analysis
Bundled commodity-and-service offerings still dominate residential retention, though unbundled procurement is gaining traction among corporate buyers who separate energy, RECs, and risk management into distinct contracts. Price differentiation hinges on generation source attribution—wind-solar-battery portfolios command premiums over gas-heavy blends—and contract granularity, with hourly-matched products capturing margin above annual REC equivalents. Pricing pressure stems from interconnection queue delays that prevent new renewable assets from backing green tariff promises, forcing providers to source higher-cost secondary markets. Industrial data center buyers exhibit lowest price sensitivity, prioritizing 24/7 carbon-free matching over cents-per-kWh savings, while credit-constrained residential segments in prepaid markets show acute sensitivity to deposit requirements and disconnect thresholds.
Supply Chain Analysis
Regional distribution centers in Texas ERCOT and California CAISO territories anchor hub-and-spoke logistics for retail electricity delivery, with nodal pricing volatility determining procurement dispatch patterns across each zone. Generation supply concentrates in the United States, Germany, and Australia where deregulated market structures enable competitive retail entry. Raw material dependencies span lithium-ion battery cells for storage-backed products, solar PV modules for distributed generation, and natural gas turbines for firming capacity. Supply chain risk centers on single-source vulnerability in battery cell supply, with Asian manufacturing concentration exposing providers to tariff and logistics chokepoint disruptions. Distribution runs through independent system operator settlement systems and local utility distribution networks, requiring proprietary data integration for interval metering and billing precision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail electricity functions as a regulatory compounder where FERC Order 2222 implementation across state PUCs is restructuring competitive access rules and unlocking distributed energy resource aggregation revenue streams.
For Market Incumbents: Cement generation-backed pricing power through captive wind-solar-storage fleets in ERCOT and CAISO territories, insulating retail margins from gas price volatility that erodes fixed-rate contract profitability. Acquire behind-the-meter aggregation platforms to capture FERC Order 2222-enabled capacity and ancillary service revenues before compliance deadlines spread to Northeast states. Prioritize data science talent recruitment to optimize hourly storage dispatch algorithms that differentiate premium product tiers.
For New Entrants and Emerging Players: Enter via industrial electrification clusters in hydrogen, steel, and chemical processing corridors where incumbent utility green tariffs lack 24/7 carbon-free granularity. Target data center load growth in Northern Virginia and Dallas-Fort Worth, where science-based target commitments outstrip existing provider hourly-matching capabilities. Lead with dynamic pricing platforms linked to real-time ISO data streams, capturing value from price-responsive commercial demand that incumbents with legacy billing systems cannot serve.
For Investors and Strategic Acquirers: Asymmetric upside sits with distributed energy resource aggregation specialists possessing FERC Order 2222-compliant software stacks and utility interconnection relationships. Long-term viability favors providers with demonstrated ability to monetize customer-sited batteries and EVs as virtual power plants across multiple ISO territories. Watch interconnection queue clearance rates as the inflection signal—accelerated grid access enables physical asset-backed green products that command structural premiums over certificate-only alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Behind-the-Meter Aggregation Platform | FERC Order 2222 compliance unlocks wholesale market revenue streams from customer-sited assets in Texas and California. |
| Hourly Carbon-Free Matching Product | Science-based target commitments from data center operators create premium tier demand exceeding annual REC contracting. |
| Storage-Backed Fixed Rate Offering | Containerized lithium-ion economics below four-hour duration enable peak price capping without long-term tolling contracts. |
| Dynamic Pricing Engine Deployment | Real-time rate engines linked to ISO data streams capture value from price-responsive commercial demand in nodal markets. |
| Green Certification Program Expansion | Unbundled sustainability verification services address corporate buyers separating emissions accounting from energy procurement. |
Methodological Framework
Multiple input streams — structured interviews with utility planning officers and IPP project developers, EIA generation and consumption databases, FERC interconnection queue filings, and ISO market operator disclosures — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged retail electricity provider executives, commercial and industrial energy procurement managers, state public utility commission staff, and EPC contractors active in utility-scale solar and storage development. Secondary validation drew from IEA electricity market reports, EPA power plant emissions standards documentation, and project finance databases tracking renewable energy certificate contracting trends.
Historical capacity additions and load growth patterns were cross-referenced against panel input from industry participants to anchor projection assumptions across the analysis window. The analytical framework modeled segmentation dimensions including service type, customer category, billing model, and contract length, with fuel source attribution and regional grid regulatory structure as energy-specific variables. CAGRs were derived from supply-side capacity buildout trajectories and demand-side electrification intensity assumptions, incorporating IRA tax credit elasticity effects and data center load growth scenarios as sector-specific forecast inputs.
Inputs from EIA and ISO market operators were available through the study window; gaps in behind-the-meter distributed generation telemetry and real-time corporate procurement contract terms introduce uncertainty bands around commercial segment growth estimates. Forecasts reflect documented assumptions regarding interconnection queue clearance rates, natural gas price curve stability, and state-level retail choice program expansion decisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Japan Thermal Power Plant Market
Power Generation
Distributed Power Generation Market
Power Generation
Global Turbines Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Algeria Power Market
Power Generation
Iraq Power EPC Market
Power Generation
Gas Gensets Market
Power Generation
Subsea Power Grid System Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Stirling Engine Market
Power Generation
Variable Speed Generator Market
Power Generation
Oilfield Power Generation Market
Power Generation
Global Power to Gas Market
Power Generation
Oman Power Market
Power Generation
Global Power Grid System Market
Power Generation
India Gensets Market