
 Copper Mining Market | 2026-2036
Copper Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Mining Market Intelligence
Demand from electronics manufacturers and electric vehicle producers is reorganizing the traditional buyer landscape, once dominated by the construction sector. State-owned Codelco anchors Chile's world-leading copper output. Freeport-McMoRan operates vast, geographically diverse assets, including major mines in the Americas and Indonesia. BHP leverages its extensive portfolio to navigate commodity cycles and invest in advanced extraction technologies.
Copper mining involves the extraction of ores, which are then processed to concentrate the metal for smelting. These ores, particularly porphyry deposits, often contain less than 1% copper, necessitating large-scale operations and processes like froth flotation to be economically viable. Open-pit mining remains the predominant method for these extensive, low-grade deposits. Underground mining techniques, such as block caving, are increasingly applied to access deeper, higher-grade ore bodies.
A complex regulatory environment governs the industry. The US EPA enforces stringent rules on tailings management and water discharge, while the EU's Critical Raw Materials Act aims to secure the continent's supply chain. In China, the Ministry of Ecology and Environment (MEE) imposes strict emission controls on smelters. Stakeholders must navigate these diverse environmental mandates while securing capital for long-term mine development.
Market Dynamics
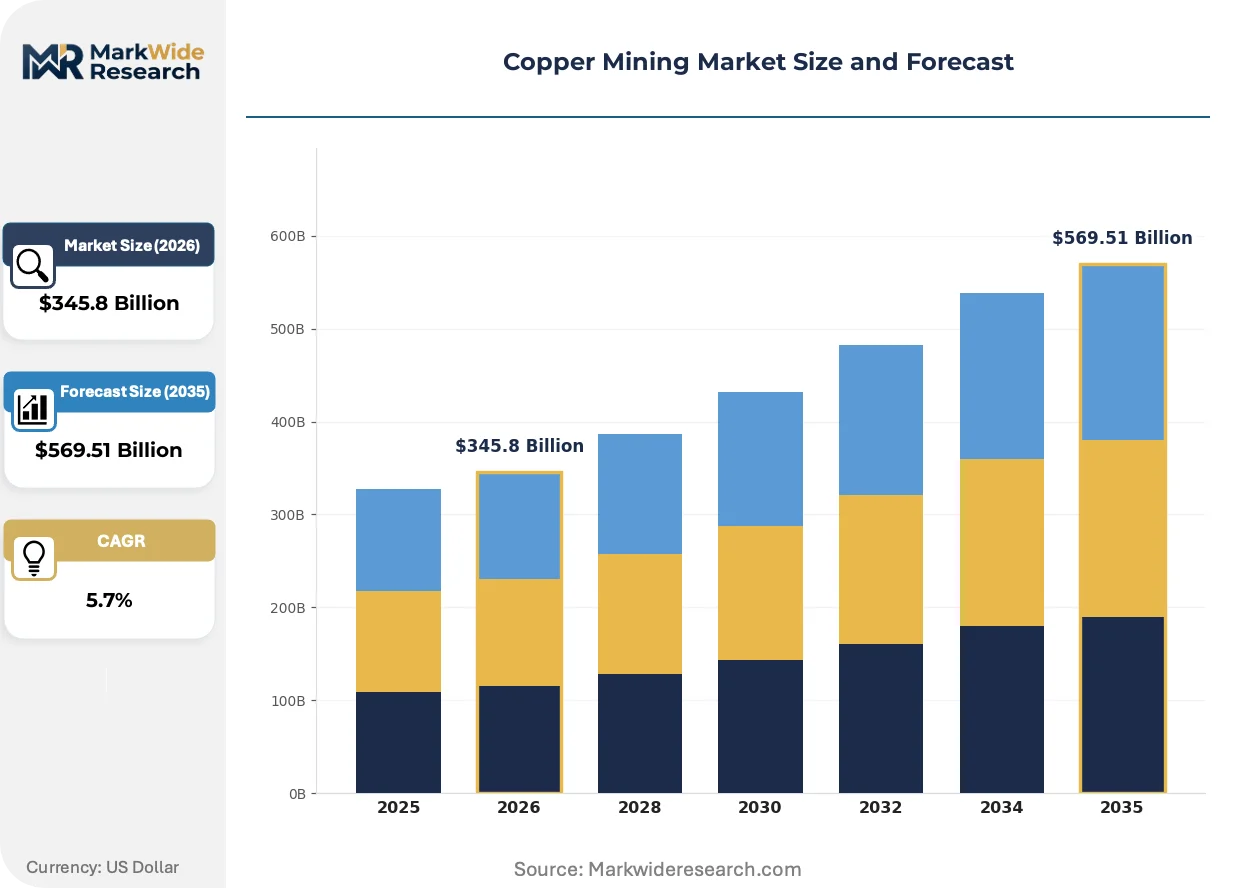
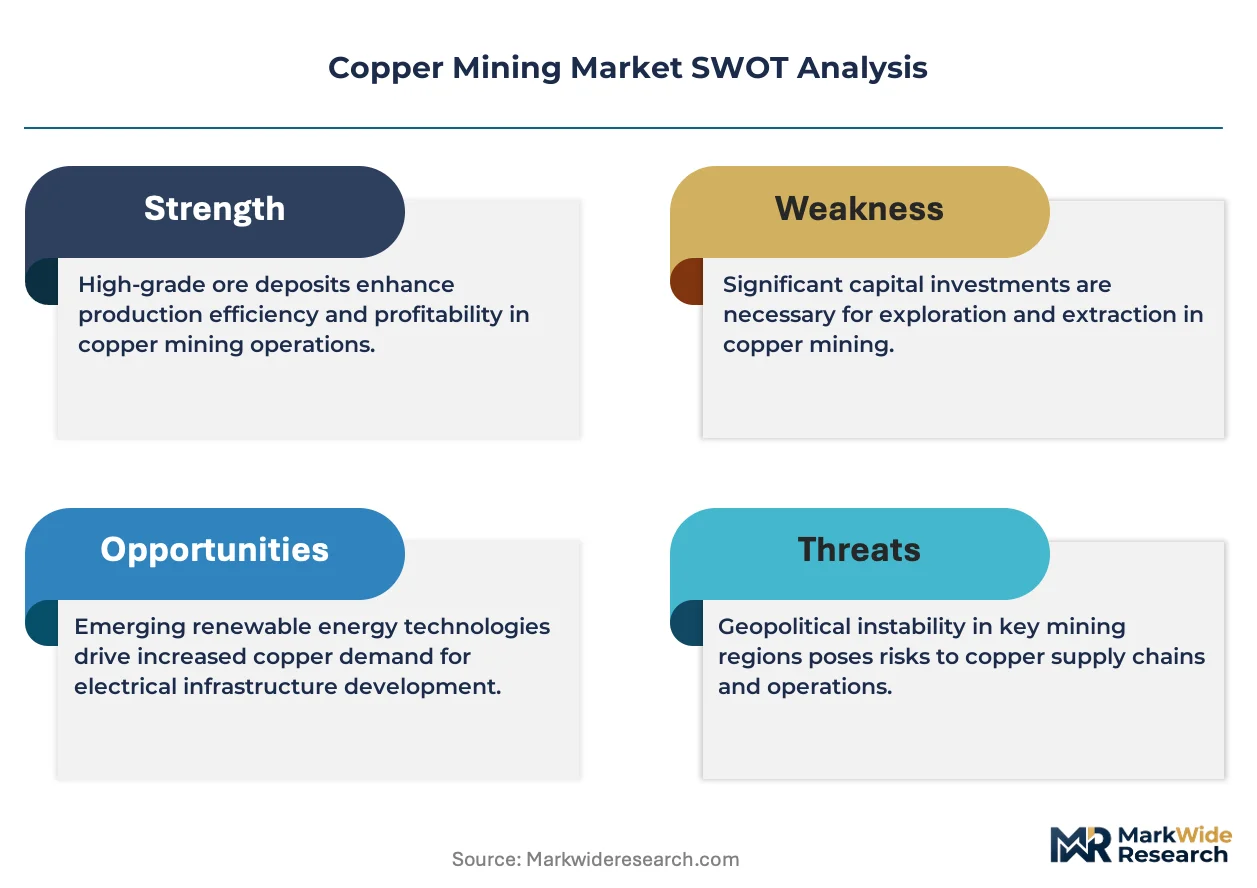
The fundamental dynamic shaping the copper mining market is the structural supply deficit emerging from the energy transition. Surging demand from electric vehicle and renewable energy sectors clashes with declining ore grades, long project development timelines, and heightened environmental scrutiny.
Growth Catalysts
- Policy Mandates:The EU Green Deal and its associated Critical Raw Materials Act are creating direct incentives and securing demand for copper to meet electrification and decarbonization targets across member states.
- Electrification Infrastructure:Demand from manufacturers of electric vehicle charging stations, grid-scale battery storage systems, and upgraded power transmission lines provides a sustained growth driver for copper consumption.
- Urbanization in Emerging Economies:Continued construction and infrastructure development in densely populated regions of India and Southeast Asia require significant volumes of copper for wiring, plumbing, and telecommunications.
Market Restraints
- Declining Ore Grades:Mature porphyry deposits in key producing nations like Chile and Peru exhibit steadily falling copper content, which increases the volume of ore that must be mined and processed per ton of finished metal.
- Water Scarcity:Mining operations, particularly in arid regions of South America and Australia, face significant operational and regulatory constraints due to the high water consumption required for ore processing.
- Permitting Delays:A complex and lengthy permitting process for new mines, involving stringent environmental impact assessments and community consultations, acts as a major barrier to bringing new supply online quickly.
Strategic Opportunities
- Deep Sea Mining:Exploration of polymetallic nodules on the seabed presents a frontier opportunity to access high-grade copper resources, although it faces significant technological and environmental hurdles.
- Secondary Processing Innovation:Investing in advanced pyrometallurgical and hydrometallurgical recycling technologies allows for the recovery of high-purity copper from electronic waste and end-of-life products, creating circular supply chains.
- Data-Driven Exploration:The application of artificial intelligence and machine learning to analyze geological survey data can significantly improve the accuracy and speed of identifying new, economically viable copper deposits.
Industry Challenges
- Capital Expenditure Intensity:The immense upfront capital required to develop a new open-pit or underground mine, including the purchase of heavy machinery and construction of processing plants, poses a significant financial challenge.
- Social License to Operate:Gaining and maintaining the support of local communities and indigenous groups is a critical, non-technical challenge that can lead to project delays, operational disruptions, and reputational damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Mining Market |
| Market Size in 2026 | $345.8 Billion |
| Market Size in 2035 | $569.51 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mining Method: Open Pit, Underground, In-Situ Leaching, Block Caving Ore Type: Porphyry, Sediment-Hosted, Volcanogenic Massive Sulfide, Supergene Enrichment End Use Industry: Electrical Equipment, Construction, Electronics Manufacturing, Transportation Systems Mining Equipment Type: Drills, Excavators, Crushers, Conveyors, Haulers |
| Companies Covered | Freeport-McMoRan, BHP, Codelco, Zijin Mining, Southern Copper, Glencore, Anglo American, KGHM Polska Miedź, Antofagasta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Mining Market Strategic Shifts & Innovations
Technological advancement and regulatory pressure are forcing a dual focus on operational efficiency and environmental sustainability. Innovations aim to extract more value from existing assets while meeting stricter mandates on water usage, emissions, and supply chain transparency, a shift that is reshaping competitive positioning.
Autonomous and Digital Mining
Digital twin and autonomous haulage systems provide a virtual replica and robotic control over mining operations. Major operators in Australia and the Americas are deploying these technologies to improve safety and operational uptime. This integration is miniaturizing the human intervention required for routine extraction tasks, allowing skilled personnel to focus on higher-level optimization and strategic planning.
ESG-Driven Supply Chain Mandates
The EU's Corporate Sustainability Reporting Directive (CSRD) requires large companies to disclose detailed information on their value chain's environmental and social impacts. This regulation compels downstream users of copper to demand greater transparency and proof of responsible sourcing from miners. The metals and mining sector is most affected, investing in traceability platforms like blockchain to verify compliance.
Buyer Demand for Certified Copper
A notable behavioral shift is the move by industrial buyers toward specifying copper with a certified low-carbon footprint. This disrupts traditional purchasing, which was based primarily on grade and price, creating a distinct market for "green" metals. This trend is most pronounced among European automotive OEMs and electronics manufacturers who use sustainability credentials as a brand differentiator.
Copper Mining Market Segmentation
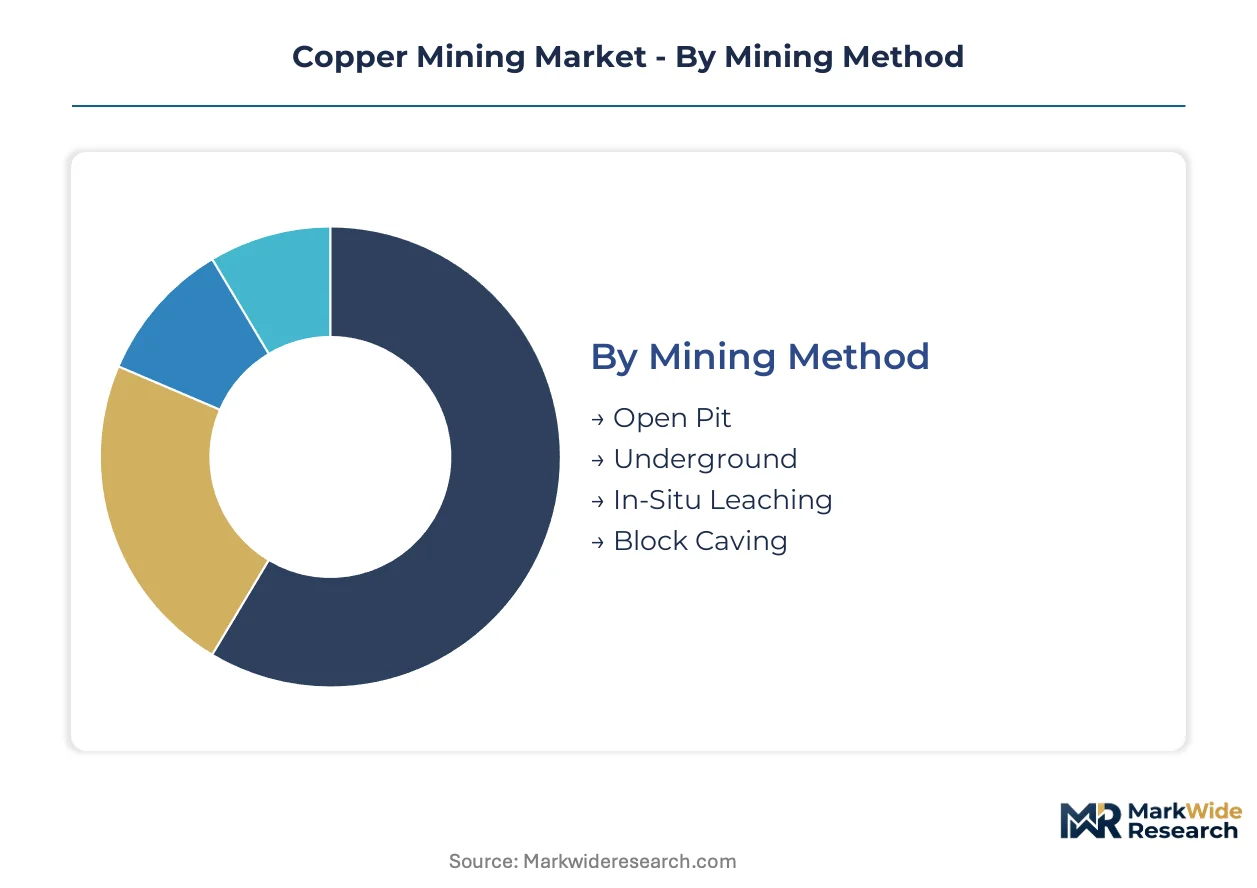
The copper mining market segments reflect the diverse operational approaches and end-use applications driving industry demand. Understanding these categories illuminates the varying capital requirements, technological advancements, and regulatory pressures across the value chain. This granular view helps stakeholders identify specific growth pockets and operational efficiencies within the broader market.
Mining Method:
The geographic spread of mining methods highlights regional geological advantages and technological maturity. Open-pit operations dominate in countries like Chile and Peru, while deeper deposits in Australia increasingly utilize underground techniques.
- Open Pit:This method involves extracting ore from a large, terraced pit, suitable for extensive, shallow, low-grade deposits. Demand for open-pit mining equipment concentrates in South American nations due to vast porphyry copper reserves, driven by the need for high-volume extraction.
- Underground:Underground mining accesses deeper ore bodies through tunnels and shafts, often targeting higher-grade deposits. Investment in underground techniques is notable in Canada and Indonesia, where complex geology necessitates precise extraction methods to maximize resource recovery.
- In-Situ Leaching:This technique involves injecting a leaching solution directly into the ore body to dissolve copper, which is then pumped to the surface. This method minimizes surface disturbance but faces strict environmental scrutiny regarding groundwater contamination.
- Block Caving:Block caving is a mass mining method for large, deep ore bodies, involving undercutting a block of ore which then collapses under its own weight. This technique offers cost efficiencies for specific geological formations.
Open Pit mining commands the established operational base. The steepest expansion runs through Underground methods, driven by the pursuit of deeper, higher-grade ore bodies.
Ore Type:
The concentration of copper ore types dictates processing requirements and overall project viability across different regions. Porphyry deposits are widely distributed globally, while sediment-hosted ores are prominent in specific geological basins.
- Porphyry:These large, disseminated deposits are the primary source of global copper production, often containing less than 1% copper. Operations in Chile and the United States rely heavily on porphyry deposits, where large-scale processing is essential for economic viability.
- Sediment-Hosted:Copper in these deposits occurs within sedimentary rocks, often in stratiform layers, yielding higher grades than porphyry. Mines in the Democratic Republic of Congo and Zambia frequently exploit sediment-hosted deposits, contributing significantly to African copper output.
- Volcanogenic Massive Sulfide:These deposits form from hydrothermal vents on the seafloor, containing significant concentrations of base metals including copper. Mines in Canada and Australia target VMS deposits for their polymetallic content.
- Supergene Enrichment:This process occurs when primary copper minerals are oxidized and redeposited at shallower depths, creating higher-grade zones. Such zones are often found overlying porphyry deposits, enhancing their economic potential.
Porphyry ore types form the foundational supply for the industry. Sediment-Hosted deposits are gaining significant volume share, particularly in emerging copper-producing regions.
End Use Industry:
The application focus of copper consumption highlights the shift in market drivers, moving from traditional sectors to those supporting the energy transition. Electronics manufacturing and transportation systems are exhibiting substantial growth in copper demand.
- Electrical Equipment:This segment includes power cables, transformers, generators, and electric motors, where copper's high conductivity is indispensable. Demand from expanding grid infrastructure in India and renewable energy projects in Europe provides a sustained consumption driver.
- Transportation Systems:Copper is vital for wiring harnesses, electric vehicle components, and charging infrastructure, facilitating the global shift towards electrified mobility. Automotive OEMs in Germany and China are increasingly specifying copper content for their new EV platforms, accelerating this demand.
- Construction:Copper is used extensively in building wiring, plumbing, roofing, and architectural applications due to its durability and aesthetic properties. Urbanization trends in Southeast Asia continue to drive consistent demand from this sector.
- Electronics Manufacturing:This category encompasses printed circuit boards, semiconductors, and consumer electronics, requiring high-purity copper for signal transmission. The expanding telecommunications sector, particularly 5G deployment, fuels this demand.
The Construction sector maintains a substantial, established demand base. Electrical Equipment and Transportation Systems demonstrate the most dynamic expansion, reshaping traditional consumption patterns.
Mining Equipment Type:
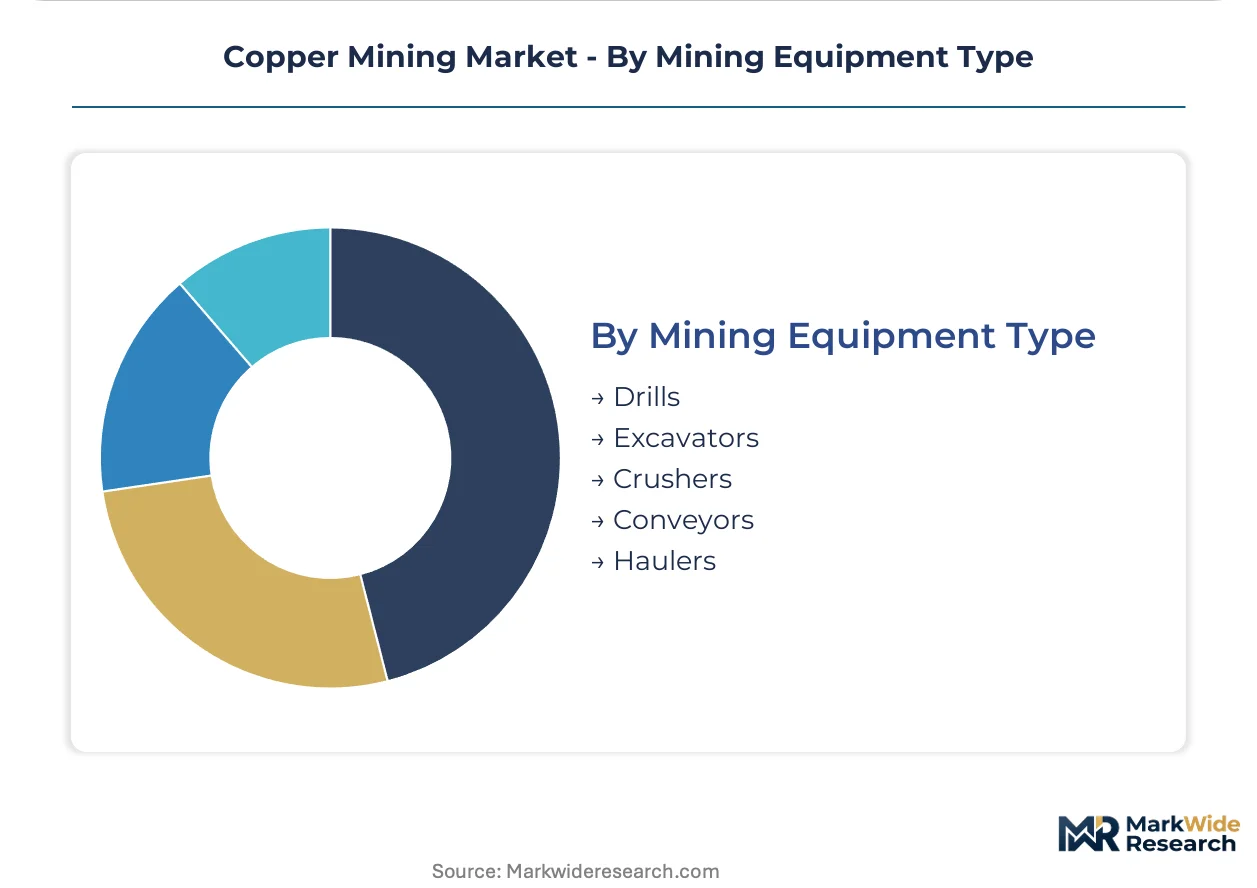
The operational scale and efficiency requirements drive the demand for specific mining equipment types. Large-scale open-pit mines in South America prioritize haulers and excavators for bulk material movement.
- Drills:These machines create blast holes for ore fragmentation in both open-pit and underground operations. Advanced drilling technologies improve precision and reduce energy consumption in Australian mines.
- Excavators:Large hydraulic shovels and excavators are used to load fragmented ore onto haul trucks in open-pit mines. Operators in the United States deploy advanced excavators for high-volume material handling efficiency.
- Crushers:Crushers reduce the size of mined ore to prepare it for further processing, such as grinding and flotation. Primary crushers are essential for handling large ore chunks at mine sites globally.
- Conveyors:Conveyor systems transport ore over long distances from the mine face to processing plants or stockpiles. These systems offer continuous material flow and reduce reliance on truck haulage.
- Haulers:Massive off-highway trucks transport ore and waste rock from the mine pit to crushers or waste dumps. Autonomous haulage systems are increasingly deployed in Chile to enhance safety and productivity.
Haulers form the bedrock of material movement in large-scale mining. Excavators are experiencing significant technological upgrades, driving efficiency gains across operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive port infrastructure along the Pacific coast underwrites South America's foundational role in global copper supply. This facilitates efficient export of raw and semi-processed materials to key manufacturing hubs. Regulatory frameworks and geological endowments significantly influence regional production capabilities and investment flows.
Chile
Demand from electric vehicle manufacturing and renewable energy infrastructure drives Chilean copper output. The country's stringent environmental impact assessments govern new mine developments. The Atacama Desert region concentrates vast porphyry deposits, supporting large-scale open-pit operations.
Australia
Urbanization in emerging economies and electronics manufacturing fuel Australian copper demand. Strict water usage regulations apply to mining operations, particularly in arid Western Australia. The Olympic Dam complex in South Australia is a major polymetallic VMS deposit, contributing significantly to national production.
Democratic Republic of Congo
Sediment-hosted deposits in the DRC meet substantial global copper demand. The national Mining Code regulates resource extraction and concession allocation. The Katanga region remains a critical area for high-grade copper production, attracting international investment.
United States
Electrical equipment and construction sectors provide consistent demand for copper in the United States. The US EPA enforces stringent rules on tailings management and water discharge. Arizona hosts large-scale porphyry operations, representing a significant portion of domestic output.
Canada
Polymetallic VMS deposits and advanced extraction technologies underpin Canadian copper production. Federal and provincial environmental regulations guide mine development and operational practices. British Columbia increasingly utilizes underground mining techniques to access deeper, higher-grade ore bodies.
Copper Mining Market Key Industry Players
Concentration sits with large, vertically integrated mining conglomerates that manage extensive global asset portfolios. The market exhibits a tiered structure, encompassing global diversified miners, state-owned national champions, and specialized mid-tier explorers. Dominant competitive moves include strategic capacity expansion and continuous investment in advanced extraction technologies. Many players also engage in strategic partnerships to de-risk large-scale resource development projects.
Global diversified miners like Freeport-McMoRan and BHP exemplify the extensive asset base required for large-scale copper extraction. These companies operate vast, geographically diverse assets, including major mines across the Americas, Australia, and Indonesia, enabling them to navigate commodity cycles effectively. Chile's state-owned Codelco represents a national champion, anchoring its country's world-leading copper output. Codelco leverages its deep domestic reserves and operational expertise to maintain a foundational supply position in the global market. Its strategic importance ensures long-term investment in national copper resources.
| Leading Market Players |
|---|
| Freeport-McMoRan |
| BHP |
| Codelco |
| Zijin Mining |
| Southern Copper |
| Glencore |
| Anglo American |
| KGHM Polska Miedź |
| Antofagasta |
Cost & Logistics Intelligence
Aluminum substitution for copper in specific electrical applications simultaneously reshapes supply geography and influences pricing economics for lower-grade copper. This dynamic requires producers to adapt their product offerings and distribution strategies to maintain market share against competing materials.
Pricing Analysis
A volume-discount tiering structure governs many long-term copper offtake contracts, reflecting the commodity nature of the metal. Price differentiation arises from the copper's quality grade, particularly for high-purity applications, and the certified low-carbon footprint demanded by European automotive OEMs. Upward pricing pressure stems from the sustained demand from the electric vehicle and renewable energy sectors. The construction sector remains the most price-sensitive buyer for bulk copper, while electronics manufacturers exhibit lower price sensitivity for specialized grades.
Supply Chain Analysis
Strategic stockpiling preferences characterize the copper mining supply chain, given long lead times for mine development and processing. Geographic supply concentration centers on Chile, the Democratic Republic of Congo, and Peru, which collectively provide a substantial portion of global output. The industry relies heavily on porphyry ores and critical processing inputs like sulfuric acid. Geopolitical instability in key producing regions represents a significant structural risk for global copper supply. Distribution runs through a combination of direct long-term contracts with smelters and refiners, alongside active trading on global commodity exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The copper market requires a robust substitution defense, as material science innovations continually introduce aluminum as a named substitute threat for certain electrical uses.
For Market Incumbents: Secure access to new, high-grade ore bodies through aggressive exploration and strategic acquisitions in regions like Canada and Indonesia. Invest in advanced extraction technologies, such as block caving and in-situ leaching, to maximize resource recovery from declining ore grades. Develop vertically integrated operations that include refining capabilities to capture more value. Prioritize ESG certifications and transparent supply chains to meet buyer demand for low-carbon copper, mitigating reputational threats.
For New Entrants and Emerging Players: A service-layer gap exists in providing certified, sustainably sourced copper to niche buyers. Target secondary processing innovation, focusing on advanced pyrometallurgical and hydrometallurgical recycling technologies for electronic waste. The certified low-carbon copper market, particularly for European automotive OEMs, offers the most penetrable segment for new supply. A direct partnership model with end-use manufacturers provides a strong go-to-market angle for these specialized products.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier miners facing capital expenditure intensity or social license to operate challenges. The long-term viability of copper demand remains robust, driven by the global energy transition over the next 5-10 years. Target acquisition profiles include companies with proven deep-ore reserves and established processing infrastructure in stable mining jurisdictions. Regulatory approvals for new large-scale copper projects serve as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New mine developments in South America secure future global copper supply. |
| Green Manufacturing Transition | Adoption of sustainable practices enhances market access for certified copper. |
| Long-term Supply Agreement | Securing stable copper volumes mitigates price volatility for industrial buyers. |
| Technology Licensing | Advanced extraction methods improve resource efficiency and reduce environmental impact. |
| Vertical Integration into Refining | In-house processing capabilities enhance control over product quality and cost. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Primary research involved discussions with mine operations managers, equipment procurement specialists, electric vehicle component manufacturers, and government regulators such as the US EPA. Secondary data sources included geological survey reports, national mining codes, company annual reports, and commodity exchange data, all triangulated to ensure accuracy.
The forecasting boundary established for this study encompasses the entire analysis window, modeling market dynamics over the projection horizon. Segmentation dimensions modeled include mining method, ore type, end-use industry, equipment type, and regional production capacity. Compound annual growth rates were derived from historical trends, coupled with future demand projections for electrification infrastructure and electric vehicles. Global electrification targets and EV production forecasts served as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal and US EPA mandates; material policy shifts would require re-modeling. The analysis reflects assumptions regarding global economic stability and continued investment in renewable energy infrastructure. Geopolitical instability in South America or rapid technological advancements in material science represent specific risk factors. Revision becomes warranted when significant changes in global economic growth or major new copper discoveries cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Frac Tree Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Australia Oil and Gas Midstream Market