
 Subsea Power Grid System Market | 2026-2036
Subsea Power Grid System Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Power Grid System Market Analytics
North Sea offshore wind build-out is fragmenting across competing transmission ownership models. Siemens Energy leverages integrated converter platform packages to anchor large-scale projects. Aker Solutions competes through subsea tieback expertise adapted for power distribution. Prysmian Group dominates high-voltage cable manufacturing with deepwater installation capabilities.
A subsea power grid system comprises wet-mate connectors, pressure-compensated switchgear, and dynamic umbilicals operating at depths exceeding 3,000 meters to transmit electricity across seabed environments. These systems enable remote power distribution to offshore oil platforms and wind turbine arrays without surface-based infrastructure. Submarine cables represent the most capital-intensive segment where margin pools concentrate around high-voltage direct current installations. DC power transmission technology leads growth due to lower losses over long-distance offshore routes compared with alternating current alternatives. Oil and gas end users remain a mature revenue base while renewable energy applications expand fastest.
DNV-ST-F203 and IEC 61892 govern subsea electrical equipment design, while Norway's Petroleum Safety Authority and the UK's Offshore Petroleum Regulator for Environment and Decommissioning enforce installation integrity standards. These frameworks mandate redundant protection systems and material traceability that extend procurement cycles but reduce operational failure risk. Stakeholders must monitor how floating offshore wind platform electrification reshapes voltage and connector specifications before committing to next-generation platform designs.
Market Dynamics
Offshore wind developers are consolidating procurement around integrated power-from-shore packages, compressing vendor selection timelines from 18 months to under 9 months as lease round deadlines tighten across European waters.
Growth Catalysts
- EU Green Deal auction mechanisms:Germany's offshore wind tendering now mandates grid-ready connection specifications that accelerate subsea cable deployment timelines for winning consortia.
- Floating platform electrification:Tension-leg and semi-submersible wind foundations require dynamic umbilical systems that expand addressable market scope beyond fixed-bottom installations.
- North Sea clustering effects:Shared transmission corridors between Denmark, the Netherlands, and Norway create procurement scale that reduces per-megawatt installation costs for bundled cable contracts.
Market Restraints
- Copper and XLPE resin volatility:Submarine cable manufacturing faces margin compression when commodity input costs spike, with limited pass-through clauses in multi-year EPC contracts.
- Installation vessel scarcity:Purpose-built cable-laying ships concentrate among Norwegian and Italian fleet operators, creating booking bottlenecks during peak construction windows.
- DNV-ST-F203 certification cycles:Pressure-compensated switchgear qualification requires 14-18 months of subsea testing that extends project financing drawdown schedules.
Strategic Opportunities
- US Atlantic lease expansion:Bureau of Ocean Energy Management auction rounds off Massachusetts and New Jersey lack mature supply chains, creating first-mover positioning for European cable manufacturers.
- Hydrogen platform integration:Offshore electrolyzer co-location with wind arrays demands higher-voltage subsea distribution architectures that retrofit existing turbine connections.
- Carbon border adjustment mechanisms:EU CBAM compliance requirements favor low-carbon cable production, advantaging manufacturers with renewable-powered smelting operations.
Industry Challenges
- Subsea electrical engineering talent pipelines:Deepwater power systems require hybrid skill sets spanning high-voltage engineering and marine hydrodynamics that university programs rarely combine.
- Legacy platform retrofit complexity:Brownfield oil and gas tie-ins must integrate with existing topside switchgear rated for alternating current, complicating direct current overlay architectures.
- Wet-mate connector standardization gaps:Proprietary interface designs from dominant suppliers lock operators into single-source maintenance contracts that inflate lifecycle costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Power Grid System Market |
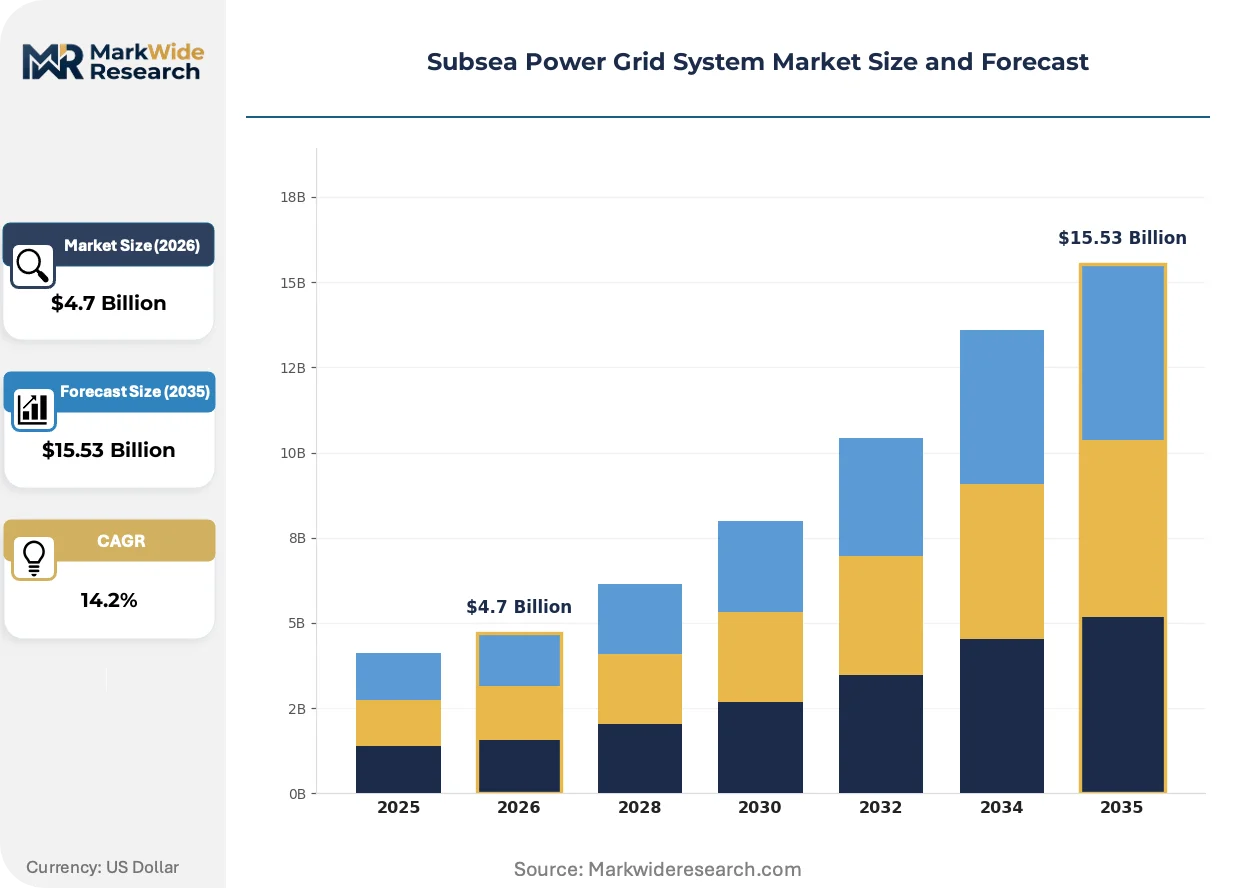
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submarine Cables, Transformers, Switchgear, Power Distribution Units Technology: AC Power Transmission, DC Power Transmission, Hybrid Systems, Control Systems End User: Utility Companies, Oil & Gas, Renewable Energy, Industrial Operators Application: Offshore Wind Farms, Oil Platforms, Marine Energy, Hybrid Power Systems |
| Companies Covered | Siemens Energy, NKT, ABB, Aker Solutions, TechnipFMC, Prysmian Group, General Electric, Subsea 7, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Power Grid System Market Evolving Landscape
Voltage level escalation and modular platform architectures are compressing installation schedules while forcing component suppliers to recertify products for harsher pressure and thermal cycling regimes.
Silicone-rubber insulated dynamic cables rated for 66 kilovolts are replacing traditional EPR-jacketed umbilicals in floating wind applications. Developers off Scotland and Portugal are specifying these systems for 25-year design lives without platform retrieval. The material's fatigue resistance under combined tension-torsion loading is rendering obsolete the armored steel wire configurations that dominated early demonstration projects.
The EU F-Gas Regulation's phase-down of sulfur hexafluoride is pressuring switchgear manufacturers to accelerate vacuum-interruptor designs for subsea pressure housings. Norway's Petroleum Safety Authority has signaled alignment with Brussels timelines, compressing product development cycles for equipment deployed after 2028. High-voltage direct current circuit breakers using alternative insulation media now dominate R&D roadmaps for cross-border interconnectors.
Long-term service agreements are unbundling from initial equipment supply as offshore wind asset owners build in-house subsea inspection capabilities. Danish and German utilities now procure cables and transformers separately from installation and maintenance contracts, reversing the integrated EPC model that characterized early sector development. This disaggregation is most advanced in the North Sea, where specialized vessel operators have captured standalone market positions.
Subsea Power Grid System Market Segmentation
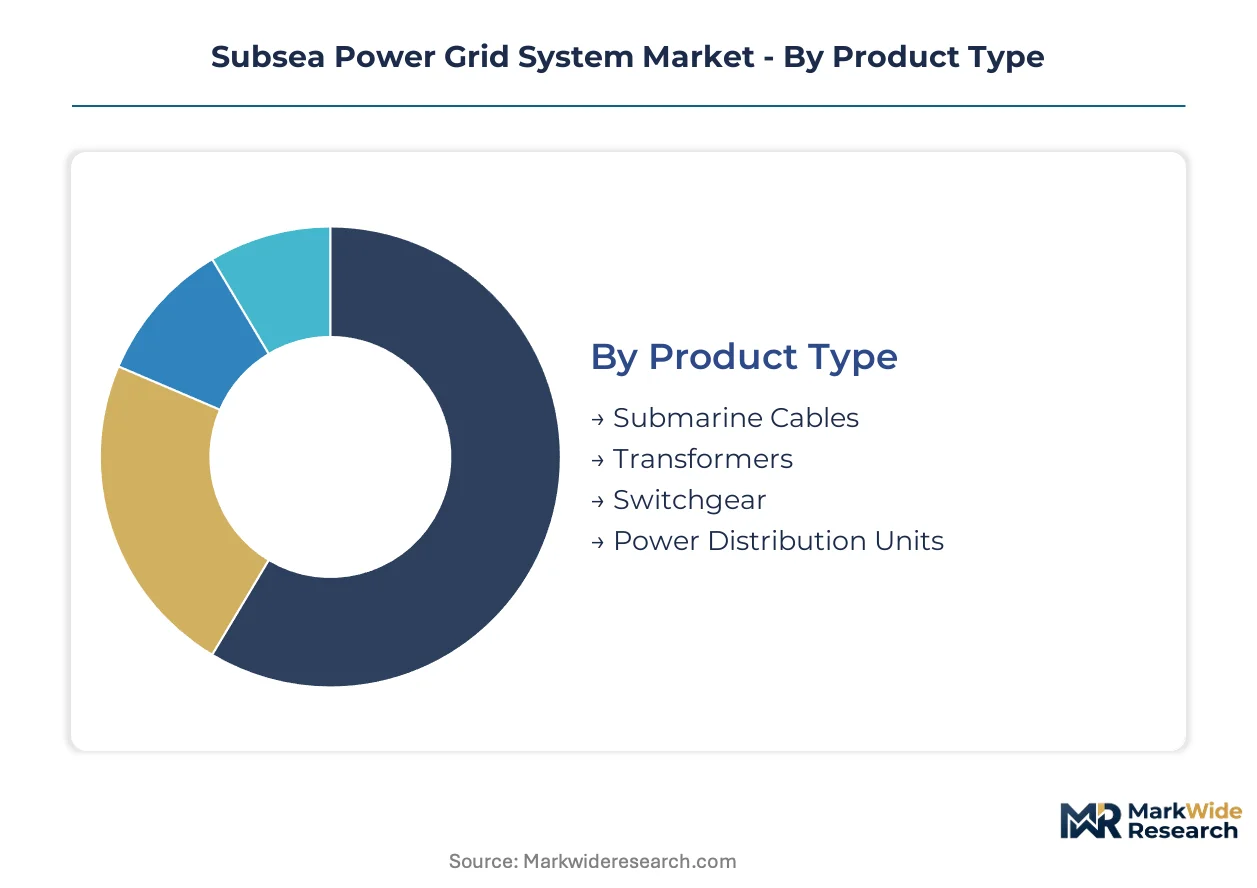
Subsea power grid procurement cycles vary dramatically by component type, with cable systems commanding 18-month lead times against 6-month turnaround for control electronics. Technology selection locks in decades of operational architecture, making early-stage segmentation decisions irreversible cost commitments for offshore developers.
Product Type:
Submarine cables turn over slowest due to capital intensity and installation complexity, while power distribution units refresh fastest through modular replacement strategies.
- Submarine Cables:Three-core XLPE-insulated conductors rated to 500 kilovolts form the backbone of inter-array and export circuits. Demand concentrates along the North Sea corridor where Germany's offshore wind auction winners bundle procurement across multi-gigawatt lease areas.
- Transformers:Oil-filled or dry-type units stepping voltage between collection and transmission levels require pressure-compensated housings for depths beyond 500 meters. Norway's oil platform electrification programs drive replacement cycles for aging AC infrastructure.
- Switchgear:Vacuum-interruptor assemblies housed in titanium or duplex steel enclosures withstand hydrostatic pressure at 3,000-meter depths. EU F-Gas Regulation timelines accelerate SF6-free qualification programs.
- Power Distribution Units:Modular skid-mounted assemblies integrate protection relays and monitoring systems for rapid platform deployment. Floating wind developers off Portugal specify these for tension-leg foundation integration.
Submarine cables dominate installed base. Power distribution units are where expansion concentrates.
Technology:
Cost tiering separates mature AC infrastructure from premium DC systems commanding 40-60% capital premiums for long-distance routes.
- AC Power Transmission:Alternating current systems using conventional copper or aluminum conductors serve distances under 80 kilometers with established supply chains. Brownfield oil platforms in the UK North Sea rely on AC for tieback economics.
- DC Power Transmission:Voltage-source converters enable efficient transmission beyond 100 kilometers with lower cable mass. Cross-border interconnectors between Denmark and Norway deploy these for offshore wind export.
- Hybrid Systems:AC-DC conversion platforms integrate multiple generation sources through unified switchgear architectures. Hybrid power systems in marine energy test sites demonstrate technical feasibility.
- Control Systems:Subsea monitoring and protection electronics enable remote fault isolation and predictive maintenance. These systems refresh fastest due to semiconductor obsolescence cycles.
AC transmission dominates installed base. DC transmission is climbing the fastest.
End User:
Customer type determines specification rigor, with utility procurement standards exceeding industrial operator requirements on material traceability and redundancy.
- Utility Companies:Grid operators mandate IEC 61892 compliance and 25-year design lives for subsea assets. German transmission system operators specify these standards for offshore wind connection points.
- Oil & Gas:Platform operators prioritize power-from-shore solutions to reduce offshore carbon emissions. Norway's Petroleum Safety Authority enforces electrification timelines for mature fields.
- Renewable Energy:Wind farm developers procure integrated cable and transformer packages under compressed lease round deadlines. Dutch auction mechanisms accelerate vendor selection timelines.
- Industrial Operators:Mining and desalination ventures deploy subsea power for remote coastal operations. These applications represent niche demand with customized voltage specifications.
Utility companies dominate installed base. Renewable energy developers are gaining share fastest.
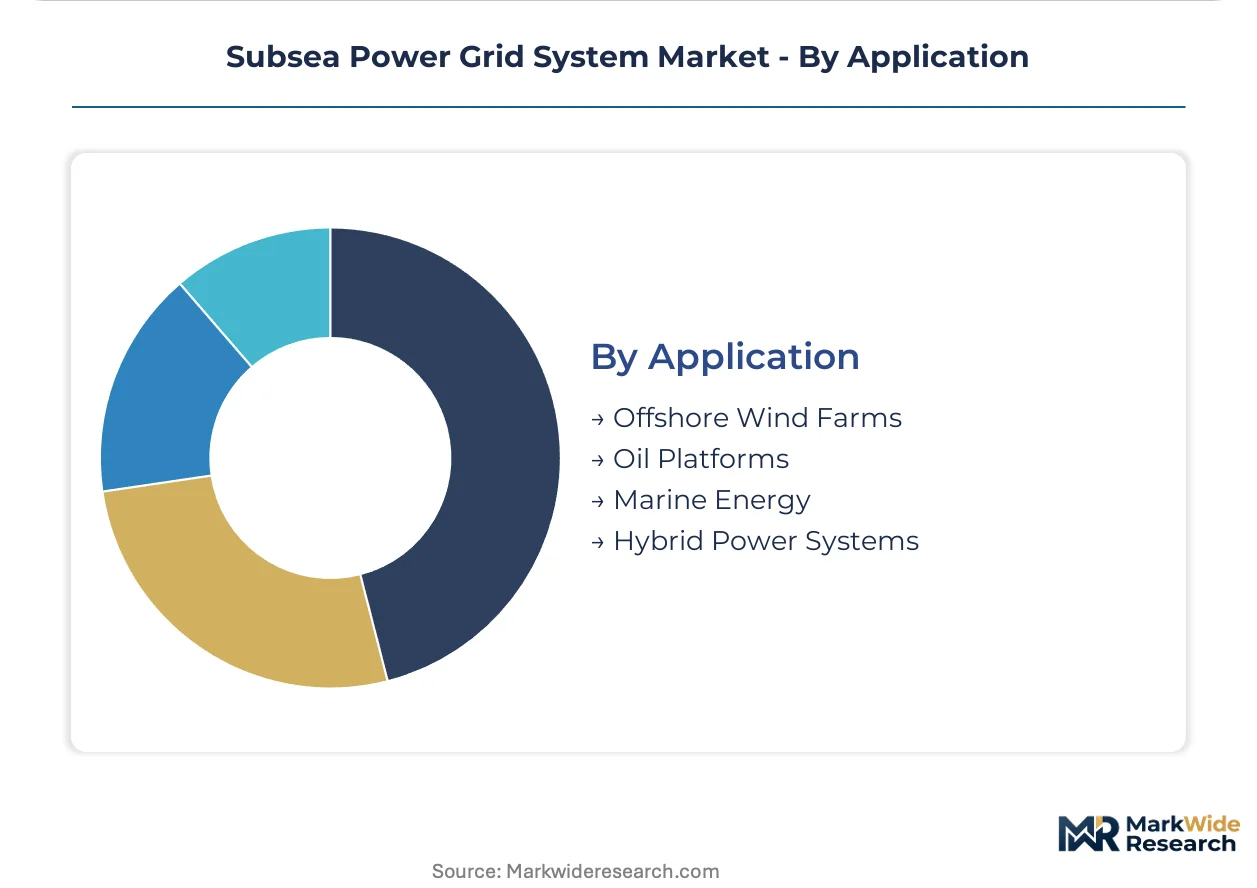
Application:
Volume concentration follows offshore wind build-out, while margin pools persist in oil platform retrofit complexity.
- Offshore Wind Farms:Inter-array cables linking turbines and export circuits to shore form the largest addressable volume. Clustered lease rounds in the North Sea create procurement scale for bundled contracts.
- Oil Platforms:Electrification of floating production units demands dynamic umbilical systems rated for combined wave-current loading. UK and Norwegian fields drive brownfield retrofit demand.
- Marine Energy:Tidal and wave energy converters require specialized power take-off systems with high fatigue resistance. Scotland's demonstration sites test commercial viability.
- Hybrid Power Systems:Co-located wind and hydrogen production platforms integrate electrolyzer loads with variable renewable output. These architectures demand higher-voltage distribution than standalone wind arrays.
Oil platforms dominate installed base. Offshore wind farms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsea cable manufacturing concentrates in Germany, Italy, and Norway where specialized vessel fleets and deepwater testing facilities cluster. Procurement scale follows offshore wind lease auctions along the North Sea corridor. Regulatory frameworks in Denmark and the Netherlands accelerate grid-connection timelines.
Germany
Offshore wind tendering mandates grid-ready specifications that compress vendor selection cycles. The Federal Network Agency enforces connection standards under the Wind Energy at Sea Act. Developers in the North Sea cluster bundle multi-gigawatt procurement across shared transmission corridors.
United Kingdom
Brownfield platform electrification drives demand for dynamic umbilical systems in mature North Sea fields. The Offshore Petroleum Regulator for Environment and Decommissioning enforces installation integrity standards. Aberdeen serves as the primary subsea engineering hub for North Sea tieback projects.
Norway
Power-from-shore programs for offshore oil platforms sustain transformer replacement cycles. The Petroleum Safety Authority mandates electrification timelines under field development plans. Stavanger hosts concentrated subsea equipment qualification and pressure-testing infrastructure.
Denmark
Cross-border interconnectors with Norway and Germany deploy high-voltage direct current systems for wind export. National energy policy prioritizes shared transmission infrastructure across clustered lease areas. Copenhagen anchors procurement coordination for bundled cable contracts.
Netherlands
Hollandse Kust auction mechanisms accelerate procurement timelines below nine months for winning consortia. The national offshore wind roadmap mandates standardized grid-connection specifications. Rotterdam functions as the primary cable load-out and installation staging port.
Subsea Power Grid System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base separates into consolidated cable manufacturers and fragmented switchgear suppliers. Three archetypes dominate: integrated energy conglomerates, subsea engineering contractors, and specialized cable fabricators. Competitive moves center on strategic partnerships for installation vessel access and portfolio diversification into floating wind components.
Within the integrated energy tier, Siemens Energy and ABB represent platform-scale system providers. Prysmian Group and Nexans occupy positions among specialized high-voltage cable fabricators. Aker Solutions exemplifies the subsea engineering contractor archetype with tieback adaptation capabilities.
| Leading Market Players |
|---|
| Siemens Energy |
| NKT |
| ABB |
| Aker Solutions |
| TechnipFMC |
| Prysmian Group |
| General Electric |
| Subsea 7 |
| Nexans |
| Others |
Value Network & Pricing Analysis
Stavanger's concentrated subsea testing infrastructure and pressure-compensated equipment qualification facilities grant Norwegian suppliers outsized pricing leverage over high-voltage transformer and switchgear contracts, particularly where DNV-ST-F203 certification timelines compress vendor selection windows for North Sea offshore wind developers.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across subsea electrical equipment, separating SF6-free vacuum-interruptor switchgear at premium levels from legacy sulfur hexafluoride systems facing accelerated phase-down. Price differentiation hinges on certification grade against IEC 61892 and material traceability depth demanded by German transmission system operators. Cost compression in standard AC cable tiers intensifies as copper and XLPE resin volatility outpaces indexation clauses in multi-year EPC contracts. Utility companies exhibit lowest price sensitivity given 25-year design life mandates, while industrial operators in remote coastal mining applications drive hardest bargain on customized voltage specifications.
Supply Chain Analysis
Copper cathode feedstock draws from Chilean and Indonesian smelting operations, with XLPE resin production anchored in German and Italian petrochemical corridors. Raw material dependencies extend to titanium and duplex steel forgings for pressure housings, plus silicone-rubber compounds for dynamic umbilical insulation. Single-source vulnerability concentrates around purpose-built cable-laying vessels operated by Norwegian and Italian fleet owners, creating booking bottlenecks during peak North Sea construction windows. Distribution runs through Rotterdam and Hamburg load-out ports for bundled contract staging to offshore wind lease areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across transmission ownership models and unbundling of long-term service agreements from initial equipment supply creates specialist niches for component vendors and standalone vessel operators alike.
For Market Incumbents: Insulate margin positions through captive control over installation vessel capacity in Norwegian and Italian fleets, while accelerating SF6-free switchgear qualification to capture EU F-Gas Regulation premiums before 2028 enforcement timelines compress. Siemens Energy and ABB should deepen backward integration into dynamic umbilical silicone-rubber compounding to offset commodity volatility pass-through limitations. For New Entrants and Emerging Players: US Atlantic lease areas off Massachusetts and New Jersey represent the most penetrable entry point for European cable manufacturers, given immature domestic supply chains and Bureau of Ocean Energy Management auction schedules lacking grid-ready specification mandates. Hydrogen platform integration architectures for offshore electrolyzer co-location offer second white-space avenue demanding higher-voltage distribution retrofit expertise. Go-to-market leverage rests on partnerships with specialized vessel operators for standalone installation and maintenance contracts disaggregated from EPC bundles. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-enabling play because subsea power grids constitute irreplaceable transmission layer for offshore wind scaling and oil platform electrification mandates regardless of generation technology shifts. Acquisition targets should display hybrid competencies spanning high-voltage engineering and marine hydrodynamics, with active DNV-ST-F203 qualification pipelines. Signal to monitor is floating offshore wind platform electrification specifications reshaping voltage and connector standards before next-generation designs crystallize.| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Capacity Expansion | Norwegian and Italian fleet operators capture standalone positions as service agreements unbundle from EPC contracts. |
| SF6-Free Switchgear Qualification | EU F-Gas Regulation alignment with Norway's Petroleum Safety Authority timelines compresses product development cycles. |
| Backward Integration into Silicone-Rubber Compounding | Dynamic umbilical suppliers offset copper and XLPE resin volatility through captive insulation material production. |
| US Atlantic Market Entry Partnerships | European cable manufacturers leverage Bureau of Ocean Energy Management auction gaps before domestic supply chains mature. |
| Hydrogen Platform Integration Development | Offshore electrolyzer co-location architectures demand higher-voltage distribution retrofitting existing turbine connections. |
Research Methodology
A standing panel of offshore wind project developers, subsea electrical engineering directors, cable procurement leads at German transmission system operators, and installation vessel fleet managers provided ongoing calibration across primary interview cycles, cross-referenced against DNV technical standards databases, IEC 61892 certification records, EU Green Deal auction mechanism filings, and national offshore wind roadmap documents from Germany, Denmark, and the Netherlands. Bottom-up component demand aggregation and top-down market sizing triangulated volume estimates.
Scenario-bracketing around commodity input volatility, installation vessel availability constraints, and regulatory phase-down timelines bounded high and low growth paths across the projection horizon. Segmentation dimensions modeled include product type, transmission technology, end-user archetype, and application, with voltage level escalation and platform architecture modularity treated as cross-cutting demand shapers. CAGRs derived from fitted growth curves anchored to disclosed procurement timelines and lease round schedules.
Stress conditions across copper and XLPE resin price bands, vessel booking bottlenecks, and DNV-ST-F203 certification cycle extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions regarding EU Green Deal auction mechanism continuity and floating offshore wind commercialization pace. Cross-checking against disclosed EPC contract values and transmission system operator capex plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Australia Thermal Power Market
Power Generation
Variable Speed Generator Market
Power Generation
Cogeneration System Market
Power Generation
Global Power Grid System Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Third Generation Energy Sources Market
Power Generation
Peaking Power Plant Market
Power Generation
Solar Generator Market
Power Generation
India Gensets Market
Power Generation
Global Gas Turbines Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Power Plant EPC Market
Power Generation
Distributed Generation Market
Power Generation
Algeria Power Market