
 Microturbine Market | 2026-2036
Microturbine Market Size, Share, and Industry Trends Forecast 2026-2036
Microturbine Market Analysis
Specialized turbomachinery engineering talent is rotating toward distributed energy OEMs as utility-scale turbine manufacturers downsize hiring. Capstone Green Energy Corporation leverages its California manufacturing base to sustain aftermarket parts revenue across installed fleets. FlexEnergy Solutions anchors its position through fuel-flexible architectures that compete across biogas and associated gas applications. Ansaldo Energia S.p.A. differentiates via European service networks that dominate long-term maintenance contracts.
A microturbine is a compact gas turbine generator typically rated below 500 kW, employing a single-stage radial compressor and turbine mounted on a shared shaft with an air-bearing-supported high-speed alternator operating at rotational speeds exceeding 50,000 RPM. These systems convert gaseous or liquid fuels into electricity and usable thermal energy through combined heat and power configurations for commercial buildings, industrial facilities, and remote installations. Natural gas product types occupy the largest installed base due to pipeline infrastructure availability, while hydrogen configurations represent the fastest-growing product category as utilities pilot green fuel integration. Industrial end users command the deepest margin pools through multi-unit installations requiring comprehensive service contracts spanning maintenance and remote monitoring.
The US EPA enforces stationary source performance standards that constrain NOx and CO emissions from microturbine installations, while California's South Coast Air Quality Management District imposes additional localized restrictions that shape product certification requirements. The EU F-Gas Regulation and CE marking directives govern equipment import and refrigerant cycle integration for European deployments. Stakeholders must monitor evolving hydrogen blending standards and carbon intensity accounting rules that will determine fuel eligibility for clean energy incentives.
Market Dynamics
EPA stationary source emissions standards are compressing NOx thresholds for sub-megawatt combustion systems, forcing OEMs to redesign recuperator architectures and fuel injection systems while oil and gas operators accelerate procurement for flared gas-to-power projects across remote wellhead sites.
Growth Catalysts
- Texas and North Dakota shale development:Associated gas flaring regulations are compelling operators to deploy compact dispatchable units at remote wellhead locations for on-site power generation.
- Hydrogen blending infrastructure:Pilot programs for green fuel integration are expanding addressable applications beyond pipeline natural gas into renewable hydrogen configurations.
- Combined heat and power mandates:Building efficiency codes in multiple jurisdictions are driving commercial and industrial facilities toward cogeneration architectures.
Market Restraints
- Air-bearing manufacturing concentration:Precision high-speed alternator component supply concentrates among limited specialized turbomachinery suppliers, creating single-source vulnerability.
- Recuperator alloy cost volatility:Nickel-based superalloy prices fluctuate with aerospace and power generation sector demand cycles, compressing margin predictability.
- Solar-plus-battery substitution:Declining lithium-ion storage costs and photovoltaic efficiency gains are displacing microturbines in sub-500kW commercial building applications.
Strategic Opportunities
- Biogas and landfill gas expansion:Agricultural waste digesters and municipal solid waste facilities represent underpenetrated deployment opportunities for fuel-flexible architectures.
- European service network gaps:Long-term maintenance contract coverage remains uneven across Eastern European industrial corridors, creating white space for technical service expansion.
- Data center resilience requirements:Hyperscale computing facilities are evaluating microturbines for islanded backup power to supplement diesel generator fleets.
Industry Challenges
- Radial compressor aerodynamics expertise:Specialized turbomachinery engineering talent shortages are extending product development timelines as utility-scale turbine manufacturers compete for the same labor pool.
- California SCAQMD certification complexity:Localized air quality management district requirements layer additional testing protocols atop federal EPA standards, lengthening approval cycles for new product introductions.
- Legacy SCADA integration friction:Industrial end users face interoperability challenges connecting high-speed alternator control systems with existing facility management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microturbine Market |
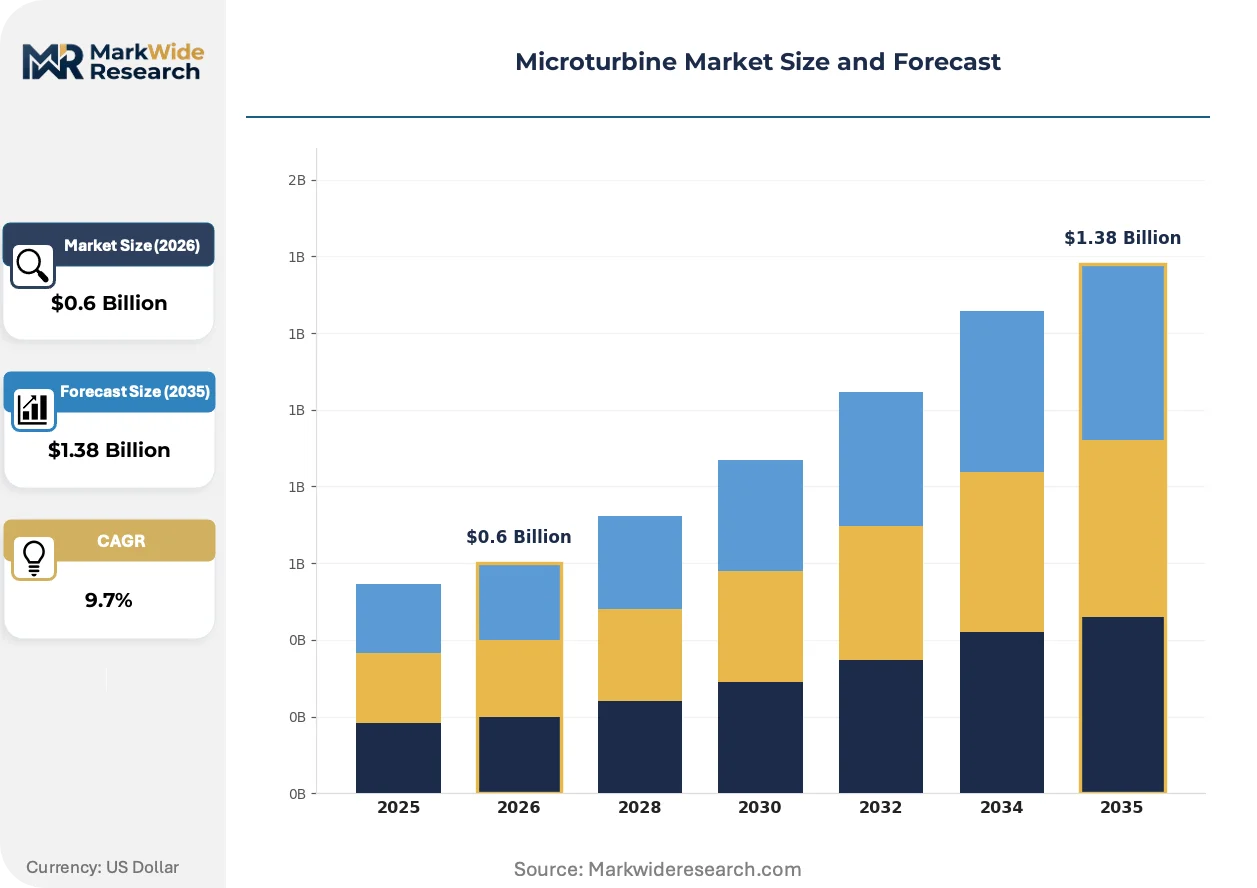
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.38 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gas, Diesel, Biogas, Hydrogen End User: Industrial, Commercial, Residential, Military Service Type: Maintenance, Installation, Consulting, Remote Monitoring Installation: Distributed Generation, Standalone, Grid Connected, Hybrid |
| Companies Covered | Capstone Green Energy Corporation, FlexEnergy Solutions, Ansaldo Energia S.p.A., Brayton Energy LLC, Bladon Micro Turbine, Aurelia Turbines Oy, MTT Microturbine, ICR Turbine Engine Corporation, Bowman Power Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microturbine Market Emerging Trajectories
Product architectures are diverging between premium fuel-flexible systems and standardized natural gas units as regulatory pressure and application diversity reshape competitive positioning across the value chain.
Recuperator technology is bifurcating between conventional metallic designs and advanced ceramic matrix composites that tolerate higher turbine inlet temperatures. Aerospace suppliers are transferring ceramic manufacturing processes to stationary power applications at accelerating rates. This materials transition is compressing thermal efficiency gaps between microturbines and larger industrial gas turbines in distributed generation ratings.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing redesigns of heat recovery systems that previously relied on conventional refrigerant cycles. Equipment manufacturers must now certify alternative thermal transfer fluids or abandon combined cooling configurations entirely. European import and CE marking compliance costs are rising fastest for product lines targeting commercial building HVAC integration.
Industrial buyers are consolidating vendor relationships through comprehensive service contracts that bundle remote monitoring, predictive maintenance, and parts replacement into long-term agreements. Traditional equipment-only transactions are retreating to smaller commercial building segments. This preference compression is most visible across Texas and North Dakota oilfield services procurement, where operators prioritize uptime guarantees over capital expenditure minimization.
Microturbine Market Segmentation
Microturbine procurement patterns diverge sharply across fuel types, end-use applications, and service arrangements. EPA emissions thresholds and state-level air quality mandates reshape competitive positioning within each segment category.
Product Type:
EPA stationary source standards and California SCAQMD thresholds create divergent certification burdens across fuel chemistries.
- Natural Gas:Pipeline infrastructure availability anchors the largest installed base. Demand concentrates in Texas and North Dakota shale basins where flared gas-to-power projects require compact dispatchable units at remote wellhead sites.
- Hydrogen:Green fuel integration pilots are expanding addressable applications beyond conventional natural gas. Utilities in California and European industrial clusters are advancing hydrogen blending standards that determine fuel eligibility for clean energy incentives.
- Diesel:Backup power applications in military and critical infrastructure settings sustain residual demand despite emissions penalties.
- Biogas:Agricultural waste digesters and landfill gas facilities represent underpenetrated deployment opportunities for fuel-flexible architectures.
Established volume favors Natural Gas; emerging adoption favors Hydrogen.
End User:
Margin depth and contract complexity separate industrial procurement from smaller-scale deployments.
- Industrial:Multi-unit installations command the deepest margin pools through comprehensive service contracts spanning maintenance and remote monitoring. Oil and gas operators across remote wellhead sites accelerate procurement for on-site power generation with uptime guarantees prioritized over capital expenditure minimization.
- Commercial:Combined heat and power mandates in building efficiency codes drive cogeneration architectures. Solar-plus-battery substitution is displacing microturbines in sub-500kW applications as lithium-ion storage costs decline.
- Residential:Limited penetration due to scale economics and interconnection complexity.
- Military:Islanded backup power requirements sustain diesel-configured procurement despite regulatory pressure.
Industrial buyers consolidate vendor relationships through bundled long-term agreements; commercial segments retreat toward equipment-only transactions.
Service Type:
Revenue predictability shifts toward recurring service models as hardware margins compress.
- Maintenance:Long-term contracts dominate Texas and North Dakota oilfield services procurement. European service networks remain uneven across Eastern European industrial corridors.
- Remote Monitoring:Predictive maintenance capabilities differentiate competitive positioning. Industrial end users face interoperability challenges connecting high-speed alternator control systems with existing facility management platforms.
- Installation:Project-based revenue with lower recurrence than service contracts.
- Consulting:Fuel assessment and site optimization for biogas and hydrogen integration projects.
Maintenance captures the most stable revenue streams; remote monitoring climbs the fastest as digitalization penetrates industrial facilities.
Installation:
Grid interconnection standards and resilience requirements shape deployment architecture selection.
- Distributed Generation:On-site power generation at remote wellhead locations drives procurement across Texas and North Dakota shale development. Associated gas flaring regulations compel operator deployment of compact dispatchable units.
- Hybrid:Data center resilience requirements are prompting hyperscale computing facilities to evaluate microturbines for islanded backup power supplementing diesel generator fleets.
- Standalone:Off-grid applications in remote industrial and military settings.
- Grid Connected:Net metering and export tariff structures influence commercial building economics.
Distributed Generation holds the deepest installed base; Hybrid configurations gain share fastest from data center reliability investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stationary source standards anchor procurement patterns in the United States, while EU F-Gas Regulation and hydrogen blending pilots reshape European deployment trajectories. Demand concentrates in shale basins and industrial corridors where emissions compliance intersects with distributed generation economics.
United States
Texas and North Dakota shale operators accelerate microturbine procurement for flared gas-to-power projects at remote wellhead sites. EPA stationary source performance standards constrain NOx thresholds for sub-megawatt combustion systems, forcing design adaptations. California's South Coast Air Quality Management District imposes additional localized restrictions that lengthen product certification cycles for OEMs targeting the Los Angeles industrial basin.
Germany
Industrial facilities in the Ruhr and Bavarian manufacturing corridors evaluate fuel-flexible architectures for biogas integration from agricultural waste digesters. EU F-Gas Regulation restrictions on fluorinated greenhouse gases force heat recovery system redesigns away from conventional refrigerant cycles. The country's national energy regulator monitors hydrogen blending standards that will determine eligibility for clean energy incentives in pilot clusters.
China
Dual carbon goals drive pilot programs for distributed generation in industrial zones seeking to reduce grid dependency. The Ministry of Ecology and Environment enforces emissions standards that shape certification requirements for sub-megawatt combustion equipment. Yangtze River Delta manufacturing hubs concentrate procurement for combined heat and power configurations in commercial building efficiency retrofits.
United Kingdom
Data center operators in the London metropolitan area and Slough corridor evaluate microturbines for islanded backup power to supplement diesel generator fleets. The national environmental regulator enforces stationary source emissions frameworks that align with EU-derived standards. Midlands industrial clusters sustain demand for maintenance-contract bundled procurement across multi-unit installations.
Canada
Remote mining and oil sands operations in Alberta deploy standalone configurations for off-grid power generation in sub-arctic conditions. Health Canada and Environment and Climate Change Canada administer emissions standards for stationary combustion systems. Ontario manufacturing corridors around Toronto concentrate commercial building cogeneration installations driven by provincial building efficiency mandates.
Microturbine Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the microturbine value chain. The vendor base organizes into three tiers: fuel-flexible system specialists commanding premium positioning, standardized natural gas unit fabricators competing on installed cost, and regional service providers capturing aftermarket revenue through maintenance contracts. Two dominant competitive moves are reshaping positioning: aerospace suppliers transferring ceramic matrix composite manufacturing processes to stationary power applications, and industrial buyers consolidating vendor relationships through comprehensive long-term service agreements that bundle remote monitoring and predictive maintenance.
Among North American OEMs, Capstone Green Energy Corporation exemplifies the vertically integrated archetype with California-based manufacturing sustaining aftermarket parts revenue across installed fleets. FlexEnergy Solutions occupies a position within the fuel-flexible tier, competing across biogas and associated gas applications. Ansaldo Energia S.p.A. represents the European service-network archetype, anchoring long-term maintenance contract coverage across Western European industrial corridors.
| Leading Market Players |
|---|
| Capstone Green Energy Corporation |
| FlexEnergy Solutions |
| Ansaldo Energia S.p.A. |
| Brayton Energy LLC |
| Bladon Micro Turbine |
| Aurelia Turbines Oy |
| MTT Microturbine |
| ICR Turbine Engine Corporation |
| Bowman Power Group Ltd. |
| Others |
Supply Flow & Price Mechanics
Ceramic matrix composite substitution for nickel-based superalloys in recuperator manufacturing is simultaneously shifting supply geography toward aerospace-tier suppliers and compressing thermal efficiency premiums that once commanded pricing power. This materials transition rewards OEMs with captive aerospace relationships while pressuring pure-play stationary power fabricators facing alloy cost volatility and extended lead times for precision castings.
Pricing Analysis
North American installed costs for fuel-flexible units run 15-25% above standardized natural gas configurations in European industrial corridors. Three-tier pricing structure across premium, standard, and economy levels separates hydrogen-ready architectures from conventional pipeline gas units from refurbished fleet equipment. Cost compression in the standard tier is intensifying because solar-plus-battery substitution is eroding commercial building addressable market. Industrial oilfield buyers exhibit lowest price sensitivity due to uptime guarantee requirements, while commercial cogeneration developers face acute capital constraint pressure.
Supply Chain Analysis
Inventory cycles for air-bearing-supported alternators now stretch 26-32 weeks, constraining OEM delivery commitments and amplifying order backlog volatility. Precision component manufacturing concentrates in the United States, Germany, and Japan, drawing from nickel-based superalloy feedstock, ceramic matrix composite preforms, and high-speed power electronics. Single-source vulnerability pervades the air-bearing segment where two specialized turbomachinery suppliers dominate global capacity. Distribution runs through direct OEM sales forces for industrial multi-unit installations and authorized service networks for aftermarket parts fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote monitoring and predictive maintenance attach rates are expanding faster than hardware unit shipments, transforming vendor economics toward recurring revenue models. This service-layer acceleration favors players with installed fleet scale and digital platform maturity.
For Market Incumbents: Shield aftermarket parts revenue through captive California and Texas service hub expansion, countering European service network challengers entering North American shale basins. Deepen backward integration into ceramic matrix composite recuperator manufacturing to capture margin migrating from alloy suppliers. Prioritize hydrogen blending certification investment ahead of California SCAQMD and EU standard finalization. For New Entrants and Emerging Players: Remote monitoring interoperability gaps in legacy SCADA integration present the most penetrable white space for software-native challengers. Eastern European industrial corridors remain unevenly covered by long-term maintenance contracts, offering service-only entry without manufacturing scale. Pursue data center islanded backup power pilots as the fastest route to referenceable hyperscale deployments. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors fuel-flexible system specialists with hydrogen certification pipelines. Long-term viability hinges on regulatory durability of flared gas-to-power economics and carbon intensity accounting rules for clean energy incentives. Watch hydrogen blending standard ratification velocity as the primary inflection indicator for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Bundling | Industrial buyers in Texas and North Dakota prioritize uptime guarantees over capital expenditure minimization. |
| Ceramic Recuperator Manufacturing | Aerospace process transfer compresses thermal efficiency gaps with larger industrial gas turbines. |
| Hydrogen Certification Investment | California SCAQMD and EU blending standards determine fuel eligibility for clean energy incentives. |
| Remote Monitoring Platform Development | Predictive maintenance capabilities differentiate competitive positioning in industrial facility digitalization. |
| Eastern European Service Expansion | Long-term maintenance contract coverage remains uneven across industrial corridors from Poland to Romania. |
Methodological Framework
Operator-level perspectives from oilfield services procurement directors, distributed generation project developers, EPC contractors, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EPA stationary source filings, FERC interconnection queues, EIA distributed generation databases, and EU ETS carbon intensity registries. Bottom-up unit deployment tracking triangulated against top-down OEM revenue aggregation across the analysis window.
Sensitivity analysis tested forecast robustness across nickel superalloy price scenarios, hydrogen blending adoption curves, and solar-plus-battery substitution rates. The analytical framework modeled fuel type, end-use application, service arrangement, and installation architecture segmentation throughout the forecast period. CAGRs derived from unit shipment trajectories weighted by regional emissions compliance stringency and pipeline infrastructure availability. Forecast inputs incorporated shale development rig counts and data center power demand projections.
Material uncertainties — regulatory revision to EPA NOx thresholds, EU F-Gas Regulation enforcement intensity, and hydrogen infrastructure buildout pace — sit outside the modeled envelope. Forecasts reflect assumptions regarding emissions standard durability and clean energy incentive continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Hydrogenerators Market
Power Generation
Residential Solar Generator Market
Power Generation
Gas Fired Power Plant Market
Power Generation
South America Thermal Power Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Power Plant EPC Market
Power Generation
LAMEA Microturbine Market
Power Generation
South East Asia Power Market
Power Generation
Stirling Engine Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Cogeneration System Market
Power Generation
Industrial Solar Generator Market
Power Generation
Distributed Power Generation Market