
 Solar Freezer Market | 2026-2036
Solar Freezer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Freezer Market Analysis
Market Context
Multi-source procurement of photovoltaic modules and DC compressors is broadening as assemblers reduce dependence on single-country supply. Dometic leverages its automotive cooling heritage to dominate portable freezer segments in recreational and emergency applications. B Medical Systems anchors medical-grade solar cold chain deployments across WHO-backed immunization programs. Kyocera sustains its position through captive solar panel production that insulates margins from polysilicate volatility.
Technical Definition and Segment Structure
A solar freezer is a thermally insulated cabinet that uses photovoltaic-generated electricity to drive a DC compressor, maintaining temperatures between minus 18 degrees Celsius and minus 25 degrees Celsius for biological sample and food preservation without grid connection. Chest freezer configurations lead unit shipments due to superior cold retention during cloudy intervals, while upright formats command margin premiums from healthcare and retail buyers prioritizing inventory accessibility. Photovoltaic-dominant systems occupy the largest technology share, though hybrid configurations pairing solar with thermal energy storage represent the fastest-expanding category for multi-day autonomy in equatorial regions with inconsistent irradiance.
Regulatory Environment
WHO Performance Quality and Safety standards govern medical solar freezer eligibility for Gavi-funded procurement, while EPA refrigerant phase-down rules under the AIM Act push manufacturers toward R600a and R290 hydrocarbon alternatives. FDA 21 CFR Part 211 cold chain guidelines extend to off-grid pharmaceutical storage, creating compliance barriers for uncertified entrants. Stakeholders must monitor evolving national renewable energy agency subsidy eligibility criteria that increasingly tie off-grid appliance financing to local assembly requirements.
Market Dynamics
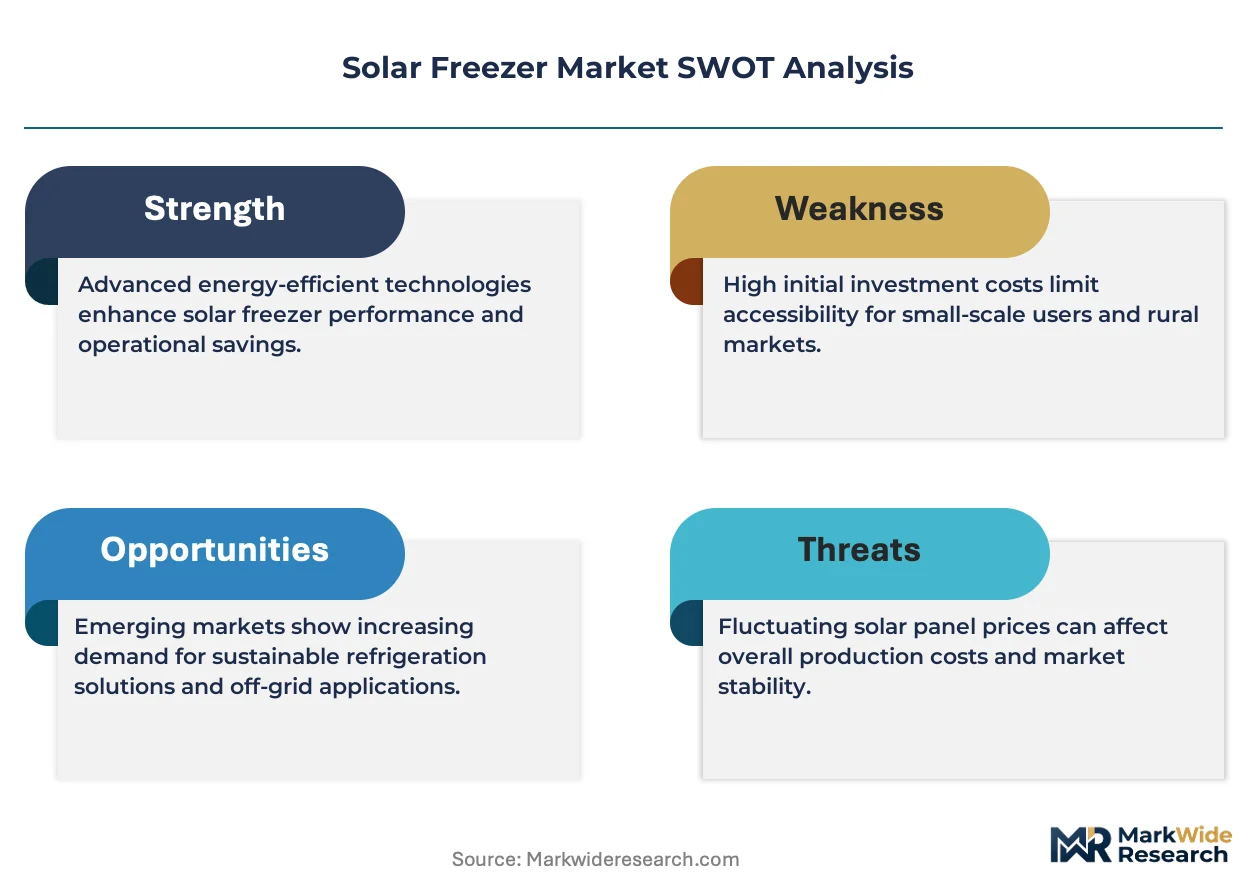
The solar freezer market pivots on lithium iron phosphate battery cost deflation, which is compressing total system pricing and eroding the diesel-generator alternative across off-grid healthcare and agricultural cold chains.
Growth Catalysts
- WHO Performance Quality and Safety standards:Gavi-funded procurement mandates for vaccine cold chains are pulling medical-grade solar freezer deployments into sub-Saharan Africa.
- Rural electrification gaps:Persistent grid unreliability in Kenya, Nigeria, and India is forcing healthcare ministries toward autonomous solar refrigeration for biological sample preservation.
- DC compressor efficiency gains:Permanent magnet motor advances are cutting energy draw per cooling degree, shrinking photovoltaic array sizing requirements for equatorial installations.
Market Restraints
- Polysilicate price volatility:Photovoltaic module input costs swing with Chinese metallurgical-grade silicon supply, compressing assembler margins during contract bidding.
- Refrigerant transition friction:EPA AIM Act phase-downs of hydrofluorocarbons are forcing retooling toward R600a and R290 hydrocarbon alternatives, extending certification timelines.
- Battery supply concentration:Lithium iron phosphate cell production clusters in China, exposing procurement to export license unpredictability and tariff exposure.
Strategic Opportunities
- Hybrid thermal storage convergence:Phase-change material integration with photovoltaic arrays is enabling multi-day autonomy in equatorial regions with inconsistent irradiance.
- Last-mile pharmaceutical distribution:Community health worker networks in rural India are creating demand for sub-50-liter portable solar freezers for temperature-sensitive biologics.
- CE marking pathway expansion:EU Green Deal financing instruments are opening subsidized procurement channels for solar cold chain infrastructure in Mediterranean agricultural zones.
Industry Challenges
- Certification timeline compression:FDA 21 CFR Part 211 cold chain guideline compliance for off-grid pharmaceutical storage is extending product validation cycles beyond 18 months.
- Field service capability scarcity:Photovoltaic-battery-refrigeration tri-skilled technician pools remain thin in target deployment geographies, constraining warranty fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Freezer Market |
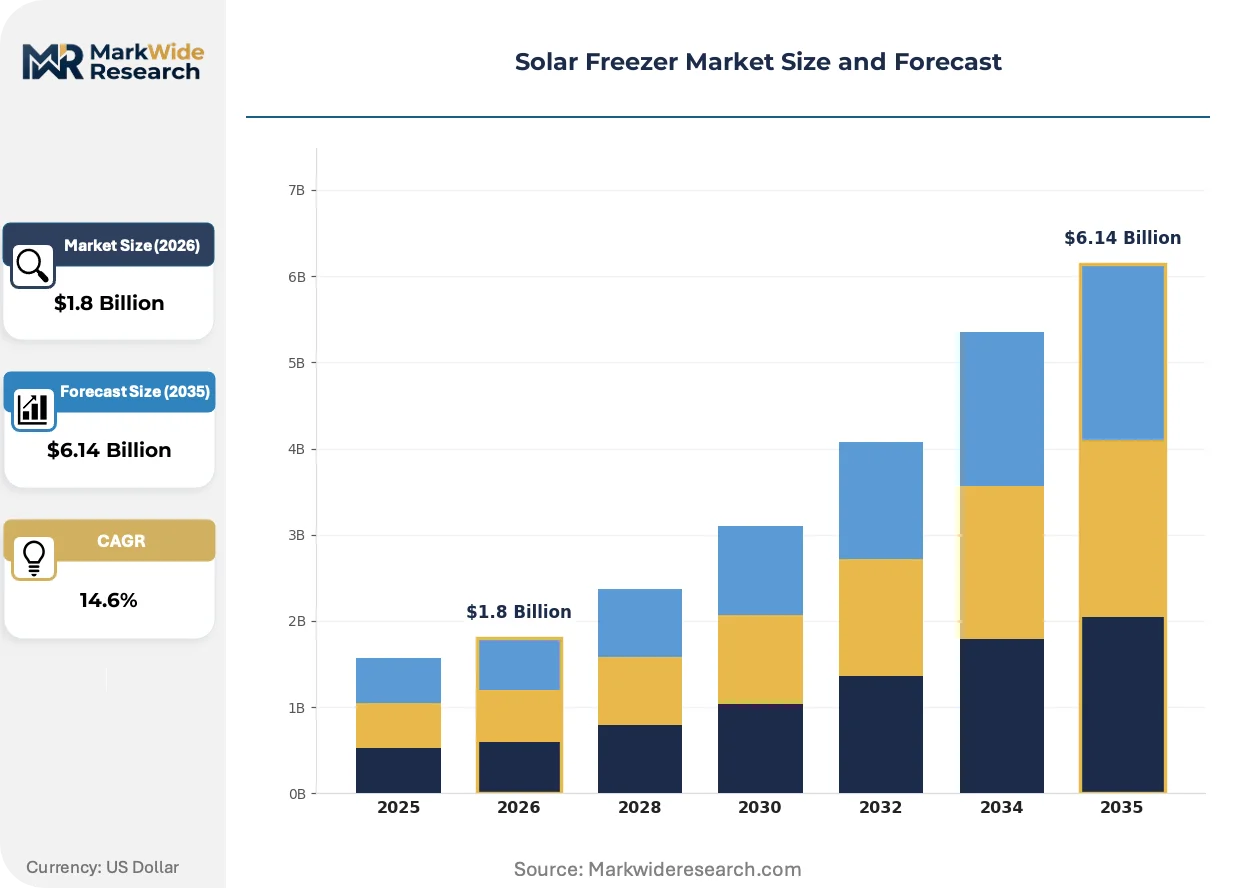
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Freezer, Chest Freezer, Upright Freezer, Solar Refrigerator End User: Households, Restaurants, Grocery Stores, Emergency Services Technology: Photovoltaic, Thermal Energy Storage, Hybrid Systems, Direct Current Application: Food Preservation, Medical Storage, Disaster Relief, Outdoor Events |
| Companies Covered | B Medical Systems, Connexa Energy, Dometic, DULAS, ECOSOLARCOOL, SUNDANZER, Kyocera, EcoFlow, Engel Coolers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Freezer Market Emerging Trajectories
Active materials research and procurement model restructuring are reshaping competitive positioning. Technology convergence between energy storage and thermal management is compressing system footprints. Regulatory refrigerant mandates are accelerating hydrocarbon adoption curves.
Phase-change materials are integrating into solar freezer architectures as latent heat buffers, absorbing daytime photovoltaic surplus and releasing cooling energy during nocturnal or cloudy intervals. Off-grid healthcare facilities in malaria-endemic regions are adopting these systems to maintain vaccine potency through multi-day grid failures. This thermal-electric hybridization is integrating battery-free autonomy into medical cold chain specifications, displacing pure electrochemical storage in equatorial deployments.
The EPA AIM Act refrigerant phase-down is mandating transition from R134a and R404A toward R600a and R290 hydrocarbon alternatives with lower global warming potential. Solar freezer assemblers are reconfiguring compressor architectures and safety systems to accommodate flammable refrigerants, extending engineering validation timelines. Medical-grade product lines face the steepest compliance burden, as WHO Performance Quality and Safety standards layer atop EPA mandates for Gavi-eligible procurement.
Aggregated procurement consortia are displacing single-facility purchasing across sub-Saharan health ministries, consolidating demand into multi-year framework agreements with performance guarantees. National medical store operators in Kenya and Nigeria are centralizing solar freezer acquisition, shifting vendor relationships from transactional spot buys toward outcome-based service contracts. This buyer concentration is compressing supplier margins while extending contract tenures and locking out uncertified regional assemblers.
Solar Freezer Market Segmentation
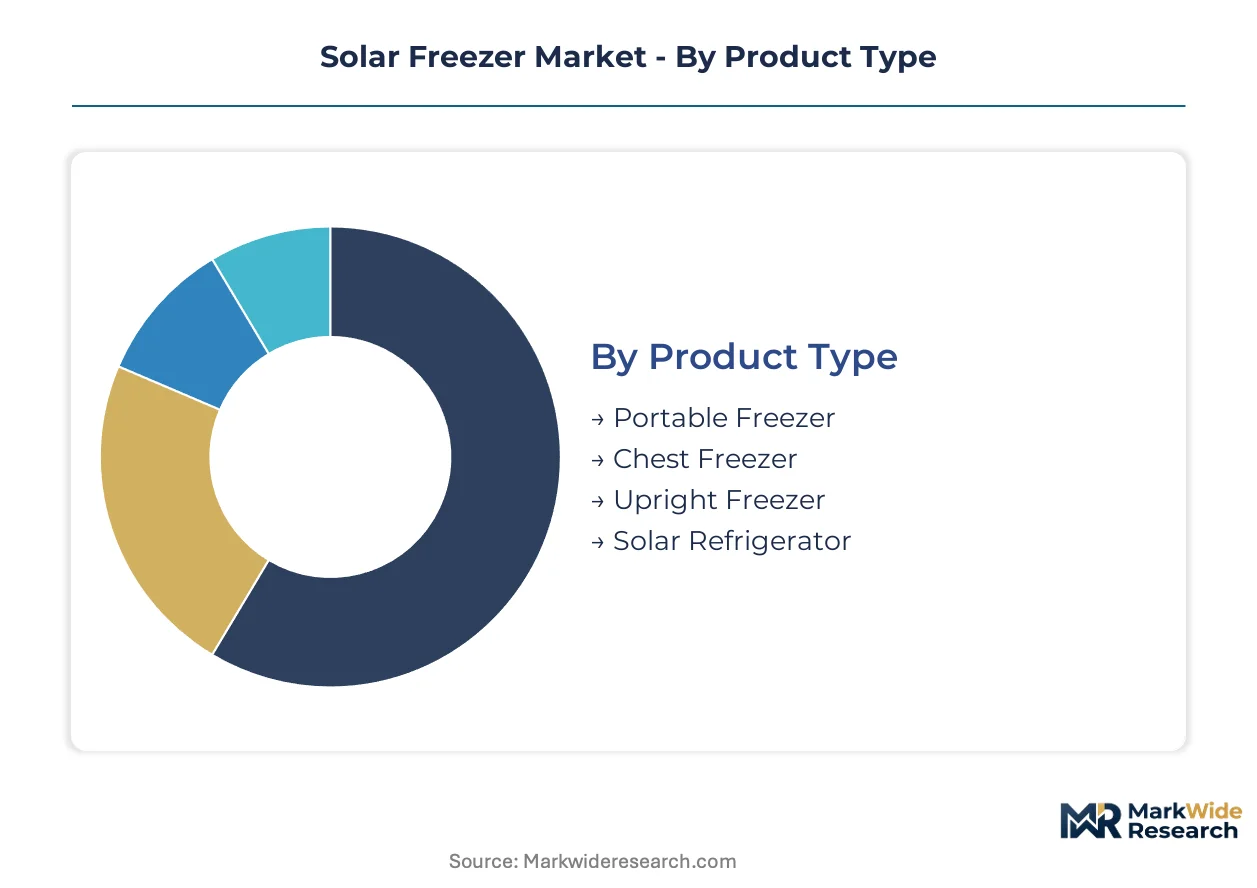
Solar freezer procurement patterns diverge sharply across use cases, with medical cold chain deployments demanding certified upright configurations while agricultural and emergency applications favor portable and chest formats. Segment-level technology choices determine total cost of ownership and autonomy duration in off-grid environments.
Product Type:
Replacement cycles in solar freezer fleets vary from five years for portable units in humanitarian logistics to twelve years for institutional chest freezers in rural health facilities.
- Chest Freezer:Horizontal cabinet geometry with top-opening lids minimizes cold air loss during access, making these units dominant in vaccine distribution networks across Kenya and Nigeria. WHO Performance Quality and Safety certification requirements concentrate procurement toward medically validated chest configurations for sub-Saharan immunization programs.
- Upright Freezer:Vertical shelving enables rapid inventory retrieval for pharmaceutical applications, commanding margin premiums from hospital pharmacies and biobanks. Front-facing compressors simplify field maintenance in remote installations where technician availability is constrained.
- Portable Freezer:Sub-50-liter DC units serve community health worker mobility in rural India and emergency medical response in disaster zones. Battery-integrated designs sacrifice capacity for transportability.
- Solar Refrigerator:Positive-temperature variants address vaccine storage at plus 2 to plus 8 degrees Celsius, distinct from freezing applications. These units dominate Gavi-funded procurement for Expanded Programme on Immunization cold chains.
Chest freezer configurations sit at the top of the volume ranking, with portable freezers climbing the fastest.
End User:
Customer procurement sophistication spans from household cash purchases to multi-year service contracts with performance guarantees.
- Households:Off-grid rural residences in India and Nigeria purchase sub-100-liter units through PAYGO financing models. These buyers prioritize first-cost minimization over efficiency specifications.
- Restaurants:Coastal seafood vendors in Kenya deploy solar freezing to preserve catch quality where grid reliability is intermittent. Cold chain continuity directly determines inventory loss rates.
- Grocery Stores:Rural retail consolidation in Nigeria is driving centralized procurement of 200-plus-liter upright units. Store owners balance display accessibility against energy autonomy requirements.
- Emergency Services:Humanitarian logistics operators in malaria-endemic regions require rapid-deployment freezer capacity for vaccine surge response. These buyers specify battery-free thermal storage for multi-day autonomy.
Households account for the broadest installed base, while emergency services procurement is expanding most rapidly.
Technology:
Technology selection determines photovoltaic array sizing and battery dependency, with direct implications for system cost and maintenance burden.
- Photovoltaic:Conventional solar-to-electric-to-compressor architectures dominate current deployments. Module efficiency gains are shrinking roofprint requirements for equivalent cooling capacity.
- Hybrid Systems:Pairing photovoltaic generation with phase-change material thermal storage enables multi-day autonomy without battery replacement cycles. These configurations are gaining specification in equatorial regions with inconsistent irradiance.
- Thermal Energy Storage:Latent heat buffers absorb daytime solar surplus and release cooling energy nocturnally. Battery-free architectures reduce long-term operating costs for remote health facilities.
- Direct Current:Native DC compressor operation eliminates inverter conversion losses, cutting energy consumption. These systems require matched PV array voltage specifications.
Photovoltaic technology holds the largest installed base, with hybrid systems gaining share fastest.
Application:
Application-specific performance requirements drive divergent certification and procurement channel strategies.
- Medical Storage:Temperature monitoring, alarm systems, and WHO PQS certification are mandatory for vaccine cold chains. Gavi funding eligibility restricts supplier pools to prequalified manufacturers.
- Food Preservation:Agricultural cold chains for dairy and seafood prioritize cost minimization over precision temperature control. These applications tolerate wider operating bands than pharmaceutical storage.
- Disaster Relief:Rapid deployment and field serviceability outweigh efficiency specifications. Humanitarian procurement favors standardized units with interchangeable components.
- Outdoor Events:Temporary refrigeration for mobile vaccination campaigns and field research requires transportable, ruggedized enclosures. Battery weight limits constrain capacity in this segment.
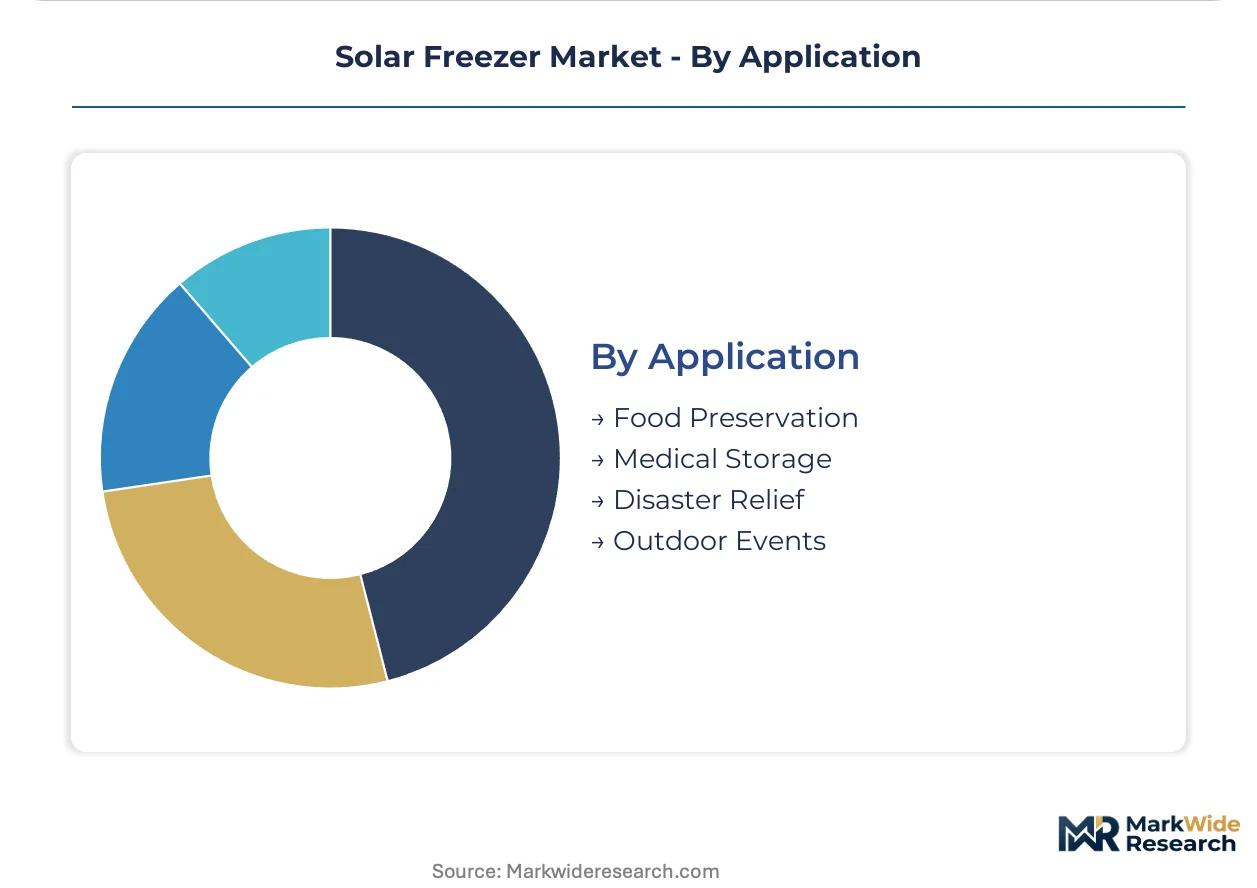
Medical storage commands the highest unit values, with disaster relief applications showing the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's off-grid healthcare corridor anchors solar freezer deployment density, with procurement concentrated through national medical store frameworks and Gavi-funded immunization programs.
Kenya
Rural electrification gaps in 23 counties drive autonomous cold chain adoption for vaccine distribution. WHO Performance Quality and Safety certification governs eligibility for Ministry of Health procurement. Nairobi-based assemblers consolidate photovoltaic module sourcing for distribution networks spanning the Rift Valley and Lake Victoria regions.
Nigeria
Grid unreliability forces healthcare ministries toward solar refrigeration for biological sample preservation. The country's national renewable energy agency ties off-grid appliance financing to local assembly requirements. Lagos and Kano industrial zones concentrate DC compressor integration facilities serving northern and southern health zones.
India
Community health worker networks in Bihar and Uttar Pradesh create demand for sub-50-liter portable units. CDSCO cold chain guidelines extend to off-grid pharmaceutical storage compliance. Gujarat and Tamil Nadu manufacturing clusters produce lithium iron phosphate battery packs for equatorial installations.
Germany
EU Green Deal financing instruments open subsidized procurement channels for Mediterranean agricultural cold chain exports. ECHA REACH compliance governs refrigerant transition toward hydrocarbon alternatives. Bavaria-based engineering firms develop phase-change material thermal storage systems for multi-day autonomy specifications.
United States
EPA AIM Act refrigerant phase-downs accelerate R600a and R290 adoption curves across medical-grade product lines. FDA 21 CFR Part 211 cold chain guidelines create compliance barriers for uncertified entrants. California and Texas distribution hubs serve emergency response and recreational vehicle segments.
Solar Freezer Market Vendor Landscape
Global majors compete with regional champions across certification tiers, with medical-grade specialists holding procurement advantages in Gavi-funded programs while portable specialists dominate recreational segments. Market structure tilts toward consolidated supply for WHO-prequalified products and fragmented competition in consumer-facing categories. Three archetypes define positioning: automotive-cooling heritage players, captive solar panel producers, and medical cold chain specialists. Capacity expansion and strategic partnerships represent the dominant competitive vectors as assemblers secure lithium iron phosphate cell supply and photovoltaic module sourcing.
Within the medical-grade tier, B Medical Systems and DULAS exemplify WHO Performance Quality and Safety prequalification as a procurement gateway. Dometic occupies a position bridging automotive cooling heritage with portable freezer segments. Kyocera represents captive solar panel production as a margin insulation strategy against polysilicate volatility. Connexa Energy and ECOSOLARCOOL sit within the regional specialist archetype, while SUNDANZER and Engel Coolers anchor recreational and emergency application positioning.
| Leading Market Players |
|---|
| B Medical Systems |
| Connexa Energy |
| Dometic |
| DULAS |
| ECOSOLARCOOL |
| SUNDANZER |
| Kyocera |
| EcoFlow |
| Engel Coolers |
| Others |
Supply Flow & Price Mechanics
EPA AIM Act refrigerant phase-downs gate both qualified supply and premium-tier pricing access, as manufacturers absorbing R600a and R290 hydrocarbon retooling costs recover margins through WHO PQS-certified product premiums while uncertified assemblers face exclusion from Gavi-funded procurement channels.
Pricing Analysis
Input-cost pass-through from lithium iron phosphate cell and photovoltaic module volatility shapes tiered pricing across certification grades. Three-tier pricing structure across premium, standard, and economy levels separates WHO PQS-validated medical units from commercial chest configurations and unbranded household units. Cost compression in economy tiers is intensifying because of polysilicate price swings and Chinese battery export license unpredictability. Household buyers in India and Nigeria exhibit highest price sensitivity through PAYGO financing constraints, while emergency services procurement prioritizes thermal autonomy over first-cost minimization.
Supply Chain Analysis
Domestic-content mandates from Nigeria's national renewable energy agency and India's PLI scheme are reshaping sourcing, forcing assemblers toward local lithium iron phosphate pack integration and DC compressor final assembly. Manufacturing clusters concentrate in China for photovoltaic modules and battery cells, India for pack assembly, and Germany for phase-change material thermal storage systems. Supply chains draw from metallurgical-grade silicon, rare earth permanent magnet motors, and hydrocarbon refrigerants. Single-source vulnerability in Chinese lithium iron phosphate cell production exposes procurement to export license unpredictability. Distribution runs through national medical store frameworks in Kenya and Nigeria, humanitarian logistics consortia, and PAYGO retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory opportunity, with WHO PQS certification and EPA AIM Act refrigerant mandates creating durable demand gates that reward prequalified incumbents while raising capital barriers for uncertified entrants.
For Market Incumbents: Acquire captive lithium iron phosphate cell supply agreements to insulate margins from Chinese export license volatility. Secure backward integration into DC compressor manufacturing or exclusive offtake with permanent magnet motor suppliers. WHO PQS certification investment represents the priority defensive lever against regional assemblers exploiting local-content financing loopholes. For New Entrants and Emerging Players: E-commerce direct-to-health-worker channels in rural India bypass consolidated national medical store procurement, enabling sub-50-liter portable unit penetration. Target community health worker networks in Bihar and Uttar Pradesh as the most penetrable white space. Pursue CDSCO cold chain guideline compliance as the go-to-market angle for pharmaceutical storage credibility. For Investors and Strategic Acquirers: Roll-up economics work for regional solar cold chain specialists because fragmented procurement across sub-Saharan health ministries is consolidating into multi-year framework agreements that favor scaled service providers. Medical-grade WHO PQS prequalification anchors long-term viability through Gavi funding continuity. Watch battery chemistry substitution signals as sodium-ion alternatives threaten lithium iron phosphate cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| WHO PQS Certification Investment | Gavi eligibility unlocks multi-year framework agreements with national medical stores in Kenya and Nigeria. |
| Backward Integration into Battery Supply | Captive lithium iron phosphate sourcing insulates margins from Chinese export license volatility and tariff exposure. |
| Phase-Change Material Thermal Storage Development | Battery-free autonomy specifications penetrate equatorial healthcare deployments with inconsistent irradiance. |
| Local Assembly Facility Establishment | Nigeria's renewable energy agency ties off-grid appliance financing to domestic content requirements. |
| Last-Mile Distribution Partnership | Community health worker networks in rural India create demand for portable sub-50-liter units. |
Methodological Framework
Multiple input streams — procurement director interviews at national medical stores, engineering consultations with photovoltaic-battery system integrators, regulatory affairs discussions with WHO PQS certification specialists, and field observations at rural health facilities — were reconciled against customs data on photovoltaic module imports, Gavi disbursement records, and EPA AIM Act regulatory filings. Bottom-up unit deployment estimates from Kenya, Nigeria, and India health ministry frameworks were cross-validated against top-down lithium iron phosphate battery demand modeling from Gujarat and Tamil Nadu manufacturing clusters.
Historical deployment trajectories in sub-Saharan immunization programs were cross-referenced against expert panel assessments of DC compressor efficiency gains and phase-change material adoption curves across the analysis window. Segmentation modeling incorporated product type, end-user procurement sophistication, technology architecture, and application-specific certification requirements. CAGRs were derived from reconciled volume projections and value chain margin compression assumptions, with particular sensitivity to polysilicate price volatility and hydrocarbon refrigerant transition timelines.
The model assumes a particular technology adoption path; alternative pathways for sodium-ion battery substitution or thermal-storage-dominant architectures would alter the outlook. Forecasts reflect assumptions regarding Gavi funding continuity, local-content rule enforcement, and WHO PQS certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Solar Cells Market