
 Plastic Solar Cell Market | 2026-2036
Plastic Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Solar Cell Market Analytics
Organic semiconductor deposition onto flexible polymer substrates is tilting manufacturing toward roll-to-roll coating methods that slash capital intensity versus silicon wafer lines. Heliatek GmbH leverages its small-molecule oligomer expertise to sustain efficiency records in ultra-lightweight modules. InfinityPV ApS anchors Nordic supply chains through printed electronics partnerships. Solarmer Energy Inc. differentiates via university-licensed polymer blends optimized for indoor energy harvesting.
Plastic solar cells integrate photoactive organic or hybrid layers—typically 100–300 nanometers thick—on polyethylene terephthalate or polyethylene naphthalate substrates, converting visible light at efficiencies of 10–18% while enabling curvature radii below 5 centimeters for architectural and wearable deployment. Organic photovoltaics dominate current production volumes due to established donor-acceptor polymer supply chains, though flexible modules capture accelerating interest from automotive interior designers seeking conformal rooftop integration. Building-integrated photovoltaics concentrates margin pools where aesthetic transparency commands premium pricing from commercial facade developers.
EPA guidelines on perfluorinated compound restrictions and the EU Green Deal's embodied carbon thresholds shape material selection for substrate and encapsulant layers, while China's MEE enforces volatile organic compound emission limits at coating facilities that filter market access. The EU AI Act's emerging energy disclosure requirements for smart building systems will cascade into procurement specifications for embedded power generation. Stakeholders must monitor how evolving extended producer responsibility frameworks in major economies redefine cost allocation across the module lifecycle.
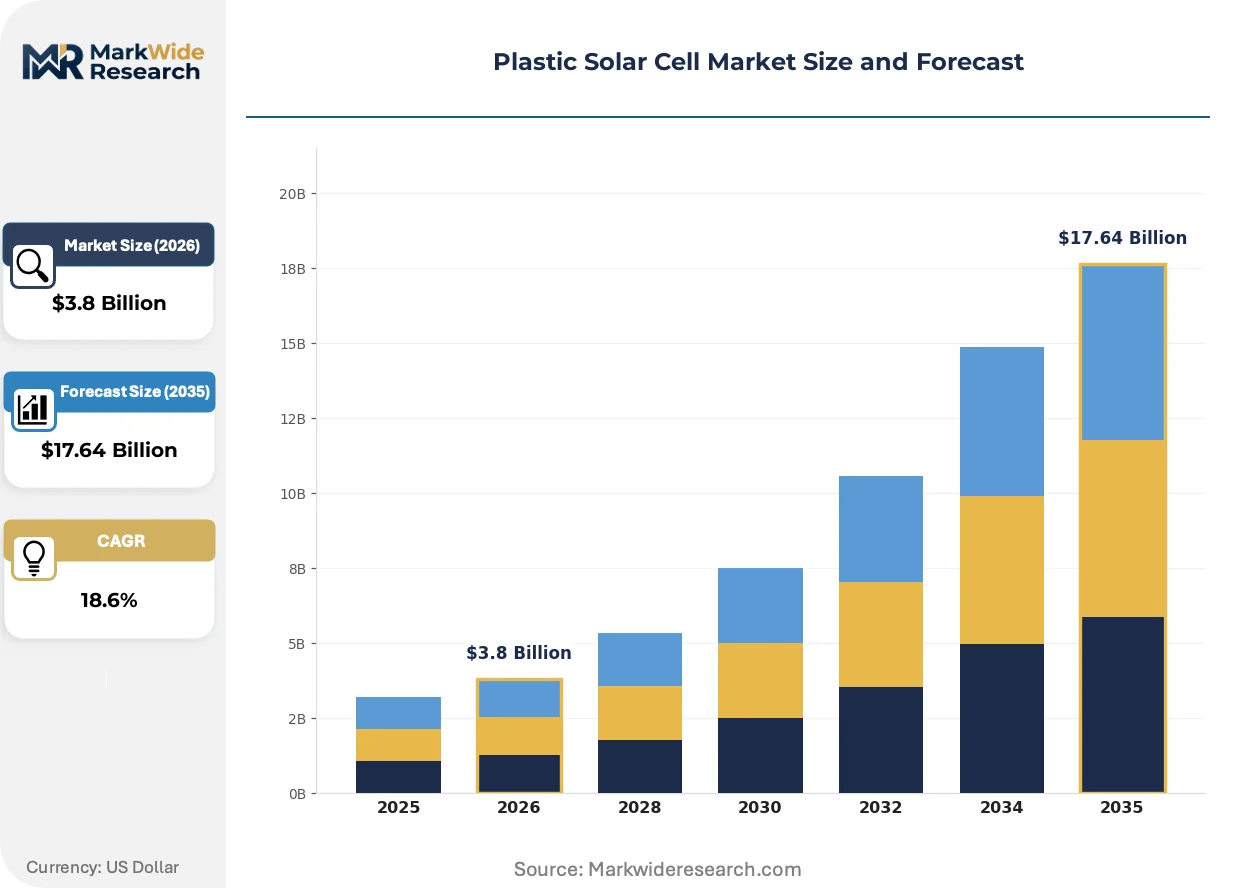
Market Dynamics
Roll-to-roll coating infrastructure is compressing capital barriers for plastic solar cell manufacturing, pulling investment away from rigid silicon wafer lines toward flexible polymer substrate systems that serve building-integrated and wearable energy applications.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on toxic heavy metals in photovoltaic substrates are accelerating substitution toward non-toxic organic semiconductors across European facade installations.
- Building-integrated photovoltaics:Commercial developers in Germany and Japan are specifying aesthetic transparency requirements that only ultra-thin organic modules can satisfy.
- East Asian manufacturing clusters:South Korea's display-to-energy conversion facilities are repurposing existing OLED deposition equipment for organic photovoltaic production.
Market Restraints
- Indium tin oxide supply concentration:Transparent electrode material sourcing concentrates in Chinese refining operations, creating input cost volatility for flexible module producers.
- Encapsulant degradation rates:Polyethylene terephthalate barrier layers face technical limitations in UV stability that compress warranted operational lifespans below silicon alternatives.
- MEE emission enforcement:China's volatile organic compound limits at coating facilities are filtering market access for non-compliant deposition equipment imports.
Strategic Opportunities
- Automotive interior integration:Conformal rooftop and glazing applications in electric vehicle cabins represent underpenetrated demand as designers seek curvature radii below 5 centimeters.
- EU AI Act energy disclosure:Emerging smart building system requirements will cascade into procurement specifications for embedded power generation in commercial construction.
- Indoor energy harvesting:Low-light optimization creates technology convergence between polymer photovoltaics and Internet-of-Things sensor networks.
Industry Challenges
- Thin-film deposition expertise:The talent gap in nanometer-scale organic semiconductor processing limits scaling of roll-to-roll coating lines.
- Extended producer responsibility frameworks:Evolving lifecycle cost allocation rules across major economies complicate module recovery and recycling infrastructure planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Solar Cell Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Photovoltaics, Thin-Film Cells, Hybrid Cells, Flexible Modules Application: Building-Integrated Photovoltaics, Wearable Devices, Portable Electronics, Automotive Power Systems End User: Residential, Commercial, Industrial, Government Installation Type: On-Grid, Off-Grid, Remote Applications, Temporary Installations |
| Companies Covered | Heliatek GmbH, Applied Materials, Abengoa S.A., Solarmer Energy Inc., NanoFlex Power Corporation, Acciona Energia S.A., Canadian Solar Inc., InfinityPV ApS, OPVIUS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Solar Cell Market Evolving Landscape
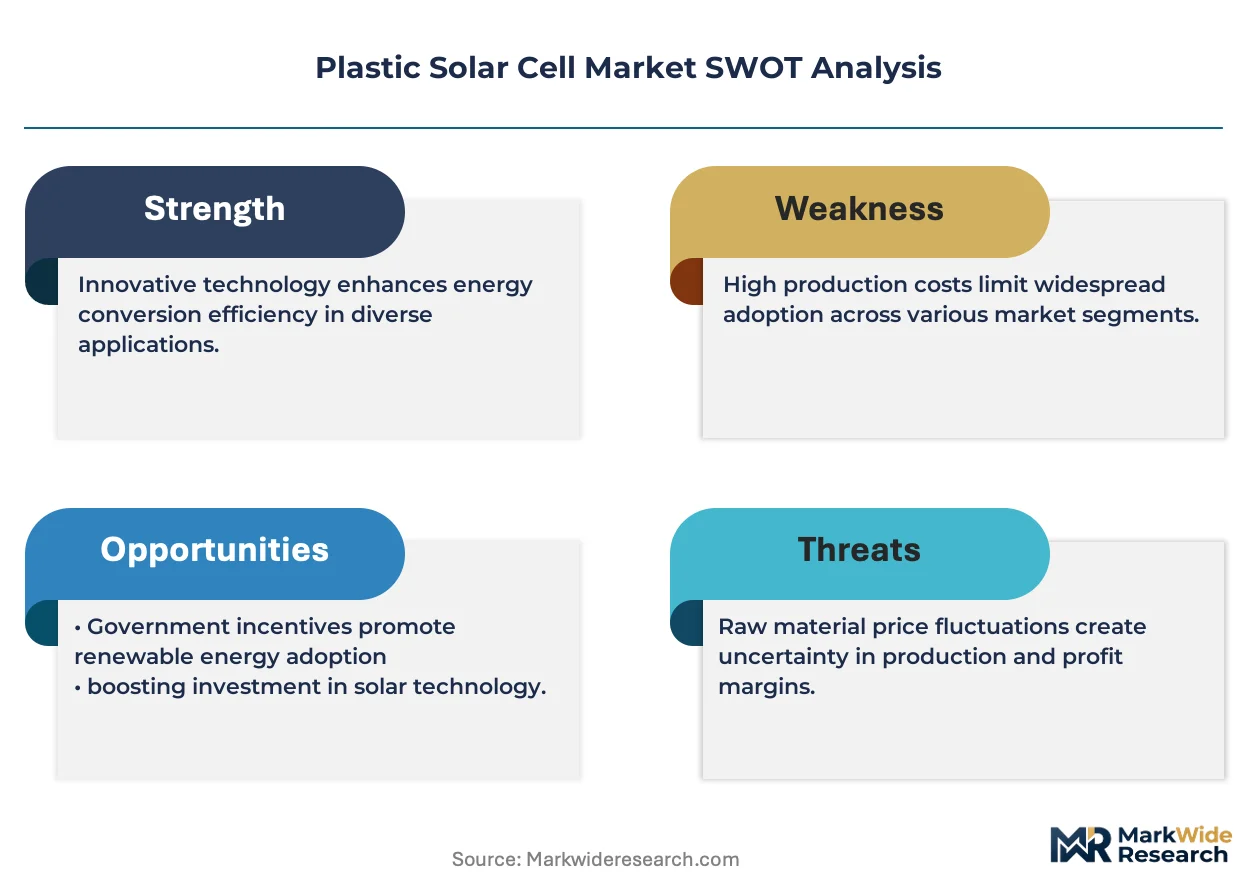
Material science advances are reconfiguring the efficiency-stability tradeoff in organic photovoltaics, while regulatory pressure on embodied carbon and chemical toxicity is filtering substrate and encapsulant selection criteria.
Tandem cell architectures are migrating from laboratory demonstrations toward pilot manufacturing, with small-molecule oligomer donors stacking with perovskite absorbers to push power conversion beyond single-junction limits. Automotive tier-one suppliers are sampling these prototypes for conformal vehicle-integrated applications. This migration from academic novelty to industrial qualification is compressing the traditional decade-long technology maturation cycle.
The EU Green Deal's embodied carbon thresholds are reshaping material selection for substrate and encapsulant layers, forcing producers to document cradle-to-gate emissions for polyethylene naphthalate alternatives. ECHA is expanding perfluorinated compound restrictions into photovoltaic barrier films. German facade developers are responding by specifying fluorine-free encapsulant stacks that trade marginal moisture protection for regulatory certainty.
Buyer specifications are fragmenting between premium aesthetic transparency and economy-grade energy yield, with procurement teams unbundling after-sales performance guarantees from hardware supply contracts. Commercial construction procurement in Japan is leading this shift, separating module supply from 25-year output warranties. This unbundling is concentrating margin capture with specialized energy service companies rather than hardware manufacturers.
Plastic Solar Cell Market Segmentation
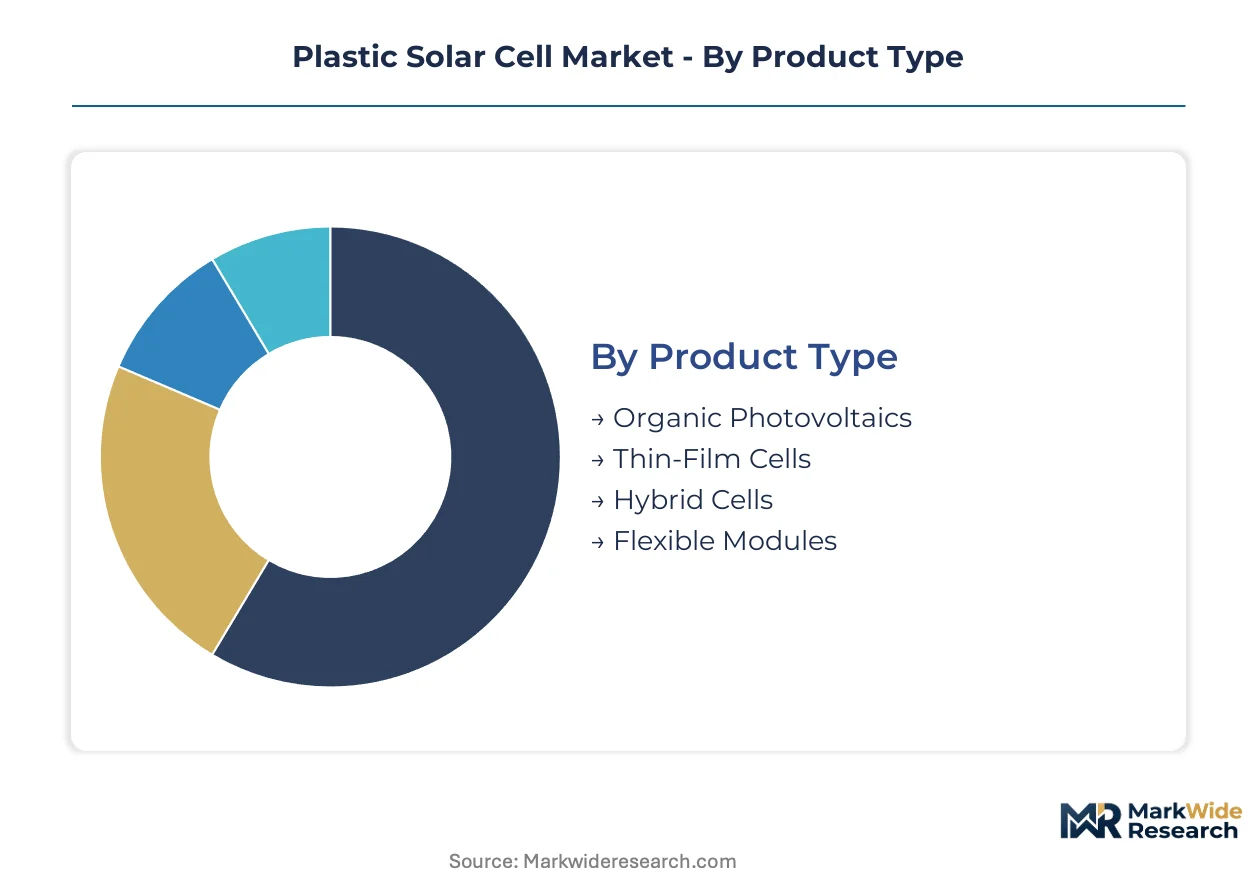
Segmentation in plastic solar cells reveals how substrate flexibility and deposition chemistry align with divergent customer procurement criteria across construction, consumer electronics, and mobility sectors. Understanding these partitions exposes where margin pools concentrate and which technology platforms face substitution pressure.
Product Type:
Application requirements span from rigid efficiency targets to extreme mechanical compliance, fragmenting the technology base across molecular architectures and substrate choices.
- Organic Photovoltaics:Donor-acceptor polymer blends deposited on flexible substrates deliver 10-18% conversion efficiency with sub-5-centimeter curvature radii. Demand concentrates in German and Japanese building-integrated installations where aesthetic transparency commands premium positioning against silicon alternatives.
- Thin-Film Cells:Nanometer-scale semiconductor layers on polyethylene terephthalate enable mass production via roll-to-roll coating. South Korean display-to-energy conversion facilities are repurposing existing OLED deposition lines for this segment, compressing capital intensity versus wafer-based manufacturing.
- Hybrid Cells:Perovskite-organic tandem stacks push power conversion beyond single-junction limits through stacked absorption bands. Automotive tier-one suppliers are sampling prototypes for conformal vehicle-integrated applications.
- Flexible Modules:Polyethylene naphthalate substrates with fluorine-free encapsulant stacks satisfy EU Green Deal embodied carbon thresholds for facade developers prioritizing regulatory certainty.
The dominant share belongs to Organic Photovoltaics, while Hybrid Cells are closing the gap fastest.
Application:
End-use environments impose distinct constraints on weight, curvature, and light spectrum, creating specialized procurement channels with divergent warranty and performance specifications.
- Building-Integrated Photovoltaics:Commercial facade developers in Germany specify transparency and color neutrality that only ultra-thin organic layers achieve. ECHA restrictions on heavy metals in substrates accelerate non-toxic semiconductor adoption across European installations.
- Wearable Devices:Sub-100-gram modules with extreme bend radius tolerance serve fitness trackers and medical patches. Indoor energy harvesting optimization creates convergence with Internet-of-Things sensor networks.
- Portable Electronics:Lightweight charging surfaces for mobile devices prioritize packaging efficiency over conversion efficiency.
- Automotive Power Systems:Conformal rooftop and glazing integration in electric vehicle cabins demands curvature radii below 5 centimeters and automotive-grade encapsulant durability.
Building-Integrated Photovoltaics holds the largest revenue pool, with Automotive Power Systems expanding most quickly as electric vehicle cabin designers specify embedded generation.
End User:
Procurement sophistication varies sharply across customer categories, with warranty unbundling and performance contracting emerging first in commercial construction.
- Commercial:Japanese procurement teams are separating module supply from 25-year output warranties, concentrating margin capture with specialized energy service companies. This unbundling is reshaping vendor relationships.
- Residential:Distributed rooftop installations prioritize ease of installation and aesthetic integration with existing architecture.
- Industrial:Large-scale facility integration emphasizes energy cost predictability and rapid deployment without structural reinforcement.
- Government:Public procurement mandates for embodied carbon disclosure and REACH compliance filter supplier eligibility in European tenders.
Commercial buyers command the deepest volume commitments, while Government procurement is gaining share fastest through green public purchasing mandates.
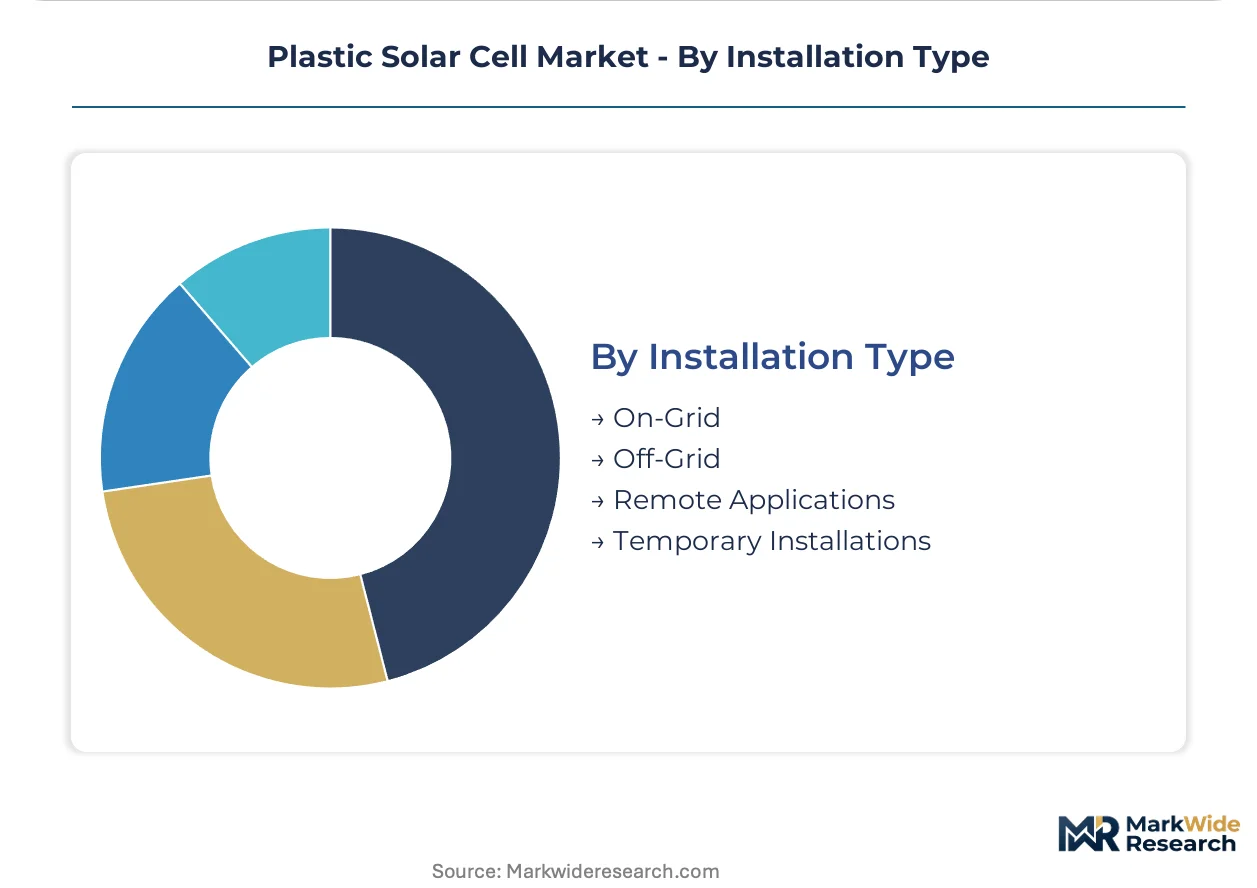
Installation Type:
Grid connectivity and permanence assumptions determine system architecture, with remote and temporary applications driving demand for ultra-lightweight, rapid-deploy module designs.
- On-Grid:Building-integrated systems feeding commercial electrical infrastructure dominate volume, leveraging existing net metering frameworks.
- Off-Grid:Standalone systems for rural electrification prioritize reliability and minimal maintenance over conversion efficiency.
- Remote Applications:Telecommunications infrastructure and environmental monitoring stations in isolated locations require self-contained power with extreme weather tolerance.
- Temporary Installations:Event power and construction site generation demand rapid deployment and redeployment capability with minimal site preparation.
On-Grid installations maintain the dominant position, though Remote Applications are climbing the fastest as off-grid telecommunications infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in plastic solar cell components are tilting toward net-import positions in European facade markets while South Korean and Chinese manufacturing bases deepen supply-side surpluses. This geographic asymmetry is reshaping capital allocation and regulatory compliance investments across major economies.
Germany
Building-integrated photovoltaics demand concentrates in commercial facade retrofits across Berlin and Hamburg, where aesthetic transparency specifications favor ultra-thin organic modules. ECHA restrictions on perfluorinated compounds in barrier films are forcing fluorine-free encapsulant adoption. The Dresden-Leipzig corridor hosts specialized roll-to-roll coating facilities repurposed from former OLED production lines.
China
Domestic absorption of flexible module output is accelerating under dual carbon goals that prioritize distributed generation in commercial construction. MEE enforcement of volatile organic compound emission limits at coating facilities is filtering equipment imports and raising compliance costs for deposition operations. The Yangtze River Delta cluster around Suzhou and Wuxi concentrates indium tin oxide refining and transparent electrode substrate manufacturing.
South Korea
Display-to-energy conversion is repurposing existing OLED deposition infrastructure in Gyeonggi Province for organic photovoltaic production, compressing capital intensity versus greenfield builds. MFDS-aligned quality frameworks for electronic materials are migrating into photovoltaic certification requirements. The Seoul Capital Area anchors pilot manufacturing of tandem cell architectures combining small-molecule oligomers with perovskite layers.
Japan
Commercial procurement teams in Tokyo and Osaka are unbundling module supply from 25-year performance warranties, concentrating margin capture with specialized energy service companies. METI efficiency standards for building-integrated systems are tightening minimum conversion thresholds. The Kansai region hosts qualification facilities for automotive conformal integration prototypes targeting sub-5-centimeter curvature radii.
United States
EPA guidelines on perfluorinated compound restrictions are shaping encapsulant material selection for architectural applications in California and New York. The Inflation Reduction Act's domestic content bonuses are pulling investment toward North American substrate and barrier film manufacturing. Research corridors in Massachusetts and Colorado anchor university-licensed polymer blend development for indoor energy harvesting optimization.
Plastic Solar Cell Market Competitive Landscape
On the supply side, the industry is fragmented across specialized material suppliers, deposition equipment fabricators, and integrated module producers with limited scale advantages. Strategic archetypes include university-spinout technology licensors, display-industry repurposers leveraging existing OLED infrastructure, and energy service companies capturing unbundled warranty value. Competitive moves concentrate on strategic partnerships for roll-to-roll coating scale-up and geographic expansion into regulatory-favorable European markets.
Among Germany-based technology developers, Heliatek GmbH and OPVIUS GmbH exemplify the small-molecule oligomer specialization archetype, while InfinityPV ApS represents Nordic supply chain anchoring through printed electronics partnerships. Solarmer Energy Inc. occupies a position within the university-licensed polymer blend segment. These named entities illustrate how competitive positioning fragments across molecular architecture expertise, geographic regulatory alignment, and end-use application focus rather than consolidating around manufacturing scale.
| Leading Market Players |
|---|
| Heliatek GmbH |
| Applied Materials |
| Abengoa S.A. |
| Solarmer Energy Inc. |
| NanoFlex Power Corporation |
| Acciona Energia S.A. |
| Canadian Solar Inc. |
| InfinityPV ApS |
| OPVIUS GmbH |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta freight corridors channel indium tin oxide substrates from Chinese refining clusters to South Korean deposition facilities, compressing logistics costs for transparent electrode procurement while amplifying price differentiation between REACH-compliant European modules and standard-grade Asian output.
Pricing Analysis
Current-generation organic photovoltaic modules command premium positioning over prior-generation amorphous silicon alternatives, while next-generation tandem cell prototypes justify development-stage pricing through automotive qualification pathways. Three-tier pricing structure across premium, standard, and economy levels reflects ECHA certification status and curvature radius specifications. Cost compression in economy-grade flexible modules intensifies as Chinese coating capacity expands. Commercial facade developers in Germany exhibit lowest price sensitivity due to aesthetic transparency requirements, while portable electronics OEMs drive hardest bargain negotiations.
Supply Chain Analysis
Extended payment terms from South Korean display-to-energy conversion facilities are stabilizing working capital for polyethylene naphthalate substrate suppliers during qualification cycles. Manufacturing gravity centers on China, South Korea, and Germany for deposition equipment and barrier film production. Raw material flows draw from indium refining in Chinese smelters, oligomer synthesis in German chemical corridors, and fluorine-free encapsulant development in Nordic polymer labs. Single-source vulnerability concentrates in indium tin oxide transparent electrode supply. Distribution runs through specialized energy service companies capturing unbundled warranty value in Japanese commercial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across building-integrated, automotive, and wearable applications creates specialized niche opportunities as buyer specifications diverge between aesthetic transparency and energy yield optimization.
For Market Incumbents: Build regulatory compliance moats through ECHA REACH pre-certification of fluorine-free encapsulant stacks before 2026 enforcement windows tighten. Deepen backward integration into oligomer synthesis to offset volatile indium tin oxide input costs. Capture channel control by anchoring Nordic supply partnerships for printed electronics scale-up. Counter emerging thin-film deposition equipment fabricators from display-industry repurposers.
For New Entrants and Emerging Players: Establish a beachhead in automotive interior integration where curvature radii below 5 centimeters filter out silicon competition. Target indoor energy harvesting for Internet-of-Things sensor networks as the most penetrable application with lowest incumbent saturation. Pursue university-licensed polymer blend partnerships as go-to-market angle for differentiated low-light optimization.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors display-industry repurposers leveraging existing OLED infrastructure over greenfield deposition builds. Long-term viability across the analysis window hinges on tandem cell architecture maturation and perovskite stability resolution. Monitor ECHA perfluorinated compound restriction expansion as inflection signal for fluorine-free encapsulant technology valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Roll-to-Roll Coating Scale-Up | Heliatek GmbH leverages small-molecule oligomer expertise to compress capital intensity versus wafer lines. |
| Fluorine-Free Encapsulant Certification | EU Green Deal embodied carbon thresholds force documentation of cradle-to-gate emissions for barrier films. |
| Tandem Cell Pilot Manufacturing | Seoul Capital Area facilities stack perovskite absorbers with organic donors for automotive qualification. |
| Warranty Unbundling Partnerships | Japanese energy service companies capture margin pools separated from module hardware supply contracts. |
| Indoor Energy Harvesting Optimization | Solarmer Energy Inc. differentiates via university-licensed polymer blends for low-light conversion. |
Research Methodology
The analysis maps organic photovoltaics, thin-film cells, hybrid tandem architectures, and flexible module sub-sectors, each validated through deposition equipment engineers, facade procurement managers, automotive tier-one supplier technologists, and printed electronics partnership directors. Primary fieldwork combined structured interviews with secondary triangulation against SEC filings from materials suppliers, ECHA substance restriction databases, and MFDS-aligned quality framework documentation. Bottom-up capacity assessments and top-down demand modeling converged through iterative stakeholder feedback.
Assumptions held fixed include REACH compliance trajectory and dual carbon goal enforcement intensity, while variables included indium price volatility bands and automotive qualification timeline dispersion. Segmentation modeling spanned product chemistry, substrate flexibility, application environment, end-user procurement sophistication, and installation grid connectivity. CAGRs derived from slope analysis of technology adoption curves weighted by regional regulatory implementation schedules. Forecast inputs incorporated roll-to-roll coating throughput rates and encapsulant degradation testing protocols.
Stress conditions across indium supply disruption scenarios, ECHA perfluorinated compound restriction acceleration, and MEE emission enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology maturation pathways. Macroeconomic contraction, regulatory timeline deviation, or perovskite stability breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market