
 Solar Ribbon Market | 2026-2036
Solar Ribbon Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Ribbon Market Insights
Cell-to-module interconnect revenue is fragmenting across copper-aluminum hybrid designs and ultra-thin ribbon geometries as cell architectures diversify. Ulbrich Solar Technologies leverages its precision rolling capabilities to anchor North American supply chains for advanced metallization. SHENMAO Technology competes through vertical control over tin-coating chemistries that reduce soldering temperatures for heterojunction cells. Sveck Photovoltaic New Materials specializes in nickel-plated ribbon formulations that sustain conductivity under elevated module operating temperatures.
Solar ribbon denotes precision-drawn copper conductors, typically 0.8–2.0 mm wide and 0.1–0.3 mm thick, coated with tin or nickel alloys via hot-dip or electroplating processes to enable low-resistance soldering between photovoltaic cells. These ribbons function as the primary current collection pathway in crystalline silicon modules, with electrical resistivity specifications below 0.0175 ohm·mm²/m ensuring minimal power loss at cell junctions. Flat ribbons dominate utility-scale panel assembly where automated stringers process high cell throughput, while tinned ribbons capture expanding share in rooftop installations demanding solderability across variable temperature cycles. Round ribbons occupy niche positions in bifacial module designs where reduced shading ratio improves rear-side light harvesting.
China's SAMR enforces GB/T standards for ribbon tensile strength and coating uniformity that determine module certification eligibility under the national PV product catalogue. The EU's RoHS Directive and REACH restrictions on lead-containing solder alloys are redirecting coating formulations toward pure tin and silver-tin alternatives for European-bound exports. India's BIS compulsory registration scheme for solar photovoltaic systems now extends to interconnect materials, creating compliance thresholds for imported ribbon. Stakeholders must monitor how cell efficiency roadmaps toward 26% front-side conversion will force ribbon cross-section reductions that test manufacturing yield thresholds.
Market Dynamics
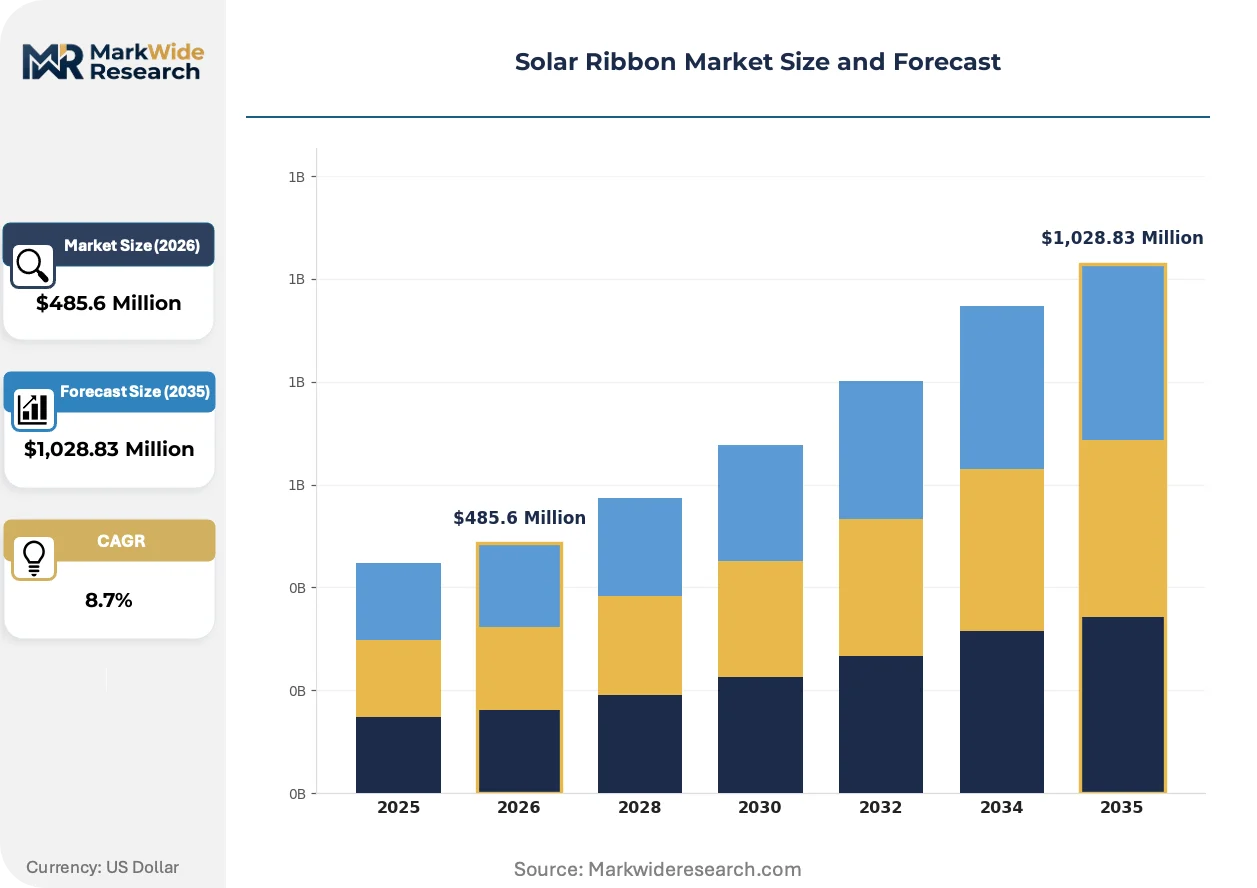
Cell architecture roadmaps toward 26% front-side conversion efficiency are forcing ribbon cross-section reductions below 0.15 mm thickness, testing manufacturing yield thresholds and reshaping supplier capability requirements across interconnect supply chains.
Growth Catalysts
- China's dual carbon goals:Updated GB/T standards for solar component efficiency tighten product certification requirements and accelerate replacement cycles for legacy ribbon inventories in Jiangsu and Zhejiang manufacturing clusters.
- Heterojunction cell expansion:Low-temperature soldering requirements for temperature-sensitive cell architectures pull demand for advanced tin-coating chemistries that reduce thermal stress during module assembly.
- Utility-scale solar farm buildout:Automated stringer lines processing high cell throughput in photovoltaic module assembly lines drive specification standardization for high-conductivity interconnect materials.
Market Restraints
- Copper price volatility:Raw material cost swings in LME copper futures compress margin buffers for toll-coating operations and precision rolling facilities serving solar OEMs.
- Coating chemistry concentration:Supply of high-purity tin and specialty flux formulations concentrates among Asian chemical processors, creating single-source vulnerability for European and North American ribbon finishers.
- REACH compliance friction:EU restrictions on lead-containing solder alloys force coating reformulation timelines that lag module certification deadlines for European-bound exports.
Strategic Opportunities
- Bifacial module designs:Round ribbon geometries capturing niche positions in rear-side light harvesting applications offer premium positioning for suppliers with precision drawing capabilities.
- India BIS registration expansion:Compulsory registration scheme extension to interconnect materials creates first-mover compliance advantages for certified exporters targeting Indian module assembly.
- Silver-tin coating convergence:Hybrid metallization chemistries combining conductivity performance with RoHS alignment open specification windows for next-generation heterojunction and TOPCon cell architectures.
Industry Challenges
- Sub-0.15 mm rolling precision:Ultra-thin ribbon geometries demand micron-level thickness control that exceeds legacy cold-rolling equipment tolerances, forcing capital-intensive retooling programs.
- Multi-standard certification complexity:Simultaneous compliance with China's SAMR GB/T requirements, EU REACH restrictions, and India BIS registration creates testing backlog and timeline uncertainty for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Ribbon Market |
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,028.83 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Ribbons, Round Ribbons, Tinned Ribbons, Nickel-Plated Ribbons Application: Solar Panels, Solar Inverters, Power Storage Systems, Solar Thermal Solutions End User: Manufacturers, Installers, Distributors, Energy Providers Connectivity: Wired, Wireless, Hybrid, Integrated |
| Companies Covered | Ulbrich Solar Technologies, Hitachi Cable, Sveck Photovoltaic New Materials, Bruker-Spaleck, Sarkuysan, Sanysolar, Targray Technology International, SHENMAO Technology, Baoding Yitong PV Science & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Ribbon Market Trends and Innovations
Interconnect technology is bifurcating between ultra-thin flat ribbons for automated utility-scale assembly and specialized round geometries for bifacial light management, with coating chemistry emerging as the primary differentiation axis.
Copper-aluminum hybrid ribbon designs combining conductivity performance with cost structure optimization are rendering obsolete pure copper conductors in standard monocrystalline module applications. Tier-1 module assemblers in Southeast Asia and Eastern Europe have adopted hybrid geometries for 60-cell and 72-cell string configurations since late 2023. The shift is compressing premium pricing for conventional tinned copper ribbon in commodity module segments while opening specification windows for aluminum-core specialists.
REACH restrictions on lead-containing solder alloys are redirecting European-bound coating formulations toward pure tin and silver-tin alternatives, with ECHA substance authorization timelines determining product qualification windows. Module exporters to EU member states now face dual-track inventory management for lead-compliant and lead-free ribbon stocks. German and Dutch module integrators are accelerating silver-tin qualification to preempt 2025 authorization cliff effects.
Automated stringer procurement specifications now prioritize ribbon coil consistency and splice-free length over unit pricing, reversing legacy purchasing evaluation frameworks. Equipment OEMs serving Chinese and Vietnamese module factories have tightened feeding tolerance requirements to ±0.01 mm. Procurement teams at vertically integrated cell-to-module manufacturers are consolidating supplier bases to three qualified sources per coating chemistry type.
Solar Ribbon Market Segmentation
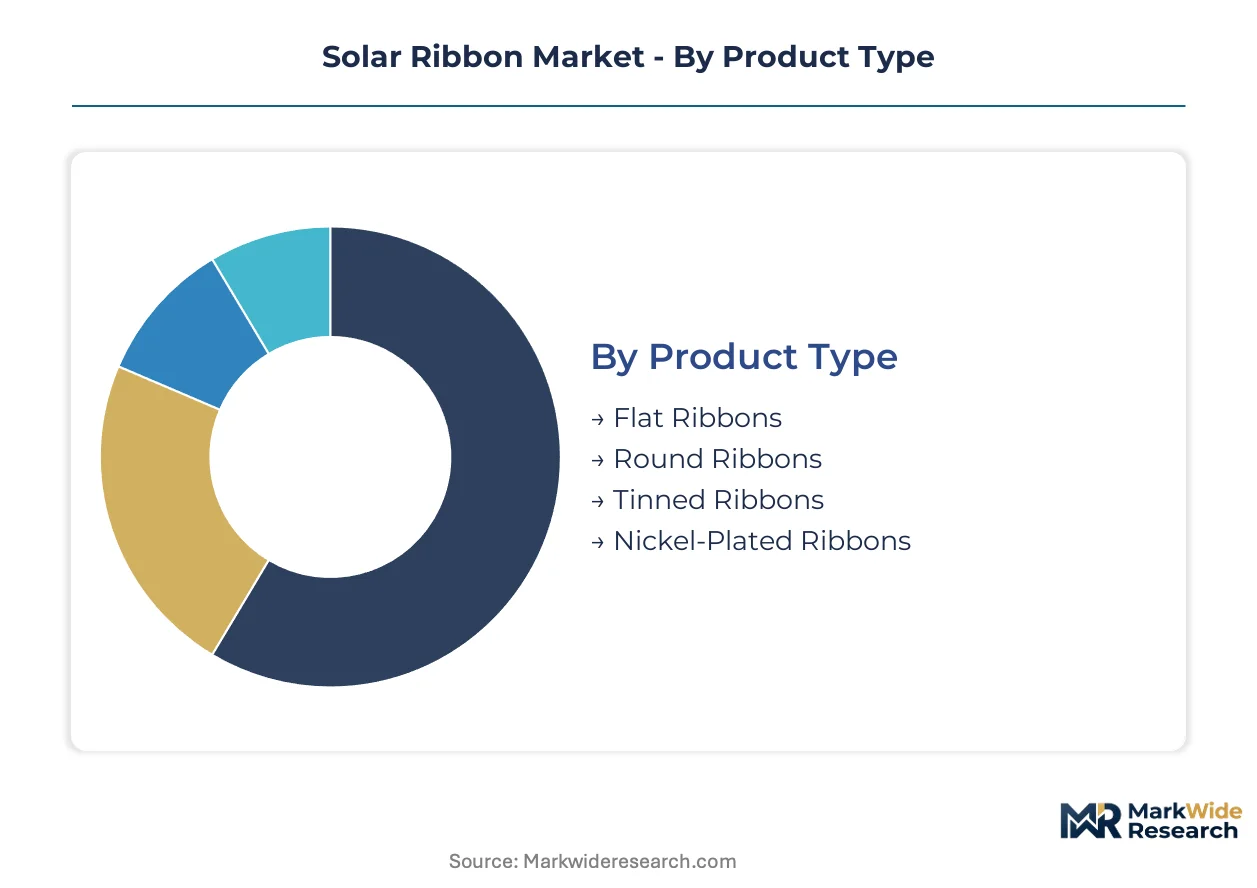
Solar ribbon segmentation maps directly to cell architecture evolution and assembly automation requirements. Product geometry and coating chemistry determine compatibility with stringer equipment and module efficiency targets.
Product Type:
Cost tier differentiation separates commodity interconnect from precision-engineered variants serving next-generation cell architectures.
- Flat Ribbons:Rectangular copper conductors 0.8–2.0 mm wide with tin or nickel surface coatings. Automated stringer lines in Jiangsu and Zhejiang province manufacturing clusters specify these for high-throughput utility-scale panel assembly where feeding consistency outweighs unit cost.
- Round Ribbons:Circular cross-section geometries reduce shading ratio on bifacial cell rear surfaces. Demand concentrates in heterojunction and TOPCon module designs where rear-side light harvesting drives efficiency gains, though precision drawing requirements limit supplier pools.
- Tinned Ribbons:Hot-dip or electroplated tin coatings enable low-temperature soldering for temperature-sensitive cell architectures.
- Nickel-Plated Ribbons:Electroplated nickel barrier layers sustain conductivity under elevated module operating temperatures in harsh climate installations.
Flat ribbons command the established base. The steepest expansion runs through round ribbons.
Application:
Volume concentration tracks utility-scale deployment cycles and distributed generation buildout patterns.
- Solar Panels:Crystalline silicon module assembly represents the dominant demand sink, with interconnect specifications tied directly to cell efficiency roadmaps and stringer automation protocols. Jiangsu province cell-to-module manufacturers drive procurement standardization.
- Power Storage Systems:Battery interconnect applications for utility-scale solar-plus-storage projects require ribbon formulations with enhanced thermal cycling resistance. India's CEA grid integration mandates are accelerating specification development for storage-coupled installations.
- Solar Inverters:Power electronics busbar applications utilize heavier gauge ribbon derivatives for DC-AC conversion stages.
- Solar Thermal Solutions:Concentrated solar power plants employ specialized high-temperature interconnect for receiver assembly.
Solar panels absorb the volume concentration. Storage system applications are climbing the fastest.
End User:
Customer type determines specification authority and procurement evaluation frameworks across the value chain.
- Manufacturers:Vertically integrated cell-to-module producers hold primary specification authority, with procurement teams consolidating qualified supplier bases to three sources per coating chemistry type. China's SAMR GB/T certification requirements filter vendor eligibility.
- Installers:Rooftop and utility-scale EPC contractors influence ribbon selection through module brand preferences and field reliability feedback.
- Distributors:Inventory management and logistics providers handle secondary sourcing for aftermarket and replacement demand.
- Energy Providers:Utility and independent power producer procurement specifications increasingly incorporate module-level interconnect quality clauses.
Manufacturers retain specification control. Installer influence is gaining share fastest.
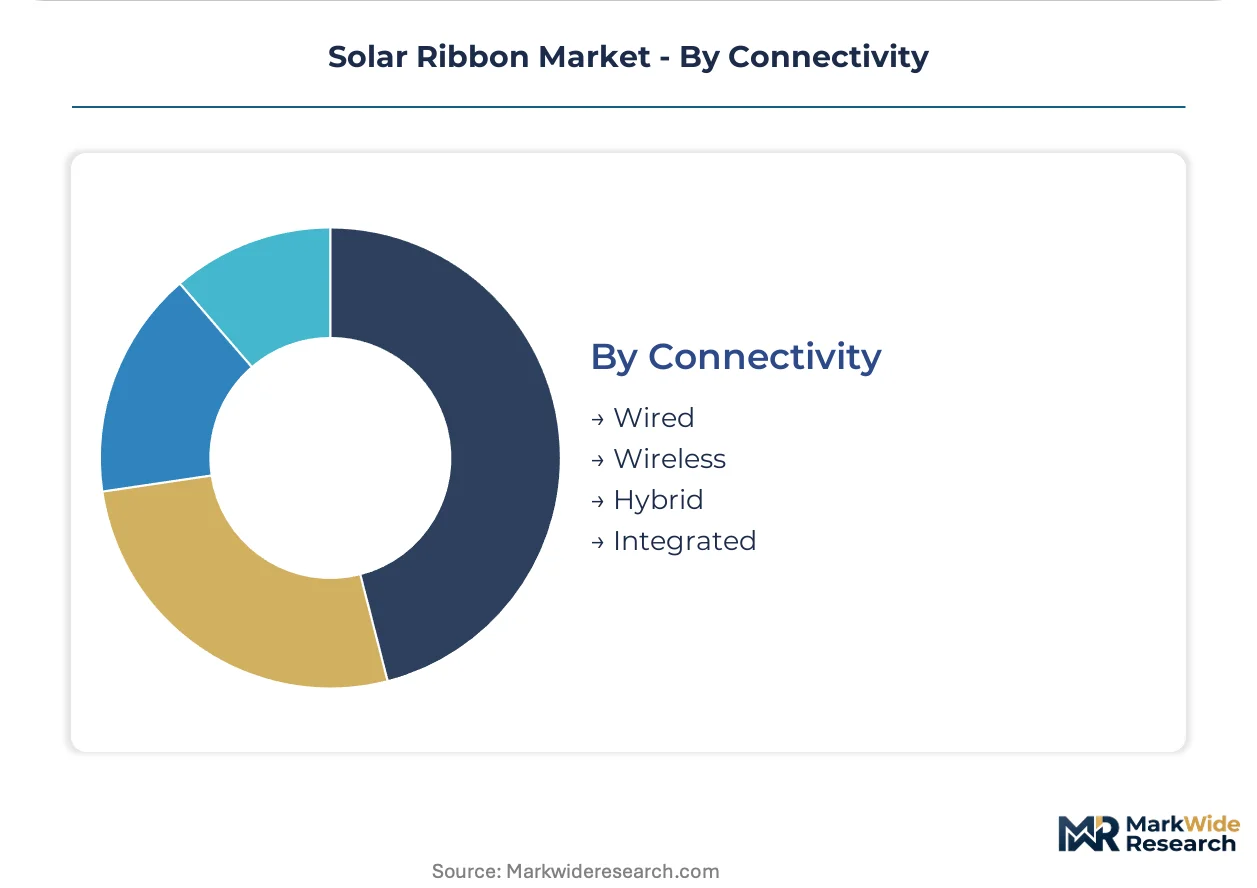
Connectivity:
Integration maturity separates legacy wired architectures from emerging smart interconnect approaches.
- Wired:Conventional soldered ribbon connections dominate current module assembly, with established equipment ecosystems and qualification protocols. REACH-compliant lead-free formulations are redirecting European-bound coating specifications toward pure tin and silver-tin alternatives.
- Integrated:Module-embedded interconnect systems combining ribbon, bypass diode, and junction box functions reduce assembly steps. India's BIS compulsory registration scheme extension to interconnect materials creates compliance thresholds for integrated system suppliers.
- Wireless:Capacitive or inductive coupling approaches remain experimental for cell-to-cell interconnection.
- Hybrid:Mixed wired and contactless architectures target specific reliability or manufacturing efficiency gains.
Wired architectures hold the installed base. Integrated solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers prioritize volume scale and coating consistency over unit pricing, while European and North American procurement teams absorb premiums for REACH-compliant formulations and automated stringer compatibility.
China
Jiangsu and Zhejiang province manufacturing clusters drive the dominant share of cell-to-module interconnect procurement. SAMR enforces GB/T standards for ribbon tensile strength and coating uniformity that determine module certification eligibility under the national PV product catalogue. Suzhou-based precision rolling facilities are retooling for sub-0.15 mm thickness tolerances to serve heterojunction cell roadmaps.
Germany
German module integrators are accelerating silver-tin coating qualifications to preempt 2025 ECHA substance authorization cliff effects for lead-free alternatives. RoHS Directive compliance redirects European-bound coating formulations toward pure tin and silver-tin metallurgies. Erfurt and Dresden assembly operations are consolidating qualified supplier bases to three sources per coating chemistry type.
United States
Domestic content incentives under the IRA are pulling North American module assembly capacity toward vertically integrated ribbon finishing operations. FERC grid interconnection queues for utility-scale solar-plus-storage projects are driving specification development for thermally robust interconnect materials. Arizona and Texas manufacturing zones are attracting toll-coating investments to serve regional OEMs.
India
Gujarat and Tamil Nadu module assembly corridors are expanding procurement specifications to incorporate BIS compulsory registration requirements for interconnect materials. CEA grid integration mandates for solar-plus-storage installations are accelerating demand for ribbon formulations with enhanced thermal cycling resistance. Mundra and Chennai port zones are developing import compliance infrastructure for certified ribbon exporters.
Vietnam
Automated stringer lines in Bac Ninh and Hai Phong manufacturing zones are standardizing on coil consistency and splice-free length specifications over unit pricing. Tier-1 module assemblers are consolidating supplier bases to match Chinese procurement frameworks. Haiphong logistics corridors are positioning for transshipment of REACH-compliant ribbon stocks to European markets.
Solar Ribbon Market Competitive Landscape
Precision metallization specialists and toll-coating operators split the market along capability lines, with the former controlling drawing tolerances and the latter dominating surface chemistry. The vendor base concentrates among Asian precision rollers and European coating finishers serving distinct certification regimes. Three archetypes define positioning: vertically integrated cell-to-module manufacturers with captive ribbon operations, independent precision metallization houses, and specialty coating chemistry providers. Capacity expansion and backward integration into tin-coating chemistries represent the dominant competitive vectors.
Among North American precision metallization houses, Ulbrich Solar Technologies occupies a position exemplifying automated rolling capabilities for advanced interconnect geometries. Within the Asian coating chemistry tier, SHENMAO Technology and Sveck Photovoltaic New Materials represent alternative approaches to surface metallization for temperature-sensitive cell architectures. These three anchors illustrate how geographic specialization and technical differentiation are reshaping supplier qualification frameworks across module assembly corridors.
| Leading Market Players |
|---|
| Ulbrich Solar Technologies |
| Hitachi Cable |
| Sveck Photovoltaic New Materials |
| Bruker-Spaleck |
| Sarkuysan |
| Sanysolar |
| Targray Technology International |
| SHENMAO Technology |
| Baoding Yitong PV Science & Technology |
| Others |
Pricing and Supply Chain Analysis
Copper cathode concentration in Chilean and Peruvian mining operations funnels margin capture toward LME futures desks and toll-coating facilities rather than precision rolling houses. This upstream chokepoint shapes how downstream module assemblers negotiate long-term offtake terms versus spot market exposure.
Pricing Analysis
After-sales coating chemistry replenishment contracts now anchor lifetime value for ribbon finishers serving heterojunction cell manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified silver-tin formulations from commodity tinned copper and uncoated bare copper. Cost compression in standard-grade flat ribbons is intensifying because Chinese module OEMs are consolidating qualified supplier bases to three sources per chemistry type. Distributed generation installers in European rooftop segments show least price sensitivity due to premium module brand preferences, while Southeast Asian toll-coating operators absorb maximum margin pressure.
Supply Chain Analysis
Copper cathode feedstock draws from Chile, Peru, and Indonesian smelting complexes before reaching Jiangsu and Zhejiang precision rolling facilities. High-purity tin ingot and specialty flux formulations rest on Malaysian and Thai chemical processors, creating single-source vulnerability for European and North American finishers. Tariff exposure on Chinese-origin coated ribbon shipments to EU and US markets is accelerating qualification of Vietnamese and Indian toll-coating alternatives. Distribution runs through vertically integrated cell-to-module manufacturers with captive finishing operations, bypassing independent metallization houses in procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar ribbon incumbents face substitution pressure from copper-aluminum hybrid interconnect designs that render pure copper conductors obsolete in standard monocrystalline applications. Module assemblers in Southeast Asia and Eastern Europe have accelerated hybrid adoption since late 2023.
For Market Incumbents: Build coating chemistry moats through backward integration into tin and silver-tin alloy production. Secure SAMR GB/T certification renewals ahead of heterojunction cell efficiency roadmaps to maintain eligibility in China's national PV product catalogue. Defend against copper-aluminum hybrid displacement by qualifying ultra-thin round ribbon geometries for bifacial rear-side harvesting applications. For New Entrants and Emerging Players: India's BIS compulsory registration scheme extension to interconnect materials represents the most penetrable entry point for certified exporters targeting Gujarat and Tamil Nadu module assembly corridors. Round ribbon precision drawing capabilities for heterojunction and TOPCon rear-side applications offer white-space positioning where incumbent supplier pools remain limited. Lead with thermal cycling resistance specifications for solar-plus-storage installations under CEA grid integration mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision rolling houses in North America and European coating finishers with REACH-compliant formulation libraries. Five-to-ten-year viability hinges on retooling timelines for sub-0.15 mm thickness tolerances serving next-generation cell architectures. Watch ECHA substance authorization timelines for lead-free solder alternatives as inflection indicators for coating chemistry valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | Captures margin pools from high-purity tin and silver-tin alloy supply concentrated among Asian chemical processors. |
| Sub-0.15 mm Rolling Precision Retooling | Enables qualification for heterojunction and TOPCon cell roadmaps demanding micron-level thickness control. |
| BIS Registration Compliance Buildout | Creates first-mover advantage for certified exporters targeting Gujarat and Tamil Nadu module assembly corridors. |
| Silver-Tin Coating Qualification Acceleration | Preempts ECHA authorization cliff effects for lead-free alternatives in German and Dutch module integrator supply chains. |
| Integrated Interconnect System Development | Combines ribbon, bypass diode, and junction box functions to reduce assembly steps for automated stringer lines. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with precision rolling plant managers, module OEM procurement leads, toll-coating operations directors, and heterojunction cell R&D heads; and secondary validation through SAMR GB/T certification databases, ECHA REACH substance authorization filings, BIS compulsory registration records, and SEC disclosures from listed solar component manufacturers. Bottom-up cell-to-module production capacity estimates triangulated against top-down interconnect consumption models derived from utility-scale installation databases.
Forecast inputs incorporated coating chemistry type, ribbon geometry class, cell architecture compatibility tier, and regional regulatory cluster across the analysis window. CAGRs emerged from segmented volume projections weighted by module efficiency roadmaps and stringer automation penetration curves. Heterojunction cell expansion timelines and BIS registration compliance deadlines shaped trajectory assumptions for premium coating formulations.
Practitioners should monitor ECHA authorization timelines, LME copper futures volatility, and Chinese dual carbon policy implementation pace for early signals of forecast revision. Cross-checking against FERC grid interconnection queue data and IEA utility-scale deployment projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Distributed Solar Energy Market